
 FM Transmitters Market | 2026-2036
FM Transmitters Market Size, Share, and Industry Trends Forecast 2026-2036
FM Transmitters Market Analytics
Broadcast-grade transmitter specifications is collapsing into a narrower band of premium-tier products as stations face spectral efficiency mandates. Nautel Ltd. leverages its solid-state architecture leadership to anchor North American supply relationships. Rohde & Schwarz competes through precision engineering in European public broadcasting tenders. GatesAir sustains its position via extensive service networks across Latin American broadcast markets.
An FM transmitter converts audio signals into frequency-modulated radio waves for terrestrial broadcast distribution, typically operating in the 87.5–108 MHz band with power outputs ranging from milliwatts for micro-broadcasting to hundreds of kilowatts for regional coverage. The device serves as the terminal RF amplification stage in broadcast chains, feeding antenna systems that radiate programmed content to consumer receivers. Rack-mount transmitters dominate commercial broadcast installations where space optimization and thermal management drive procurement decisions, while portable units capture growth in emergency broadcasting and temporary event coverage. Analog FM technology still occupies the majority of installed base volumes, though RDS-enabled digital integration is displacing legacy stereo-only configurations in European and Asian upgrade cycles.
The FCC governs transmitter type acceptance and spectral emissions limits in the United States, while Brazil's ANATEL enforces local content requirements that shape import substitution patterns for regional manufacturers. Elenos navigates CE marking obligations under the EU Radio Equipment Directive to maintain market access across continental European broadcasters. Procurement teams must monitor spectrum auction timelines and national digitization roadmaps to align capital deployment with regulatory windows.
Market Dynamics
Spectral efficiency mandates and broadcast spectrum repack programs are compressing transmitter replacement cycles while collapsing product tiers toward premium-grade, digitally-integrated systems.
Growth Catalysts
- FCC Repack Mandates:The FCC's broadcast spectrum repack in the United States forces stations to replace aging analog transmitters with compliant digital-ready equipment, accelerating capital deployment across commercial and public broadcasters.
- Low-Power FM Licensing Reforms:Brazil's ANATEL licensing reforms for community and regional stations have opened installation volumes in previously restricted frequency bands, creating procurement pull from municipal broadcasters.
- RDS-Enabled Digital Integration:Radio Data System technology is displacing legacy stereo-only configurations in European and Asian upgrade cycles, mandating transmitter replacements that support enhanced data services.
Market Restraints
- GaN and LDMOS Component Volatility:Gallium nitride and laterally-diffused metal-oxide semiconductor prices fluctuate with compound semiconductor foundry capacity constraints in East Asian supply chains, compressing transmitter manufacturer margins.
- CE Marking Compliance Burden:The EU Radio Equipment Directive's stringent electromagnetic compatibility and safety testing requirements create extended certification timelines that delay product launches for non-European manufacturers.
- Streaming Audio Substitution:Internet radio and podcast platforms erode terrestrial FM listenership in developed markets, reducing station revenue available for transmitter capital expenditure.
Strategic Opportunities
- Emergency Broadcasting Infrastructure:Portable FM transmitter procurement for disaster response and temporary event coverage represents underpenetrated demand as civil defense agencies modernize resilient communication systems.
- Sub-Saharan Africa Community Radio Expansion:International development funding for rural information access is driving transmitter procurement across Kenya, Nigeria, and Tanzania where broadcast penetration remains below urban saturation.
- Digital Radio Mondiale Convergence:Hybrid FM-DRM transmitter architectures enable simultaneous analog and digital broadcasting, allowing stations to transition audiences without dual infrastructure investment.
Industry Challenges
- RF Engineering Talent Scarcity:Specialized expertise in high-power amplifier design and antenna matching networks is concentrating among aging practitioner cohorts, constraining manufacturer R&D velocity and field service capacity.
- Legacy Analog Integration Complexity:Stations with decades-old studio-to-transmitter links and mixing consoles face expensive ancillary system upgrades when installing modern transmitters, extending sales cycles and complicating vendor specification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FM Transmitters Market |
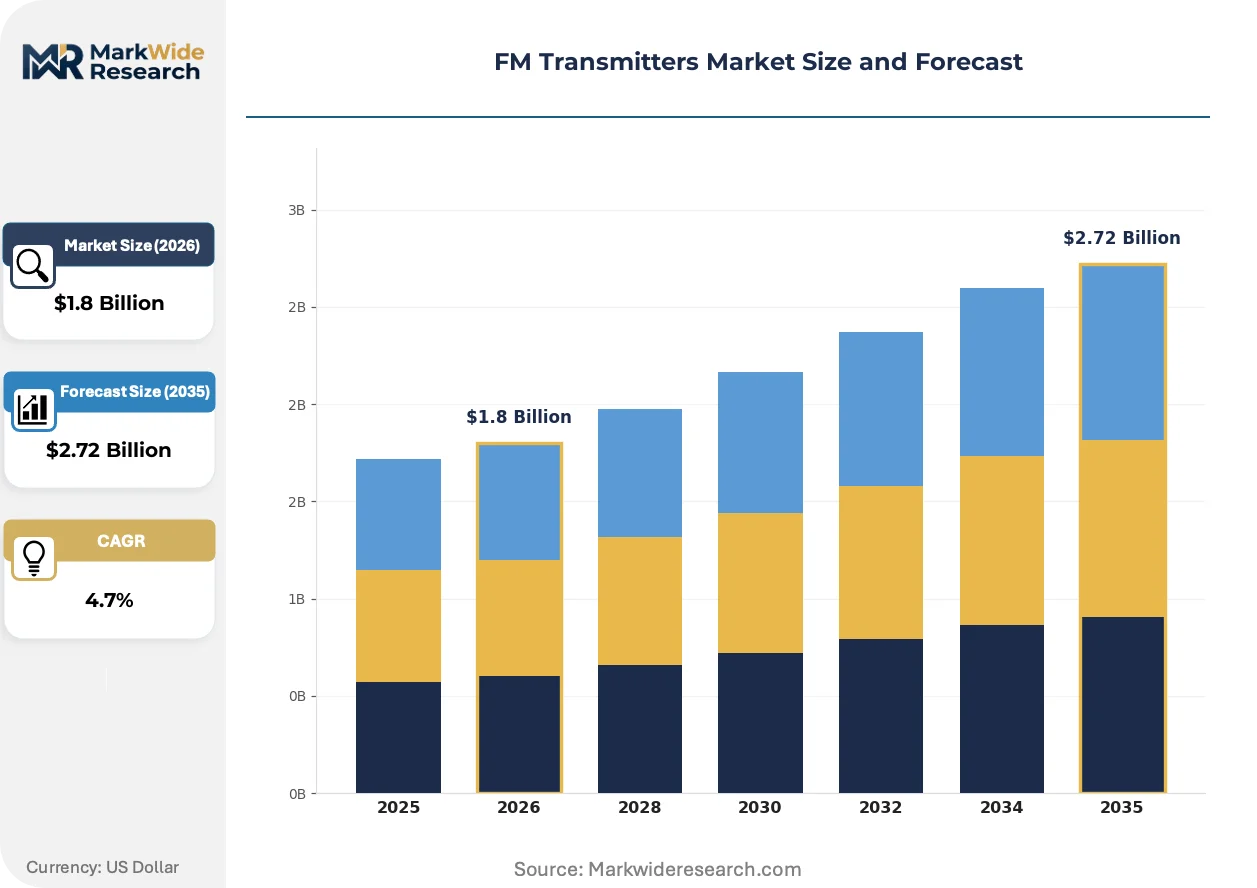
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Transmitters, Rack-Mount Transmitters, Portable Transmitters, Surround Sound Transmitters Technology: Analog FM, Digital FM, Stereo FM, RDS (Radio Data System) End User: Broadcast Stations, Educational Institutions, Commercial Establishments, Hobbyists Deployment: On-Premise, Cloud-Based, Hybrid, Integrated Solutions |
| Companies Covered | Crown Broadcast, DB Elettronica Telecomunicazioni Spa, Harris Corporation, Continental Electronics, Elenos, Nautel Ltd., Bext Inc., GatesAir, Rohde & Schwarz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FM Transmitters Market Evolving Landscape
Broadcast infrastructure is undergoing forced modernization as regulatory compression meets semiconductor evolution and shifting audience consumption patterns.
Solid-state transmitter architectures utilizing LDMOS and GaN power devices are supplanting tube-based systems across medium and high-power installations. Public broadcasters in Germany and the United Kingdom are accelerating this transition to meet efficiency mandates and reduce cooling infrastructure. The technology is compressing maintenance intervals and enabling remote diagnostics that tube systems cannot support.
REACH substance restrictions and RoHS compliance deadlines in the European Union are forcing redesigns of printed circuit board assemblies and thermal interface materials. Manufacturers serving continental European markets must reformulate solder alloys and eliminate restricted flame retardants from power supply enclosures. This regulatory pressure is most acute for rack-mount transmitter lines where component density complicates material substitution.
Station engineering departments are consolidating vendor relationships and demanding extended warranty packages that bundle preventive maintenance with hardware supply. Regional broadcast groups in Brazil and community radio networks in sub-Saharan Africa are replacing transactional equipment purchases with multi-year service agreements. This pattern is most visible where capital constraints meet aggressive uptime requirements for advertising-supported operations.
FM Transmitters Market Segmentation
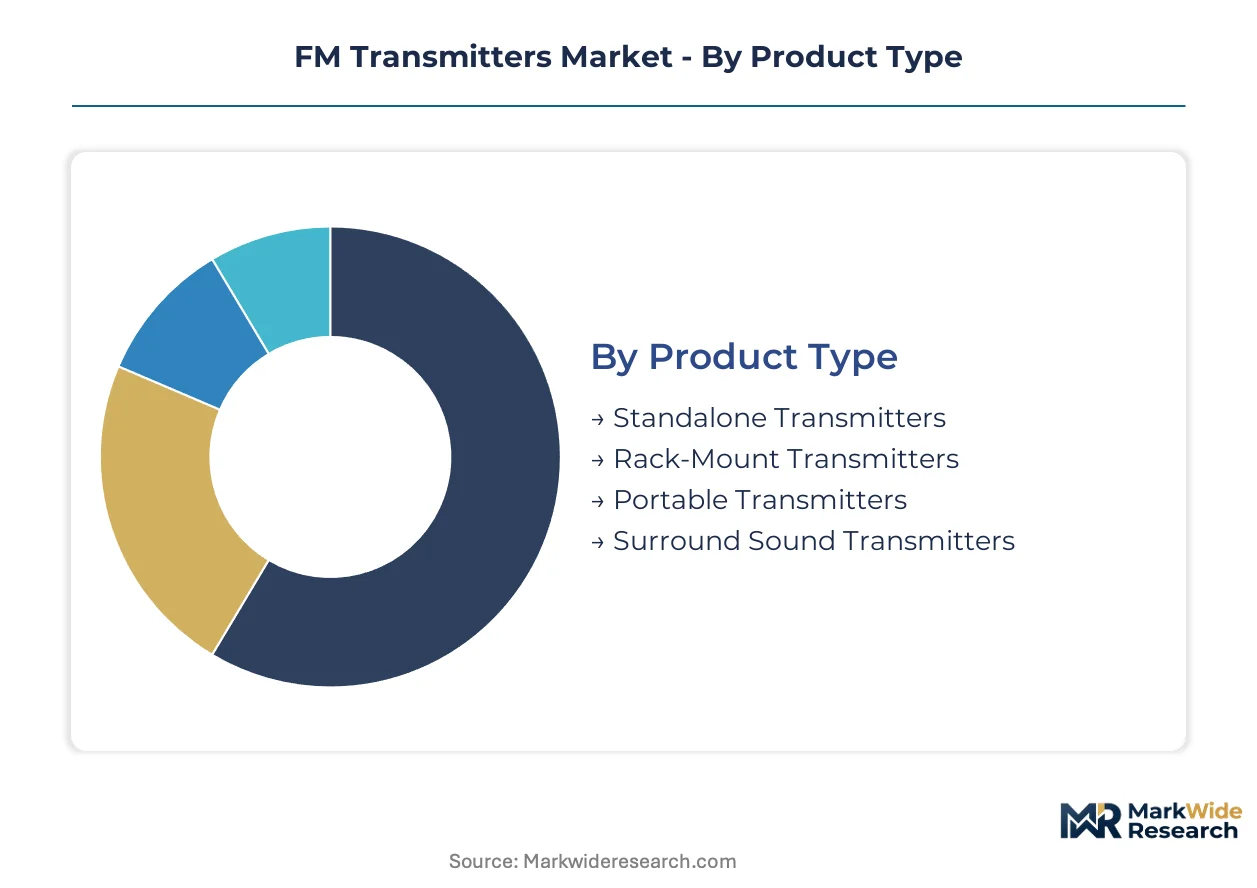
FM transmitter procurement patterns diverge sharply across installation contexts, with spectral efficiency mandates and broadcast format requirements reshaping segment priorities. Procurement teams must align product specifications with regulatory windows, infrastructure maturity, and operational scale.
Product Type:
Streaming audio substitution pressures terrestrial broadcast equipment unevenly, with fixed installations facing steeper revenue erosion than portable emergency systems.
- Standalone Transmitters:These floor-mounted units deliver high-power RF amplification for regional broadcast coverage, typically housing tube or solid-state amplifier stages in weatherized enclosures. Demand concentrates in Brazil's regional broadcasting sector, where ANATEL licensing reforms have expanded installation volumes for municipal stations seeking expanded coverage footprints.
- Rack-Mount Transmitters:Compact 19-inch chassis designs integrate power amplification, exciter modules, and monitoring systems for space-constrained facilities. European public broadcasters in Germany and the United Kingdom are accelerating procurement to meet efficiency mandates and reduce cooling infrastructure requirements.
- Portable Transmitters:Battery-powered or generator-compatible units enable rapid deployment for disaster response and temporary event coverage. Civil defense agencies across sub-Saharan Africa are modernizing resilient communication systems with these configurations.
- Surround Sound Transmitters:Specialized architectures supporting multi-channel audio encoding for premium broadcast formats. Theatrical and immersive radio experiments in Japan and South Korea drive limited procurement volumes.
Rack-Mount Transmitters retain volume leadership; Portable Transmitters hold the steepest expansion curve.
Technology:
Cost tier stratification separates legacy analog infrastructure from digitally-integrated premium configurations required for regulatory compliance.
- Analog FM:Conventional frequency modulation without digital augmentation still dominates installed base volumes across developing markets. Community radio stations in sub-Saharan Africa prioritize these systems for capital-constrained expansion.
- Digital FM:Digitally-processed baseband and modulation architectures enabling software-defined parameter adjustment. Brazil's regional broadcasters are adopting these systems to simplify multi-site network management.
- Stereo FM:Two-channel multiplex encoding for standard left-right audio reproduction. Legacy configurations face displacement as RDS-enabled alternatives penetrate European and Asian upgrade cycles.
- RDS (Radio Data System):Subcarrier data embedding for station identification, traffic updates, and emergency alerts. The FCC's broadcast spectrum repack mandates in the United States are accelerating replacement of stereo-only equipment with RDS-capable transmitters.
Analog FM retains volume leadership; RDS holds the steepest expansion curve.
End User:
Customer type determines procurement sophistication, with commercial broadcasters demanding integrated service packages that educational and hobbyist segments cannot support.
- Broadcast Stations:Professional terrestrial radio operators requiring continuous-duty transmission with regulatory compliance documentation. These entities are consolidating vendor relationships and demanding extended warranty packages that bundle preventive maintenance with hardware supply.
- Educational Institutions:University and school radio operations with intermittent broadcast schedules and student-operated technical staff. Campus stations in the United States leverage low-power FM licensing frameworks to minimize spectral fees.
- Commercial Establishments:Retail, hospitality, and venue operators using micro-broadcasting for customer experience or internal communications. Drive-through restaurants and shopping malls in Brazil deploy these systems for localized audio distribution.
- Hobbyists:Individual enthusiasts operating Part 15-compliant micro-transmitters or licensed low-power community stations. This segment concentrates in North American and European markets with accessible licensing pathways.
Broadcast Stations retain volume leadership; Commercial Establishments hold the steepest expansion curve.
Deployment:
Volume distribution favors physical infrastructure, though cloud-managed configurations are gaining share in multi-site broadcast networks.
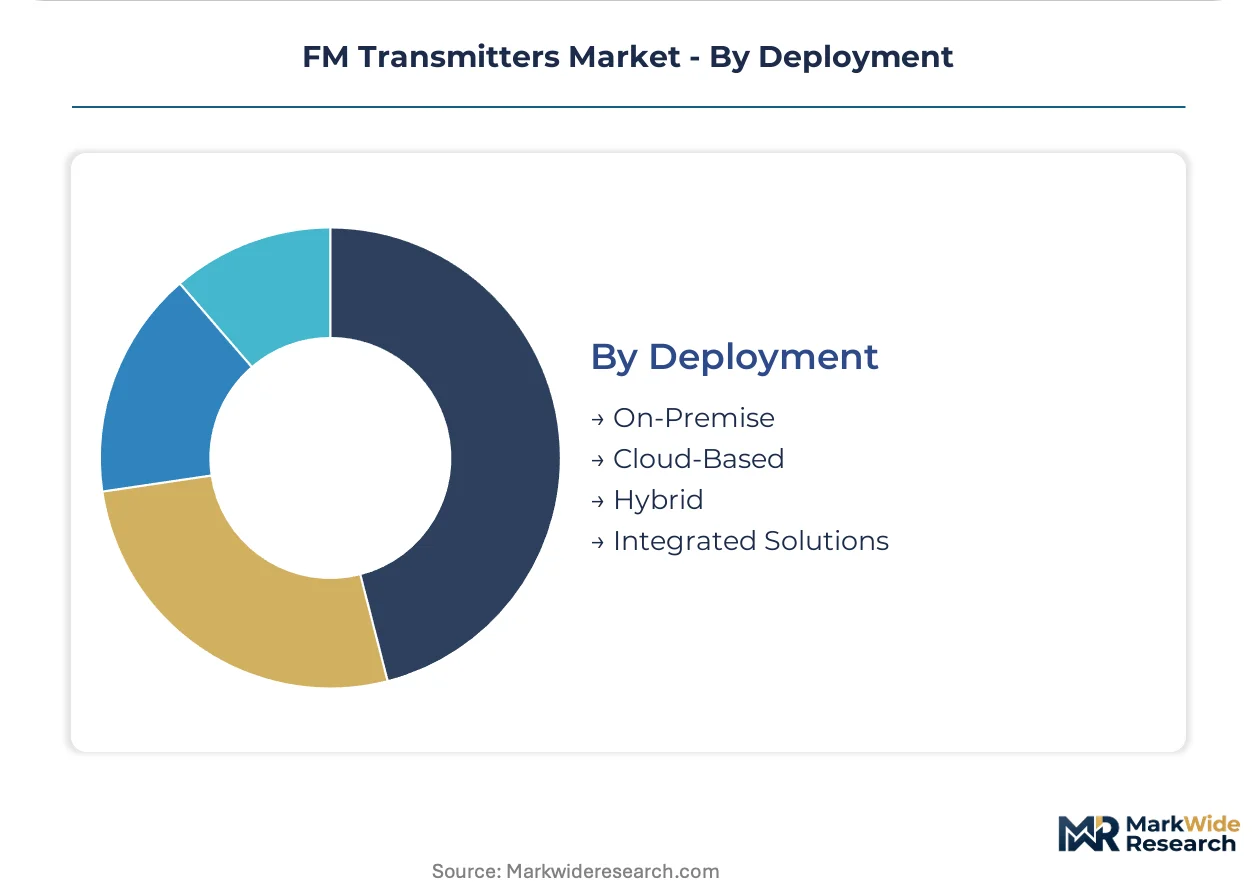
- On-Premise:Fully localized transmitter installation with dedicated studio-to-transmitter links and site engineering staff. This architecture dominates where spectrum licensing ties transmission facilities to specific geographic coordinates.
- Cloud-Based:Remote monitoring and control interfaces with centralized management dashboards. Regional broadcast groups in Brazil are piloting these configurations to reduce field engineering headcount across dispersed transmitter sites.
- Hybrid:Split architectures combining on-site RF amplification with cloud-hosted automation and content delivery. European public broadcasters are evaluating these models for disaster resilience.
- Integrated Solutions:Turnkey packages bundling transmitters, antennas, transmission line, and installation services. Sub-Saharan African community radio networks favor these offerings to overcome local RF engineering talent scarcity.
On-Premise retains volume leadership; Integrated Solutions hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in FM transmitter equipment tilt toward deficit positions in sub-Saharan Africa and surplus concentrations in Germany, the United States, and Brazil. Procurement teams track spectrum auction timelines and local content mandates to align capital deployment with regulatory windows.
United States
The FCC's broadcast spectrum repack mandates force stations to replace aging analog transmitters with compliant digital-ready equipment. Commercial and public broadcasters accelerate capital deployment to meet spectral efficiency deadlines. Station clusters in Texas and California drive concentrated procurement volumes for rack-mount and high-power standalone systems.
Brazil
ANATEL licensing reforms for community and regional stations have opened installation volumes in previously restricted frequency bands. Municipal broadcasters across São Paulo and Minas Gerais states seek expanded coverage footprints through standalone transmitter procurement. Local content requirements shape import substitution patterns for regional manufacturers.
Germany
Public broadcasters accelerate solid-state transmitter adoption to meet efficiency mandates and reduce cooling infrastructure. REACH substance restrictions and RoHS compliance deadlines force redesigns of printed circuit board assemblies. Engineering procurement concentrates in Bavaria and North Rhine-Westphalia where broadcast infrastructure modernization programs operate at scale.
Kenya
International development funding for rural information access drives transmitter procurement where broadcast penetration remains below urban saturation. Community radio networks favor integrated solutions bundling transmitters, antennas, and installation services to overcome local RF engineering talent scarcity. Nairobi anchors distribution logistics for sub-regional deployment.
United Kingdom
Public broadcasters transition tube-based systems to solid-state architectures to meet efficiency targets and enable remote diagnostics. CE marking obligations under the EU Radio Equipment Directive shape procurement specifications for continental market access. Broadcast engineering clusters in London and the Midlands coordinate multi-site network upgrades.
FM Transmitters Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and service network dimensions. The vendor base stratifies around solid-state architecture competence, precision engineering capabilities, and geographic service density. Three archetypes dominate: semiconductor-integrated manufacturers, precision RF engineering houses, and service-network broadcast specialists. Competitive moves concentrate on multi-year service agreement bundling and regional certification acquisition to defend installed base positions.
Within the precision engineering tier, Rohde & Schwarz and Elenos exemplify European technical specification leadership. Nautel Ltd. occupies a position among North American solid-state architecture providers. GatesAir anchors the service-network specialist archetype across Latin American broadcast markets. These three represent distinct competitive positioning vectors without overlapping core competence claims.
| Leading Market Players |
|---|
| Crown Broadcast |
| DB Elettronica Telecomunicazioni Spa |
| Harris Corporation |
| Continental Electronics |
| Elenos |
| Nautel Ltd. |
| Bext Inc. |
| GatesAir |
| Rohde & Schwarz |
| Others |
Value Network & Pricing Analysis
Foundry utilization rates in East Asian compound semiconductor manufacturing anchor cost structures across transmitter power amplifier tiers, compressing margins for mid-power equipment while premium rack-mount systems retain pricing power through integrated service bundling. Brazil's ANATEL local content mandates and the EU's REACH compliance deadlines force dual-track sourcing strategies that widen price spreads between certified and non-certified product lines.
Pricing Analysis
Broadcast station procurement teams anchor three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by CE marking compliance and remote diagnostic capability. Premium configurations from Rohde & Schwarz and Nautel Ltd. command service-inclusive contracts, while economy tiers face price erosion from GaN component spot-market volatility. Community radio networks in sub-Saharan Africa exhibit highest price sensitivity; European public broadcasters prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Strategic stockpiling of LDMOS and GaN power devices dominates inventory strategy as foundry allocation cycles create 12-18 month procurement windows for high-power amplifier stages. Manufacturing concentrates in Germany, the United States, and Italy, with raw material dependencies spanning Taiwanese silicon carbide substrates, Japanese precision ceramics, and Chinese rare-earth magnet assemblies. Single-source vulnerability in compound semiconductor foundries exposes transmitter OEMs to allocation risk. Distribution runs through authorized broadcast equipment distributors with field engineering capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spectral efficiency mandates and solid-state architecture transitions are reshaping competitive positioning, creating asymmetric opportunities across incumbent defense and new entrant white-space capture.
For Market Incumbents: Compound service network density in Latin America and sub-Saharan Africa to offset margin compression from GaN component costs. Deepen backward integration into power amplifier module assembly to reduce foundry allocation exposure. Prioritize multi-year preventive maintenance bundling to lock out low-cost competitors in Brazil's expanding municipal broadcaster segment. For New Entrants and Emerging Players: Aftermarket service coverage gaps in sub-Saharan African community radio networks present the most penetrable entry vector. Target integrated solution offerings bundling transmitters, antennas, and installation support to overcome local RF engineering scarcity. Pursue ANATEL certification pathways early to qualify for Brazil's licensing reform procurement windows. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors solid-state architecture specialists with captive service networks over tube-legacy installed base owners. Long-term viability hinges on digital integration capability for RDS and DRM convergence. Monitor FCC spectrum auction timelines as inflection signals for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Service Agreement Bundling | Locks in recurring revenue from Brazilian municipal broadcasters facing capital constraints. |
| CE Marking Fast-Track Certification | Accelerates EU market access for non-European manufacturers competing for public broadcaster tenders. |
| GaN Power Module Backward Integration | Reduces foundry allocation risk and compresses amplifier stage costs for mid-power transmitters. |
| Portable Transmitter Product Line Expansion | Captures civil defense modernization budgets across sub-Saharan African disaster response agencies. |
| RDS-Enabled Digital Architecture Migration | Aligns product portfolios with FCC repack mandates and European upgrade cycle requirements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with broadcast station chief engineers, RF amplifier design leads at transmitter OEMs, ANATEL certification specialists, and community radio network procurement coordinators. Secondary validation drew from FCC equipment authorization databases, ETSI technical specification filings, Brazilian customs import records, and World Bank development finance disclosures for sub-Saharan African media infrastructure. Bottom-up transmitter unit demand estimates triangulated against top-down broadcast spectrum licensing data.
Across the analysis window, forecasts segment by product type (standalone, rack-mount, portable, surround sound), technology tier (analog FM, digital FM, stereo FM, RDS), end-user category (broadcast stations, educational institutions, commercial establishments, hobbyists), and deployment model (on-premise, cloud-based, hybrid, integrated solutions). CAGRs derive from replacement cycle modeling against regulatory deadline schedules and semiconductor foundry capacity expansion trajectories. Specific inputs include ANATEL licensing reform implementation pace and FCC repack completion rates.
Forecasts assume regulatory continuity in FCC spectrum management, ANATEL local content enforcement, and EU Radio Equipment Directive certification requirements; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Radio and Audio Media
Traditional Radio Advertising Market
Radio and Audio Media
Podcast Advertising Market
Radio and Audio Media
Radio Advertising Market
Radio and Audio Media
Digital Audio Market
Radio and Audio Media
Voice Over New Radio Market
Radio and Audio Media
Podcast Hosting Services Market
Radio and Audio Media
Global Professional Audio Market
Radio and Audio Media
Audiobooks Market
Radio and Audio Media
Podcasting Market
Radio and Audio Media
Global 3D Audio Market
Radio and Audio Media
Audio Mixing Console Market
Radio and Audio Media
Latin America Soundbar Market
Radio and Audio Media
Microphone Market
Radio and Audio Media
Podcast Market
Radio and Audio Media
Internet Radio Market