
 Voice Over New Radio Market | 2026-2036
Voice Over New Radio Market Size, Share, and Industry Trends Forecast 2026-2036
Voice Over New Radio Market Analytics
Platform licensing revenue is fragmenting across chipset vendors, baseband suppliers, and network equipment makers as 5G standalone core deployments multiply. Qualcomm Technologies leverages its modem-RF system architecture to anchor premium tier device contracts. Nokia Corporation competes through Open RAN interoperability investments that sustain European operator relationships. Huawei Technologies controls domestic deployment scale while navigating export restriction complexities in select Western markets.
Voice Over New Radio (VoNR) transmits packetized voice natively over 5G new radio access without fallback to LTE circuits, requiring sub-20 millisecond end-to-end latency and EVS codec support for high-definition audio. The technology serves industrial IoT, autonomous systems, and mission-critical communications where legacy circuit-switched voice proves inadequate. Digital technology leads current infrastructure spend as operators retire analog backhaul, while streaming content type captures the fastest-growing revenue pool among broadcast applications. Distribution through online platforms concentrates margin expansion as programmatic ad insertion replaces traditional spot-buying workflows.
The 3GPP standards body governs VoNR air interface specifications, while national regulators including the FCC in the United States, Ofcom in the United Kingdom, and the Bundesnetzagentur in Germany enforce spectrum allocation and quality-of-service mandates that determine deployment timelines. Equipment vendors must certify products against country-specific electromagnetic compatibility and emergency calling requirements before commercial activation. Stakeholders should monitor 3GPP Release 18 timelines for satellite-terrestrial convergence features that could redefine voice service continuity expectations.
Market Dynamics
The transition from 5G non-standalone to standalone core architectures is forcing operators to reconfigure voice service delivery, eliminating LTE fallback dependencies and compressing deployment timelines for native packetized voice infrastructure.
Growth Catalysts
- 3GPP Release 16 mandates:The standards body enforces sub-20 millisecond latency benchmarks and EVS codec requirements that accelerate VoNR-capable device certification cycles.
- Connected vehicle platforms:Automotive OEMs integrate native 5G voice into telematics systems for emergency calling and over-the-air diagnostics, creating dedicated network slices.
- Industrial IoT voice:Manufacturing and logistics operations deploy mission-critical push-to-talk over 5G, replacing legacy TETRA and PTT systems in German chemical clusters and Chinese port automation zones.
Market Restraints
- Baseband chipset concentration:Premium-tier modem-RF system supply concentrates among three vendors, creating allocation bottlenecks during network buildout phases.
- Spectrum auction costs:Mid-band 5G licenses in the United States, Germany, and India consume 15-25% of operator capex budgets, diverting funds from core voice infrastructure.
- Interoperability testing burden:Multi-vendor Open RAN deployments require 18-24 month certification cycles against country-specific electromagnetic compatibility regimes.
Strategic Opportunities
- Satellite-terrestrial convergence:3GPP Release 18 non-terrestrial network specifications will enable voice service continuity in remote mining corridors and maritime shipping lanes.
- Programmatic ad insertion:Streaming broadcast applications are migrating spot-buying workflows to automated platforms, capturing margin expansion in audio content distribution.
- Mission-critical verticals:Public safety agencies in South Korea and the United Arab Emirates are procuring dedicated 5G voice networks for first responder coordination.
Industry Challenges
- VoLTE-to-VoNR migration complexity:Operators must maintain dual-stack voice cores during transition periods, doubling operational overhead and test automation requirements.
- RF engineering talent scarcity:mmWave propagation modeling and beam management expertise concentrates among specialists in Qualcomm's San Diego corridor and Huawei's Shenzhen base.
- Emergency calling certification:FCC E911 location accuracy mandates and Ofcom access requirements impose per-device testing costs that delay budget device launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voice Over New Radio Market |
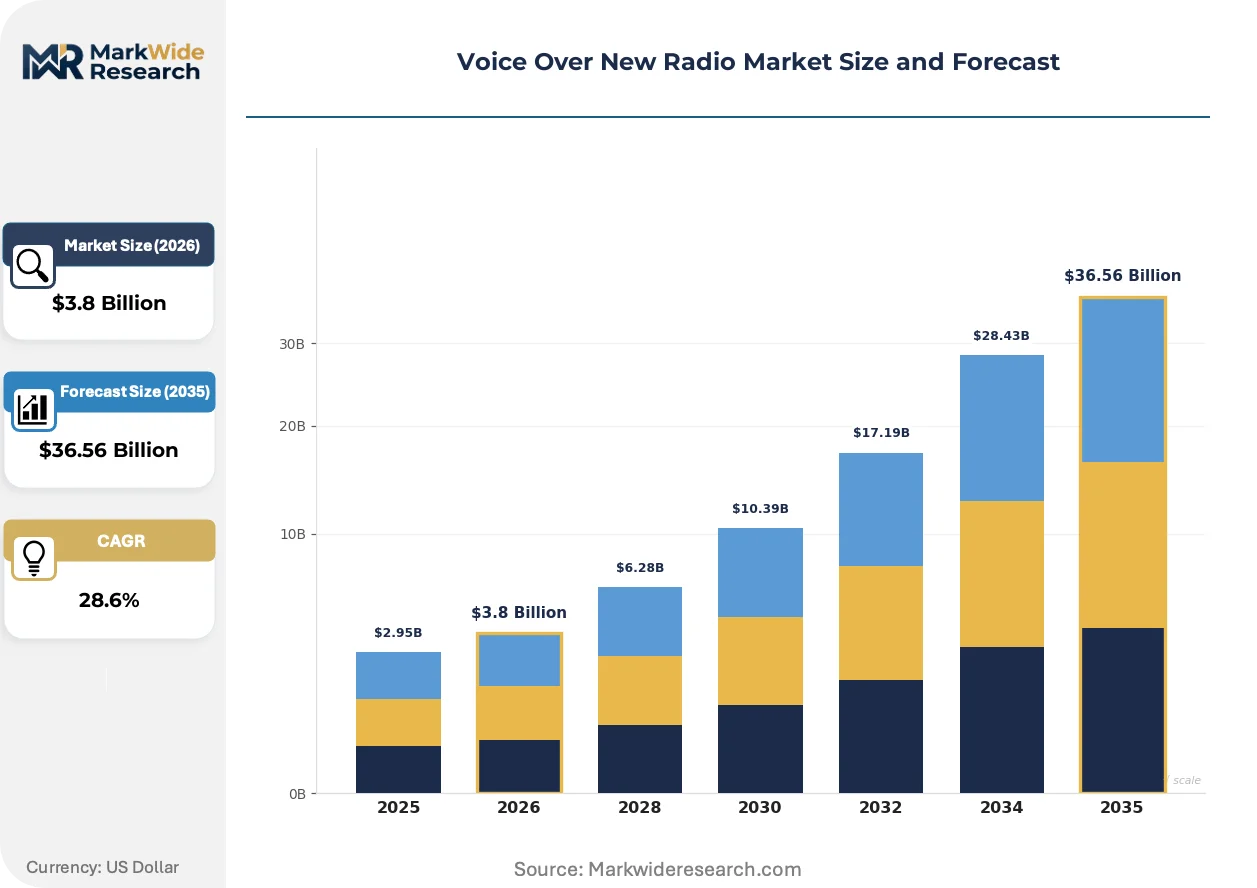
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.56 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Digital, Analog, Streaming, Mobile Content Type: Commercial Ads, News Reports, Talk Shows, Music Programming Distribution Channel: Online Platforms, Traditional Radio, Podcasting, Social Media End User: Advertisers, Broadcasters, Content Creators, Consumers |
| Companies Covered | T-Mobile USA, Nokia Corporation, Telefonaktiebolaget LM Ericsson, Qualcomm Technologies, Huawei Technologies, STC, Zain, Jio Platforms, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voice Over New Radio Market Evolving Landscape
Native packetized voice architectures are compressing the boundary between access and core networks, eliminating circuit-switched heritage and enabling new service definitions that operators are racing to commercialize before standards fully stabilize.
Enhanced Voice Services (EVS) codec implementation is rendering obsolete narrowband AMR-WB compression in premium smartphone tiers. Device OEMs in South Korea and Japan now mandate full-rate EVS support for flagship launches, forcing mid-tier suppliers to license codec IP or exit voice-capable segments. This codec shift is rendering obsolete the cost-optimized audio processing chains that dominated 4G-era bill-of-materials.
The FCC's 5G Fund for Rural America and the EU's Gigabit Infrastructure Act are redirecting subsidy eligibility toward standalone 5G voice coverage obligations. Operators in Montana and Bavaria must now demonstrate native VoNR service availability to qualify for deployment grants, altering site selection priorities. Rural infrastructure vendors are responding with integrated small-cell designs that collapse baseband and radio into single-enclosure formats.
Enterprise buyers in manufacturing and energy verticals are consolidating communications procurement under single-platform managed service contracts. Systems integrators are displacing traditional telecom resellers in German automotive supplier parks and Texas oilfield operations. This consolidation is most visible in the North American market, where AT&T and Verizon have established dedicated vertical sales divisions for industrial voice and IoT bundling.
Voice Over New Radio Market Segmentation
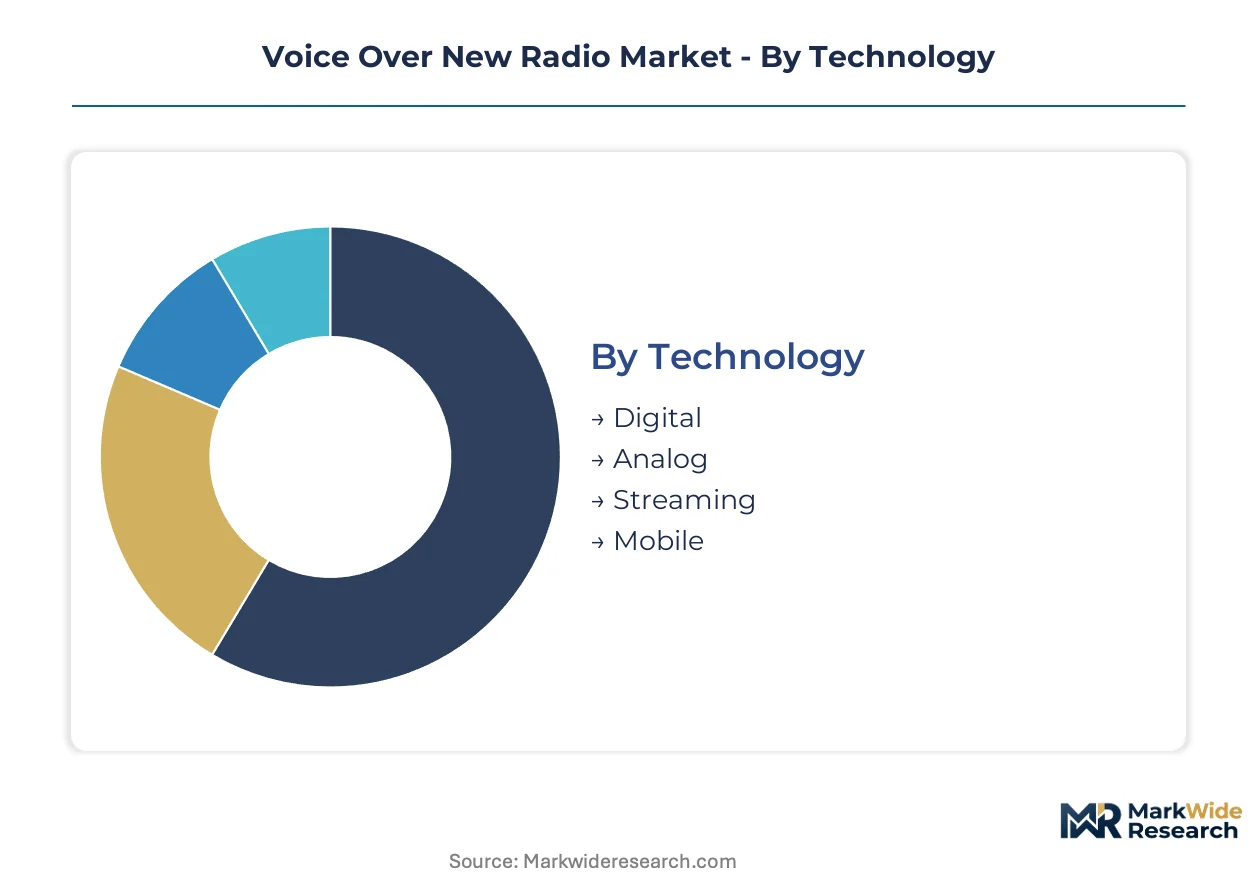
VoNR market segmentation reveals how voice service economics bifurcate across infrastructure maturity and content monetization models. Understanding these divisions exposes where operators capture margin versus where they merely transport bits.
Technology:
Cost tier determines deployment sequencing and margin capture across voice infrastructure layers.
- Digital:Packet-switched voice over 5G standalone cores eliminates circuit-switched fallback dependencies. Operators in China and Germany prioritize digital infrastructure spend as they retire analog backhaul systems and compress latency budgets below 20 milliseconds.
- Streaming:Adaptive bitrate voice delivery enables high-definition audio in bandwidth-constrained environments. South Korean device OEMs now mandate full-rate EVS codec support for flagship launches, forcing codec IP licensing downstream.
- Analog:Legacy circuit-switched infrastructure persists in rural coverage obligations where VoNR handset penetration remains insufficient.
- Mobile:Smartphone-native voice clients dominate consumer-facing deployments but require dual-stack core maintenance during transition periods.
Digital commands the established base. The steepest expansion runs through Streaming.
Content Type:
Application use case separates infrastructure-heavy emergency services from monetizable media formats.
- Commercial Ads:Programmatic insertion workflows replace traditional spot-buying, concentrating margin in automated platforms. Audio content distributors in the United States capture expanded margins as programmatic systems displace manual trafficking.
- News Reports:Live field reporting demands sub-20 millisecond latency for two-way interviews. Broadcasters in the United Kingdom deploy dedicated network slices for correspondent uplinks.
- Talk Shows:Studio-based formats tolerate higher latency thresholds, reducing infrastructure premium.
- Music Programming:Pre-recorded content minimizes real-time quality constraints.
Commercial Ads commands the established base. The steepest expansion runs through News Reports.
Distribution Channel:
Customer type determines who controls the listener relationship and data exhaust.
- Online Platforms:Centralized streaming services aggregate audience measurement and ad targeting. German automotive OEMs integrate native 5G voice into telematics systems, creating dedicated network slices for over-the-air diagnostics and emergency calling.
- Podcasting:On-demand audio formats shift consumption patterns away from linear broadcast schedules.
- Traditional Radio:Terrestrial broadcast maintains reach in demographics with lower smartphone penetration.
- Social Media:Ephemeral voice content competes for attention in fragmented consumption environments.
Traditional Radio commands the established base. The steepest expansion runs through Online Platforms.
End User:
Maturity of voice service adoption varies sharply across buyer sophistication and procurement scale.
- Advertisers:Demand granular attribution data that IP-based voice infrastructure enables. Systems integrators displace traditional telecom resellers in Texas oilfield operations as enterprise buyers consolidate communications procurement.
- Broadcasters:Require guaranteed quality-of-service for live production workflows.
- Content Creators:Independent producers prioritize low-barrier distribution over technical specifications.
- Consumers:Mass-market adoption depends on handset replacement cycles and carrier VoNR activation policies.
Broadcasters commands the established base. The steepest expansion runs through Advertisers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys VoNR infrastructure at manufacturing scale, while Germany and the United States concentrate on precision latency benchmarks for automotive and industrial verticals. This consumption-mix differential shapes how operators prioritize capex across markets.
United States
Verizon and AT&T drive standalone 5G core buildouts for industrial IoT voice in Texas oilfields and Arizona semiconductor corridors. The FCC's 5G Fund for Rural America mandates native VoNR coverage for subsidy eligibility. Montana and North Dakota operators now deploy integrated small-cell designs to meet grant requirements.
Germany
Bundesnetzagentur enforces quality-of-service mandates that compress deployment timelines for automotive OEM telematics. Bavarian chemical clusters and Baden-Württemberg automotive supplier parks replace legacy TETRA systems with mission-critical push-to-talk. The EU Gigabit Infrastructure Act redirects subsidies toward standalone 5G voice obligations.
China
MIIT spectrum allocations accelerate mid-band 5G voice deployment across Yangtze River Delta manufacturing hubs. Huawei Technologies anchors domestic equipment supply while export restrictions limit Western market penetration. Shenzhen and Shanghai operators retire analog backhaul systems ahead of 3GPP Release 16 deadlines.
South Korea
Seoul Capital Area operators mandate full-rate EVS codec support for flagship device launches. MFDS certification requirements push mid-tier suppliers toward codec IP licensing or segment exit. Public safety agencies procure dedicated 5G voice networks for first responder coordination in Busan-Ulsan industrial zones.
United Arab Emirates
Etisalat and du integrate native 5G voice into NEOM smart city infrastructure and Dubai logistics automation. MOHAP coordinates emergency calling certification with GCC interoperability standards. Abu Dhabi oilfield operators consolidate communications procurement under single-platform managed service contracts.
Voice Over New Radio Market Competitive Landscape
Capability concentration sits with integrated modem-RF system architects; scale advantage sits with network equipment vendors with Open RAN interoperability investments. The market structures around three tiers: premium-tier chipset vendors, European operator-focused equipment makers, and China-scale domestic deployers. Strategic moves center on 3GPP standards compliance acceleration and vertical sales division establishment for industrial voice bundling.
Within the integrated chipset tier, Qualcomm Technologies occupies the premium device anchor position. Nokia Corporation and Telefonaktiebolaget LM Ericsson exemplify the European operator relationship archetype through Open RAN certification investments. Huawei Technologies represents the domestic-scale deployer model, navigating export restriction complexities while controlling equipment supply in its home market.
| Leading Market Players |
|---|
| T-Mobile USA |
| Nokia Corporation |
| Telefonaktiebolaget LM Ericsson |
| Qualcomm Technologies |
| Huawei Technologies |
| STC |
| Zain |
| Jio Platforms |
| Samsung Electronics |
| Others |
Value Network & Pricing Analysis
Undercapacity in mmWave baseband chipset fabrication across Taiwan and South Korea is compressing supplier margins while forcing premium-tier OEMs into multi-year offtake commitments that lock in pricing floors for VoNR-capable modem-RF systems.
Pricing Analysis
Long-term offtake contracts dominate premium-tier chipset procurement, with operators committing to volume minimums that insulate Qualcomm Technologies and Samsung Electronics from spot-market volatility. Price differentiation hinges on EVS codec certification tier and network slice orchestration capability, with mid-tier suppliers facing cost compression as South Korean device OEMs mandate full-rate codec support. Pricing pressure stems from spectrum auction cost absorption diverting operator capex from voice infrastructure. Broadcasters exhibit least price sensitivity due to quality-of-service guarantees, while mid-tier smartphone OEMs face acute margin constraints.
Supply Chain Analysis
Upstream feedstock concentration in gallium arsenide wafer production centers on Japan, Germany, and the United States, with substrate supply tightening as defense and telecom applications compete for limited foundry slots. Raw material dependencies span RF front-end filters, baseband processor silicon, and advanced packaging substrates. Single-source vulnerability concentrates in beamforming antenna module supply, where Qualcomm's San Diego corridor and Huawei's Shenzhen base concentrate specialized engineering talent. Distribution runs through direct operator procurement channels and systems integrator-managed service contracts for industrial verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
VoNR infrastructure deployment represents a high-growth disruption as 3GPP Release 16 mandates force simultaneous retirement of analog backhaul and compression of latency budgets below 20 milliseconds across three major economies.
For Market Incumbents: Entrench modem-RF system architecture advantages through accelerated EVS codec IP licensing to mid-tier device OEMs facing certification exit threats. Expand Open RAN interoperability investments to sustain European operator relationships against Nokia Corporation and Telefonaktiebolaget LM Ericsson consolidation moves. Prioritize vertical sales division establishment for industrial voice bundling in German chemical clusters and Texas oilfield operations.
For New Entrants and Emerging Players: Rural coverage obligation markets in Montana and Bavaria represent the most penetrable entry point, where integrated small-cell design capabilities bypass incumbent baseband concentration. Mission-critical push-to-talk replacement in Chinese port automation zones offers second-mover positioning as legacy TETRA systems depreciate. Target systems integrator partnerships over direct operator sales to bypass certification cycle barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across standalone 5G core voice infrastructure as dual-stack maintenance requirements double operational overhead during VoLTE-to-VoNR migration windows. Acquisition candidates should demonstrate 3GPP Release 18 satellite-terrestrial convergence roadmap positioning. Monitor Bundesnetzagentur and FCC rural coverage grant disbursement velocity as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| EVS Codec IP Licensing Expansion | Mid-tier OEM certification compliance in South Korea and Japan forces licensing revenue capture from suppliers facing segment exit. |
| Open RAN Interoperability Certification | European operator relationships with Nokia Corporation and Ericsson sustain against integrated chipset vendor consolidation. |
| Network Slice Orchestration Platform Launch | German automotive OEM telematics integration creates dedicated infrastructure revenue streams for emergency calling services. |
| Vertical Sales Division Establishment | AT&T and Verizon industrial voice bundling in Texas oilfields displaces traditional telecom reseller channels. |
| Satellite-Terrestrial Convergence R&D | 3GPP Release 18 non-terrestrial specifications enable voice continuity in remote mining corridors beyond terrestrial coverage. |
Research Methodology
Desk research of 3GPP standards documentation, national regulatory filings with the FCC and Bundesnetzagentur, and operator capex disclosure statements preceded structured interviews with network equipment procurement directors, baseband chipset product managers, automotive telematics platform engineers, and broadcast technology integration specialists. Secondary validation drew from spectrum auction result databases, device certification registries, and infrastructure deployment tracking systems. Bottom-up triangulation across operator rollout timelines and top-down reconciliation against equipment vendor revenue disclosures anchored market sizing.
Assumptions around 3GPP Release 16 compliance deadlines and mid-band spectrum allocation timelines were held fixed, while VoNR handset penetration curves and industrial IoT voice adoption rates were varied across sensitivity scenarios. Segmentation modeling spanned technology tier, content monetization format, distribution channel control, and end-user procurement sophistication. CAGRs were derived from logistic diffusion curves fitted to infrastructure deployment data. Forecast inputs incorporated Open RAN certification cycle durations and rural coverage grant eligibility thresholds.
Practitioners should monitor 3GPP Release 18 timeline acceleration and satellite-terrestrial network integration standards for early signals of voice service continuity expectation shifts. Forecasts reflect assumptions around regulatory mandate adherence and chipset supply allocation stability. Cross-checking against national spectrum auction outcome databases and equipment vendor order backlog disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Radio and Audio Media
Podcast Hosting Services Market
Radio and Audio Media
Podcast Market
Radio and Audio Media
Podcasting Market
Radio and Audio Media
Microphone Market
Radio and Audio Media
Audio Mixing Console Market
Radio and Audio Media
Audiobooks Market
Radio and Audio Media
Radio Advertising Market
Radio and Audio Media
Global 3D Audio Market
Radio and Audio Media
Latin America Soundbar Market
Radio and Audio Media
Traditional Radio Advertising Market
Radio and Audio Media
Internet Radio Market
Radio and Audio Media
Global Professional Audio Market
Radio and Audio Media
Digital Audio Market
Radio and Audio Media
FM Transmitters Market
Radio and Audio Media
Podcast Advertising Market