
 Latin America Soundbar Market | 2026-2036
Latin America Soundbar Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Soundbar Market Intelligence
Buyer concentration across Latin American retail channels is shifting as e-commerce platforms fragment traditional electronics distribution while specialized audio retailers consolidate in major metros. Samsung Electronics leverages its integrated display-audio ecosystem to control shelf space in Brazilian and Mexican big-box chains. Sony Group Corporation anchors premium positioning through acoustic engineering specialization and home theater bundling. LG Electronics competes aggressively on price-performance ratios in mid-tier wireless segments.
A soundbar is a loudspeaker enclosure containing multiple drivers—typically tweeters, mid-range woofers, and sometimes integrated subwoofers—designed to project audio from a single horizontal chassis beneath a television display, with power outputs ranging from 40W to 500W and connectivity via HDMI ARC, optical TOSLINK, or wireless protocols. Wireless and Bluetooth-enabled units lead volume growth as consumers abandon wired home theater installations, while multi-room configurations capture margin pools among affluent households seeking whole-home audio synchronization. HDMI ARC technology dominates commercial and hospitality deployments where single-cable simplicity reduces installation complexity.
ANATEL in Brazil, IFETEL in Mexico, and SUBTEL in Chile enforce electromagnetic compatibility and radio frequency standards that dictate wireless audio product certification timelines and technical compliance costs. These frameworks delay market entry for unapproved SKUs while favoring manufacturers with established regional testing relationships. Stakeholders must monitor evolving energy efficiency labeling requirements and streaming codec licensing shifts that could reshape product feature prioritization.
Market Dynamics
Streaming platform expansion across Brazil and Mexico is compressing replacement cycles for legacy home theater systems, while ANATEL certification mandates force hardware redesigns that favor established suppliers with regional testing infrastructure.
Growth Catalysts
- ANATEL Certification Alignment:Brazil's radio frequency standards for wireless audio devices are accelerating compliance investments among manufacturers with existing São Paulo testing partnerships.
- HDMI ARC Protocol Dominance:Single-cable audio return channel technology is displacing optical TOSLINK in hospitality and commercial installations throughout Mexico City and Santiago corridors.
- Metropolitan Household Density:São Paulo and Mexico City apartment dwellers favor space-efficient soundbar form factors over multi-speaker surround configurations.
Market Restraints
- Bluetooth Module Supply Concentration:Dependence on Asian semiconductor foundries for wireless chipsets creates lead time volatility for Brazilian assembly operations.
- IFETEL Spectrum Allocation Friction:Mexico's frequency harmonization delays for 5GHz Wi-Fi audio transmission extend product validation timelines by four to six months.
- Smart Speaker Substitution:Voice-activated assistant devices from Amazon and Google capture budget-conscious consumers seeking multi-function audio endpoints.
Strategic Opportunities
- Chilean SUBTEL Streamlining:Santiago's simplified electromagnetic compatibility filing process offers faster market entry for Wi-Fi 6E-enabled soundbar variants.
- Multi-Room Audio Convergence:Integration of Dolby Atmos height virtualization with whole-home synchronization protocols targets affluent households in Rio de Janeiro's Zona Sul.
- Specialized Audio Retail Consolidation:Dedicated home theater chains in Monterrey and Guadalajara provide premium positioning channels outside mass-market big-box saturation.
Industry Challenges
- Acoustic Engineering Talent Scarcity:Limited regional expertise in DSP tuning for confined enclosure acoustics forces reliance on outsourced firmware development.
- Cross-Border Certification Complexity:Divergent SUBTEL, IFETEL, and ANATEL test protocols require redundant documentation for pan-Latin American product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Soundbar Market |
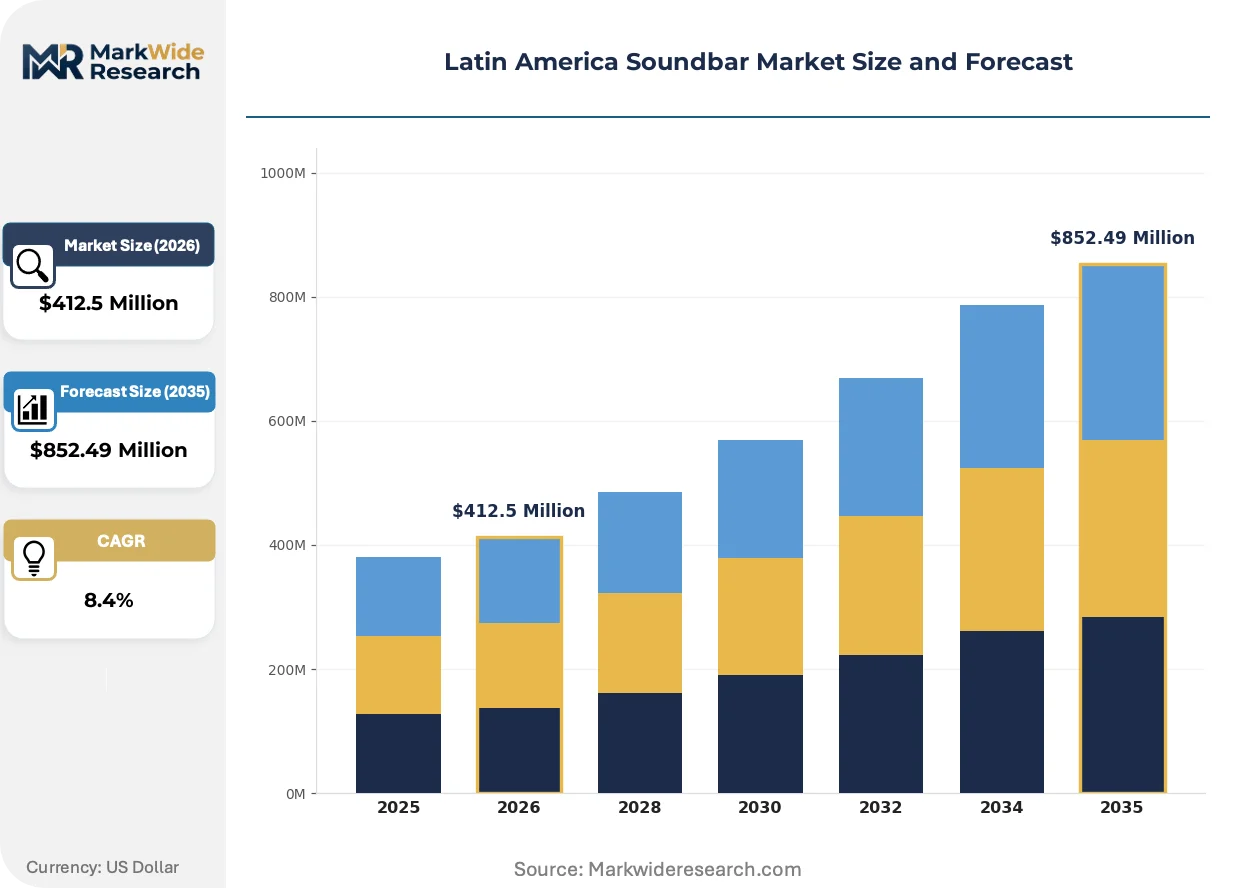
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $852.49 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired, Wireless, Multi-Room, Soundbase End User: Residential, Commercial, Entertainment Venues, Hospitality Technology: Bluetooth, Wi-Fi, HDMI ARC, Optical Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesalers |
| Companies Covered | Bose Corporation, VOXX International, Samsung Electronics, Panasonic Holdings, Koninklijke Philips, Sony Group Corporation, DEI Holdings, Yamaha Corporation, LG Electronics, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Soundbar Market Strategic Shifts & Innovations
Dolby Atmos height virtualization and Wi-Fi 6E wireless protocols are compressing the performance gap between compact soundbars and discrete multi-speaker installations across Latin American metropolitan markets.
Dolby Atmos virtualization technology is rewriting spatial audio expectations by synthesizing overhead height channels through upward-firing drivers and psychoacoustic processing. Residential buyers in São Paulo's luxury condominium segment are specifying Atmos-enabled units for 65-inch and larger television pairings. The technology is compressing demand for ceiling-mounted speaker installations that dominate legacy home theater configurations.
ANATEL's updated Resolution 2420 for short-range devices mandates revised electromagnetic emission testing protocols for all Bluetooth 5.3 and Wi-Fi 6E audio products entering Brazilian commerce. Manufacturers with established INMETRO-accredited laboratory relationships capture six-to-eight-week certification advantages over new market entrants. Premium wireless soundbar SKUs face disproportionate compliance cost impacts relative to entry-level optical-only alternatives.
Specialized audio retailers in Mexico City and Monterrey are unbundling installation and calibration services from hardware transactions, shifting toward consultative selling models. This channel evolution displaces pure price competition at big-box electronics chains while capturing margin pools from affluent buyers seeking acoustic optimization. The behavioral shift is most visible in Nuevo León state, where dedicated home theater showrooms report service attach rates exceeding forty percent of hardware transactions.
Latin America Soundbar Market Segmentation
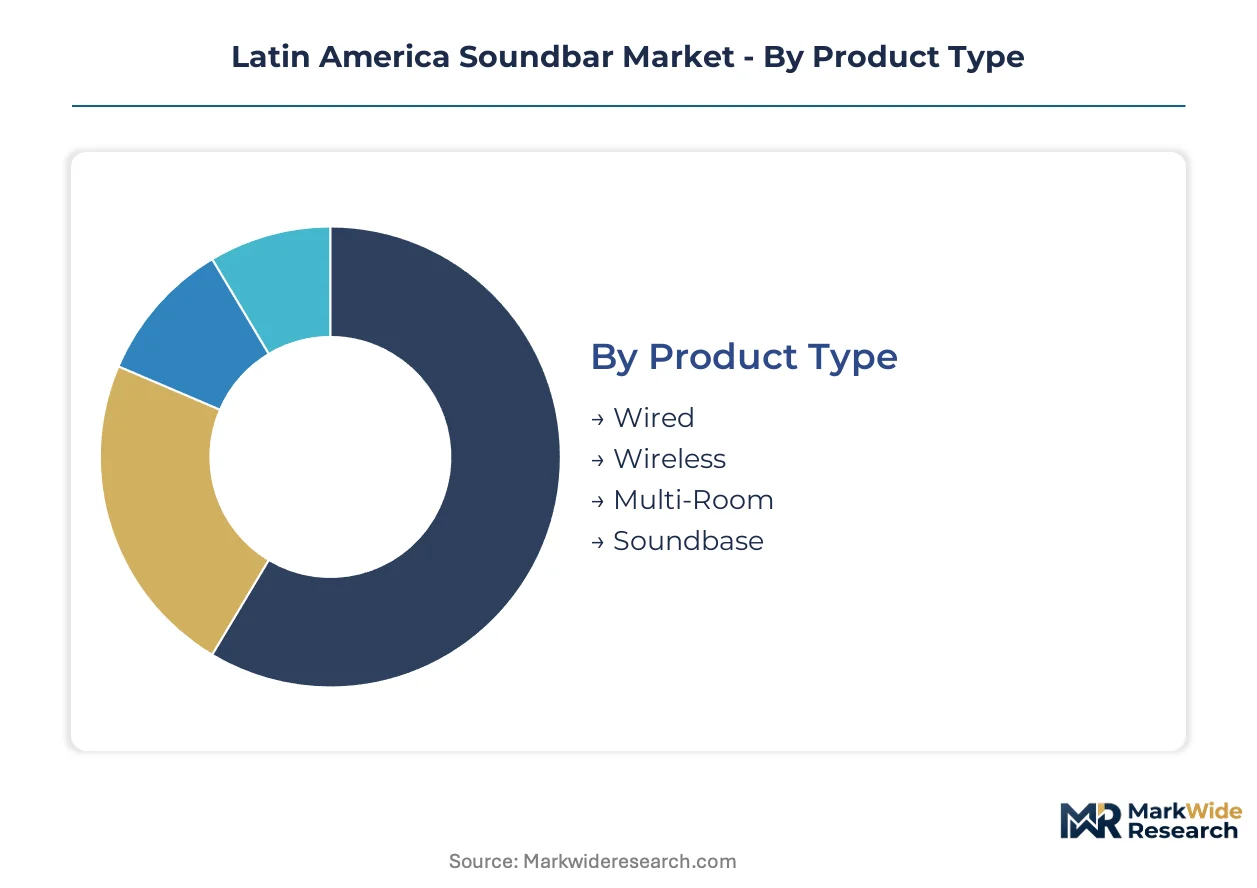
Soundbar purchasing patterns across Latin America fragment sharply across connectivity preferences, installation environments, and retail access. Manufacturers must align SKU portfolios with divergent certification requirements and acoustic constraints that vary by deployment setting.
Product Type:
Form factor and connectivity architecture separate buyers by installation flexibility and spatial constraints.
- Wireless:Bluetooth and Wi-Fi-enabled chassis eliminate cable runs for apartment dwellers in São Paulo and Mexico City. ANATEL certification for 2.4GHz and 5GHz modules favors suppliers with established Brazilian testing partnerships, compressing margins for new entrants.
- Multi-Room:Synchronized whole-home audio configurations integrate with residential automation systems in Rio de Janeiro's Zona Sul and Monterrey's San Pedro district. Dolby Atmos height virtualization drives specification for premium condominium installations.
- Wired:HDMI ARC and optical TOSLINK connections dominate hospitality retrofit projects where infrastructure reliability outweighs consumer convenience priorities.
- Soundbase:Integrated subwoofer enclosures serve television pedestal applications in space-constrained Santiago apartments where wall mounting is prohibited by lease terms.
Volume sits with Wireless; growth tilts toward Multi-Room.
End User:
Acoustic performance requirements and procurement authority structures reshape competitive dynamics across buyer categories.
- Residential:Streaming service penetration in Brazilian and Mexican metropolitan households compresses replacement cycles for legacy home theater systems. Buyers prioritize single-cable HDMI ARC simplicity over multi-speaker calibration complexity.
- Commercial:Corporate boardrooms and co-working spaces in Santiago's Las Condes district specify soundbars for video conferencing integration. Procurement runs through facility management contracts with standardized audio-visual vendors.
- Hospitality:Hotel chains across Mexico City and Guadalajara deploy soundbars in guest rooms to reduce installation labor versus in-wall speaker systems. IFETEL certification timelines delay product refresh cycles.
- Entertainment Venues:Small-format cinemas and gaming lounges in São Paulo's Pinheiros neighborhood adopt compact soundbar arrays where floor space commands premium rents.
Residential commands absolute volume; Hospitality exhibits the steepest expansion trajectory as hotel chains standardize room audio.
Technology:
Protocol selection determines certification burden, latency characteristics, and interoperability with existing display infrastructure.
- HDMI ARC:Audio return channel technology transmits uncompressed multi-channel streams through single-cable television connections. Commercial installations throughout Mexico City and Santiago corridors favor this protocol for reduced installation complexity.
- Bluetooth:Short-range wireless pairing dominates entry-level residential sales where smartphone audio streaming is the primary use case. ANATEL Resolution 2420 mandates revised electromagnetic emission testing for Bluetooth 5.3 variants.
- Wi-Fi:Whole-home synchronization and high-resolution codec support attract affluent buyers seeking lossless audio transmission. IFETEL spectrum allocation friction for 5GHz bands extends Mexican product validation timelines.
- Optical:TOSLINK connections persist in legacy hospitality installations where HDMI infrastructure predates ARC protocol standardization.
HDMI ARC anchors current deployment volume; Wi-Fi is climbing the fastest as multi-room configurations penetrate premium residential segments.
Distribution Channel:
Channel selection reflects buyer price sensitivity, installation service requirements, and geographic access to physical retail infrastructure.
- Online Retail:E-commerce platforms fragment traditional electronics distribution while capturing price-comparison shoppers in Brazilian and Mexican secondary cities. Logistics networks concentrate fulfillment in São Paulo and Mexico City metropolitan corridors.
- Offline Retail:Big-box electronics chains maintain shelf space dominance for impulse purchases and immediate gratification buyers. Samsung leverages integrated display-audio ecosystem control to secure prominent positioning.
- Direct Sales:Manufacturer-owned channels bypass retail margin capture for commercial and hospitality volume contracts. Procurement teams in Monterrey and Guadalajara favor direct relationships for standardized property-wide deployments.
- Wholesalers:Regional distributors serve specialized audio retailers in Santiago and smaller Brazilian markets where direct manufacturer presence remains limited.
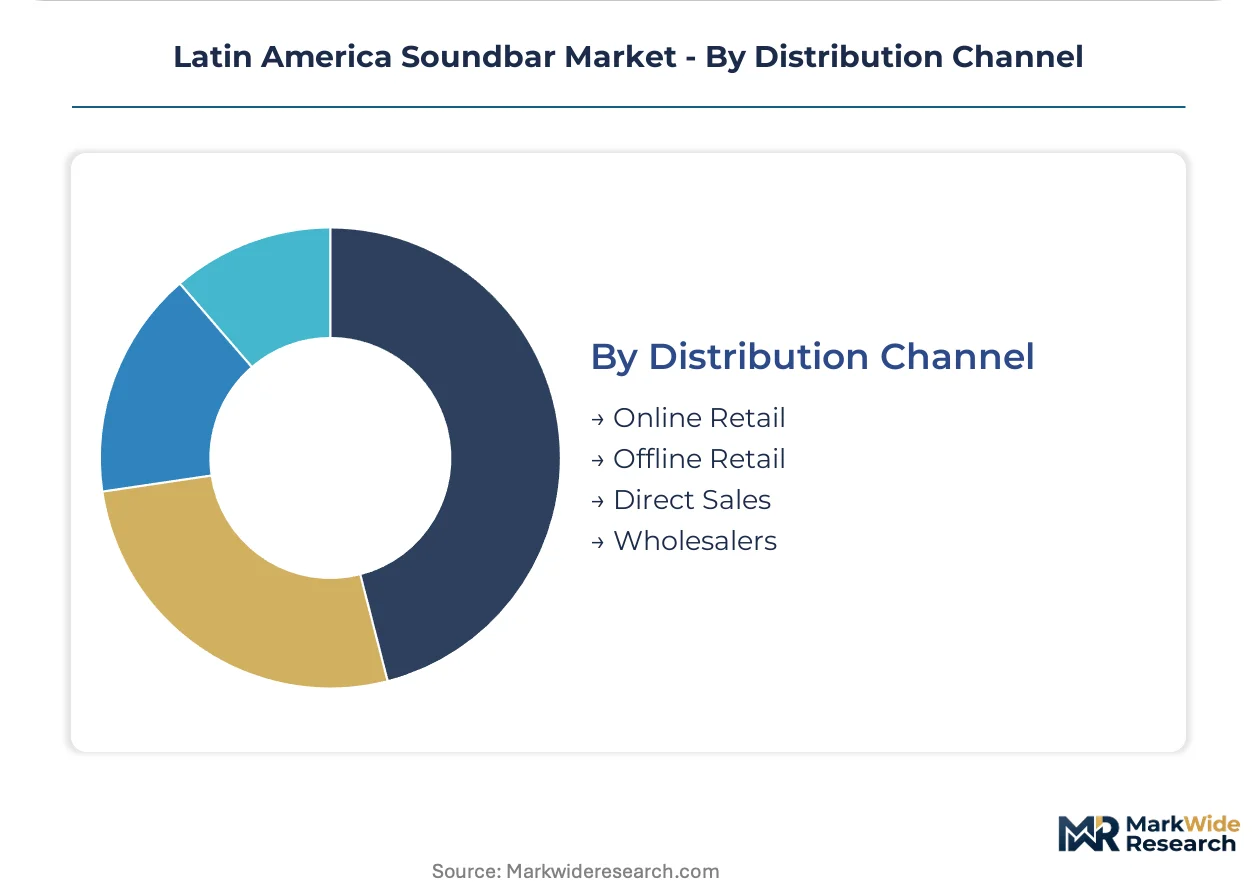
Offline Retail retains volume leadership; Online Retail is gaining share fastest as fulfillment infrastructure penetrates secondary metropolitan areas.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian semiconductor assembly clusters anchor Latin American soundbar supply, with São Paulo metropolitan foundries feeding downstream audio electronics manufacturing across the continent.
Brazil
Streaming service penetration in São Paulo and Rio de Janeiro condominiums compresses replacement cycles for legacy home theater systems. ANATEL Resolution 2420 mandates revised electromagnetic emission testing for all Bluetooth 5.3 and Wi-Fi 6E audio products entering Brazilian commerce. INMETRO-accredited laboratories in São Paulo's Barra Funda district capture six-to-eight-week certification advantages over new market entrants.
Mexico
IFETEL spectrum allocation friction for 5GHz Wi-Fi audio transmission extends product validation timelines by four to six months for manufacturers lacking established testing partnerships. Nuevo León state's dedicated home theater showrooms report service attach rates exceeding forty percent of hardware transactions. Monterrey and Guadalajara specialized audio retailers are unbundling installation and calibration services from hardware transactions.
Chile
Santiago's simplified SUBTEL electromagnetic compatibility filing process offers faster market entry for Wi-Fi 6E-enabled soundbar variants. Apartment dwellers in Las Condes and Providencia favor space-efficient soundbar form factors over multi-speaker surround configurations. Corporate boardrooms in Santiago's financial district specify soundbars for video conferencing integration through facility management contracts.
Argentina
Currency volatility and import restrictions compress consumer electronics procurement budgets in Buenos Aires metropolitan households. The country's national telecommunications regulator enforces electromagnetic compatibility standards that delay product registration for manufacturers without established local representation. Palermo and Recoleta district retailers concentrate premium audio inventory for affluent buyers seeking whole-home audio synchronization.
Colombia
Bogotá and Medellín metropolitan corridors exhibit accelerating demand for HDMI ARC-enabled units as streaming platform adoption expands. The country's national spectrum agency manages radio frequency certification timelines that favor suppliers with existing Andean region testing relationships. Zona Rosa and Parque Lleras entertainment districts drive commercial soundbar deployment for small-format cinema and gaming lounge applications.
Latin America Soundbar Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue multi-room audio convergence and specialized retail channel consolidation. The market structures around three distinct maturity tiers: integrated display-audio ecosystem controllers, acoustic engineering specialists, and price-performance optimizers. Strategic archetypes include ecosystem bundlers leveraging television shelf space dominance, premium positioning specialists emphasizing home theater bundling, and mid-tier wireless segment aggressors. Competitive moves concentrate on certification infrastructure investments and specialized audio retail partnership development.
Within the integrated ecosystem tier, Samsung Electronics and LG Electronics occupy positions exemplifying display-audio bundling strategies. Sony Group Corporation anchors the premium acoustic engineering specialist archetype. Bose Corporation represents the dedicated audio pure-play positioning that specialized retailers favor for consultative selling environments. Yamaha Corporation and Panasonic Holdings sit within the diversified electronics conglomerate category with historical home theater category presence.
| Leading Market Players |
|---|
| Bose Corporation |
| VOXX International |
| Samsung Electronics |
| Panasonic Holdings |
| Koninklijke Philips |
| Sony Group Corporation |
| DEI Holdings |
| Yamaha Corporation |
| LG Electronics |
| Others |
Cost & Logistics Intelligence
Acoustic engineering talent concentration in São Paulo's Barra Funda district feeds labor-cost differentials that widen spreads between premium Atmos-enabled units and entry-level optical alternatives. Manufacturers with captive firmware development teams capture margin advantages while outsourcing-dependent competitors absorb certification compliance premiums.
Pricing Analysis
Warranty and installation service bundling separates big-box retail pricing from specialized audio showroom models, with Nuevo León retailers reporting service attach rates above forty percent of hardware transactions. Three-tier pricing structure across premium, standard, and economy levels stratifies by HDMI ARC protocol inclusion and ANATEL certification grade. Cost compression in entry-level Bluetooth segments is intensifying because Asian semiconductor foundry concentration creates lead time volatility. Hospitality procurement teams exhibit lowest price sensitivity due to facility management contract standardization, while residential online shoppers drive aggressive price comparison.
Supply Chain Analysis
Warehouse distribution layers concentrate in São Paulo metropolitan corridors, with hub-and-spoke patterns radiating to Mexico City and Santiago secondary markets. Semiconductor assembly draws from Taiwan, South Korea, and China for wireless chipsets; enclosure manufacturing rests on Brazilian and Mexican plastics molding clusters. Single-source vulnerability in Bluetooth module supply creates bottleneck exposure for Brazilian assembly operations. Distribution runs through regional electronics wholesalers serving specialized audio retailers in Monterrey and Guadalajara.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin American soundbar supply is constrained by ANATEL certification laboratory capacity, with INMETRO-accredited São Paulo facilities propping pricing power for compliant manufacturers.
For Market Incumbents: Hedge against smart speaker substitution by deepening home theater bundling relationships with television OEMs. Secure six-to-eight-week certification advantages through exclusive INMETRO laboratory partnerships in Barra Funda. Capture margin pools via Dolby Atmos height virtualization R&D investments that compress demand for ceiling-mounted speaker alternatives. For New Entrants and Emerging Players: Launch via direct sales channels targeting Monterrey and Guadalajara hospitality procurement teams seeking standardized property-wide deployments. Exploit Chilean SUBTEL streamlined filing for Wi-Fi 6E-enabled variants entering Santiago's Las Condes luxury condominium segment. White-space sits with multi-room audio convergence for affluent Rio de Janeiro Zona Sul households. For Investors and Strategic Acquirers: Re-rating potential sits with acoustic engineering specialists given Dolby Atmos virtualization adoption acceleration across Brazilian luxury residential. Long-term viability favors manufacturers with backward integration into DSP firmware development and established regional certification infrastructure. Monitor IFETEL 5GHz spectrum harmonization resolution as inflection indicator for Mexican market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| ANATEL Certification Partnership | INMETRO-accredited São Paulo laboratory relationships compress product validation timelines against new entrants. |
| Multi-Room Audio Platform Launch | Whole-home synchronization integration targets affluent Rio de Janeiro Zona Sul condominium specifications. |
| Specialized Retail Channel Expansion | Dedicated home theater showroom presence in Nuevo León captures forty-percent service attach rates. |
| Dolby Atmos Virtualization R&D | Height channel synthesis technology displaces legacy ceiling-mounted speaker installation demand. |
| Direct Hospitality Procurement Contracts | Facility management relationships in Mexico City and Guadalajara bypass retail margin capture. |
Research Approach
Multi-period observation of streaming platform penetration rates, certification timeline durations, and retail channel inventory turns anchored the trend analysis, supplemented by interviews with audio product procurement managers at Brazilian big-box chains, acoustic engineering directors at São Paulo assembly operations, hospitality facility management contractors in Mexico City, and specialized home theater retailers in Monterrey. Secondary validation drew from ANATEL regulatory filings, IFETEL spectrum allocation notices, SUBTEL electromagnetic compatibility databases, and customs import records for wireless audio components. Bottom-up SKU-level volume builds triangulated against top-down category spending estimates derived from metropolitan household electronics expenditure surveys.
Input-output matrices modeled connectivity protocol adoption curves, certification cost pass-through coefficients, and regional price elasticity differentials across the projection horizon. Segmentation dimensions included form factor architecture, end-user procurement authority structure, technology protocol selection, and distribution channel service bundling intensity. CAGRs were derived from logistic diffusion curves fitted to wireless audio replacement cycle compression patterns and streaming subscriber growth trajectories. Forecast inputs incorporated ANATEL Resolution 2420 compliance cost assumptions and IFETEL 5GHz harmonization scenario probabilities.
Regulatory enforcement intensity shifts, semiconductor foundry allocation disruptions, and smart speaker substitution acceleration are the dominant revision risks that could compress or extend projected adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Radio and Audio Media
Audio Mixing Console Market
Radio and Audio Media
Podcast Advertising Market
Radio and Audio Media
Podcast Market
Radio and Audio Media
Podcasting Market
Radio and Audio Media
Traditional Radio Advertising Market
Radio and Audio Media
Digital Audio Market
Radio and Audio Media
Voice Over New Radio Market
Radio and Audio Media
Podcast Hosting Services Market
Radio and Audio Media
Global Professional Audio Market
Radio and Audio Media
Microphone Market
Radio and Audio Media
Global 3D Audio Market
Radio and Audio Media
FM Transmitters Market
Radio and Audio Media
Audiobooks Market
Radio and Audio Media
Internet Radio Market
Radio and Audio Media
Radio Advertising Market