
 Traditional Radio Advertising Market | 2026-2036
Traditional Radio Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Traditional Radio Advertising Market Intelligence
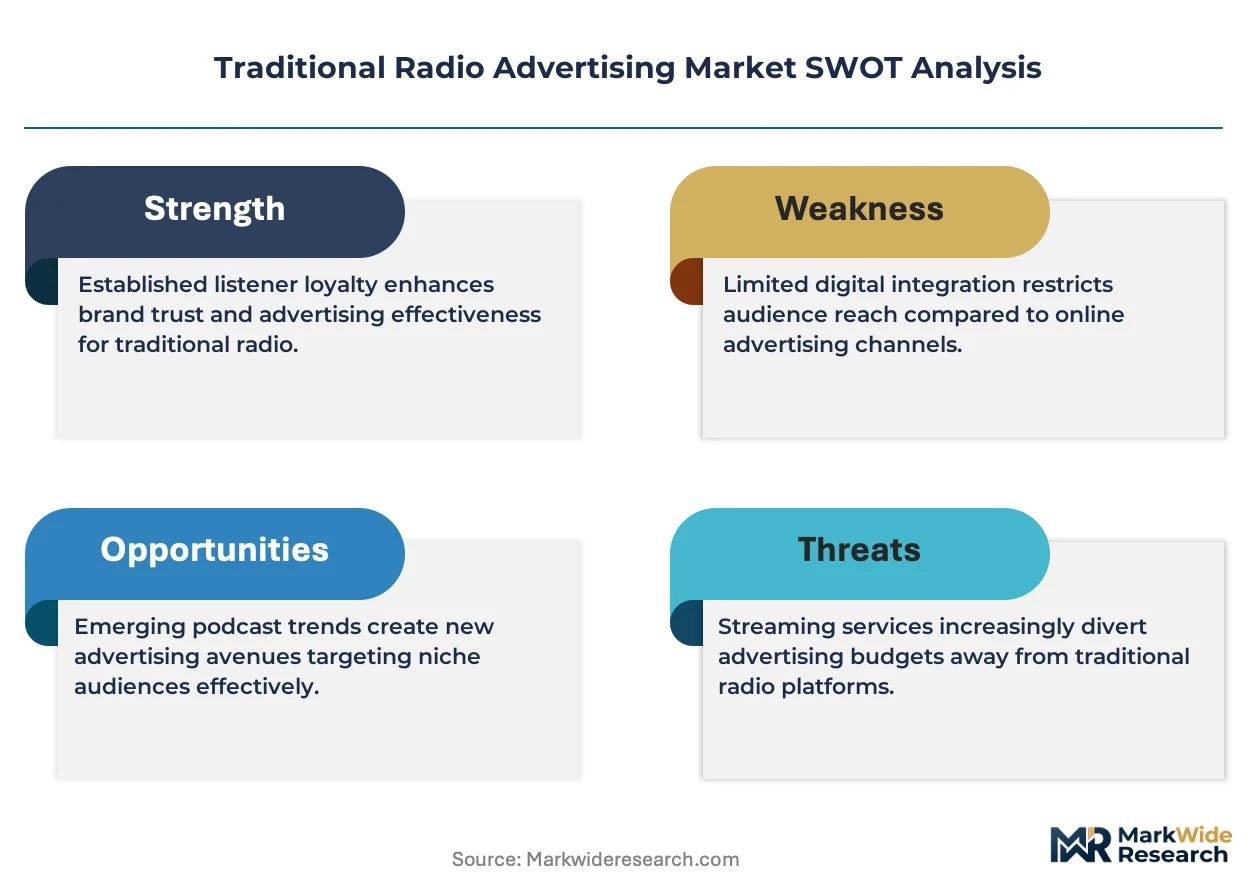
Digital audio metrics are broadening the economic calculus for traditional radio campaigns as programmatic verification tools replace legacy audience-estimation methods. iHeartMedia leverages its national network scale to bundle terrestrial inventory with digital extensions. Audacy competes through hyper-local sports and news franchises in top-ten media markets. Cumulus Media anchors its position in mid-market regions where AM talk formats sustain premium spot rates.
Traditional radio advertising comprises audio commercials delivered via AM, FM, satellite, or internet-streamed broadcasts, typically produced as live reads, recorded spots, jingles, or sponsored programming segments ranging from fifteen to sixty seconds in duration. The medium serves commercial purposes by delivering geographic and demographic targeting to advertisers seeking reach during commuter hours, live events, and local weather or traffic updates. Live Ads command the deepest margin pools among ad formats due to host-read authenticity and limited inventory scalability. Small Businesses represent the most resilient client type during economic softness, as spot buyers retreat to proven local channels rather than experiment with untested digital platforms.
The FCC governs station ownership limits and indecency standards that directly constrain inventory supply and pricing power in the United States. The FTC's truth-in-advertising enforcement and ASCAP/BMI royalty frameworks shape creative production costs and liability exposure for broadcasters and agencies alike. Stakeholders must monitor how streaming measurement standards from the Audio Advertising Bureau migrate into terrestrial verification protocols, as this transition will determine which broadcasters retain rate-card authority and which surrender pricing power to platform intermediaries.
Market Dynamics
Programmatic audio verification tools are compressing the measurement gap between terrestrial broadcasts and digital streams, forcing broadcasters to reprice inventory around verified listenership rather than legacy diary estimates.
Growth Catalysts
- Automotive dealership clusters:Drive-time advertising retains pricing power in suburban corridors where vehicle purchase cycles align with commuter patterns.
- FCC local ownership caps:Regulatory limits on station consolidation preserve independent inventory pools that sustain spot-rate premiums in mid-sized markets.
- Live read formats:Host-authenticated advertisements command scarcity premiums that recorded spots cannot replicate, anchoring margin pools for broadcasters with recognizable talent.
Market Restraints
- Digital audio substitution:Streaming platforms and podcast networks capture younger demographic cohorts that terrestrial formats struggle to retain.
- ASCAP/BMI royalty escalations:Performing rights organization rate negotiations inflate content acquisition costs for music-intensive formats.
- Signal infrastructure depreciation:AM transmission equipment requires capital renewal that station groups defer, degrading coverage reach in rural zones.
Strategic Opportunities
- Hyper-local weather and traffic integration:Sponsored information segments offer advertisers embedded presence in high-attention moments that pre-recorded digital audio cannot intercept.
- FTC truth-in-advertising clarity:Regulatory guidance on native advertising disclosure creates compliant frameworks for branded content that blends editorial and commercial voice.
- Sports betting legalization waves:Newly regulated wagering markets generate fresh advertiser demand for live event adjacencies and real-time odds integration.
Industry Challenges
- Audience measurement talent scarcity:Broadcasters struggle to recruit analysts fluent in both legacy Arbitron methodologies and emerging digital attribution protocols.
- Legacy automation integration:Traffic and billing systems built for spot-based workflows resist seamless incorporation of programmatic insertion orders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Traditional Radio Advertising Market |
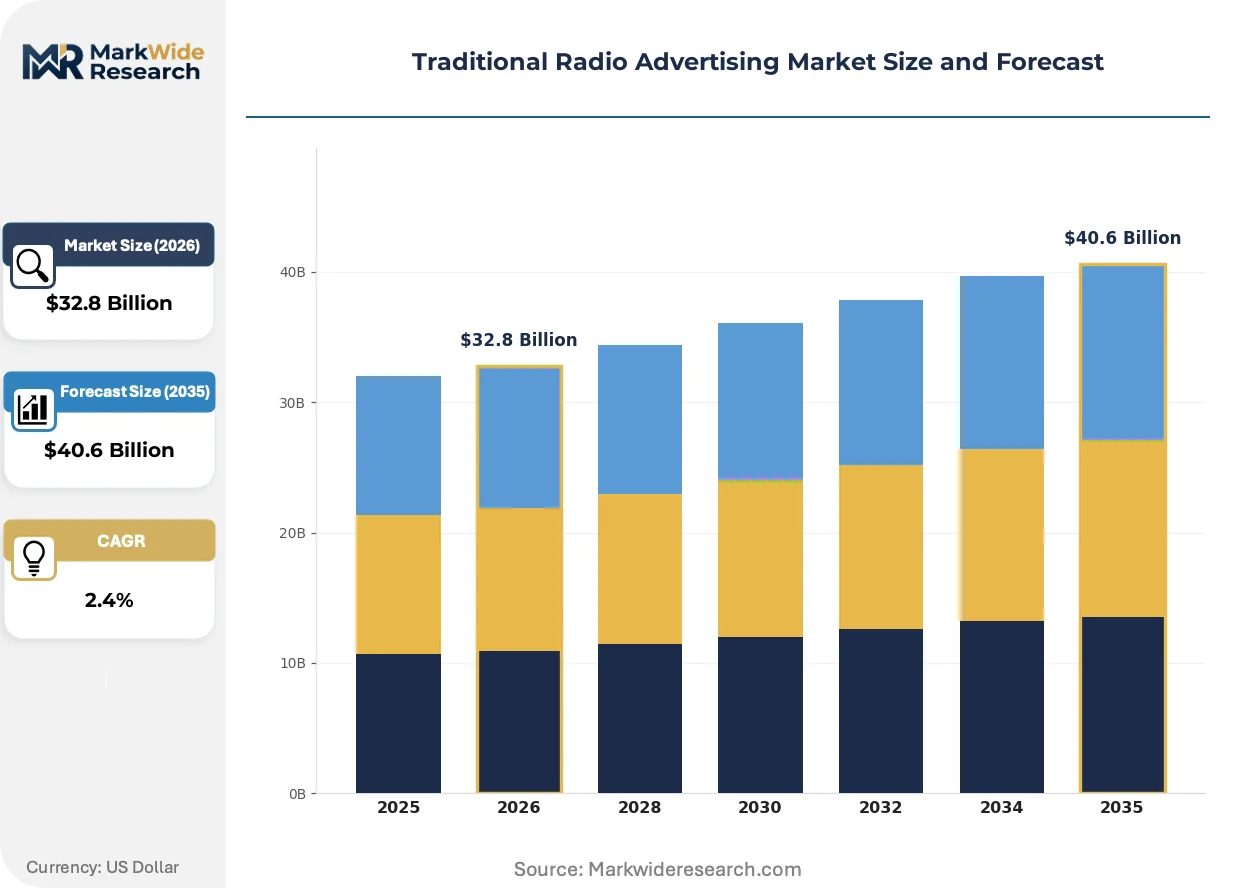
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $40.6 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ad Format: Live Ads, Recorded Spots, Jingles, Sponsorships Client Type: Small Businesses, National Brands, Non-profits, Local Agencies Broadcast Method: AM Transmission, FM Transmission, Internet Streaming, Satellite Radio Content Type: News, Talk Shows, Music, Weather Reports |
| Companies Covered | iHeartMedia, Cumulus Media, Audacy, Sirius XM Holdings, Townsquare Media, Bauer Media Group, Cox Media Group, Salem Media Group, Beasley Broadcast Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Traditional Radio Advertising Market Strategic Shifts & Innovations
Audio advertising is bifurcating into precision-targeted digital streams and high-attention terrestrial moments, with technology investments determining which broadcasters capture pricing authority in each channel.
Dynamic ad insertion technology is electrifying broadcast workflows by enabling real-time creative swaps based on listener location, weather conditions, or inventory availability. Automotive advertisers in drive-time slots adopt these capabilities fastest, replacing static dealership spots with inventory-triggered messages. The technology is electrifying rate-card structures by collapsing the premium gap between live reads and automated placements.
The FTC's evolving native advertising enforcement posture is reshaping how broadcasters structure host-read sponsorships to maintain editorial credibility while satisfying disclosure mandates. Stations now embed standardized verbal acknowledgments that satisfy regulatory scrutiny without disrupting listener engagement. Talk and sports formats face the steepest compliance recalibration as their commercial content most closely resembles programming.
Small business advertisers are consolidating spot purchases around proven local channels rather than experimenting with untested digital platforms during economic softness. This behavioral rotation benefits established AM news and FM country stations with deep advertiser relationships in their designated market areas. The pattern concentrates demand in United States markets where terrestrial broadcast infrastructure retains the deepest small-business trust.
Traditional Radio Advertising Market Segmentation
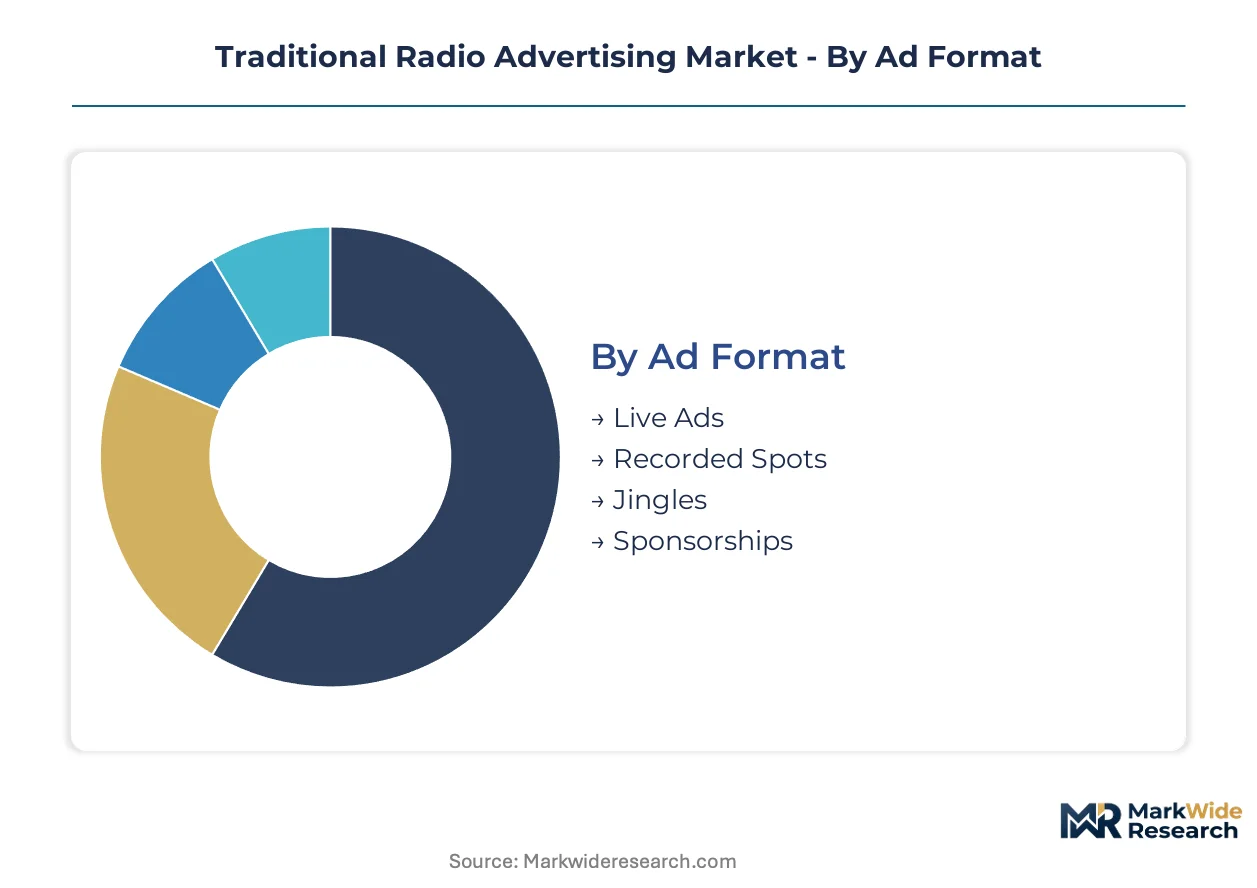
Radio advertising inventory fragments across technical delivery modes, creative formats, and buyer sophistication levels. Broadcasters must align rate-card structures with how each segment values reach, frequency, and geographic precision.
Ad Format:
Creative production investment determines pricing tier and margin capture for inventory holders.
- Live Ads:Host-delivered endorsements carry authenticity premiums that recorded spots cannot replicate. Automotive dealerships in suburban United States corridors concentrate demand here, paying scarcity premiums for talent with proven commuter-hour audiences.
- Recorded Spots:Pre-produced commercials enable rapid creative rotation and regional versioning at lower unit cost. National brands with seasonal campaign calendars drive volume, prioritizing reach efficiency over host association.
- Jingles:Musical brand signatures deliver memorability through sonic repetition. Local agencies serving retail and service clients favor these for sustained top-of-mind presence.
- Sponsorships:Embedded programming partnerships blend commercial and editorial voice. Non-profits leverage these for cause-aligned visibility during community-focused segments.
Volume sits with Recorded Spots; growth tilts toward Live Ads.
Client Type:
Organizational scale shapes contract duration, payment terms, and sensitivity to rate fluctuations.
- Small Businesses:Spot buyers with localized trading areas prioritize proven channels over experimental digital platforms. United States mid-market regions sustain resilient demand here during economic softness.
- National Brands:Centralized procurement seeks network-scale bundles across multiple designated market areas. These buyers command volume discounts that compress per-spot yields.
- Non-profits:Mission-driven organizations value donated or discounted inventory for public service messaging. FCC public interest obligations incentivize station compliance.
- Local Agencies:Media buying intermediaries aggregate fragmented advertiser demand. Their commission structures influence rate negotiation intensity in competitive markets.
Revenue concentrates with National Brands; expansion tilts toward Small Businesses.
Broadcast Method:
Signal infrastructure maturity and audience measurement reliability govern advertiser confidence.
- FM Transmission:Superior audio fidelity and established Arbitron measurement protocols anchor premium pricing. Music-intensive formats in United States urban centers concentrate demand here.
- AM Transmission:Extended reach and lower production costs sustain talk and news formats. Rural coverage degradation from deferred capital renewal constrains pricing power.
- Internet Streaming:Digital delivery enables geographic and behavioral targeting with programmatic verification. Younger demographic cohorts are expanding most quickly in this channel.
- Satellite Radio:Subscription-funded models limit advertising inventory, creating scarcity value for national reach. Automotive OEM pre-installation agreements lock in audience access.
Spend concentrates with FM Transmission; adoption climbs fastest in Internet Streaming.
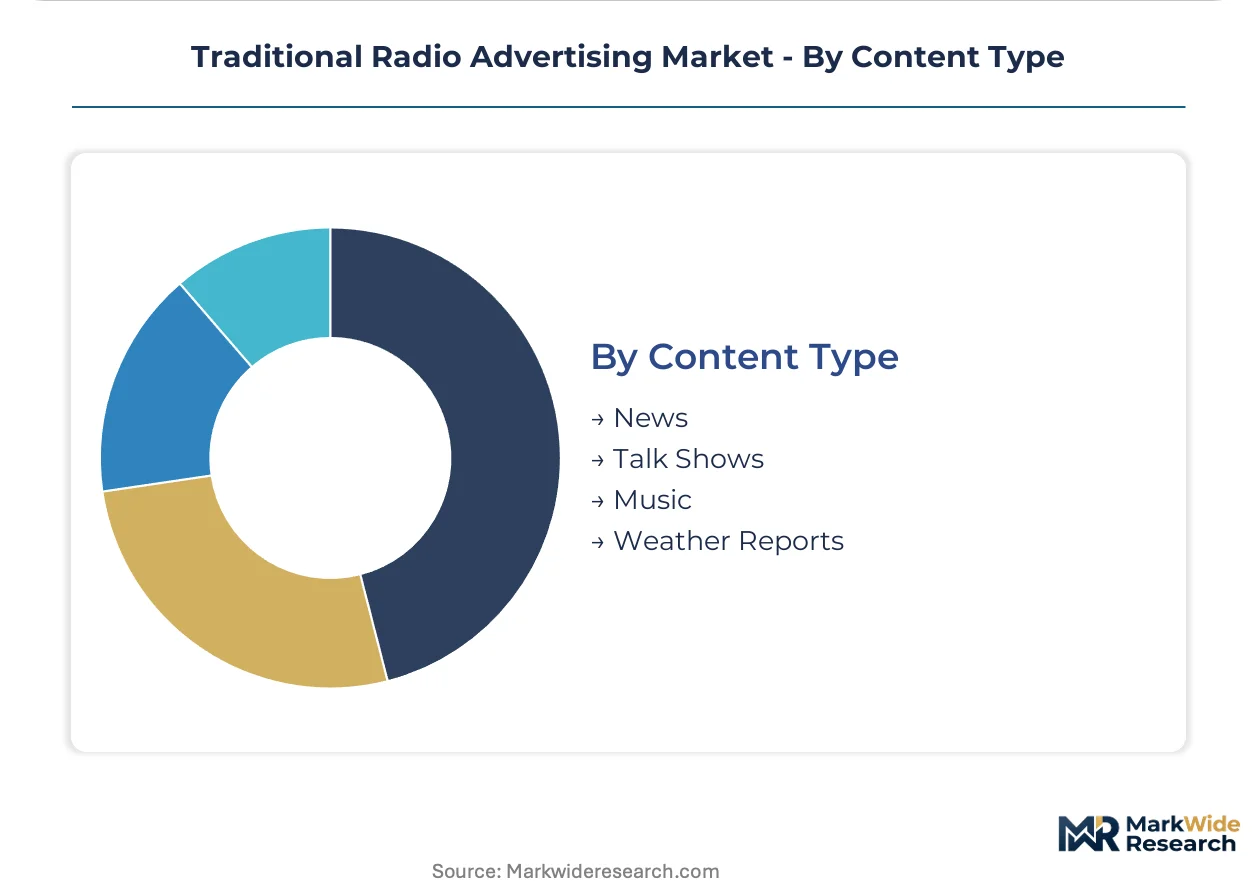
Content Type:
Listener attention intensity during specific programming windows determines spot rate premiums.
- News:High-attention morning and evening drive-time slots command rate-card peaks. Local advertisers in United States markets pay premiums for adjacency to weather and traffic updates.
- Talk Shows:Host-audience relationship depth enables native advertising integration with disclosure compliance. FTC truth-in-advertising enforcement shapes creative boundaries here.
- Music:Format diversity across genres enables demographic targeting at scale. ASCAP and BMI royalty escalations inflate content acquisition costs for station groups.
- Weather Reports:Sponsored information segments intercept high-intent moments with embedded brand presence. Insurance and home services advertisers concentrate demand here.
Rate premiums peak in News; inventory growth tilts toward Talk Shows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advertiser demand concentrates in the United States, where terrestrial broadcast infrastructure retains the deepest relationships with automotive dealerships and small businesses purchasing drive-time inventory.
United States
Automotive dealership clusters in suburban corridors sustain premium spot rates for drive-time advertising. The FCC's local ownership caps preserve independent inventory pools that support pricing power in mid-sized markets. Dallas-Fort Worth and Atlanta metropolitan areas anchor concentration for AM talk and FM country formats with proven commuter-hour audiences.
Germany
Bauer Media Group leverages national network scale to bundle terrestrial inventory across regional stations. The country's media regulator enforces concentration limits that shape competitive dynamics among broadcasters. Munich and Hamburg media clusters concentrate demand for automotive and retail advertising during rush-hour programming windows.
United Kingdom
Commercial broadcasters compete through hyper-local news and sports franchises in designated market areas. Ofcom ownership rules constrain station consolidation patterns that would otherwise compress inventory premiums. London and Manchester metropolitan areas sustain the deepest advertiser relationships for drive-time spot purchases.
Canada
Mid-market regions sustain resilient demand from small businesses retreating to proven local channels during economic softness. The CRTC's commercial radio policy frameworks govern licensing and content requirements that shape inventory supply. Toronto and Vancouver broadcast clusters anchor premium pricing for FM music and talk formats.
Australia
Southern Cross Austereo and ARN Media compete through metropolitan network scale and regional station portfolios. ACMA licensing frameworks govern spectrum allocation and ownership limits that preserve competitive inventory pools. Sydney and Melbourne media markets concentrate advertiser demand for live read formats and sponsored information segments.
Traditional Radio Advertising Market Key Industry Players
Network consolidation dominates the current landscape as broadcasters seek scale economies to offset digital audio substitution. The vendor base structures around three tiers: national network operators with multi-format portfolios, regional specialists anchoring mid-market positions, and format-focused players in niche segments. Strategic archetypes include scale-driven bundlers, hyper-local franchise builders, and AM talk format specialists. M&A activity and programmatic technology licensing represent the dominant competitive moves reshaping rate-card authority.
Within the national network tier, iHeartMedia and Cumulus Media exemplify scale-driven operators leveraging terrestrial inventory bundling with digital extensions. Audacy occupies a position emphasizing hyper-local sports and news franchises in top-ten media markets. These three entities represent contrasting strategic postures: iHeartMedia anchors national reach, Cumulus Media concentrates mid-market regional depth, and Audacy prioritizes metropolitan market density.
| Leading Market Players |
|---|
| iHeartMedia |
| Cumulus Media |
| Audacy |
| Sirius XM Holdings |
| Townsquare Media |
| Bauer Media Group |
| Cox Media Group |
| Salem Media Group |
| Beasley Broadcast Group |
| Others |
Cost & Logistics Intelligence
Talent scarcity among broadcast engineers in the United States Midwest widens pricing-tier spreads, as stations with certified technical staff command live-read premiums while understaffed outlets discount recorded spots to retain automotive dealership accounts.
Pricing Analysis
Volume concentrates with recorded spots while margins pool in live ads. Three-tier pricing structure across premium, standard, and economy levels separates host-authenticated endorsements from automated placements and remnant inventory. Price differentiation rests on talent recognition and programmatic verification status. Cost compression in economy tiers is intensifying because digital audio platforms capture rate-card authority through verified attribution. Small businesses exhibit highest price sensitivity; national brands with network bundles show lowest.
Supply Chain Analysis
Dual-sourcing requirements from automotive advertisers mandate broadcasters maintain relationships with both ASCAP and BMI for music licensing coverage. Content acquisition draws from United States, United Kingdom, and Germany for format syndication and talent development. Raw material dependencies span transmission equipment, studio hardware, and royalty-bearing music catalogs. Single-source vulnerability concentrates in performing rights organization rate negotiations. Distribution runs through direct station sales teams, programmatic platforms, and media buying agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race as broadcasters pursue in-house programmatic technology stacks to reclaim rate-card authority from platform intermediaries.
For Market Incumbents: Lock in exclusive talent contracts for drive-time hosts before digital platforms expand live-read capabilities. Acquire regional station clusters in FCC-protected mid-markets to consolidate inventory pricing power against streaming substitution. Prioritize backward integration into dynamic ad insertion technology to automate premium inventory without surrendering margin to vendors.
For New Entrants and Emerging Players: The gap between premium live-read rates and economy remnant pricing creates white-space entry for podcast networks offering host-authenticated inventory at mid-tier positioning. Target hyper-local weather and traffic sponsorships in suburban United States corridors where terrestrial signals retain advertiser trust. Deploy direct-to-advertiser sales models bypassing legacy agency commission structures.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-market station groups given FCC ownership cap relaxation catalysts. Long-term viability favors broadcasters with proven commuter-hour audiences and sports betting advertising adjacencies. Watch for Audio Advertising Bureau measurement standard adoption as inflection indicator separating rate-card winners from pricing-power losers.
| Strategic Initiative | Industry Significance |
|---|---|
| Dynamic Ad Insertion Deployment | Enables real-time creative swaps for automotive advertisers during drive-time inventory windows. |
| Performing Rights Organization Rate Negotiation | Direct ASCAP and BMI agreements reduce content acquisition cost inflation for music formats. |
| Programmatic Technology Licensing | Third-party verification tools restore advertiser confidence in terrestrial audience metrics. |
| Hyper-Local Sports Franchise Acquisition | Live event adjacencies capture sports betting advertiser demand in newly regulated wagering markets. |
| Host Talent Contract Extension | Exclusive live-read agreements protect scarcity premiums that automated placements cannot replicate. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with station general managers, media buying agency executives, automotive dealership marketing directors, and FCC regulatory affairs specialists combined with secondary validation from Arbitron audience measurement databases, ASCAP and BMI royalty filings, and SEC broadcaster disclosures. Bottom-up station-level revenue modeling and top-down network-scale aggregation enabled triangulation across the analysis window.
Data-stream reconciliation across the projection horizon integrated ad format segmentation, client type tiers, broadcast method channels, and content type programming windows. CAGRs were derived from historical trajectory analysis and forward-looking demand elasticity assumptions. Forecast inputs incorporated FCC ownership cap policy scenarios and Audio Advertising Bureau measurement standard migration timelines.
Inputs from trade associations and regulatory bodies were available through the study window; gaps in programmatic verification adoption rates introduce uncertainty bands around digital substitution assumptions. Forecasts reflect documented assumptions about commuter pattern stability and automotive advertising cycle alignment. Deviation in sports betting legalization velocity or FCC local ownership cap modification would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Radio and Audio Media
Voice Over New Radio Market
Radio and Audio Media
Podcast Hosting Services Market
Radio and Audio Media
FM Transmitters Market
Radio and Audio Media
Microphone Market
Radio and Audio Media
Global Professional Audio Market
Radio and Audio Media
Podcast Market
Radio and Audio Media
Radio Advertising Market
Radio and Audio Media
Internet Radio Market
Radio and Audio Media
Podcasting Market
Radio and Audio Media
Digital Audio Market
Radio and Audio Media
Global 3D Audio Market
Radio and Audio Media
Audio Mixing Console Market
Radio and Audio Media
Audiobooks Market
Radio and Audio Media
Podcast Advertising Market
Radio and Audio Media
Latin America Soundbar Market