
 Podcast Advertising Market | 2026-2036
Podcast Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Podcast Advertising Market Outlook
Buyer concentration among direct-to-consumer brands is hardening as these advertisers shift larger portions of customer acquisition budgets into podcast channels. Spotify leverages its proprietary streaming data to target listeners across music and podcast surfaces. iHeartMedia anchors national scale through its broadcast-to-podcast syndication network. Acast competes on open-platform monetization tools for independent creators.
Podcast advertising denotes audio promotional content inserted into episodic digital audio programs, typically delivered through RSS feeds or proprietary streaming protocols with dynamically inserted ad slots that enable impression-level targeting and attribution. Its commercial purpose centers on capturing engaged, niche audiences during lean-back listening moments that resist visual ad blocking. Host-read formats command premium rates due to trust transfer from personality to product, while programmatic channels are expanding fastest as automated buying reduces friction for mid-market advertisers. Pre-roll inventory remains the most standardized and liquid segment, though mid-roll placements capture deeper listener attention during episode peaks.
The Federal Trade Commission enforces endorsement disclosure rules that govern host-read sponsorships, while the Federal Communications Commission maintains oversight of broadcast-origin content that syndicates into podcast feeds. The EU Digital Services Act introduces algorithmic transparency obligations for platform-distributed audio ads, affecting how Spotify and Apple Podcasts surface promoted content. Stakeholders must monitor evolving privacy regulations around device-level identifiers, as the deprecation of mobile ad IDs threatens the measurement infrastructure that justifies podcast premium pricing.
Market Dynamics
Programmatic buying infrastructure is compressing transaction friction between podcast publishers and mid-market advertisers, while host-read formats retain pricing power through trust transfer mechanics that automated placements cannot replicate.
Growth Catalysts
- Direct-to-consumer reallocation:Subscription box brands and wellness retailers are redirecting customer acquisition spend from saturated social channels into podcast host-read inventory. These advertisers value the lean-back attention environment that resists visual ad blocking.
- Dynamic ad insertion technology:Server-side ad stitching enables impression-level targeting based on listener device, geography, and contextual episode metadata. Publishers monetize back catalogs without re-recording host segments.
- EU Digital Services Act:Algorithmic transparency obligations for platform-distributed audio ads are forcing Spotify and Apple Podcasts to disclose ranking factors for promoted content. This regulatory pressure paradoxically validates podcast advertising as a mature medium worthy of oversight.
Market Restraints
- Mobile ad ID deprecation:Apple's App Tracking Transparency and Google's Privacy Sandbox phaseout threaten device-level attribution that justifies premium podcast CPMs. Advertisers face measurement gaps between impression and conversion.
- Supply concentration in English-language inventory:Monetizable podcast content clusters disproportionately in US, UK, and Australian creator ecosystems. Advertisers seeking non-English audiences encounter limited scalable inventory.
- Host dependency risk:Premium pricing for personality-driven sponsorships creates concentration exposure when talent exits or controversies erupt. Brands cannot easily transfer creative equity to replacement hosts.
Strategic Opportunities
- Latin American market penetration:Brazil and Mexico exhibit podcast consumption growth without proportional advertising infrastructure development. Early entrants capture undervalued inventory before local CPMs adjust to demand.
- Brand safety automation:AI-powered content classification tools enable pre-flight screening of episode transcripts for advertiser suitability. This technology convergence reduces manual review bottlenecks that slow campaign activation.
- Connected TV audio extension:Smart television platforms are integrating podcast apps that surface audio content through living room speakers. This channel innovation captures co-listening moments that pure mobile consumption misses.
Industry Challenges
- Attribution engineering talent scarcity:Publishers and agencies compete for data scientists capable of building incrementality models that satisfy finance departments skeptical of last-click measurement. Compensation inflation in this function squeezes mid-tier operator margins.
- Cross-platform frequency capping:Listeners consume podcasts across multiple apps and devices without unified identity graphs. Advertisers risk oversaturation that degrades brand perception without technical solutions to coordinate exposure caps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Podcast Advertising Market |
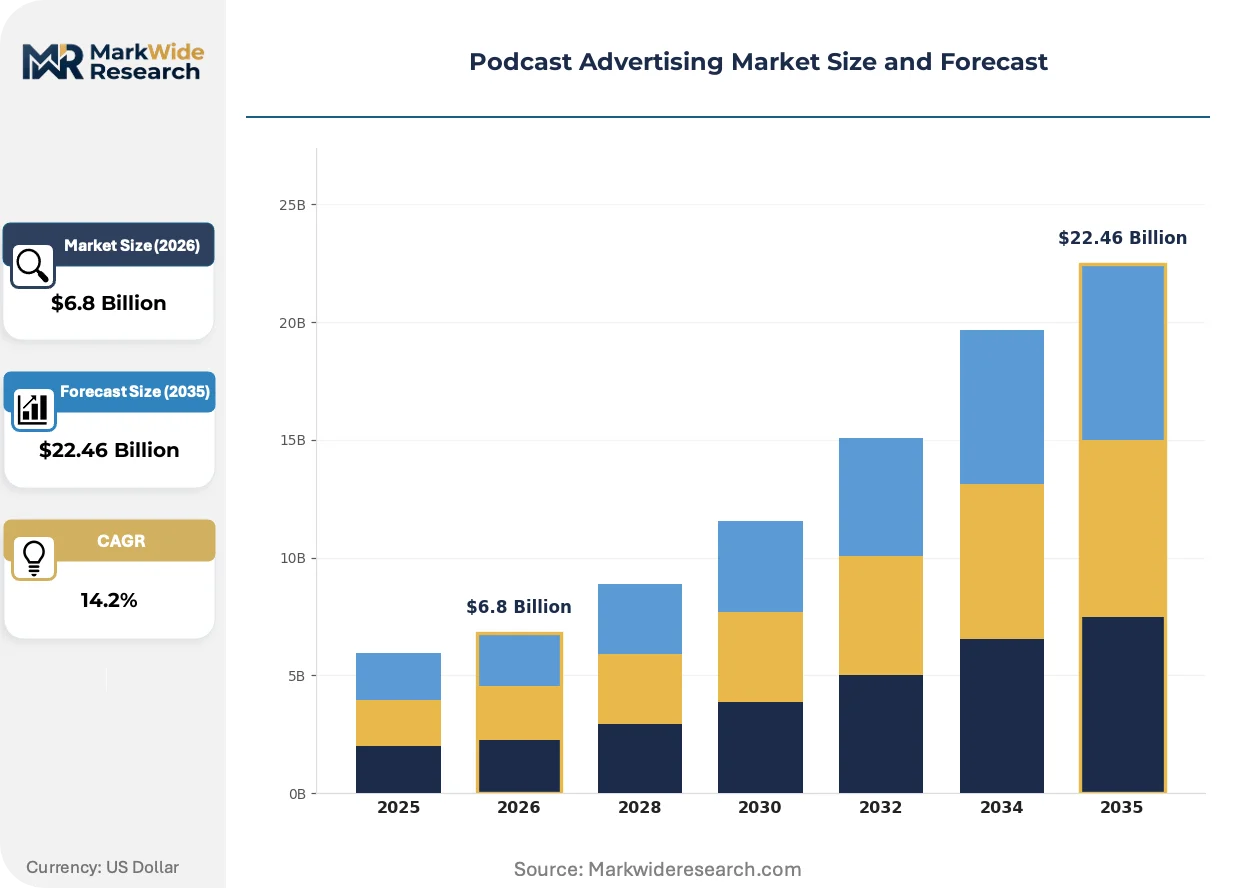
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ad Format: Host-Read, Pre-Roll, Mid-Roll, Post-Roll Advertiser Type: Brands, Agencies, Affiliates, Non-Profits Listener Demographics: Age Group, Gender, Income Level, Education Distribution Channel: Direct Purchase, Programmatic, Sponsorship, Network |
| Companies Covered | Spotify, Apple Podcasts, iHeartMedia, Acast, SiriusXM Media, Podbean, Audioboom, Wondery, AdsWizz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Podcast Advertising Market Strategic Shifts
Voice cloning and synthetic media tools are disrupting the economics of host-read advertising, while regulatory frameworks in multiple jurisdictions force platform transparency that reshapes competitive positioning between open RSS and walled-garden distribution.
Generative voice synthesis is absorbing production workflows for mid-market advertisers who previously could not afford personality talent. Direct-to-consumer brands in supplements and financial services are adopting synthetic host-reads for performance testing before committing to premium human talent. This technology is absorbing budget that would have flowed to smaller independent creators, compressing their monetization options.
The EU Digital Services Act mandates algorithmic transparency for content recommendation systems that surface promoted audio. Platforms must disclose ranking parameters and provide ad archive access, increasing compliance overhead. European podcast listeners encounter more explicit labeling of sponsored content, while publishers adapt creative formats to satisfy disclosure requirements without disrupting narrative flow.
Buyer concentration among direct-to-consumer brands is reshaping sales organization structures at podcast networks. Account teams now embed directly within advertiser marketing departments, co-developing creative concepts rather than transacting pre-produced inventory. This behavior shift is most visible in US coastal media markets where venture-backed consumer brands cluster and demand bespoke measurement frameworks.
Podcast Advertising Market Segmentation
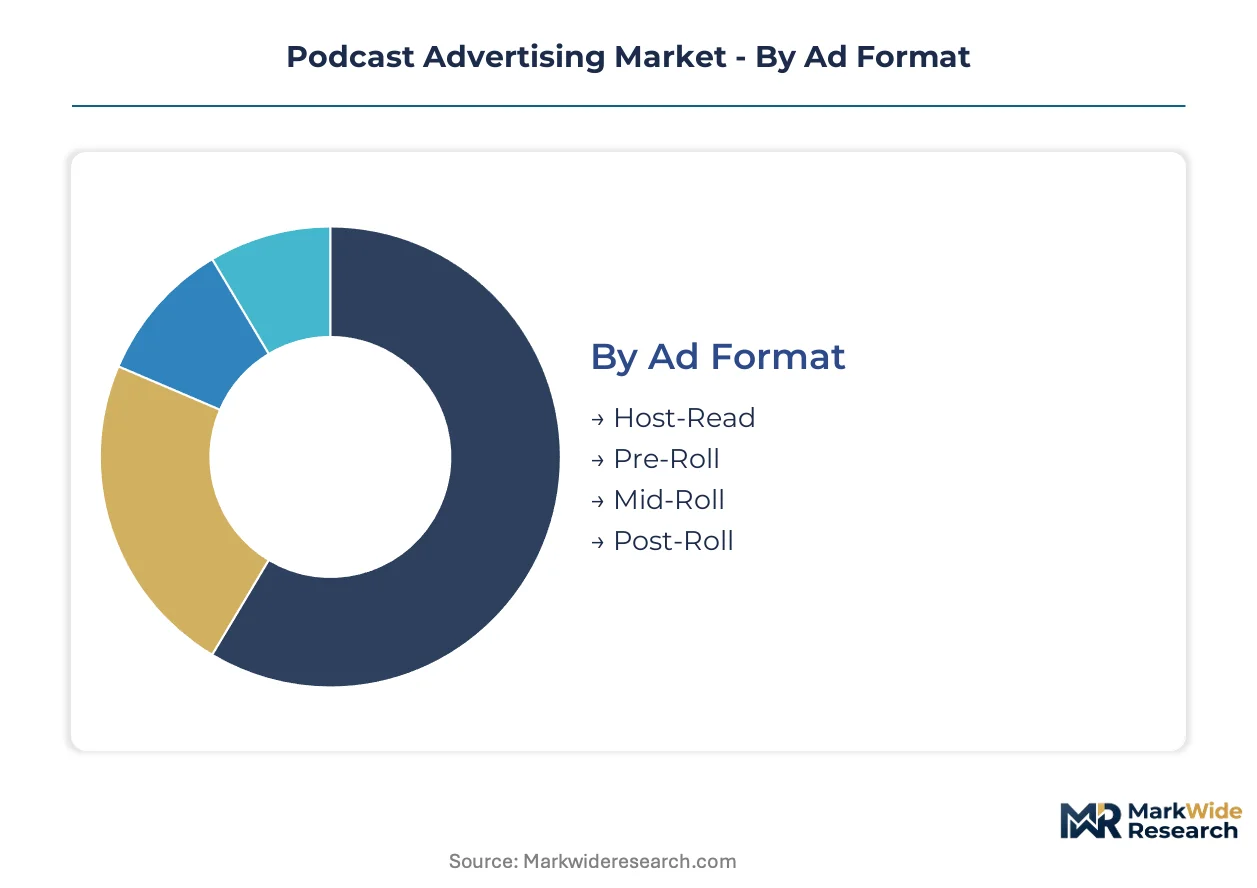
Podcast advertising segments diverge sharply by technical execution and buyer sophistication. Format mechanics determine attribution capabilities, while distribution infrastructure separates premium inventory from commoditized placements. Advertiser type and listener targeting layers further stratify pricing power across the ecosystem.
Ad Format:
Technical execution defines listener attention capture and creative flexibility across insertion points.
- Host-Read:Personality-delivered endorsements recorded during episode production or stitched dynamically. Direct-to-consumer wellness brands concentrate spend here, trusting trust-transfer mechanics that automated placements cannot replicate. FTC disclosure rules govern script transparency.
- Mid-Roll:Insertions during episode narrative peaks command deeper attention than peripheral slots. Supply constraints from limited commercial minutes per episode sustain premium rate cards. Brand safety screening bottlenecks slow campaign activation.
- Pre-Roll:Standardized 15-30 second slots before content start represent the most liquid inventory segment. Programmatic pipes flow primarily through this format. Mid-market advertisers lacking creative resources default here.
- Post-Roll:Final-position placements capture remnant attention with lower completion rates. Conversion-focused direct response advertisers tolerate attenuated engagement for discounted CPMs.
Host-Read leads on scale; Mid-Roll leads on momentum.
Advertiser Type:
Procurement sophistication separates buyers by creative control requirements and measurement rigor.
- Brands:Corporate advertisers with established audio budgets demand bespoke attribution frameworks and brand safety verification. Finance departments require incrementality modeling beyond last-click metrics. Talent scarcity in podcast data science inflates agency fees.
- Agencies:Media buying intermediaries aggregate demand across multiple advertisers, extracting volume discounts from networks. Trading desk infrastructure enables cross-platform frequency management that individual brands cannot execute.
- Affiliates:Performance marketers track code-based conversions with strict return-on-ad-spend thresholds. Host-read inventory suits their accountability requirements. Payment structures concentrate risk on publishers.
- Non-Profits:Cause-driven organizations prioritize audience alignment over reach efficiency. Mission resonance with podcast genres drives placement decisions. Donor acquisition economics tolerate higher cost-per-donation benchmarks.
Agencies dominate transaction volume; Brands drive pricing expansion.
Listener Demographics:
Targeting granularity determines inventory scarcity and rate differentiation.
- Age Group:Cohort-based segmentation enables life-stage relevant messaging. Advertisers in financial services and education concentrate on 25-44 year segments with established purchasing power.
- Gender:Demographic splits matter for categories with skewed consumption patterns. Beauty and gaming advertisers pay premiums for gender-concentrated shows.
- Income Level:High-earner targeting commands CPM multiples through IP-based geolocation and content genre proxies. Luxury and investment product categories concentrate here.
- Education:Attainment-level segmentation suits professional development and higher education advertisers. Podcast genres cluster by educational profile, enabling efficient audience assembly.
Income Level captures premium pricing; Age Group anchors volume.
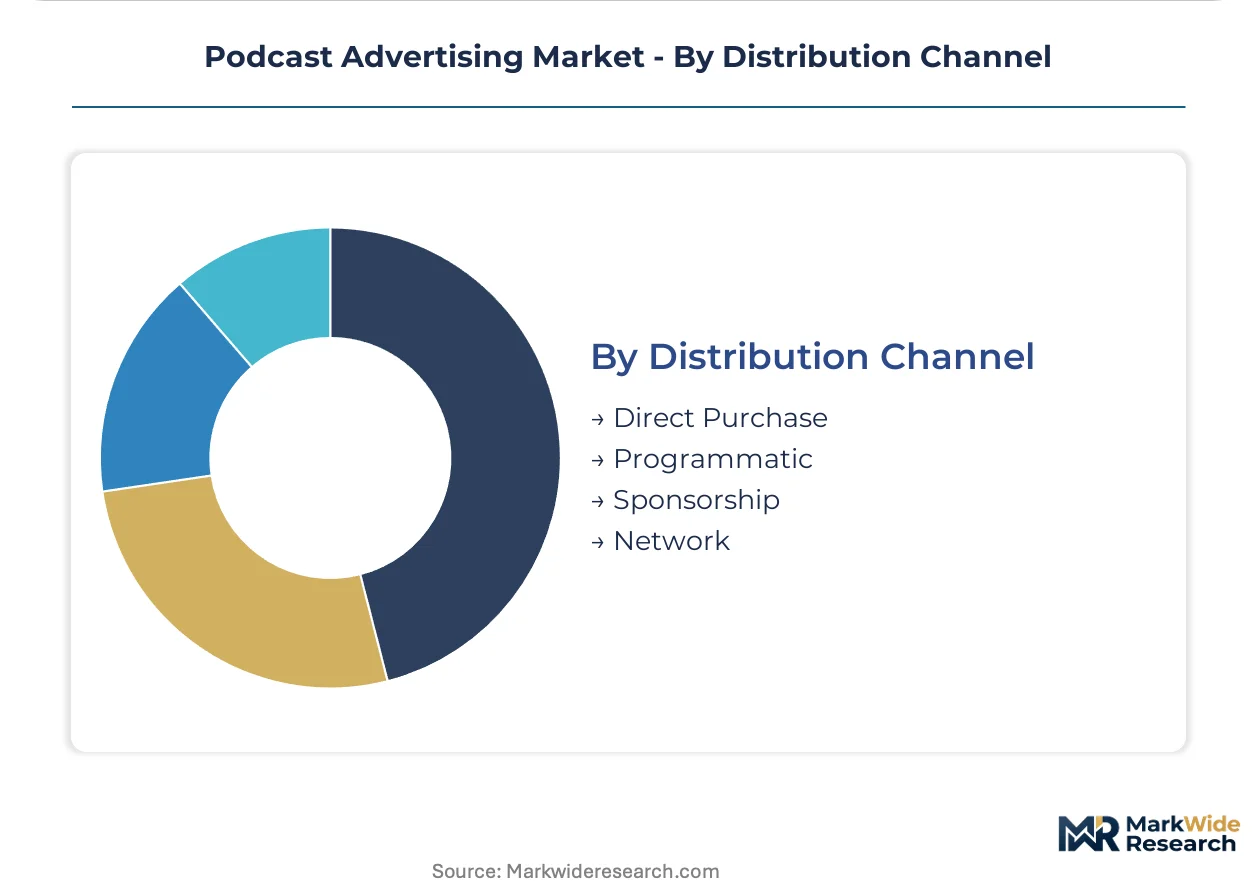
Distribution Channel:
Transaction mechanics separate premium relationship selling from automated efficiency.
- Direct Purchase:Publisher-advertiser relationships enable custom creative development and exclusive inventory holds. Top-tier podcast networks staff embedded account teams for major brand partnerships.
- Programmatic:Automated buying infrastructure compresses transaction friction for mid-market advertisers. Real-time bidding pipes expand fastest as measurement standardization improves.
- Sponsorship:Long-term show partnerships integrate brands into content architecture. Full-season commitments provide revenue predictability for independent creators.
- Network:Aggregator models pool inventory across multiple shows for scale buying. Representation agreements concentrate negotiating leverage for smaller publishers.
Network aggregation leads on reach; Programmatic infrastructure expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands premium CPMs through mature programmatic infrastructure, while Brazil captures undervalued inventory before local rate adjustments. Germany and the United Kingdom anchor European monetization through strict regulatory compliance frameworks. Australia rounds out developed-market concentration with English-language content advantages.
United States
Venture-backed direct-to-consumer brands cluster in coastal media markets, embedding account teams within advertiser marketing departments. The Federal Trade Commission enforces endorsement disclosure rules governing host-read sponsorships. New York and Los Angeles anchor national-scale podcast networks that syndicate broadcast-origin content into digital feeds.
Germany
Corporate advertisers demand bespoke attribution frameworks and brand safety verification through finance-controlled procurement. The EU Digital Services Act mandates algorithmic transparency for platform-distributed audio ads affecting Spotify operations. Berlin and Munich concentrate independent creator monetization tools competing with open-platform infrastructure.
Brazil
Podcast consumption growth outpaces proportional advertising infrastructure development across Portuguese-language content. Brazil's national advertising regulator monitors disclosure standards for influencer-mediated promotions including audio endorsements. São Paulo hosts early-entrant networks capturing undervalued inventory before local CPMs adjust to demand.
United Kingdom
Mid-market advertisers default to standardized pre-roll inventory through automated buying pipes. The UK Advertising Standards Authority applies Committee of Advertising Practice codes to podcast sponsorship disclosures. London concentrates agency trading desks enabling cross-platform frequency management that individual brands cannot execute.
Australia
English-language content advantages attract Asia-Pacific regional advertising budgets seeking scalable inventory. The Australian Communications and Media Authority oversees broadcast-origin content syndicating into podcast feeds. Sydney and Melbourne anchor creator ecosystems with disproportionate monetizable content relative to population size.
Podcast Advertising Market Competitive Environment
United States platforms anchor one tier; European open-platform specialists hold differentiated positions through regulatory compliance tooling. Market structure concentrates around streaming-integrated distribution, broadcast-to-digital syndication, and independent creator monetization. Three archetypes dominate: walled-garden data integrators, legacy media adapters, and creator-economy infrastructure providers. Competitive moves center on proprietary targeting algorithm development and exclusive content acquisition.
Within the streaming-integrated tier, Spotify leverages proprietary listening data across music and podcast surfaces. iHeartMedia anchors national scale through broadcast-to-podcast syndication infrastructure. Acast occupies a position exemplifying open-platform monetization tools for independent creators facing synthetic voice competition.
| Leading Market Players |
|---|
| Spotify |
| Apple Podcasts |
| iHeartMedia |
| Acast |
| SiriusXM Media |
| Podbean |
| Audioboom |
| Wondery |
| AdsWizz |
| Others |
Value Chain & Pricing Dynamics
Digital audio ad server capacity pricing in the United States and Western Europe cascades through the podcast advertising supply chain into three distinct inventory tiers. Premium host-read placements command rate-card multiples over programmatic pre-roll slots because talent scarcity and brand safety verification costs concentrate in the top tier.
Pricing Analysis
Capacity additions in Brazil and Mexico are reshaping price floors for Portuguese and Spanish-language inventory as early entrants capture undervalued placements before local CPMs adjust. Three-tier pricing structure across premium host-read, standard programmatic, and economy remnant post-roll segments dominates transaction architecture. Price differentiation stems from talent exclusivity and measurement granularity, with direct-to-consumer wellness brands least sensitive to rate inflation and mid-market performance marketers most responsive to CPM compression. Pricing pressure stems from synthetic voice technology absorbing budget that previously flowed to smaller independent creators.
Supply Chain Analysis
Direct-to-advertiser channels handle enterprise brand demand requiring bespoke attribution frameworks and embedded account teams. Supply concentrates in the United States, the United Kingdom, and Australia for English-language monetizable content. Raw material dependencies include server-side ad insertion technology, voice synthesis licensing, and programmatic bidding infrastructure. Single-source vulnerability in host talent relationships creates concentration exposure when personality-driven shows lose creative equity. Distribution runs through streaming-integrated platforms, broadcast-to-podcast syndication networks, and open-platform monetization tools for independent creators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The podcast advertising market functions as a regulatory compounder where the EU Digital Services Act's algorithmic transparency obligations validate audio advertising as a mature medium worthy of oversight and compliance investment.
For Market Incumbents: Acquire synthetic voice production capabilities to defend margin position against automated creative tools displacing mid-market host-read inventory. Consolidate exclusive talent relationships through multi-year sponsorship locks before competitors replicate embedded account-team structures. Backward integration into proprietary measurement infrastructure addresses finance-department skepticism of last-click attribution.
For New Entrants and Emerging Players: Enter via Latin American Portuguese and Spanish-language podcast networks where consumption growth outpaces advertising infrastructure development. Brazil's São Paulo creator ecosystem offers the most penetrable geography for undervalued inventory capture. A go-to-market angle anchored in local brand safety automation tools bypasses manual review bottlenecks slowing campaign activation for early movers.
For Investors and Strategic Acquirers: Asymmetric upside sits with open-platform monetization infrastructure providers serving independent creators facing synthetic voice competition. Long-term viability over the next decade hinges on regulatory compliance tooling for EU Digital Services Act mandates and emerging platform transparency rules. The signal to watch is consolidation velocity among direct-to-consumer brands as customer acquisition budget concentration hardens.
| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Voice Capability Acquisition | Absorbs mid-market advertiser budgets that automated creative tools are displacing from independent creators. |
| Latin American Market Entry | Captures undervalued Portuguese and Spanish-language inventory before São Paulo and Mexico City CPMs adjust. |
| Embedded Account Team Expansion | Places publisher sales staff within venture-backed direct-to-consumer brand marketing departments for co-development. |
| Brand Safety Automation Investment | Reduces manual transcript review bottlenecks that slow campaign activation for mid-market advertisers. |
| Regulatory Compliance Tooling Buildout | Addresses EU Digital Services Act algorithmic transparency obligations affecting Spotify and Apple Podcasts operations. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to triangulate market sizing and growth trajectory. Primary conversations with podcast network sales executives, direct-to-consumer brand marketing officers, programmatic platform engineers, and media agency trading desk operators informed demand-side dynamics. Secondary validation drew from SEC filings of audio streaming platforms, EU Digital Services Act regulatory texts, IAB podcast advertising revenue reports, and customs data on digital audio technology imports. Bottom-up aggregation of publisher-reported inventory volumes and top-down validation against advertiser budget flows converged on segment-level estimates.
Comparable historical periods anchored the projection horizon to observed growth trajectories across the analysis window without assuming structural breaks. Segmentation modeling captured ad format mechanics, advertiser procurement sophistication, listener demographic targeting granularity, and distribution channel transaction structures. CAGRs were derived from trend extrapolation adjusted for regulatory milestone impacts and technology substitution effects. Forecast inputs incorporated dynamic ad insertion penetration rates and synthetic voice adoption curves affecting host-read pricing power.
Inputs from platform disclosure filings and network revenue reports were available through the study window; gaps in independent creator monetization data introduce uncertainty bands around long-tail inventory estimates. Forecasts reflect assumptions about EU regulatory enforcement intensity and mobile ad ID deprecation timelines that could shift with stakeholder lobbying outcomes. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Radio and Audio Media
Podcast Market
Radio and Audio Media
Radio Advertising Market
Radio and Audio Media
Latin America Soundbar Market
Radio and Audio Media
Global Professional Audio Market
Radio and Audio Media
Internet Radio Market
Radio and Audio Media
Podcast Hosting Services Market
Radio and Audio Media
Audiobooks Market
Radio and Audio Media
Podcasting Market
Radio and Audio Media
Traditional Radio Advertising Market
Radio and Audio Media
Digital Audio Market
Radio and Audio Media
FM Transmitters Market
Radio and Audio Media
Microphone Market
Radio and Audio Media
Audio Mixing Console Market
Radio and Audio Media
Global 3D Audio Market
Radio and Audio Media
Voice Over New Radio Market