
 Audio Mixing Console Market | 2026-2036
Audio Mixing Console Market Size, Share, and Industry Trends Forecast 2026-2036
Audio Mixing Console Market Insights
Studio-grade signal fidelity is collapsing into mid-market price brackets. Yamaha leverages its semiconductor subsidiary to sustain captive DSP supply chains. Allen & Heath competes through analog heritage positioning in boutique recording environments. DiGiCo specializes in theater and touring-grade FPGA architectures that dominate West End and Broadway installations.
An audio mixing console is an electronic device for combining, routing, and modifying audio signals through parametric equalization, dynamics processing, and panning, typically handling 16 to 128 input channels with bit depths of 24-bit/96 kHz or higher. Its primary purpose is real-time audio balance control for music production, live reinforcement, and broadcast transmission. Digital consoles now lead product type revenue as analog retains niche artisan demand. Cloud-based technology represents the fastest-growing architecture, though hardware-based systems still anchor broadcast reliability requirements. Live events command the largest end-user spend pool, while podcasting shows the steepest application trajectory.
FCC equipment authorization rules govern RF emissions from networked consoles in US broadcast deployments. CE marking and the EU's Radio Equipment Directive shape market access for European installations. Japan's Ministry of Internal Affairs and Communications sets terrestrial broadcast audio standards that METI enforces through product certification. Stakeholders must monitor whether IP transport protocols consolidate around AES67, SMPTE 2110, or proprietary ecosystems before committing to console platform architectures.
Market Dynamics
The migration from dedicated hardware to networked audio-over-IP infrastructure is compressing capital cycles and forcing console manufacturers to recertify platforms against evolving transport protocols. Broadcasters now prioritize interoperability over proprietary DSP architectures.
Growth Catalysts
- AES67/SMPTE 2110 Convergence:The unification of IP transport standards eliminates vendor lock-in and accelerates console refresh cycles across broadcast facilities.
- Germany's Public Broadcasting Infrastructure:ARD and ZDF maintain sustained technical procurement budgets that stabilize demand for theater-grade FPGA consoles.
- Podcast Studio Buildouts:Content creators deploying mid-market digital consoles drive volume in the 16-32 channel segment previously dominated by analog mixers.
Market Restraints
- FPGA Supply Concentration:Xilinx and Intel dominate programmable logic supply, creating single-source vulnerability for theater-grade console manufacturers.
- Legacy Analog Inventory:Decades of installed base in educational institutions and houses of worship extends replacement cycles beyond typical depreciation schedules.
- RF Spectrum Reallocation:FCC wireless microphone band compressions force concurrent console and microphone system upgrades, stretching facility budgets.
Strategic Opportunities
- Cloud-Native Mixing Architectures:Remote production workflows enable console-as-a-service models for regional broadcasters lacking capital for on-premise hardware.
- India's FM Radio Expansion:Phase III licensing creates demand for cost-optimized digital consoles in tier-2 and tier-3 cities.
- Immersive Audio Mandates:Streaming platforms requiring Dolby Atmos compatibility drive channel count expansion in music production consoles.
Industry Challenges
- Dante Certification Timelines:Audinate's interoperability testing creates 6-12 month product launch delays for networked console releases.
- RF Engineering Skill Gap:IP transport expertise shortages in broadcast engineering departments complicate console deployment and troubleshooting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Audio Mixing Console Market |
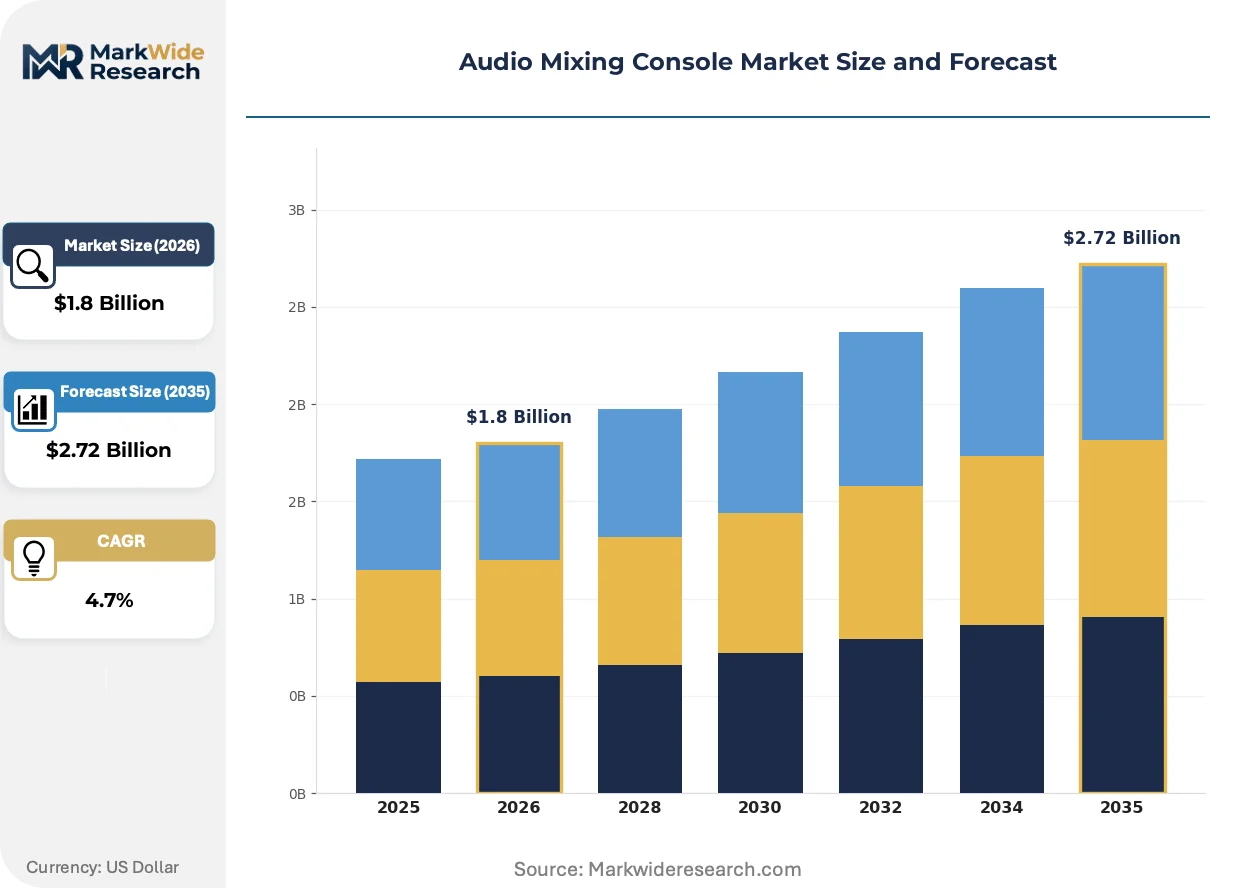
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Consoles, Digital Consoles, Hybrid Consoles, Personal Mixers End User: Recording Studios, Broadcast Stations, Live Events, Educational Institutions Technology: Software-Based, Hardware-Based, Cloud-Based, Integrated Solutions Application: Music Production, Film Scoring, Live Sound, Podcasting |
| Companies Covered | Allen & Heath, DiGiCo, Yamaha, Behringer, PreSonus Audio Electronics, Harman, Mackie, Soundcraft, Avid Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Audio Mixing Console Market Trends and Innovations
DSP hardware is dissolving into software-defined architectures while regulatory pressure on RF emissions intensifies certification requirements. These forces are compressing product lifecycles and redrawing competitive boundaries between semiconductor suppliers and console integrators.
Surface-mount DSP chipsets are miniaturizing console footprints without sacrificing channel density or processing latency. Podcast studios and mobile broadcast trucks adopt these compact platforms to maximize physical space efficiency. The technology is miniaturizing the economic threshold for professional-grade mixing, collapsing distinctions between entry-level and mid-market product tiers.
The EU's Radio Equipment Directive now mandates electromagnetic compatibility testing for all networked audio devices entering European installations. Manufacturers must demonstrate compliance with EN 55103 standards for professional audio equipment immunity. German broadcast integrators report 8-14 week certification delays affecting product launch synchronization across member states.
Facility managers increasingly unbundle console hardware from long-term service contracts, demanding à-la-carte maintenance options. Systems integrators respond with tiered support models separating software updates from on-site technical response. This shift is most pronounced in US live-event rental houses where equipment utilization rates drive preference for flexible cost structures.
Audio Mixing Console Market Segmentation
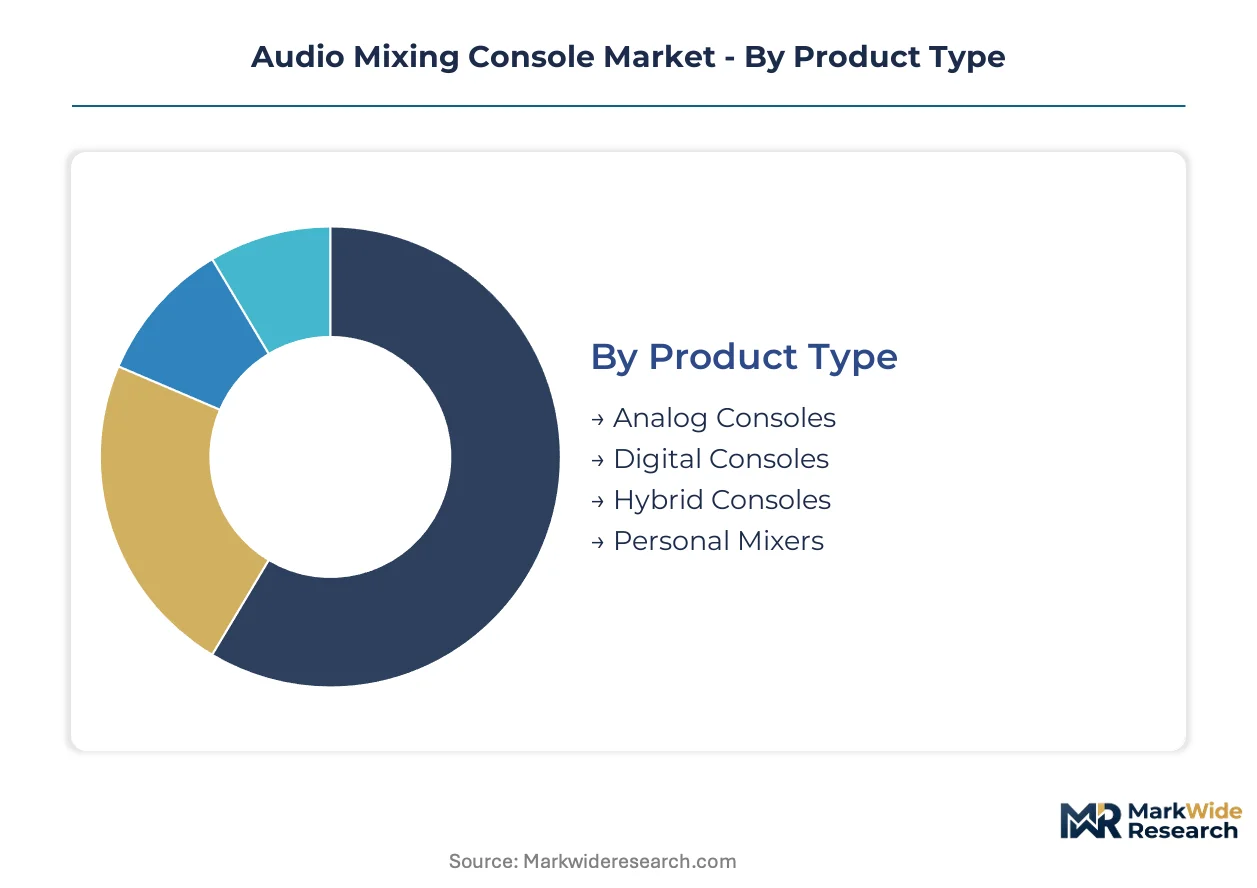
Console procurement patterns diverge sharply across deployment contexts. Broadcast engineers prioritize protocol certification longevity while podcast producers optimize for channel-per-dollar ratios. Each segment category reflects distinct technical trade-offs between signal fidelity, spatial footprint, and interoperability requirements.
Product Type:
Regulatory differentiation separates analog and digital pathways. FCC equipment authorization rules exempt purely analog consoles from RF emissions testing, while networked digital platforms face escalating certification burdens under EU Radio Equipment Directive electromagnetic compatibility mandates.
- Digital Consoles:FPGA and DSP architectures process 24-bit/96 kHz signals across 32-128 input channels with sub-millisecond latency. Broadcast stations in Germany drive procurement volume as ARD and ZDF modernize IP-based audio infrastructure. AES67/SMPTE 2110 protocol convergence accelerates refresh cycles by eliminating vendor lock-in risks.
- Analog Consoles:Discrete transistor and transformer-based signal paths deliver harmonic saturation prized in boutique recording environments. Allen & Heath sustains demand through heritage positioning in London and Nashville studio clusters. No firmware dependencies extend operational lifespan beyond typical depreciation schedules, constraining replacement revenue.
- Hybrid Consoles:Analog front-end with digital routing core bridges legacy workflows and networked infrastructure.
- Personal Mixers:Compact 8-16 channel surfaces target podcast studios and mobile content creators prioritizing space efficiency.
Digital consoles handle the majority of throughput; personal mixers are expanding most quickly on share.
End User:
Cost tier stratification separates capital-intensive broadcast deployments from volume-driven educational procurement. Theater-grade FPGA consoles command 10-20x per-channel pricing against entry-level digital surfaces.
- Live Events:Touring-grade consoles with redundant power supplies and ruggedized chassis withstand 300+ annual show cycles. DiGiCo dominates West End and Broadway installations through dedicated theater FPGA architectures. Rental houses in Las Vegas and London prioritize flexible service contracts over bundled long-term maintenance.
- Broadcast Stations:IP-native consoles with AES67/SMPTE 2110 compliance anchor facility-wide audio-over-IP migrations. US stations navigate FCC spectrum reallocations forcing concurrent wireless microphone and console system upgrades. German public broadcasters stabilize demand through sustained technical infrastructure budgets.
- Recording Studios:Hybrid analog-digital configurations serve music production clients demanding tactile control surfaces.
- Educational Institutions:Decades of installed analog base extends replacement cycles beyond typical depreciation schedules.
Live events command the largest spend pool; podcasting-adjacent educational buildouts are gaining share fastest.
Technology:
Application context dictates architecture selection. Remote production workflows favor cloud-native mixing while on-premise broadcast demands hardware-based reliability guarantees.
- Cloud-Based:Browser-accessible DSP instances enable console-as-a-service models for regional broadcasters lacking capital for physical infrastructure. Latency constraints limit deployment to non-time-critical post-production workflows. India's FM Radio Phase III expansion creates demand for distributed mixing in tier-2 and tier-3 cities.
- Hardware-Based:Dedicated DSP chipsets from Yamaha's semiconductor subsidiary ensure captive supply chain security. Surface-mount miniaturization collapses economic thresholds between entry-level and mid-market tiers. RF emissions certification under EU Radio Equipment Directive creates 8-14 week launch delays.
- Software-Based:Native processing on commercial computing hardware reduces BOM cost for podcast studio deployments.
- Integrated Solutions:Pre-configured console, stagebox, and networking bundles simplify procurement for non-technical buyers.
Hardware-based systems anchor current revenue; cloud-native architectures show the steepest expansion trajectory.
Application:
Volume concentration in live sound contrasts with margin structure in specialized production verticals. Dolby Atmos compatibility mandates drive channel count inflation in music-focused deployments.
- Music Production:Immersive audio requirements from streaming platforms expand channel counts from stereo to 7.1.4 and beyond. Film scoring stages in Los Angeles and London demand 64+ fader surfaces with dedicated surround panning modules. FPGA supply concentration from Xilinx and Intel creates single-source vulnerability for high-channel-count manufacturers.
- Podcasting:16-32 channel digital consoles displace analog mixers in content creator buildouts. USB-C connectivity and automated mixing workflows reduce technical operator requirements. Dante certification timelines from Audinate impose 6-12 month product launch delays.
- Live Sound:Rapid scene recall and networked personal monitoring dominate festival and touring requirements.
- Film Scoring:Tight integration with picture playback systems distinguishes purpose-built orchestral mixing stages.
Live sound handles the majority of throughput; podcasting is the fastest mover on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor fabrication for DSP chipsets concentrates in Japan and Taiwan, while console assembly and systems integration cluster in Germany, the United Kingdom, and the United States. This geographic split between component supply and finished goods manufacturing shapes regional procurement patterns and certification timelines.
United States
Broadcast stations in New York and Los Angeles drive demand for IP-native consoles as FCC spectrum reallocations force concurrent wireless and mixing infrastructure upgrades. FCC equipment authorization rules govern RF emissions from networked installations, creating compliance bottlenecks for foreign manufacturers. Nashville's recording studio cluster sustains demand for analog heritage consoles through boutique music production workflows.
Germany
ARD and ZDF public broadcasters maintain sustained technical procurement budgets that stabilize demand for theater-grade FPGA consoles across Berlin and Cologne facilities. CE marking and the EU's Radio Equipment Directive mandate electromagnetic compatibility testing under EN 55103 standards, generating 8-14 week certification delays. Hamburg's systems integration houses serve as distribution hubs for Central European broadcast deployments.
United Kingdom
West End theater productions and London broadcast facilities anchor demand for touring-grade redundant consoles with rapid scene recall capabilities. Ofcom spectrum management policies align with EU electromagnetic compatibility frameworks post-Brexit, preserving certification continuity. Manchester's live event rental houses prioritize flexible service contracts over bundled long-term maintenance agreements.
Japan
Yamaha's semiconductor subsidiary in Hamamatsu ensures captive DSP supply chain security for domestic console manufacturers serving NHK broadcast standards. METI enforces terrestrial broadcast audio certification through the Ministry of Internal Affairs and Communications, creating regulatory alignment between component and finished goods testing. Tokyo's post-production studios drive demand for immersive audio-compatible surfaces as streaming platforms mandate Dolby Atmos output.
India
Phase III FM radio licensing creates demand for cost-optimized digital consoles in tier-2 cities including Pune, Jaipur, and Lucknow as private broadcasters expand beyond Delhi and Mumbai. TRAI broadcasting regulations govern spectrum allocation and facility licensing, indirectly shaping equipment procurement specifications. Bengaluru's podcast studio buildouts drive volume in compact 16-32 channel segments previously served by analog mixers.
Audio Mixing Console Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Premium-tier manufacturers differentiate through FPGA architectures and theater-grade reliability certifications, while mid-market competitors optimize channel-per-dollar ratios for podcast and educational deployments. Three archetypes dominate: semiconductor-integrated conglomerates with captive chip supply, analog heritage specialists serving boutique recording environments, and networked audio protocol specialists. Competitive moves center on Dante certification acquisition and cloud-native architecture development rather than price-based rivalry.
Within the semiconductor-integrated tier, Yamaha anchors Japanese supply chain security through in-house DSP fabrication. Allen & Heath and DiGiCo occupy distinct positioning vectors—Allen & Heath exemplifies analog heritage preservation for London and Nashville studio clusters, while DiGiCo represents theater-grade FPGA specialization for West End and Broadway installations. These three companies illustrate how geographic origin and technical archetype combine to define competitive territory without direct product overlap.
| Leading Market Players |
|---|
| Allen & Heath |
| DiGiCo |
| Yamaha |
| Behringer |
| PreSonus Audio Electronics |
| Harman |
| Mackie |
| Soundcraft |
| Avid Technology |
| Others |
Pricing and Supply Chain Analysis
Eight-to-fourteen-week certification delays under the EU Radio Equipment Directive compress inventory turnover and amplify pricing power for pre-certified console manufacturers serving German broadcast integrators. FPGA supply concentration from Xilinx and Intel creates single-source dependency that hardware-based manufacturers pass through as cost premiums on theater-grade installations.
Pricing Analysis
FCC equipment authorization rules dictate the pricing tier structure across US broadcast deployments, separating exempt analog consoles from RF-tested digital platforms bearing compliance premiums. Three-tier pricing structure across premium theater-grade, standard broadcast, and economy podcast-studio levels stratifies by channel count and protocol certification depth. Cost compression in the mid-market tier intensifies because surface-mount DSP miniaturization collapses distinctions between entry-level and professional-grade feature sets. Educational institutions exhibit highest price sensitivity due to decades of depreciated analog inventory, while German public broadcasters show lowest sensitivity through sustained ARD and ZDF technical infrastructure budgets.
Supply Chain Analysis
Taiwan and Japan semiconductor fabrication underwrites global DSP chipset availability for console manufacturers, with Hamamatsu-based captive production securing Yamaha's supply chain independence. Raw material dependencies center on programmable logic devices from Xilinx and Intel, surface-mount capacitors and resistors from East Asian component houses, and aluminum chassis extrusions from Chinese metalworking clusters. Single-source vulnerability in FPGA supply creates procurement risk for theater-grade console manufacturers dependent on 64+ channel processing architectures. Distribution runs through Hamburg and London systems integration houses serving Central European broadcast facilities, with direct OEM relationships dominating North American live-event rental markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as podcast studio buildouts and India's FM Radio Phase III expansion create demand niches underserved by incumbent broadcast-focused portfolios. Cloud-native mixing architectures and compact personal mixer segments reward specialized entrants over diversified conglomerates.
For Market Incumbents: Compound protocol certification advantages by accelerating AES67/SMPTE 2110 convergence investments before Dante certification timelines lengthen further. Secure captive FPGA supply through long-term offtake agreements with Xilinx and Intel to defend against theater-grade console supply interruptions. Vertical integration into semiconductor fabrication, as Yamaha demonstrates, insulates against programmable logic price volatility. For New Entrants and Emerging Players: Cloud-native mixing service gaps in tier-2 Indian cities and regional US broadcast markets offer white-space penetration below incumbent hardware-focused priorities. India's FM Radio Phase III licensing creates the most penetrable geography for cost-optimized digital console-as-a-service models. Podcast studio operators in Bengaluru and tier-3 Indian cities present channel-per-dollar optimization opportunities through USB-C-enabled compact surfaces with automated mixing workflows. For Investors and Strategic Acquirers: Long-term, this sits as a protocol consolidation play because AES67/SMPTE 2110 standardization eliminates vendor lock-in and accelerates replacement cycles across installed bases. Acquisition targets should exhibit Dante certification completion and cloud-native architecture pipelines rather than hardware-centric legacy revenue. Watch Audinate's interoperability testing queue length as inflection indicator for networked console launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Dante Certification Acquisition | Audinate interoperability testing completion unlocks 6-12 month faster product launches for networked consoles. |
| Cloud-Native Architecture Development | Browser-accessible DSP instances enable console-as-a-service models for capital-constrained regional broadcasters. |
| FPGA Supply Agreement | Long-term Xilinx and Intel offtake contracts secure theater-grade console production against single-source vulnerability. |
| Immersive Audio Compatibility Investment | Dolby Atmos output capability expands addressable market to film scoring stages and streaming platform mandates. |
| Compact Surface Miniaturization | Surface-mount DSP integration collapses economic thresholds for podcast studio and mobile broadcast truck penetration. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with broadcast station chief engineers, live-event rental house technical directors, podcast studio operators, and systems integration firm procurement leads. Secondary validation drew from FCC equipment authorization filings, EU Radio Equipment Directive certification databases, METI terrestrial broadcast audio standards, and customs records of DSP chipset imports. Bottom-up console shipment estimates by channel count and price tier were triangulated against top-down broadcast facility capital expenditure surveys.
Across the analysis window, volume and value outputs were modeled through segmentation by product type, end user, technology architecture, and application vertical, with additional dimensioning by protocol certification status and geographic regulatory cluster. CAGRs were derived from historical replacement cycle analysis and projected IP infrastructure migration timelines. Industry-specific forecast inputs included ARD and ZDF disclosed technical procurement budgets, India TRAI Phase III licensing progress, and Audinate Dante certification queue data.
Forecasts assume regulatory continuity in FCC equipment authorization rules, EU Radio Equipment Directive electromagnetic compatibility mandates, and Japan METI broadcast audio certification regimes; material policy shifts would require re-modeling console refresh cycle assumptions. Practitioners should keep alternative scenarios live as IP transport protocol consolidation around AES67, SMPTE 2110, or proprietary ecosystems evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Radio and Audio Media
Voice Over New Radio Market
Radio and Audio Media
Digital Audio Market
Radio and Audio Media
Radio Advertising Market
Radio and Audio Media
Global Professional Audio Market
Radio and Audio Media
Internet Radio Market
Radio and Audio Media
Global 3D Audio Market
Radio and Audio Media
Podcast Hosting Services Market
Radio and Audio Media
Podcast Advertising Market
Radio and Audio Media
Latin America Soundbar Market
Radio and Audio Media
Audiobooks Market
Radio and Audio Media
FM Transmitters Market
Radio and Audio Media
Podcasting Market
Radio and Audio Media
Podcast Market
Radio and Audio Media
Microphone Market
Radio and Audio Media
Traditional Radio Advertising Market