
 Global 3D Audio Market | 2026-2036
Global 3D Audio Market Size, Share, and Industry Trends Forecast 2026-2036
Global 3D Audio Market Foresight
The EU Green Deal's digital sustainability benchmarks are realigning procurement criteria for audio hardware across European broadcast networks. Dolby Laboratories sustains technology leadership through proprietary object-based encoding ecosystems. Sony Corporation dominates professional cinematic production workflows with immersive mixing consoles. Sennheiser Electronic GmbH & Co. KG anchors the high-end headphones segment through precision transducer engineering.
3D audio encompasses spatial sound reproduction systems that manipulate head-related transfer functions, interaural time differences, and reverberation algorithms to create perceived three-dimensional sound fields. These systems typically operate across frequency ranges from 20 Hz to 20 kHz with channel configurations exceeding traditional stereo to enable elevation, azimuth, and distance perception for gaming, virtual reality, and cinematic applications. Headphones capture the largest installed base among product types due to personal entertainment consumption patterns. Object-based audio technology leads growth trajectories as streaming platforms and automotive entertainment systems adopt adaptive bitrate spatial formats. Gaming and virtual reality applications concentrate margin pools through hardware-software bundled licensing models.
The FCC in the United States mandates accessibility standards for broadcast audio that increasingly incorporate spatial description channels for visually impaired audiences. EMA and CE marking frameworks in Europe enforce electromagnetic compatibility and safety protocols for wearable audio devices entering commercial distribution. Content creators and broadcast companies must monitor evolving interoperability standards between proprietary spatial formats and open-source ambisonics specifications to avoid technology lock-in.
Market Dynamics
The transition from channel-based to object-based audio encoding is restructuring competitive advantage across content production workflows, compressing legacy hardware margins while elevating software licensing revenues.
Growth Catalysts
- EU AI Act content provenance mandates:Broadcasters in France and Germany must embed spatial metadata for synthetic media detection, accelerating object-based audio infrastructure procurement.
- South Korean esports infrastructure investment:Seoul's broadcasting clusters deploy elevation-capable sound systems for tournament livestreams, pulling transducer and DSP hardware through dedicated supply contracts.
- Head-related transfer function personalization:Biometric scanning services in Tokyo and San Francisco enable individualized HRTF profiles, deepening immersion stickiness for premium headphone subscribers.
Market Restraints
- Neodymium magnet supply concentration:Rare earth processing for high-performance transducers clusters in China's Jiangxi and Inner Mongolia provinces, exposing manufacturers to export quota volatility.
- Proprietary format lock-in:Dolby's Atmos ecosystem maintains incompatible metadata schemas with open-source ambisonics, forcing content creators into duplicate mastering workflows.
- Electromagnetic compatibility certification costs:CE marking and FCC Part 15 testing for wearable spatial audio devices adds twelve to eighteen months to product launch timelines.
Strategic Opportunities
- Automotive cabin acoustics:German and Japanese OEMs integrate head-tracking seat arrays for autonomous vehicle entertainment, opening $2,000-plus per-vehicle component attach rates.
- Accessibility mandate expansion:FCC rules on audio description for streaming services create dedicated spatial description channel requirements, mandating new production tool procurement.
- Ambisonics-Atmos convergence middleware:Software bridges enabling format-agnostic distribution reduce mastering duplication costs for mid-tier production houses in London and Los Angeles.
Industry Challenges
- Immersive audio engineering talent scarcity:Object-based mixing expertise concentrates in Copenhagen, Los Angeles, and Tokyo facilities, constraining scaling for regional production centers.
- Legacy broadcast infrastructure retrofit costs:SDI-to-IP conversion for spatial audio transport demands capital redeployment that public broadcasters in Italy and Spain defer amid budget compression.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 3D Audio Market |
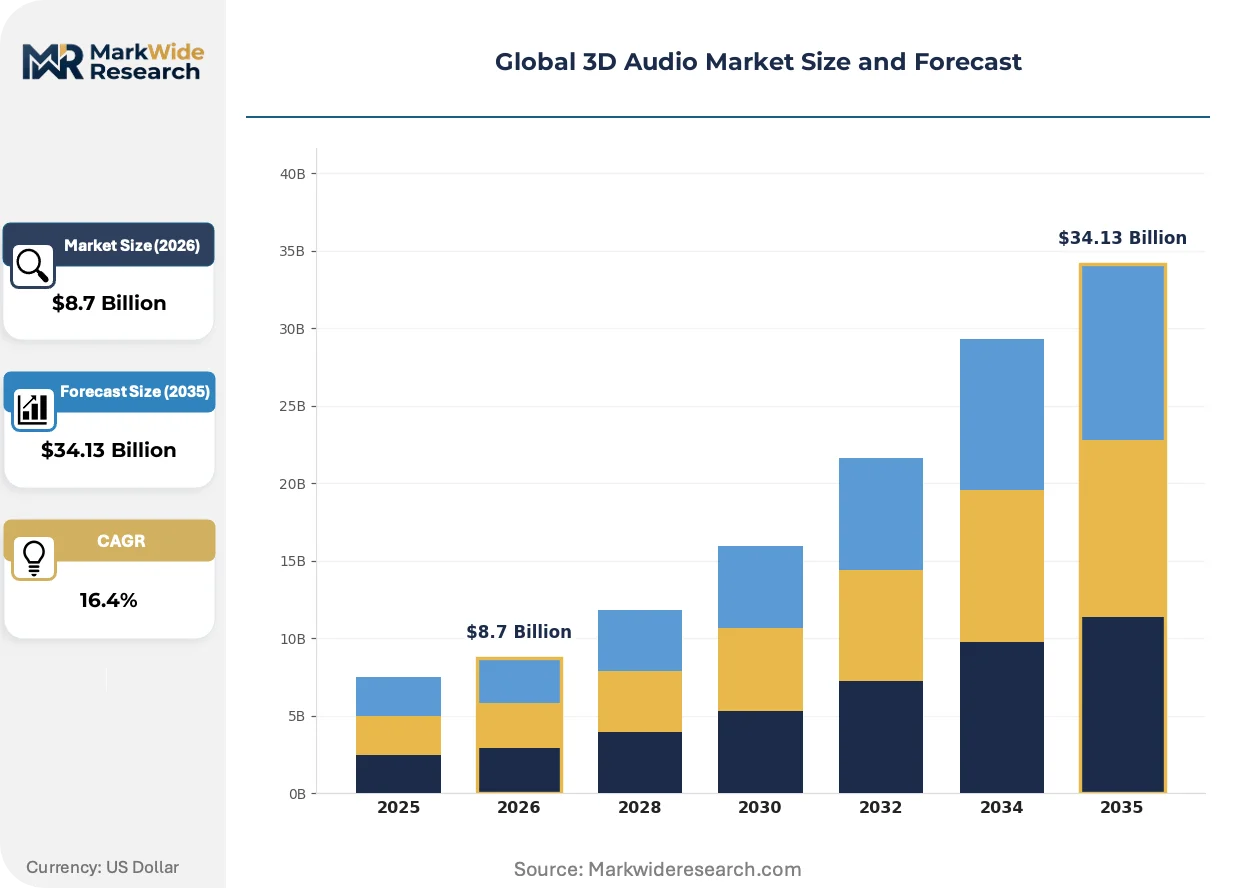
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headphones, Speakers, Soundbars, Microphones, Amplifiers Technology: Binaural Audio, Ambisonics, Wave Field Synthesis, Stereo Lithophonic, Object-Based Audio Application: Gaming, Virtual Reality, Cinematic Production, Music Streaming, Automotive Entertainment End User: Content Creators, Audio Engineers, Event Organizers, Broadcast Companies, Consumer Electronics Firms |
| Companies Covered | Google LLC, Qualcomm Technologies, Inc., Dolby Laboratories, Inc., Auro Technologies, DTS, Inc., Sony Corporation, Sennheiser Electronic GmbH & Co. KG, Waves Audio Ltd., Apple Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 3D Audio Market Shifts & Advancements
Spatial audio technology stacks are fragmenting into interoperable component layers, decoupling capture, rendering, and distribution functions previously bound to single-vendor ecosystems.
Cloud-native spatial audio production tools are modularizing post-production workflows. Independent mixing engineers in London and Mumbai rent GPU-based rendering instances by the hour rather than purchasing dedicated hardware. This compression of fixed-cost barriers enables boutique studios to bid on theatrical and streaming projects previously reserved for facility-based competitors.
REACH restrictions on persistent organic pollutants are reshaping transducer material specifications. European manufacturers reformulate voice coil adhesives and diaphragm polymers to eliminate restricted phthalates and flame retardants. Headphone and loudspeaker OEMs serving EU distribution channels accelerate supplier qualification timelines to maintain CE marking continuity.
Subscription bundling is displacing perpetual licensing for spatial audio creation tools. Game audio departments in Montreal and Stockholm negotiate enterprise seats with usage-based overage rather than site-wide perpetual agreements. This preference shift pressures middleware vendors to restructure revenue recognition and customer success functions around consumption metrics rather than upfront purchase milestones.
Global 3D Audio Market Segmentation
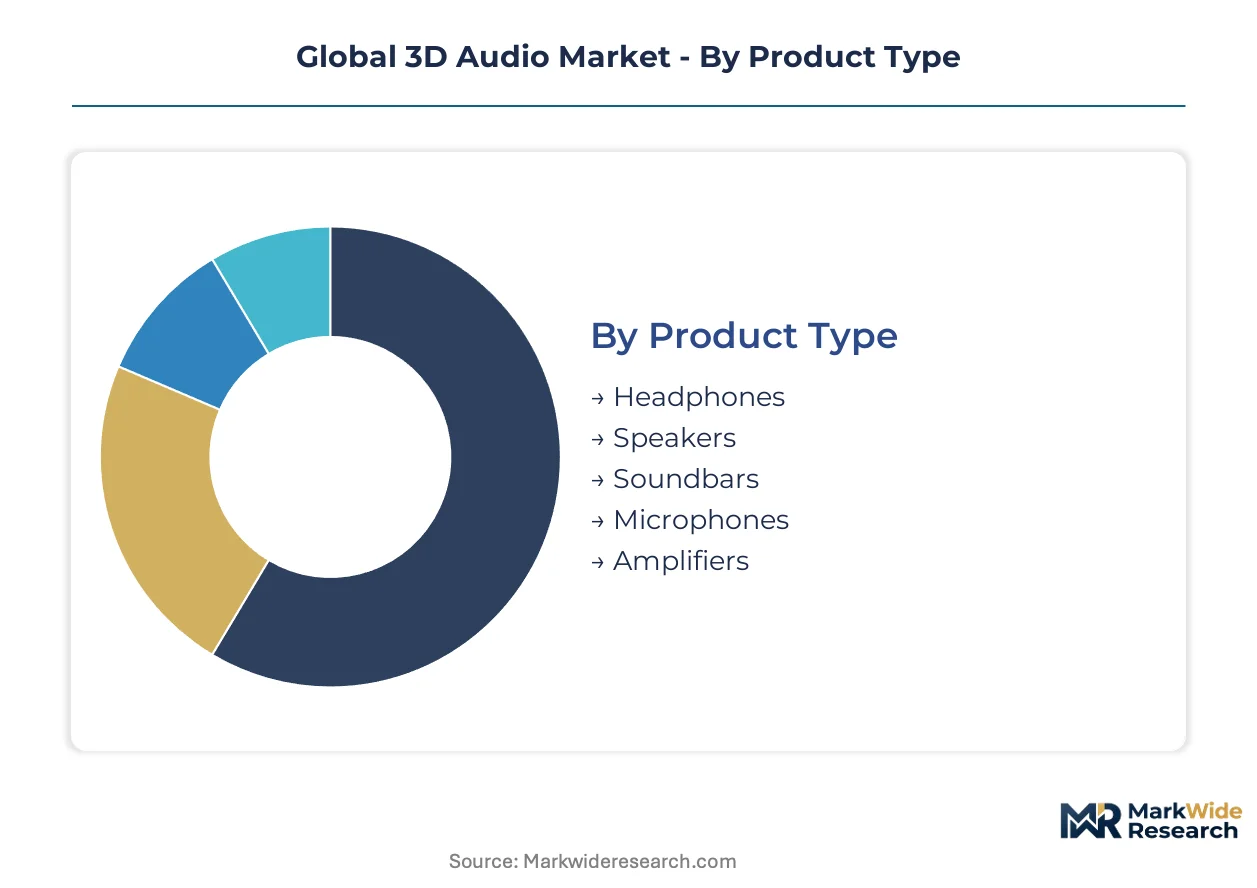
Segmentation in 3D audio reveals divergent capital requirements and margin profiles across hardware manufacturing, software licensing, and professional services. Product type and technology dimensions impose fundamentally different fixed-cost burdens on market participants.
Product Type:
Capital intensity varies sharply across physical manufacturing segments, with transducer engineering and acoustic calibration demanding the heaviest upfront tooling investment.
- Headphones:Personal spatial audio devices integrate MEMS accelerometers for head-tracking alongside miniature balanced armature or dynamic drivers. Seoul's manufacturing clusters and Shenzhen's assembly ecosystems concentrate consumer-grade volume, while Tokyo and Munich facilities handle premium audiophile tiers with individualized HRTF calibration services.
- Speakers:Multi-driver arrays for elevation and azimuth reproduction require precision crossover networks and room-correction DSP. Professional monitoring installations in Los Angeles and London post-production suites drive demand for reference-grade systems with calibrated directivity patterns.
- Soundbars:Compact form factors deploy beam-steering transducer arrays and virtual height processing to simulate overhead channels without ceiling-mounted hardware.
- Microphones:Ambisonic capture devices utilize tetrahedral capsule arrangements for full-sphere recording, with European broadcasters standardizing on A-format/B-format conversion workflows.
- Amplifiers:Multi-channel Class D architectures with object-based rendering engines enable scalable channel counts for immersive cinema installations.
Most installed capacity flows through Headphones. Expansion is steepest in Soundbars as living-room spatial audio adoption accelerates.
Technology:
Intellectual property intensity separates proprietary ecosystems from open-source alternatives, reshaping licensing economics across content creation tools.
- Object-Based Audio:Metadata-driven sound elements carry positional coordinates independent of playback channel count, enabling adaptive rendering across headphones, soundbars, and theatrical arrays. Dolby's Atmos and MPEG-H dominate broadcast and streaming standardization, with EU AI Act provenance mandates accelerating encoder procurement in France and Germany.
- Ambisonics:Full-sphere capture and reproduction using spherical harmonic decomposition offers format-agnostic interchange. Independent creators in London and Mumbai favor open-source toolchains for VR and 360-degree video workflows to avoid royalty-bearing proprietary stacks.
- Binaural Audio:Headphone-specific rendering applies individualized HRTF filtering to create externalized sound sources without multi-channel hardware.
- Wave Field Synthesis:Loudspeaker arrays reconstruct acoustic wavefronts through precise delay and amplitude control for holographic sound fields.
- Stereo Lithophonic:Emerging techniques manipulate interaural cues through specialized transducer geometries for glasses-free spatial perception.
Object-Based Audio commands the dominant share of professional infrastructure investment. Ambisonics is gaining share fastest among independent and open-source production communities.
Application:
Customer willingness-to-pay for spatial audio fidelity diverges dramatically between entertainment consumption and professional content creation use cases.
- Gaming:Real-time spatial audio engines integrate with game physics for dynamic occlusion, reverberation, and elevation cues. Montreal and Stockholm studios bundle proprietary middleware with hardware peripherals through platform-holder licensing agreements, capturing recurring revenue from attach rates.
- Virtual Reality:Six-degrees-of-freedom head tracking demands sub-20-millisecond audio latency with positional updates synchronized to visual rendering. San Francisco and Tokyo VR platform operators subsidize HRTF personalization services to reduce churn among premium subscribers.
- Cinematic Production:Theatrical mixing stages in Los Angeles and Copenhagen deploy object-based authoring tools for theatrical and streaming distribution.
- Music Streaming:Adaptive bitrate spatial formats from Apple, Sony, and Tidal compete for exclusive artist releases and subscriber acquisition.
- Automotive Entertainment:German and Japanese OEMs integrate head-tracking seat arrays for autonomous vehicle passenger entertainment, with per-vehicle component values exceeding premium infotainment tiers.
Gaming and Virtual Reality together absorb the majority of real-time rendering hardware shipments. Automotive Entertainment is climbing the fastest as cabin acoustics become a differentiation vector for luxury electric vehicles.
End User:
Procurement sophistication and budget scale separate enterprise-grade production infrastructure from individual creator tool purchases.
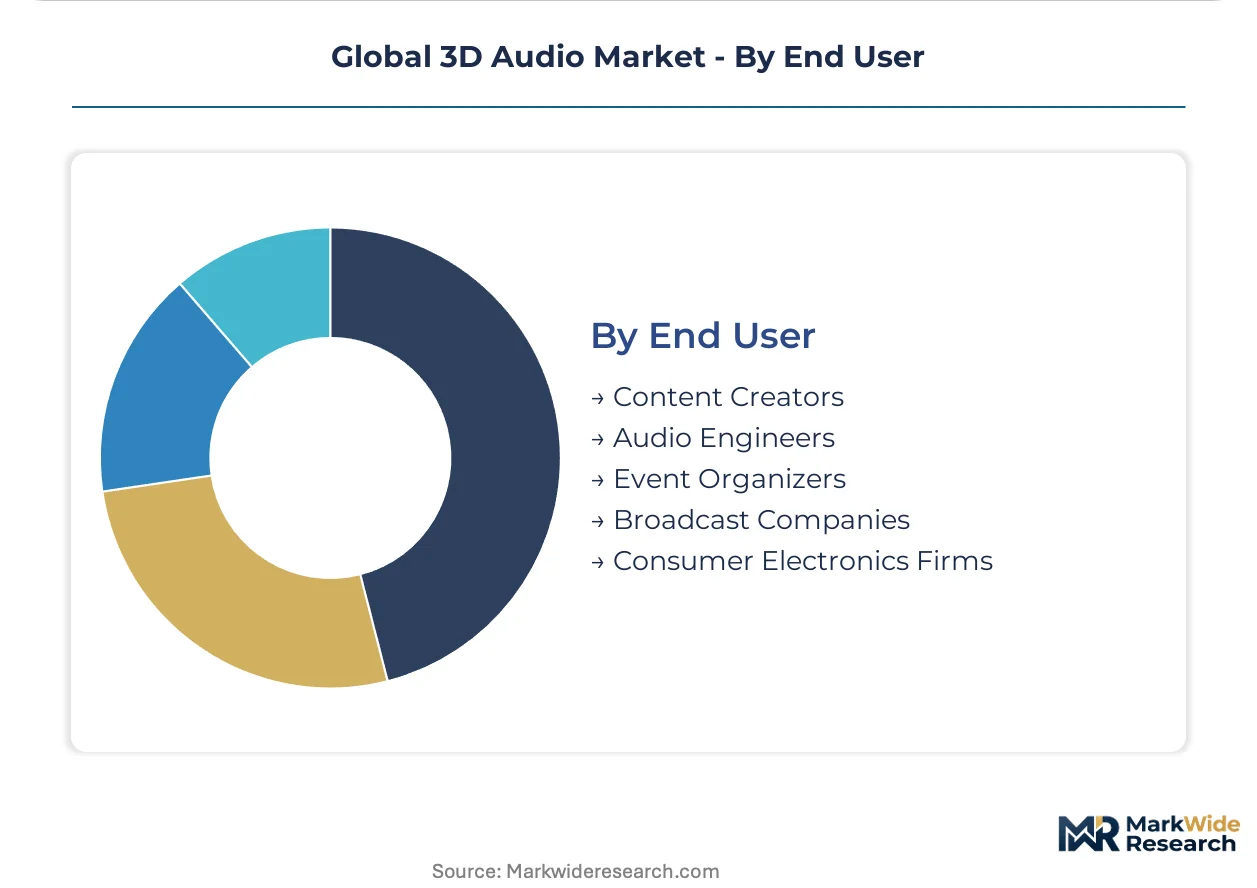
- Content Creators:Individual YouTube, podcast, and indie game producers rent cloud-native spatial audio tools by consumption rather than purchasing perpetual licenses. GPU-based rendering instances from London and Mumbai service providers enable boutique studios to bid on theatrical projects.
- Audio Engineers:Freelance and facility-based mixing professionals in Copenhagen, Los Angeles, and Tokyo command premium rates for object-based mixing expertise, with talent scarcity constraining regional production center scaling.
- Event Organizers:Live esports and concert producers deploy temporary elevation-capable arrays for immersive audience experiences.
- Broadcast Companies:Public networks in Italy and Spain defer SDI-to-IP infrastructure retrofits for spatial audio transport amid budget compression, while South Korean esports broadcasters accelerate procurement.
- Consumer Electronics Firms:Smartphone, laptop, and wearable OEMs integrate spatial audio processing IP through semiconductor licensing.
Consumer Electronics Firms represent the largest procurement volume by unit shipment. Content Creators are expanding most quickly as subscription-based tool access lowers entry barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spatial audio engineering talent concentrates in Copenhagen, Los Angeles, and Tokyo, anchoring premium production workflows while manufacturing clusters in Seoul and Shenzhen drive hardware volume at divergent margin tiers.
United States
San Francisco VR platform operators subsidize HRTF personalization services to reduce subscriber churn, while Los Angeles theatrical mixing stages deploy object-based authoring tools for streaming distribution. FCC accessibility mandates for audio description channels push broadcasters toward spatial metadata procurement. Greater Los Angeles absorbs the majority of North American cinematic post-production infrastructure investment.
Germany
German automotive OEMs integrate head-tracking seat arrays for autonomous vehicle entertainment, opening premium per-vehicle component attach rates. EU AI Act content provenance requirements accelerate object-based encoder procurement across French and German broadcasters. Munich facilities handle premium audiophile headphone tiers with individualized calibration services.
South Korea
Seoul's esports broadcasting clusters deploy elevation-capable sound systems for tournament livestreams, pulling transducer and DSP hardware through dedicated supply contracts. MFDS electromagnetic compatibility frameworks govern wearable device commercial distribution. Seoul Capital Area manufacturing ecosystems concentrate consumer-grade spatial audio assembly capacity.
Japan
Tokyo VR platform operators and biometric scanning services enable individualized HRTF profiles for premium headphone subscribers. METI standards coordination influences regional spatial audio interoperability specifications. Kanto region facilities anchor precision transducer engineering for high-end headphones and professional monitoring systems.
China
Shenzhen assembly ecosystems concentrate consumer-grade spatial audio hardware volume, while rare earth processing for neodymium magnets clusters in Jiangxi and Inner Mongolia provinces. MIIT electromagnetic compatibility protocols shape product launch timelines for wearable devices. Pearl River Delta manufacturing nodes supply transducer components to global OEM procurement networks.
Global 3D Audio Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the spatial audio value chain, with semiconductor foundries and acoustic engineering houses occupying divergent margin positions. The vendor base organizes around three strategic archetypes: proprietary format licensors capturing software recurring revenue, precision transducer manufacturers defending hardware margins, and cloud-native tool providers disrupting perpetual licensing models. Dominant competitive moves include format ecosystem expansion through platform partnerships and backward integration into MEMS sensor fabrication for head-tracking capabilities.
Within the proprietary format tier, Dolby Laboratories and DTS exemplify intellectual property licensors that anchor industry standardization through metadata schema control. Sony Corporation occupies a position spanning both professional cinematic hardware and consumer electronics integration. Among precision audio specialists, Sennheiser Electronic GmbH & Co. KG represents the high-end transducer engineering archetype. Google LLC and Apple Inc. sit within the platform-operator segment, bundling spatial audio processing into mobile operating systems and subscription services.
| Leading Market Players |
|---|
| Google LLC |
| Qualcomm Technologies, Inc. |
| Dolby Laboratories, Inc. |
| Auro Technologies |
| DTS, Inc. |
| Sony Corporation |
| Sennheiser Electronic GmbH & Co. KG |
| Waves Audio Ltd. |
| Apple Inc. |
| Others |
Supply & Pricing Matrix
Neodymium magnet costs cascade through transducer manufacturing tiers, with Jiangxi and Inner Mongolia rare earth processing quotas compressing margins for premium headphone OEMs while forcing mid-tier soundbar producers toward ferrite alternatives. This input-cost stratification widens the gap between individualized HRTF-calibrated products and mass-market beam-steering arrays.
Pricing Analysis
Bundled hardware-software licensing dominates gaming and VR verticals, while unbundled component sales persist in professional cinematic workflows. Three-tier pricing structure across premium, standard, and economy levels separates individualized HRTF calibration services from MEMS-accelerometer-integrated consumer units and basic virtual-height soundbars. Pricing pressure stems from cloud-native production tools collapsing fixed-cost barriers for mid-tier mixing houses. Content creators exhibit highest price sensitivity through hourly GPU-rental models, whereas automotive OEMs absorb premium per-vehicle component attach rates with minimal negotiation.
Supply Chain Analysis
Domestic-content mandates in South Korea's esports infrastructure procurement and EU Green Deal digital sustainability benchmarks are reshaping sourcing toward regional transducer assembly. Manufacturing concentrates in Shenzhen for consumer-grade volume, Seoul Capital Area for mid-tier assembly, and Tokyo-Munich corridors for precision audiophile engineering. Voice coil adhesives and diaphragm polymers draw from reformulated European suppliers eliminating REACH-restricted phthalates. Single-source vulnerability clusters in China's rare earth processing nodes. Distribution runs through dedicated supply contracts for tournament broadcasters and semiconductor IP licensing for mobile OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion hinges on software licensing displacing hardware-centric revenue, with object-based audio metadata standards enabling recurring encoder royalties that outpace transducer commoditization cycles.
For Market Incumbents: Acquire cloud-native spatial audio rendering platforms to offset perpetual license displacement by subscription models. Consolidate object-based mixing talent in Copenhagen and Los Angeles through earnout-structured acquisitions. Defend against open-source ambisonics encroachment by embedding proprietary metadata schemas into platform-holder SDKs. Backward integration into MEMS accelerometer fabrication secures head-tracking hardware margins. For New Entrants and Emerging Players: FCC accessibility mandates in the United States open a window for spatial description channel production tools targeting streaming service compliance. White-space exists in ambisonics-Atmos convergence middleware for London and Mumbai mid-tier houses burdened by duplicate mastering workflows. Target automotive cabin acoustics for German and Japanese OEM autonomous vehicle programs through head-tracking seat array partnerships. Go-to-market through direct engineering contracts rather than channel distribution. For Investors and Strategic Acquirers: Consolidation pressure builds where cloud-native tool providers disrupt perpetual licensing incumbents with consumption-based revenue recognition. Long-term viability favors asset-light software licensors over capital-heavy transducer manufacturers facing REACH material reformulation costs. Acquisition targets include GPU-rendering service operators in London and Mumbai and HRTF personalization biometric scanning services in Tokyo and San Francisco. Watch for EU AI Act provenance mandate enforcement acceleration as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Object-Based Encoder Licensing Expansion | Dolby and MPEG-H schema control captures recurring royalties from French and German broadcast compliance procurement. |
| Cloud-Native Production Platform Launch | GPU-based hourly rendering instances collapse fixed-cost barriers for boutique London and Mumbai mixing studios. |
| HRTF Personalization Service Acquisition | Biometric scanning capabilities in Tokyo and San Francisco deepen subscriber stickiness for premium headphone tiers. |
| Automotive Cabin Acoustics Partnership | German and Japanese OEM head-tracking seat arrays unlock per-vehicle component values exceeding premium infotainment tiers. |
| REACH-Compliant Material Supplier Qualification | European voice coil adhesive and diaphragm polymer reformulation maintains CE marking continuity for distribution channels. |
Research Methodology
Direct dialogue with spatial audio engineering leads, broadcast technology procurement officers, automotive cabin acoustics platform engineers, and cloud-native tool product managers grounded qualitative findings in operational reality. Secondary validation drew from FCC accessibility rulemakings, EU AI Act implementation guidance, ECHA REACH restriction updates, and SEC filings of publicly traded audio technology licensors. Bottom-up segment sizing triangulated against top-down market envelope estimates from trade flow analysis and semiconductor IP licensing disclosures.
Bottom-up modeling built volume and value outputs from transducer shipment data, software seat counts, and professional services billing rates across the projection horizon. Segmentation dimensions spanned product type, technology architecture, application vertical, and end-user procurement sophistication. CAGRs derived from historical growth rate analysis adjusted for regulatory mandate timing and platform adoption curves. Industry-specific inputs included esports broadcasting infrastructure investment pipelines and automotive OEM autonomous vehicle entertainment roadmaps.
Revisions become necessary when rare earth export quota volatility, REACH restriction scope expansion, or ambisonics-Atmos format convergence accelerates beyond modeled timelines. Forecasts reflect documented assumptions about regulatory enforcement pacing and platform-holder SDK integration schedules. A small set of named triggers warrants ongoing watch: EU AI Act spatial metadata mandate rollout velocity, South Korean esports broadcasting procurement cycle timing, and cloud-native tool consumption metric reporting transparency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Radio and Audio Media
Traditional Radio Advertising Market
Radio and Audio Media
FM Transmitters Market
Radio and Audio Media
Podcast Hosting Services Market
Radio and Audio Media
Podcasting Market
Radio and Audio Media
Podcast Advertising Market
Radio and Audio Media
Microphone Market
Radio and Audio Media
Global Professional Audio Market
Radio and Audio Media
Podcast Market
Radio and Audio Media
Radio Advertising Market
Radio and Audio Media
Internet Radio Market
Radio and Audio Media
Voice Over New Radio Market
Radio and Audio Media
Latin America Soundbar Market
Radio and Audio Media
Audiobooks Market
Radio and Audio Media
Digital Audio Market
Radio and Audio Media
Audio Mixing Console Market