
 Audiobooks Market | 2026-2036
Audiobooks Market Size, Share, and Industry Trends Forecast 2026-2036
Audiobooks Market Intelligence
Subscription bundling is broadening buyer choice as platforms merge audiobooks with music, podcasts, and video into single monthly plans. Spotify leverages its streaming infrastructure to cross-promote audiobook content to existing music subscribers. Audible anchors the premium segment through exclusive original productions and deep backlist partnerships with major publishers. Kuku FM competes in emerging markets with hyper-local language content and aggressive mobile-first pricing.
An audiobook is a recorded spoken-word adaptation of written text, distributed digitally through compressed audio formats such as MP3, AAC, or proprietary DRM-protected files, with typical runtime spanning six to twenty hours depending on title length; its primary commercial purpose is to transform reading into a hands-free, mobile-compatible consumption experience for time-constrained audiences. The platform dimension shows streaming services capturing the fastest growth as cloud delivery eliminates download friction, while mobile apps dominate daily engagement through offline caching and sleep-timer features. Genre segmentation reveals non-fiction and self-help titles generating disproportionate per-user revenue due to repeat listening and professional development use cases.
The Federal Communications Commission shapes digital audio distribution through net neutrality frameworks that affect platform bandwidth costs, while the European Union's Digital Services Act imposes content moderation obligations on cross-border streaming platforms. The U.S. Copyright Office and the EU's collective management organizations both influence licensing terms between publishers and audiobook distributors. Stakeholders must monitor how evolving royalty structures and platform antitrust scrutiny in Washington and Brussels reshape exclusive content deals and subscriber acquisition economics.
Market Dynamics
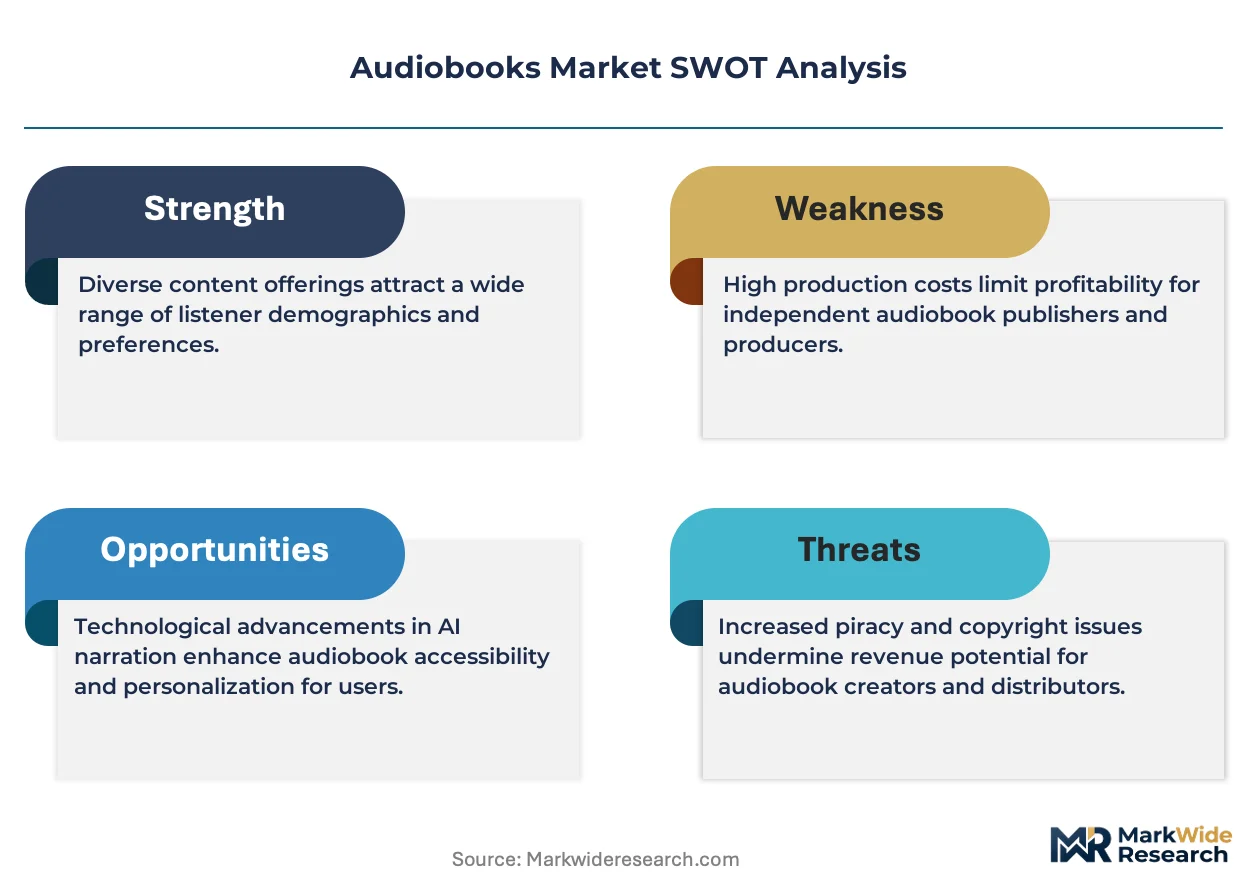
AI-driven text-to-speech synthesis is compressing production timelines for backlist titles while reshaping cost structures across the audiobooks value chain, forcing incumbents to defend premium positioning against algorithmic alternatives.
Growth Catalysts
- Net neutrality frameworks:The Federal Communications Commission's bandwidth regulations reduce platform delivery costs, enabling streaming-first business models that expand addressable audiences beyond download-dependent users.
- Commuter professionals:Time-constrained white-collar workers in dense metropolitan corridors convert drive-time and transit hours into consumption opportunities, driving subscription attach rates for bundled audio services.
- Library digital lending:Municipal and university library systems in the United States expand patron access through OverDrive and similar platforms, normalizing audiobook consumption among cost-sensitive reader segments.
Market Restraints
- Narrator talent scarcity:Experienced voice actors command premium rates for exclusive contracts, inflating production costs for original content that cannot be algorithmically generated without quality degradation.
- Publisher concentration:Five major trade publishers control exclusive licensing for frontlist titles, limiting distributor negotiating leverage and compressing margin pools for mid-tier platforms.
- DRM interoperability friction:Proprietary encryption standards across Audible, Apple Books, and Spotify create consumer lock-in that suppresses platform switching and fragments library ownership.
Strategic Opportunities
- India vernacular expansion:Hindi, Tamil, and Marathi content gaps present white-space opportunities for mobile-first platforms targeting tier-two city consumers with data-optimized streaming.
- EU Digital Services Act compliance:Content moderation obligations create barriers for non-compliant entrants, favoring established distributors with legal infrastructure to absorb regulatory overhead.
- Podcast-audiobook convergence:Serialized fiction podcasts on Spotify and Apple Podcasts train listeners on episodic audio consumption, creating pipeline audiences for full-length narrative adaptations.
Industry Challenges
- Royalty rate disputes:Publishers and distributors clash over equitable compensation for AI-narrated titles, with unresolved IP frameworks delaying backlist digitization programs.
- Platform exclusivity fragmentation:Audible's original content investments and Spotify's audiobook bundling force competitors to burn capital on subscriber acquisition without path to profitability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Audiobooks Market |
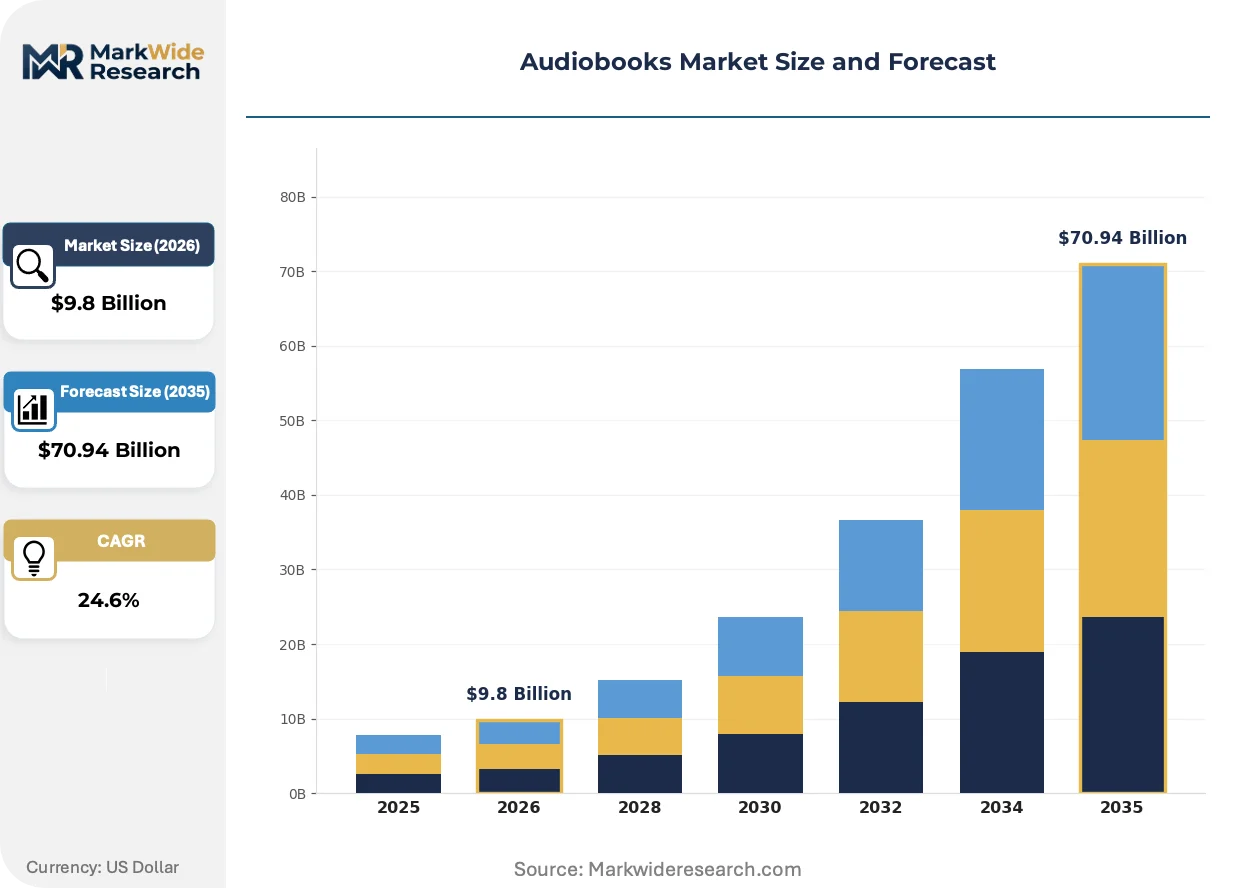
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $70.94 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Format: Digital, CD, Vinyl, Audio Cassette Genre: Fiction, Non-Fiction, Self-Help, Educational Platform: Mobile Apps, Streaming Services, Audiobook Retailers, Libraries Target Audience: Young Adults, Professionals, Students, Seniors |
| Companies Covered | Spotify, Nextory, RBmedia, Google, Audioteka, Audible, Kuku FM, Apple, Storytel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Audiobooks Market Strategic Shifts & Innovations
Synthetic voice technology and regulatory fragmentation are reconfiguring production economics and competitive boundaries simultaneously, rewarding platforms that integrate algorithmic efficiency with compliance infrastructure.
Neural text-to-speech engines from Google and Amazon is modularizing the audiobook production pipeline, compressing title turnaround from weeks to hours. Mid-tier publishers and self-published authors adopt these tools for backlist monetization where narrator costs previously rendered projects unviable. The structural consequence is a bifurcation between premium human-narrated originals and algorithmic volume plays that saturate price-sensitive segments.
The European Union's Digital Services Act imposes algorithmic transparency and content moderation duties on streaming platforms with cross-border reach. Distributors must deploy localized trust-and-safety teams and audit recommendation engines, raising operational fixed costs. Smaller platforms serving EU markets face compliance-driven consolidation pressure as legal overhead disproportionately burdens limited revenue bases.
Subscription bundling across music, podcasts, and audiobooks is displacing standalone audiobook purchases among younger demographics. Spotify's unified audio feed trains users to discover narrated content through algorithmic surfaces rather than deliberate search, disrupting Audible's catalog-centric discovery model. This behavioral shift concentrates most acutely in the United States and United Kingdom, where platform penetration and payment infrastructure support seamless bundling economics.
Audiobooks Market Segmentation
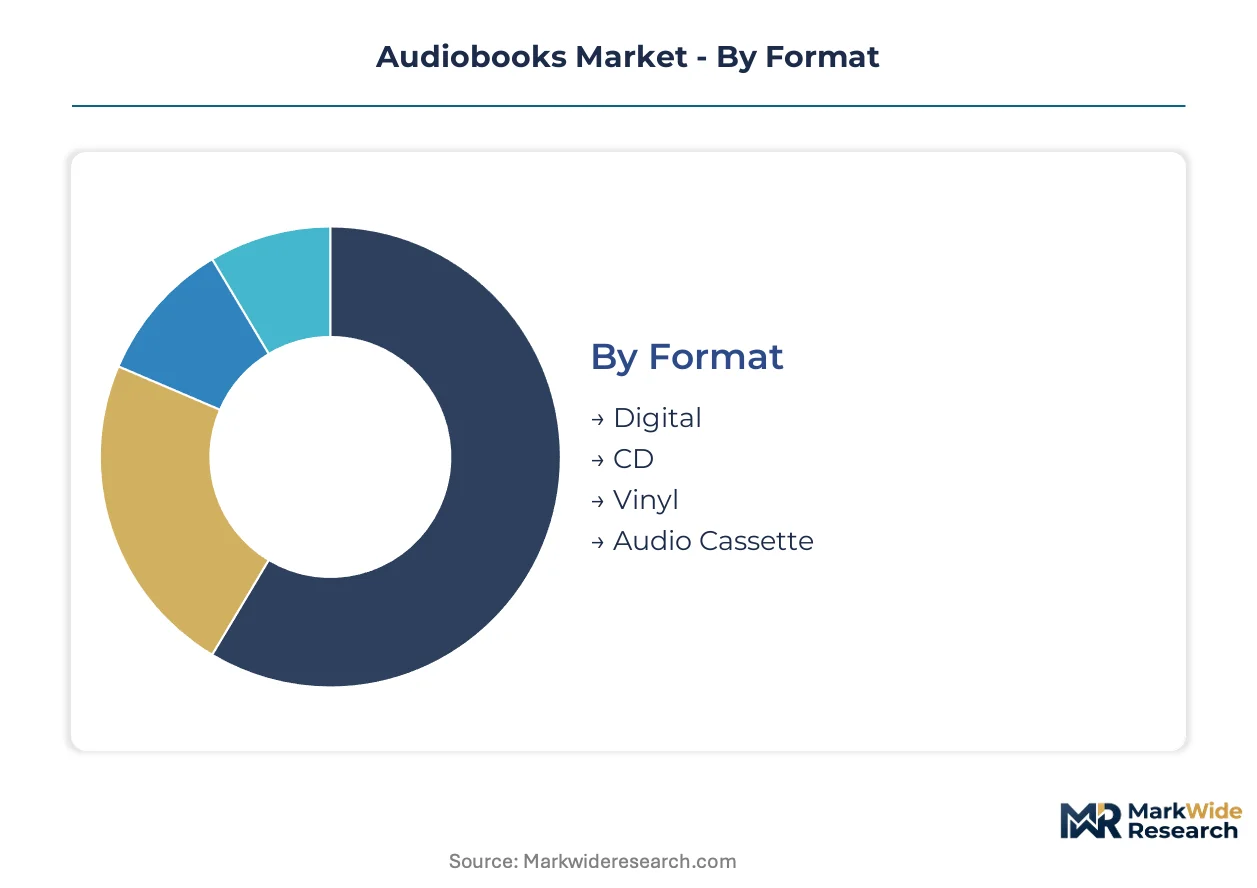
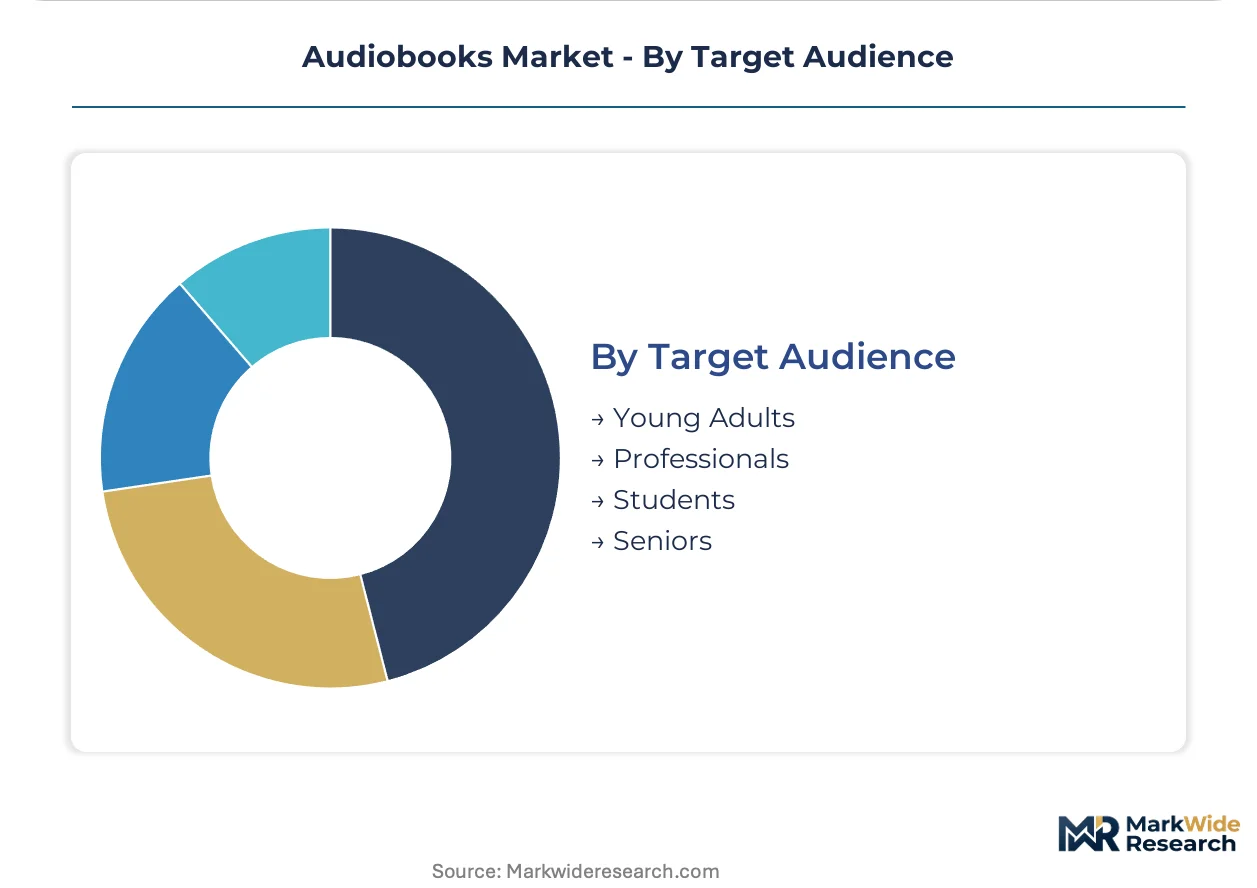
Segmentation in the audiobooks market reveals how consumption patterns fragment across technical formats, content genres, distribution channels, and demographic cohorts. Each dimension carries distinct margin profiles and upgrade dynamics that reshape platform investment priorities.
Format:
Upgrade cycles in audiobook formats compress as cloud infrastructure matures and legacy physical media depreciates.
- Digital:Compressed audio files delivered through MP3, AAC, or DRM-protected formats enable instant streaming and offline caching across smartphones and connected vehicles. Commuter professionals in the United States drive attach rates for cloud-delivered titles, with sleep-timer features and variable playback speeds cementing daily habit formation.
- CD:Optical disc distribution persists among library systems and gift-market segments where physical ownership retains perceived value. Collector demographics and institutional procurement in Germany and Japan sustain residual manufacturing volumes despite terminal decline trajectory.
- Vinyl:Limited-edition spoken-word pressings serve niche audiophile segments seeking analog warmth for poetry and dramatic readings. Boutique labels in the United Kingdom and United States press small-batch titles for premium gift positioning.
- Audio Cassette:Magnetic tape formats survive in vintage automotive installations and retro-aesthetic subcultures. Independent publishers in Portland and Berlin exploit cassette nostalgia through limited-run literary fiction releases.
Digital sits at the top of the volume ranking, with vinyl climbing the fastest among format segments.
Genre:
Genre economics diverge sharply between repeat-listening non-fiction and one-pass fiction consumption.
- Fiction:Narrative storytelling spanning mystery, romance, science fiction, and literary categories dominates total listening hours through binge-consumption patterns. Young adults in the United States and United Kingdom propel subscription attach rates for serialized fantasy and thriller series.
- Non-Fiction:Biography, history, and business titles generate disproportionate per-user revenue through professional development use cases and repeat reference listening. Corporate learning budgets in the United States and Singapore normalize expense reimbursement for leadership and industry-specific titles.
- Self-Help:Personal improvement content targets commuter professionals seeking productivity optimization and wellness frameworks. Mobile-first platforms in India and Brazil localize mindfulness and career acceleration content for tier-two city expansion.
- Educational:Curriculum-aligned adaptations serve K-12 and higher education institutions through library licensing and direct institutional sales. State digital lending programs in California and Texas expand accessibility for visually impaired and dyslexic student populations.
Fiction commands the largest addressable audience, with educational titles expanding most quickly through institutional procurement channels.
Platform:
Platform choice determines discovery mechanics, pricing power, and subscriber lifetime value.
- Mobile Apps:Native iOS and Android applications dominate daily engagement through offline caching, variable speed controls, and personalized recommendation algorithms. Spotify and Audible compete for home-screen placement in the United States through exclusive original productions and bundled subscription economics.
- Streaming Services:Cloud-first delivery eliminates download friction and enables instant sampling across music-audiobook-podcast unified feeds. Young adults in the United Kingdom and Australia exhibit highest conversion rates from free-tier music subscribers to audiobook upsells.
- Audiobook Retailers:Transactional purchase models persist for frontlist titles and permanent library ownership outside subscription ecosystems. Apple Books and Google Play Books anchor this segment through integrated payment infrastructure and family sharing features.
- Libraries:Municipal and university systems license digital titles through OverDrive, hoopla, and similar platforms with per-checkout or simultaneous-use pricing. The United States leads penetration with city-funded programs in New York, Los Angeles, and Chicago normalizing cost-free access.
Mobile apps capture the steepest expansion trajectory, with streaming services gaining share fastest among younger demographics.
Target Audience:
Audience segmentation maps life-stage constraints to consumption contexts and willingness-to-pay.
- Young Adults:Digital-native listeners aged 18-34 exhibit highest platform switching rates and discovery-driven consumption through social media recommendation. TikTok and Instagram book communities in the United States and United Kingdom drive viral title momentum for fantasy and romance genres.
- Professionals:Time-constrained white-collar workers convert commute and exercise hours into non-fiction and self-help consumption. Subscription bundling with music services in London, San Francisco, and Singapore maximizes addressable minutes through seamless audio feed integration.
- Students:Educational and recreational listening concentrates in secondary and post-secondary populations with price sensitivity and multi-tasking study habits. Campus library partnerships in Ontario and New South Wales expand access through institutional licensing.
- Seniors:Vision-impaired and leisure-reading demographics favor human-narrated fiction and memoir through simplified app interfaces and customer support. Large-print publisher partnerships in Florida and Arizona retirement communities sustain dedicated outreach programs.
Professionals generate the highest per-user revenue, with young adults scaling fastest through viral discovery mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The audiobooks industry traces its commercial origins to the United States, where library cassette lending programs and commuter culture first established spoken-word audio as a mass-market format. Platform penetration and digital payment infrastructure matured earliest in North American and Western European markets, while mobile-first adoption now accelerates across South Asia and Southeast Asia.
United States
Commuter professionals in metropolitan corridors from Boston to Los Angeles drive subscription attach rates for bundled audio services, converting drive-time into consumption hours. The FCC's net neutrality frameworks reduce platform bandwidth costs and enable streaming-first business models that expand beyond download-dependent users. New York City anchors original production activity, with major publishers and voice actor talent pools concentrated in Manhattan and Brooklyn.
United Kingdom
Young adults exhibit highest conversion rates from free-tier music subscribers to audiobook upsells through unified streaming feeds. The Digital Services Act imposes algorithmic transparency and content moderation duties on cross-border platforms serving British consumers. London's creative sector hosts boutique spoken-word production houses and literary fiction audio specialists.
Germany
Collector demographics and institutional procurement sustain residual CD manufacturing volumes despite terminal decline trajectory. The country's collective management organizations influence licensing terms between publishers and audiobook distributors operating across EU markets. Berlin's independent publisher ecosystem experiments with limited-run cassette nostalgia releases for retro-aesthetic subcultures.
India
Tier-two city consumers in Maharashtra and Tamil Nadu present white-space opportunities for mobile-first platforms targeting Hindi, Marathi, and Tamil content gaps. TRAI's data pricing regulations shape streaming economics for price-sensitive audiences on limited bandwidth. Bangalore's technology sector supplies neural text-to-speech engines that compress production timelines for vernacular backlist titles.
Japan
Corporate learning budgets normalize expense reimbursement for leadership and industry-specific non-fiction titles among white-collar professionals. METI's digital content promotion policies support platform infrastructure investment for cross-border distribution. Tokyo's voice acting industry supplies premium narrator talent for exclusive original productions targeting East Asian markets.
Audiobooks Market Key Industry Players
Premium-margin players sit above commodity-margin players across content exclusivity and production quality tiers. The market structure concentrates around bundled streaming platforms, dedicated audiobook specialists, and emerging-market mobile-first entrants. Three archetypes dominate: streaming incumbents leveraging music infrastructure, pure-play audiobook platforms with original production capabilities, and regional challengers optimizing for local language content. Competitive moves center on exclusive content licensing and AI-driven production cost compression.
Within the streaming incumbent tier, Spotify exemplifies cross-promotion leverage through unified audio feeds that train algorithmic discovery. Audible anchors the premium original production segment through exclusive partnerships with major trade publishers. Kuku FM represents the emerging-market challenger archetype, occupying a position focused on hyper-local language content and aggressive mobile-first pricing for tier-two city expansion.
| Leading Market Players |
|---|
| Spotify |
| Nextory |
| RBmedia |
| Audioteka |
| Audible |
| Kuku FM |
| Apple |
| Storytel |
| Others |
Cost & Logistics Intelligence
Commuter professionals in metropolitan United States corridors anchor demand concentration for subscription-bundled audio services, locking platforms into recurring-revenue models that trade per-title premiums for lifetime value capture.
Pricing Analysis
Subscription bundling across music, podcasts, and audiobooks stratifies into three tiers: premium unlimited access, standard limited-title plans, and economy ad-supported entry points. Price differentiation hinges on exclusive content depth and narrator quality grade, with human-narrated originals commanding substantial premiums over AI-synthesized backlist. Pricing pressure stems from algorithmic narration compressing production costs and flooding lower tiers with substitute supply. Students and cost-sensitive library borrowers exhibit highest price sensitivity; corporate learning budgets show lowest sensitivity due to expense reimbursement normalization.
Supply Chain Analysis
Narrator talent pools rest on concentrated geographic hubs in the United States, United Kingdom, and Japan, with Los Angeles, London, and Tokyo anchoring premium voice-actor representation. Raw material dependencies include studio recording infrastructure, audio engineering software licenses, and cloud storage bandwidth for streaming delivery. Supply chain risk centers on single-source vulnerability for exclusive narrator contracts that inflate original production costs. Distribution runs through platform-owned mobile applications and third-party library licensing networks that aggregate consumer access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The audiobooks market operates as a regulatory compounder, with the EU Digital Services Act's content moderation obligations creating compliance barriers that favor capitalized incumbents over under-resourced challengers.
For Market Incumbents: Acquire exclusive narrator talent rosters to lock premium production capacity against synthetic voice erosion. Anchor defensive positioning through backward integration into original content studios in New York and London, while absorbing EU regulatory overhead through localized trust-and-safety teams that smaller rivals cannot replicate. For New Entrants and Emerging Players: Neural text-to-speech engines offer a technology-first wedge for vernacular backlist digitization in underserved Indian tier-two cities. Target Hindi, Tamil, and Marathi content gaps with data-optimized streaming architectures, penetrating through aggressive mobile-first pricing that undercuts human-narrated premium tiers. For Investors and Strategic Acquirers: Streaming platforms with music infrastructure are the most active acquirer in this space, seeking audiobook capabilities to complete unified audio feed strategies. Long-term viability favors targets with vernacular content libraries and AI production pipelines over pure human-narrated backlist. Watch narrator guild collective bargaining outcomes as the critical inflection signal for synthetic voice substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Original Production | Audible's Manhattan studios lock premium narrator talent against Spotify's bundling economics. |
| AI Narration Scale-Up | Google and Amazon engines compress backlist turnaround from weeks to hours for price-sensitive segments. |
| Vernacular Content Expansion | Kuku FM's Hindi and Tamil investments capture tier-two city growth ahead of multinational localization. |
| Library Licensing Partnership | OverDrive's municipal contracts in Chicago and Los Angeles normalize cost-free access for subscriber acquisition. |
| Regulatory Compliance Infrastructure | EU Digital Services Act obligations favor established distributors with legal teams in Brussels and Berlin. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with audiobook platform executives, publishing rights directors, voice actor guild representatives, and library systems procurement officers with secondary validation against SEC filings, App Annie engagement metrics, and FCC regulatory dockets. Bottom-up title-level production cost modeling and top-down streaming revenue estimates triangulated through cross-reference.
Segment-weighting across format, genre, platform, and audience dimensions structured the analytical framework over the projection horizon. CAGRs derived from trend-line extrapolation of subscriber attach rates and per-user revenue trajectories, with AI narration adoption curves and bundling penetration ratios as industry-specific forecast inputs.
The model holds under stable regulatory enforcement and platform competition intensity; deviation in narrator collective bargaining outcomes or EU content moderation interpretation would shift production cost assumptions materially. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Radio and Audio Media
Podcast Hosting Services Market
Radio and Audio Media
Microphone Market
Radio and Audio Media
Internet Radio Market
Radio and Audio Media
Digital Audio Market
Radio and Audio Media
Audio Mixing Console Market
Radio and Audio Media
Global 3D Audio Market
Radio and Audio Media
FM Transmitters Market
Radio and Audio Media
Podcast Market
Radio and Audio Media
Traditional Radio Advertising Market
Radio and Audio Media
Podcasting Market
Radio and Audio Media
Latin America Soundbar Market
Radio and Audio Media
Global Professional Audio Market
Radio and Audio Media
Podcast Advertising Market
Radio and Audio Media
Voice Over New Radio Market
Radio and Audio Media
Radio Advertising Market