
 UK Pet Diet Market | 2026-2036
UK Pet Diet Market Size, Share, and Industry Trends Forecast 2026-2036
UK Pet Diet Market Insights
The capital-intensity divergence between co-manufacturers and brand owners is reorganizing competitive dynamics across the UK Pet Diet Market. Mars Incorporated leverages its captive supply chain to sustain margin control over premium dry food production. Nestle Purina competes through R&D intensity in hypoallergenic formulations. GA Pet Food Partners anchors its position by controlling contract manufacturing scale for private-label entrants.
UK Pet Diet encompasses nutritionally formulated feeds for companion animals, typically comprising specified protein meals, carbohydrates, fats, vitamins, and minerals processed through extrusion, canning, or cold-pressing methods to meet FEDIAF nutritional guidelines. Dry Food occupies the largest volume share due to shelf stability and cost efficiency in mass retail distribution. Protein-Focused ingredient types are expanding fastest as pet humanization trends redirect owner spending toward fresh meat inclusion rates. Wet Food in pouch formats commands disproportionate margin pools through convenience positioning and portion control.
The Food Standards Agency enforces compositional standards and labeling requirements under EU-derived retained law, while Defra administers animal by-product regulations affecting raw material sourcing for pet food manufacturers. Trading Standards officers at local authority level conduct market surveillance and enforce the Animal Feed Regulations across England, Scotland, Wales, and Northern Ireland. Veterinary channel compliance with the RCVS Code of Professional Conduct shapes prescription diet dispensing and influences owner trust in clinical nutrition recommendations. Stakeholders must monitor divergence between UK-specific labeling evolution and EU regulatory alignment post-Brexit to anticipate compliance cost trajectories and reformulation timelines.
Market Dynamics
Capital-intensity divergence between co-manufacturers and brand owners is reorganizing competitive dynamics across the UK Pet Diet Market. Mars Incorporated leverages its captive supply chain to sustain margin control over premium dry food production. Nestle Purina competes through R&D intensity in hypoallergenic formulations. GA Pet Food Partners anchors its position by controlling contract manufacturing scale for private-label entrants.
Growth Catalysts
- FSA Labeling Enforcement:Stricter compositional standards under retained EU law are accelerating premiumization as manufacturers reformulate to meet transparency mandates. This regulatory pressure concentrates demand in grain-free and protein-focused formulations.
- Pet Humanization in Urban England:Owner spending patterns in London, Manchester, and Birmingham are redirecting toward fresh meat inclusion rates. Urban centers now drive disproportionate volume in wet food pouch formats.
- Cold-Pressing Technology:Lower-temperature processing methods are preserving nutritional integrity in premium segments. This production shift enables manufacturers to command margin premiums through quality differentiation.
Market Restraints
- Raw Material Sourcing Friction:Defra's animal by-product regulations constrain supply flexibility for manufacturers dependent on specific protein meals. Sourcing compliance adds timeline risk to reformulation cycles.
- Co-Manufacturer Concentration:Contract manufacturing capacity clusters with limited UK-based extrusion specialists. Private-label entrants face queue constraints at GA Pet Food Partners and comparable facilities.
- Veterinary Channel Gatekeeping:RCVS Code of Professional Conduct compliance requirements limit direct-to-consumer prescription diet access. This structural barrier protects incumbent clinical nutrition brands.
Strategic Opportunities
- Scotland and Wales Underpenetration:Rural veterinary networks and independent pet retailers outside England's urban corridor represent distribution white space. Regional expansion targets owner segments with lower premium product exposure.
- Subscription Direct-to-Consumer Models:Portion-controlled fresh meal delivery is bypassing traditional retail shelf competition. This channel innovation captures lifetime value through recurring revenue structures.
- Brexit Regulatory Divergence:UK-specific labeling evolution creates first-mover advantage for domestic reformulation. Manufacturers aligning early with FSA trajectories avoid EU alignment compliance costs.
Industry Challenges
- Formulation Talent Scarcity:Veterinary nutritionists and FEDIAF guideline specialists command premium compensation. Recruitment friction delays NPD timelines for mid-tier manufacturers.
- Cold Chain Capex Requirements:Fresh and raw diet expansion demands refrigerated distribution infrastructure. Capital deployment for temperature-controlled logistics strains balance sheets.
- Post-Brexit Certification Complexity:Diverging UK-EU nutritional adequacy approvals create dual-track testing burdens. Export-oriented manufacturers face extended timeline risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Pet Diet Market |
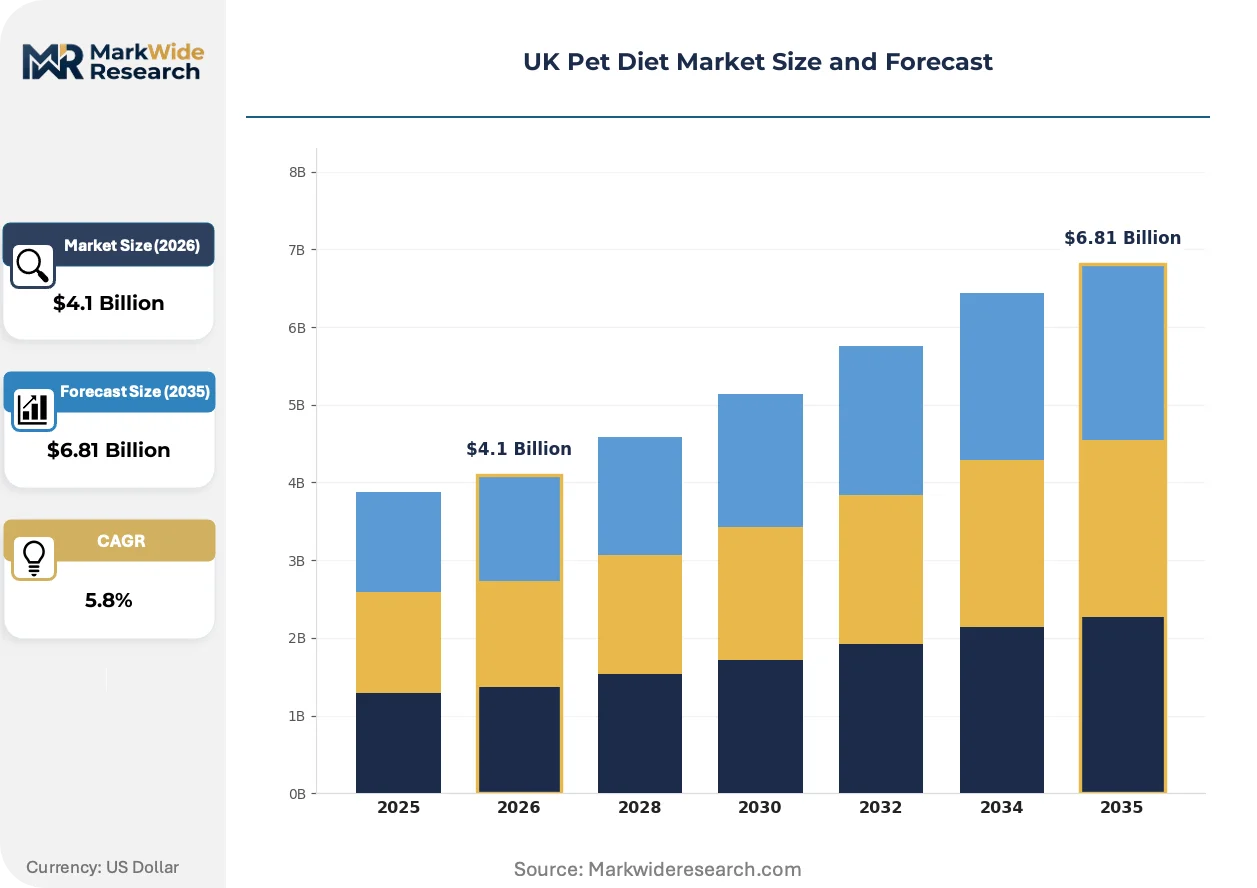
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Raw Food Ingredient Type: Organic, Grain-Free, Protein-Focused, Hypoallergenic Packaging Type: Bags, Cans, Pouches, Bulk End User: Dog Owners, Cat Owners, Pet Stores, Veterinarians |
| Companies Covered | GA Pet Food Partners, Mars Incorporated, Nestle Purina, Hill's Pet Nutrition Inc., Inspired Pet Nutrition, Butcher's Pet Care, Pets Choice, Diamond Pet Foods, General Mills Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Pet Diet Market Trends and Innovations
Cold-pressed production methods are displacing conventional extrusion in premium positioning. FSA enforcement trajectories are tightening compositional transparency requirements. Owner purchasing behavior is fragmenting across convenience-oriented channels and subscription formats.
High-pressure processing technology is displacing thermal sterilization in wet food manufacturing. Premium brand owners in England's urban centers are adopting these systems to preserve protein bioavailability. This shift is displacing shelf-stable canning economics with shorter-dated, refrigerated alternatives that command retail price premiums.
The Food Standards Agency's evolving labeling standards under retained EU law are mandating clearer meat content declarations. Manufacturers face reformulation costs to meet percentage threshold requirements for "with meat" claims. Dry food producers targeting supermarket distribution are most affected, accelerating recipe simplification to reduce compliance complexity.
Subscription-based fresh meal delivery is fragmenting traditional retail dependence among urban dog owners. Independent veterinary practices and specialty pet retailers are losing traffic to direct-to-consumer platforms offering portion customization. This channel shift is most visible in Greater London and the Southeast, where logistics density enables viable cold-chain economics.
UK Pet Diet Market Segmentation
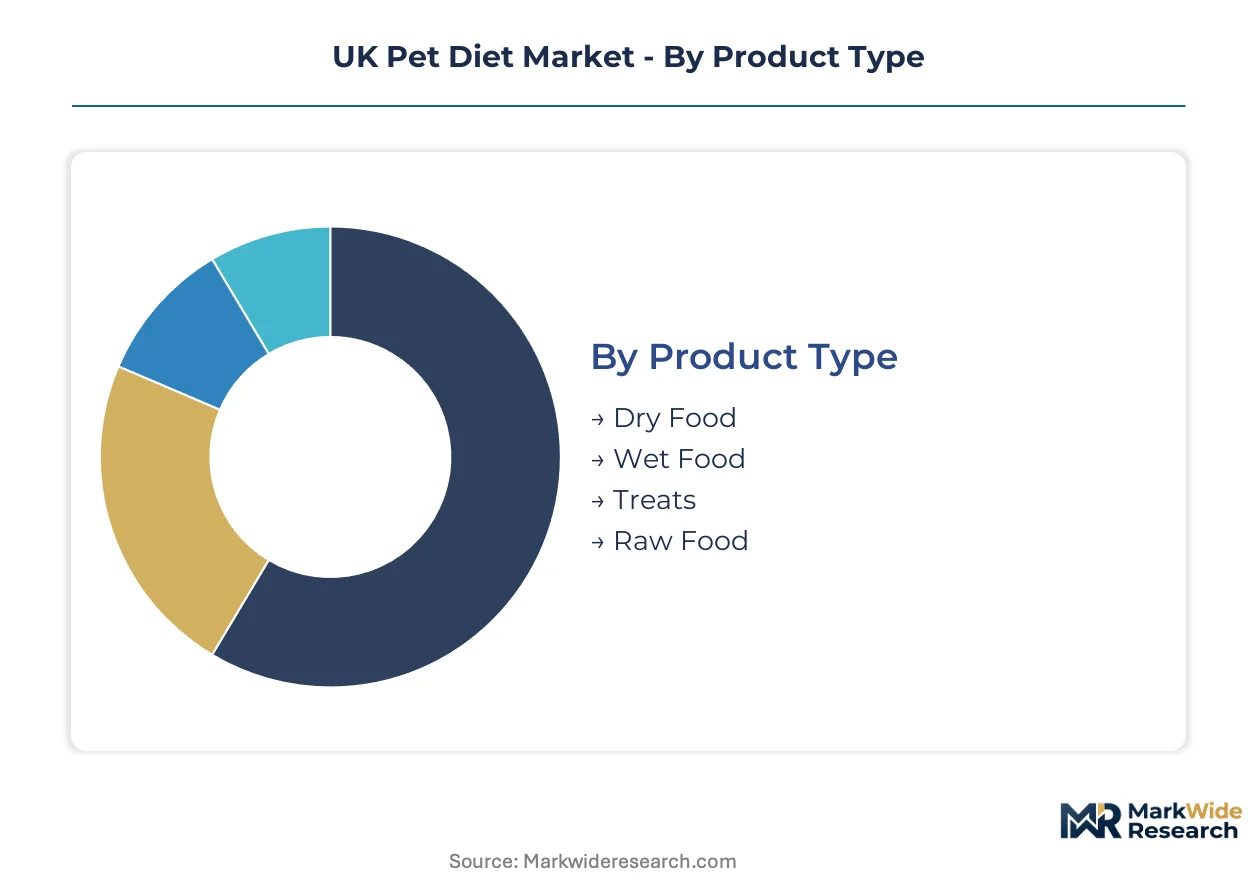
Segmentation in the UK Pet Diet Market reveals how regulatory pressure and channel fragmentation are splitting demand across incompatible production systems. Manufacturers must align capital deployment with specific segment economics rather than pursuing undifferentiated scale.
Product Type:
Substitute pressure runs strongest where shelf-stable formats compete against fresh alternatives, forcing incumbents to defend position through convenience claims or cold-chain investment.
- Dry Food:Extruded kibble formulations deliver shelf stability and cost efficiency in supermarket distribution. Demand concentrates in England's urban centers where Mars Incorporated's captive supply chain sustains margin control over premium positioning despite FSA labeling reformulation costs.
- Wet Food:High-moisture formulations in can or pouch formats command disproportionate margin pools through palatability and portion control. London, Manchester, and Birmingham drive disproportionate volume as pet humanization redirects owner spending toward fresh meat inclusion rates.
- Treats:Supplementary nutrition and training rewards occupy impulse-purchase positioning in specialty retail and veterinary channels.
- Raw Food:Unprocessed or minimally processed meat-based diets require frozen distribution infrastructure and face Defra animal by-product compliance constraints.
Dry Food retains volume leadership; Raw Food holds the steepest expansion curve.
Ingredient Type:
Cost tier stratification separates premium-positioned formulations from commodity alternatives, with regulatory transparency mandates accelerating migration toward higher-declaration categories.
- Organic:Certified ingredient sourcing with restricted pesticide and synthetic additive use. Production scale limits concentrate with specialist contract manufacturers.
- Grain-Free:Carbohydrate exclusion formulations targeting digestive sensitivity concerns. Scotland and Wales rural veterinary networks represent underpenetrated distribution white space for premium positioning.
- Protein-Focused:Elevated fresh meat inclusion rates with specified amino acid profiles. Urban dog owners in Greater London and the Southeast are fragmenting purchasing across subscription direct-to-consumer platforms that bypass traditional retail shelf competition.
- Hypoallergenic:Limited-ingredient diets for veterinary-diagnosed food sensitivities. Nestle Purina competes through R&D intensity in this segment, though RCVS Code of Professional Conduct compliance limits direct-to-consumer prescription access.
Protein-Focused formulations are gaining share fastest; Hypoallergenic maintains the tightest supply concentration with veterinary channel gatekeeping.
Packaging Type:
Volume-to-margin tradeoffs determine competitive viability, with single-serve convenience formats capturing urban premium spend against bulk efficiency in multi-pet households.
- Bags:Flexible packaging for dry food with varying barrier properties. Mass retail distribution in England's supermarket chains sustains volume throughput.
- Cans:Metal-container wet food with thermal sterilization economics. Shelf-stable positioning faces displacement from high-pressure processing alternatives in premium segments.
- Pouches:Flexible single-serve wet food formats. Portion control convenience commands retail price premiums in urban convenience-oriented channels.
- Bulk:Large-format packaging for multi-pet households and commercial kennels. Price-sensitive demand concentrates outside premium-positioned urban corridors.
Bags retain volume leadership; Pouches hold the steepest expansion curve.
End User:
Customer type dictates channel economics and regulatory exposure, with professional intermediaries imposing compliance burdens that protect incumbent structures.
- Dog Owners:Primary demand volume with humanization-driven premium migration. Subscription fresh meal delivery captures lifetime value through recurring revenue structures in logistics-dense Southeast England.
- Cat Owners:Smaller volume base with distinct palatability and nutritional requirements. Wet food preference runs stronger than canine segments.
- Pet Stores:Specialty retail intermediaries with independent and chain formats. Traffic fragmentation to direct-to-consumer platforms strains shelf-space economics.
- Veterinarians:Prescription diet dispensing governed by RCVS Code of Professional Conduct. Clinical nutrition recommendations influence owner trust and protect incumbent brands from price competition.
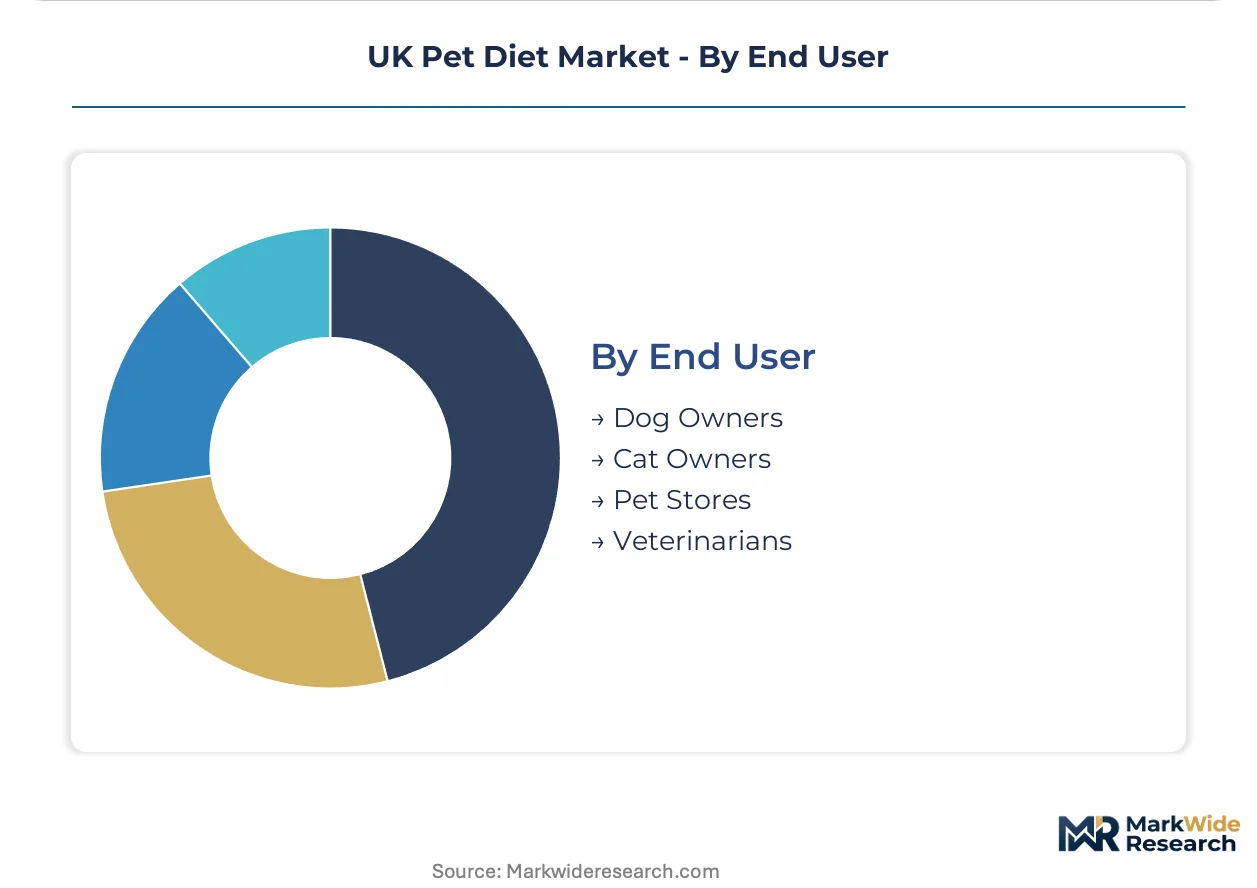
Dog Owners retain volume leadership; Subscription-engaged urban dog owners hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
England commands premium pricing power over Scotland and Wales, where rural veterinary networks and independent retailers lag in protein-focused product penetration. This asymmetry shapes manufacturer distribution priorities and margin capture across the UK's constituent nations.
England
Urban dog owners in London, Manchester, and Birmingham drive disproportionate volume in wet food pouch formats and subscription fresh meal delivery. Trading Standards officers enforce the Animal Feed Regulations with particular intensity in England's supermarket chains, accelerating FSA-mandated labeling compliance. The Greater London corridor anchors cold-chain logistics density that enables viable refrigerated distribution economics for raw and fresh diet entrants.
Scotland
Rural veterinary networks and independent pet retailers outside England's urban corridor represent underpenetrated distribution white space for grain-free and protein-focused formulations. The country's national veterinary regulator aligns with RCVS standards, preserving prescription diet gatekeeping that protects incumbent clinical nutrition brands. Edinburgh and Glasgow concentrate specialty retail traffic, though premium product exposure remains lower than comparable English cities.
Wales
Multi-pet households and commercial kennels sustain bulk-format demand, constraining margin pools relative to portion-controlled urban markets. Defra-administered animal by-product regulations apply with equivalent force, though local authority Trading Standards capacity varies across rural counties. Cardiff and Newport emerging as logistics nodes for cross-border distribution into western England.
Northern Ireland
Post-Brexit certification complexity creates dual-track testing burdens for manufacturers serving both UK and Republic of Ireland markets. The region's veterinary channel maintains RCVS Code compliance while navigating distinct EU alignment pressures. Belfast anchors distribution infrastructure, though cold-chain capex deployment lags mainland UK density.
UK Pet Diet Market Competitive Landscape
Concentration sits with multinational brand owners controlling captive supply chains and R&D pipelines. Mars Incorporated and Nestle Purina anchor the premium dry and hypoallergenic segments respectively, while GA Pet Food Partners dominates contract manufacturing scale for private-label entrants. Three archetypes define competitive positioning: vertically integrated multinationals with in-house extrusion capacity, specialist co-manufacturers serving private-label demand, and independent brand owners outsourcing production. Dominant competitive moves include backward integration into protein meal sourcing and strategic partnerships with veterinary channel gatekeepers.
Within the multinational tier, Mars Incorporated and Nestle Purina exemplify divergent margin defense strategies. Mars leverages captive supply chain control over premium dry food production, while Nestle Purina competes through formulation intensity in veterinary-recommended segments. GA Pet Food Partners anchors the contract manufacturing archetype, controlling extrusion scale that private-label entrants queue to access. These three entities collectively represent the structural poles around which mid-tier manufacturers and emerging subscription brands must position.
| Leading Market Players |
|---|
| GA Pet Food Partners |
| Mars Incorporated |
| Nestle Purina |
| Hill's Pet Nutrition Inc. |
| Inspired Pet Nutrition |
| Butcher's Pet Care |
| Pets Choice |
| Diamond Pet Foods |
| General Mills Inc. |
| Others |
Pricing and Supply Chain Analysis
High-pressure processing adoption in wet food manufacturing is displacing conventional thermal sterilization economics, simultaneously shifting production geography toward England's urban cold-chain corridors and compressing margin structures for shelf-stable canning operations. This substitution dynamic concentrates premium pricing power with logistics-dense operators while forcing commodity-format producers toward volume defense.
Pricing Analysis
The customization-premium spread between subscription-configured fresh meal plans and standard retail dry food separates urban dog owners from price-sensitive multi-pet households. Three-tier pricing structure across premium, standard, and economy levels dominates, with protein-inclusion rates and FSA labeling compliance tiers as primary differentiation drivers. Pricing pressure stems from cold-chain capex requirements as fresh format entrants absorb logistics costs to capture recurring revenue. Multi-pet households in Wales and bulk-format buyers exhibit highest price sensitivity, while subscription-engaged urban owners in Greater London show lowest elasticity.
Supply Chain Analysis
Strategic stockpile preferences dominate raw material procurement as Defra's animal by-product regulations constrain just-in-time flexibility for protein meal sourcing. Supply concentrates in UK-based extrusion facilities, with secondary dependencies on Irish and Dutch rendering operations for specialized protein meals. Single-source vulnerability sits with GA Pet Food Partners' contract manufacturing queue constraints. Distribution runs through England's supermarket chains and veterinary channels, with emerging cold-chain infrastructure enabling direct-to-consumer subscription bypass.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary nutritionist talent scarcity constrains NPD velocity for mid-tier manufacturers, creating competitive moats for incumbents with captive formulation expertise and opening acquisition premiums for specialist consultancies.
For Market Incumbents: Compound captive supply chain advantages through backward integration into protein meal rendering capacity, insulating margin control from Defra sourcing constraints. Expand cold-press extrusion footprint in Greater London logistics corridors to defend premium positioning against subscription fresh meal entrants. Prioritize FSA labeling compliance pre-emption to capture reformulation timeline advantages before regulatory divergence accelerates. For New Entrants and Emerging Players: FEDIAF nutritional adequacy certification fast-track through specialist consultancy partnerships enables veterinary channel credibility without multi-year talent recruitment cycles. Target Scotland and Wales rural veterinary networks as underpenetrated white space with lower incumbent saturation. Deploy direct-to-consumer subscription models with portion customization to bypass supermarket shelf-space economics and capture lifetime value through recurring structures. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed contract manufacturers holding extrusion scale but lacking brand equity, presenting rollup opportunities for platform consolidation. Five-to-ten-year viability favors operators with dual UK-EU regulatory compliance capabilities post-Brexit divergence. Monitor FSA labeling enforcement intensity as inflection signal for reformulation cost acceleration and margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Enables refrigerated distribution economics for raw and fresh diet segments in England's urban corridors. |
| Backward Integration into Protein Rendering | Captures margin control and insulates supply from Defra animal by-product regulatory constraints. |
| FSA Pre-Compliance Reformulation | Accelerates timeline advantage before UK-EU labeling divergence creates dual-track testing burdens. |
| Veterinary Channel Partnership Programs | Secures RCVS Code-compliant prescription diet access against direct-to-consumer competitive threats. |
| Subscription Platform Technology Investment | Captures recurring revenue structures and bypasses traditional retail shelf-space competition. |
Research Methodology
Desk research of FEDIAF nutritional guidelines, FSA regulatory filings, and Defra animal by-product administration records preceded structured interviews with veterinary nutritionists, contract manufacturing operations directors, supermarket category buyers, and independent pet retailer owners. Primary fieldwork combined with secondary validation through Trading Standards enforcement data and cold-chain logistics provider disclosures. Bottom-up segment sizing triangulated against top-down market aggregation across product type, ingredient category, packaging format, and end-user archetype dimensions.
Variance decomposition across volume and value drivers informed analytical framework construction over the projection horizon. Segmentation dimensions modeled include product format, protein inclusion tier, packaging convenience level, channel structure, and geographic urbanization density. CAGRs derived from trend extrapolation of protein-focused formulation adoption curves and subscription channel penetration rates, cross-referenced against regulatory compliance cost trajectories and cold-chain infrastructure deployment schedules.
Decision-makers should treat outputs as directional under base assumptions of continued FSA enforcement intensity and stable Defra regulatory administration; material deviation would warrant model refresh. Specific risk factors include post-Brexit certification complexity escalation, raw material sourcing friction from animal by-product rule changes, and veterinary channel gatekeeping relaxation. Revision becomes warranted when cold-chain logistics cost inflation crosses thresholds that reverse subscription model unit economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Waste Removal Services Market
Pet Care Products
Dog Dental Chews Market
Pet Care Products
UAE Pet Food Market
Pet Care Products
Europe Organic Pet Food for Cats and Dogs Market
Pet Care Products
Pet Furniture Market
Pet Care Products
Japan Pet Clothing Market
Pet Care Products
Pet Pens Market
Pet Care Products
Pet Lodging Market
Pet Care Products
Canada Pet Boarding Market
Pet Care Products
Frozen and Freeze-Dried Pet Food Market
Pet Care Products
Pet Cups Market
Pet Care Products
Pet Water Dispenser Market
Pet Care Products
Smart Pet Collar Market
Pet Care Products
Outdoor Dog Bed Market
Pet Care Products
Dog Collars Market
Pet Care Products
Global Pet Companion Robots Market