
 Herbal Pet Shampoo Market | 2026-2036
Herbal Pet Shampoo Market Size, Share, and Industry Trends Forecast 2026-2036
Herbal Pet Shampoo Market Analysis
The gap between premium botanical formulations and mass-market synthetic alternatives is realigning procurement strategies across pet care retail. Himalaya Wellness Company leverages its Ayurvedic ingredient sourcing network to anchor supply security for neem and tulsi extracts. SynergyLabs competes through veterinary channel partnerships that sustain professional endorsement pipelines. 4-Legger differentiates via USDA Organic certification, a positioning that commands shelf placement in premium pet boutiques.
Herbal pet shampoo denotes a surfactant-based cleansing preparation incorporating plant-derived active compounds—typically saponins, essential oils, or glycosides—at concentrations sufficient to confer antimicrobial, anti-inflammatory, or coat-conditioning properties without synthetic parabens or sulfates. These formulations serve the companion animal hygiene sector where owner sensitivity to chemical residues intersects with veterinary dermatology protocols for atopic or reactive skin conditions. Liquid shampoo retains dominant volume share due to established dilution economics and dispenser compatibility across grooming operations, yet solid shampoo bars capture fastest growth as zero-waste retail mandates reshape packaging specifications in European and North American pet specialty chains. The aloe vera ingredient cluster leads absolute demand for its mucopolysaccharide content that demonstrably reduces transepidermal water loss in canine skin barrier studies.
The US FDA Center for Veterinary Medicine maintains oversight of topical pet care claims, while EPA regulations govern pesticidal ingredient thresholds in tea tree oil formulations that carry acaricidal positioning. REACH registration requirements in the European Union constrain essential oil import volumes, directly elevating compliance costs for chamomile and lavender supply chains. Stakeholders must monitor evolving state-level green chemistry legislation in California and New York that threatens to classify certain botanical preservatives as candidate chemicals under extended producer responsibility frameworks.
Market Dynamics
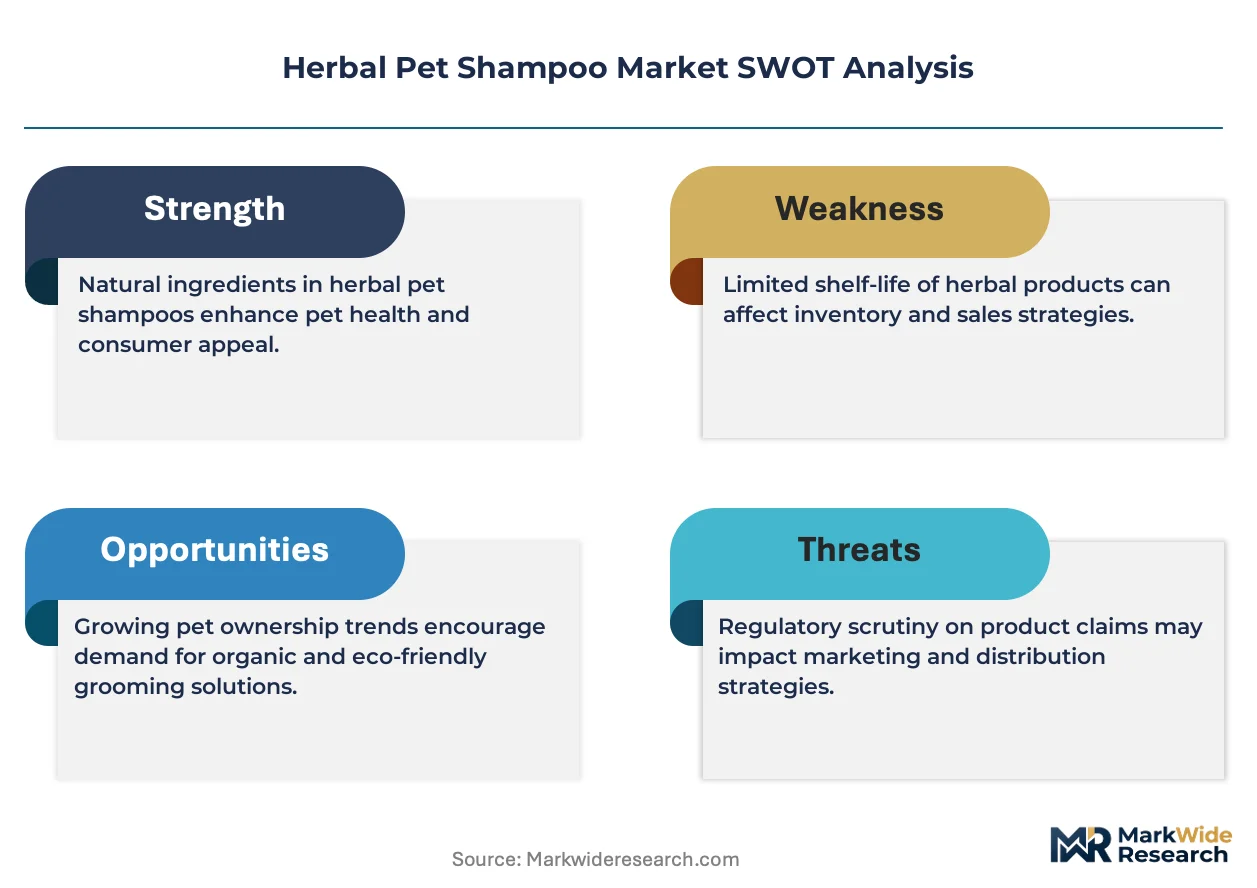
REACH registration requirements in the European Union constrain essential oil import volumes, elevating compliance costs for chamomile and lavender supply chains while compressing margins for mid-tier formulators.
Growth Catalysts
- EU Cosmetics Regulation:Mandatory safety assessments for cosmetic products sold in Europe push manufacturers toward certified organic supply chains with documented traceability.
- Veterinary dermatology protocols:Grooming salons and veterinary clinics now specify plant-based formulations for sensitive-skin treatments, creating professional endorsement pipelines that sustain premium pricing.
- German pet specialty retail:Concentrated demand in Germany commands premium shelf space for botanical pet care lines, anchoring volume commitments from ingredient suppliers.
Market Restraints
- Essential oil price volatility:Climate-sensitive harvests of tea tree and neem in Australia and India generate input cost instability that compresses formulation margins.
- REACH compliance friction:Registration requirements for botanical actives create documentation burdens that exclude smaller suppliers from European market access.
- Synthetic surfactant substitution:Mass-market pet owners continue defaulting to sulfate-based alternatives due to lower unit costs and established dispenser compatibility.
Strategic Opportunities
- Zero-waste retail mandates:Solid shampoo bars capture shelf space in European and North American pet specialty chains as packaging specifications tighten.
- USDA Organic certification:Premium pet boutiques prioritize certified organic positioning, creating differentiation white space for compliant formulators.
- Ayurvedic ingredient networks:Established sourcing infrastructure for neem and tulsi extracts enables supply security advantages for integrated wellness companies.
Industry Challenges
- Formulation chemist scarcity:Botanical preservation science requires specialized expertise in natural antimicrobial systems that outpaces current training pipelines.
- Multi-jurisdiction labeling:Divergent FDA Center for Veterinary Medicine and EPA claim requirements force redundant testing cycles for acaricidal positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herbal Pet Shampoo Market |
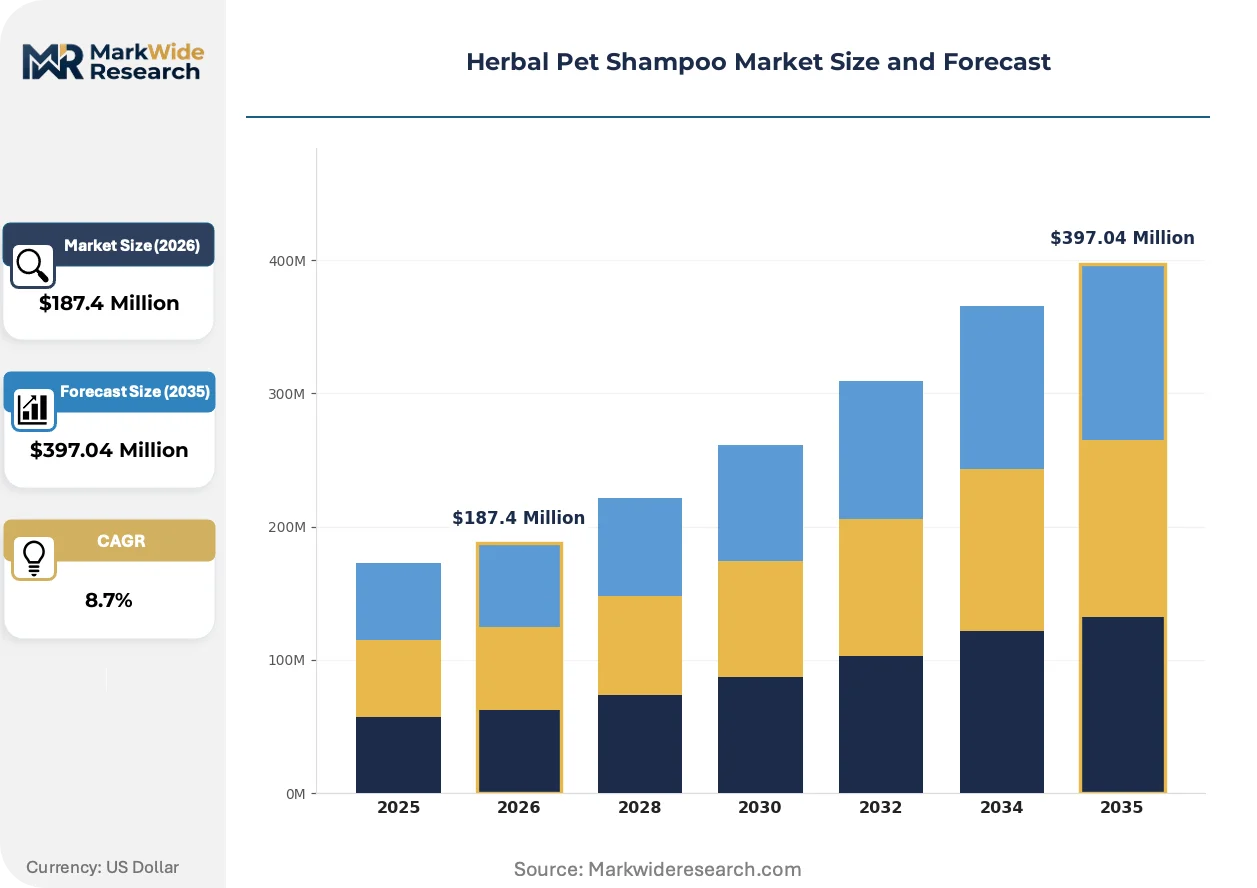
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Shampoo, Solid Shampoo Bar, Foam Shampoo, Concentrated Shampoo Ingredients: Aloe Vera, Chamomile, Lavender Oil, Tea Tree Oil Animal Type: Dogs, Cats, Horses, Small Animals Distribution Channel: Online Retail, Pet Stores, Veterinary Clinics, Supermarkets |
| Companies Covered | Himalaya Wellness Company, SynergyLabs, 4-Legger, Earthwhile Endeavors Inc., Beaphar, Burt's Bees, Petkin Inc., Bayer AG, World for Pets, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herbal Pet Shampoo Market Emerging Trajectories
Formulation science and packaging specifications are converging to reshape competitive positioning in botanical pet care. Three developments merit particular attention.
Solid shampoo bar technology is expanding into mainstream grooming operations. These concentrated formats eliminate plastic packaging while reducing shipping volumes. Professional groomers in Scandinavian markets are adopting bars at accelerating rates. The technology is expanding into liquid-dominant segments by enabling zero-waste retail compliance without performance compromise.
California's green chemistry legislation is reclassifying botanical preservatives under extended producer responsibility frameworks. The state's Department of Toxic Substances Control evaluates candidate chemicals for environmental fate testing. Manufacturers serving the California market are reformulating with exempt preservative systems. This regulatory pressure is propagating to New York and Washington state legislatures.
Certification-driven purchasing now dominates premium channel procurement decisions. Pet specialty buyers require documentation of organic supply chain integrity before shelf placement approval. Independent certification bodies verify ingredient provenance and processing standards. Germany and France exhibit the most pronounced certification premiums in retail pricing structures.
Herbal Pet Shampoo Market Segmentation
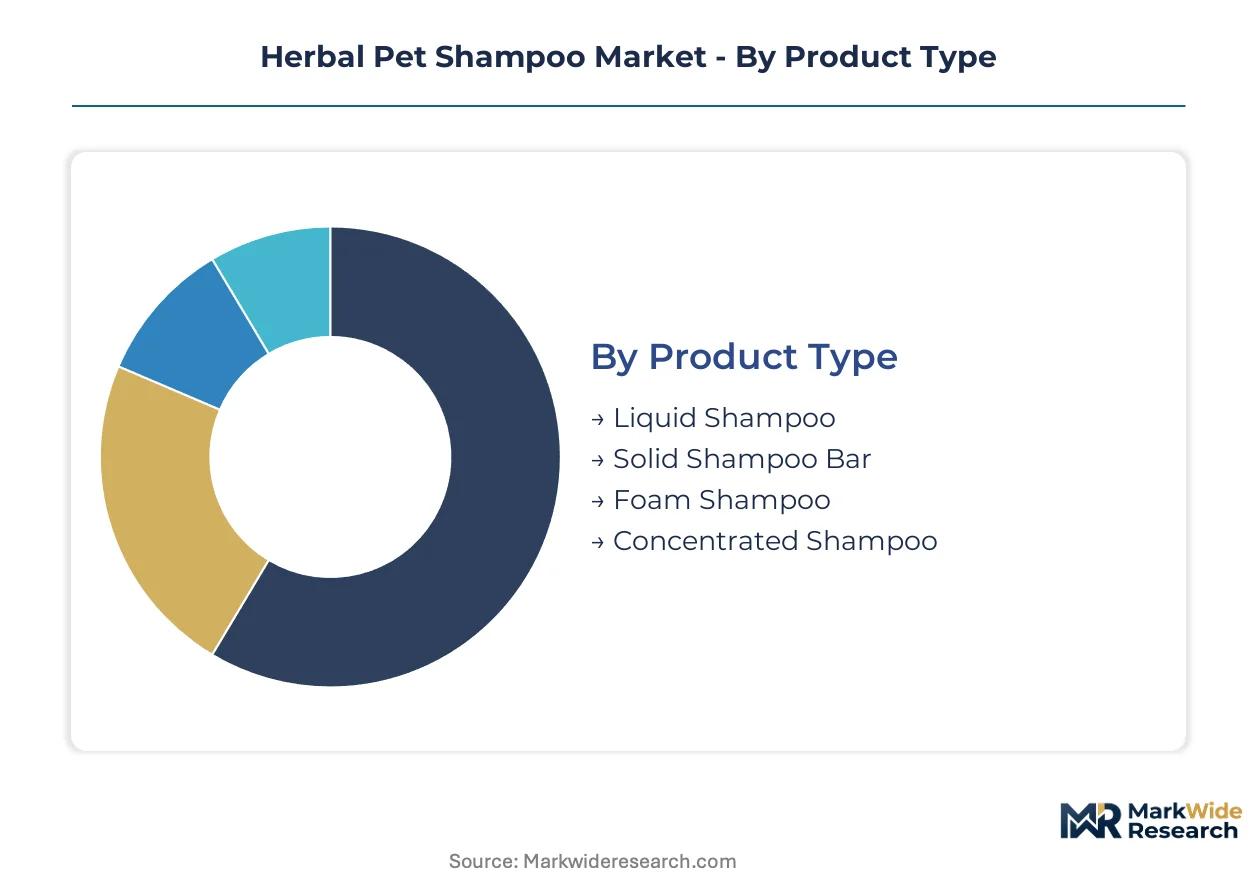
Herbal pet shampoo segmentation reflects divergent compliance burdens across formulation types and distribution channels. Veterinary clinics and premium retail channels impose distinct certification requirements that reshape manufacturing priorities.
Product Type:
Liquid shampoo formulations carry FDA Center for Veterinary Medicine oversight for antimicrobial claims, while solid bars face lighter documentation loads under EPA packaging regulations. REACH registration thresholds vary by concentration and delivery mechanism.
- Liquid Shampoo:Surfactant-based aqueous formulations incorporating plant-derived actives at concentrations suitable for dilution economics. Demand concentrates in professional grooming operations across Germany and the United States, where dispenser compatibility and established protocols sustain volume leadership despite higher synthetic surfactant competition.
- Solid Shampoo Bar:Concentrated anhydrous formats eliminating plastic packaging through saponified botanical bases. Scandinavian pet specialty chains and zero-waste mandates in California are accelerating shelf placement, with compliance advantages under extended producer responsibility frameworks reducing regulatory friction.
- Foam Shampoo:Aerosolized or pump-dispensed formats with reduced water content for spot-cleaning applications. Veterinary dermatology protocols in France favor foam for localized treatment of atopic skin conditions.
- Concentrated Shampoo:High-actives formulations requiring dilution prior to application. Professional groomers in Australia prefer concentrates for cost control in high-volume operations.
Leading the category by volume: Liquid Shampoo. Growing fastest: Solid Shampoo Bar.
Ingredients:
Ingredient sourcing determines REACH documentation intensity, with essential oil imports facing stricter ECHA thresholds than aloe vera derivatives. USDA Organic certification requirements vary by botanical origin.
- Aloe Vera:Mucopolysaccharide-rich extracts from Aloe barbadensis leaf gel demonstrating measurable reduction in canine transepidermal water loss. German pet specialty retailers command premium shelf space for aloe-dominant formulations targeting sensitive-skin protocols.
- Chamomile:Matricaria recutita-derived bisabolol and chamazulene with documented anti-inflammatory properties. Supply chain concentration in Egypt and Eastern Europe generates climate-sensitive harvest volatility compressing mid-tier formulator margins.
- Lavender Oil:Lavandula angustifolia essential oil requiring full REACH registration for volumes exceeding one tonne annually. French certification premiums support pricing power in boutique channels.
- Tea Tree Oil:Melaleuca alternifolia terpinen-4-ol with acaricidal positioning governed by EPA pesticidal thresholds. Australian harvest concentration exposes formulations to bushfire and drought risk.
Aloe vera dominates absolute demand. Tea tree oil faces steepest expansion constraints from regulatory documentation.
Animal Type:
Species-specific pH requirements and dermatology protocols create formulation specialization. Feline metabolism sensitivity to essential oil concentrations imposes stricter safety margins than canine applications.
- Dogs:Alkaline-tolerant formulations addressing breed-specific coat densities and seborrheic conditions. Volume concentrates in large-breed grooming salons across the United States and Germany.
- Cats:pH-balanced low-essential-oil formulations accounting for hepatic glucuronidation limitations. Veterinary clinic specifications in France and Japan drive premium positioning.
- Horses:High-volume applications for coat conditioning and dermatitis management. Equestrian centers in Kentucky and Normandy sustain concentrated demand.
- Small Animals:Rabbits, ferrets, and guinea pig formulations with species-specific safety profiles. Niche positioning in specialty pet stores with limited mass-market penetration.
Canine applications anchor volume. Feline formulations command highest per-unit certification premiums.
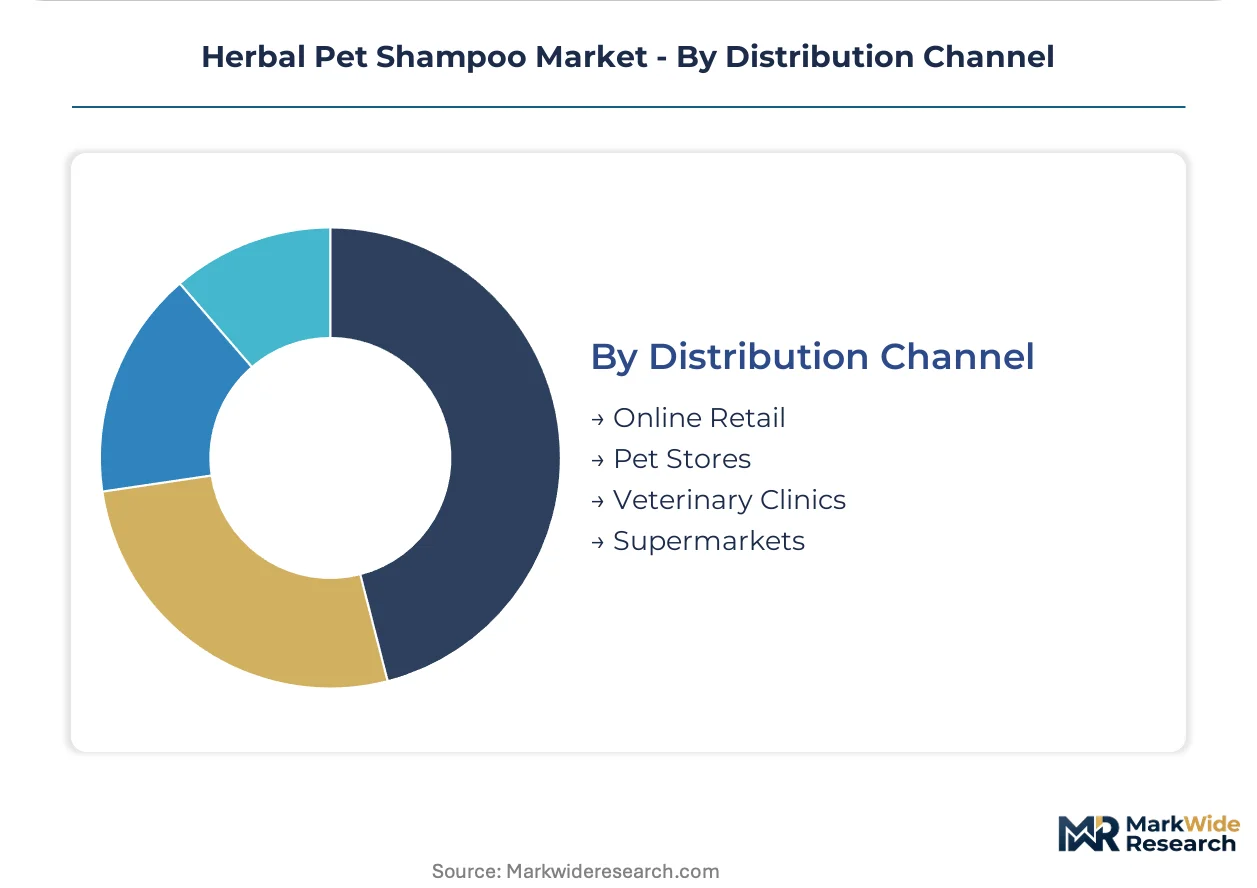
Distribution Channel:
Channel selection determines labeling burden intensity, with veterinary clinics requiring FDA-compliant therapeutic claims documentation absent from general retail.
- Online Retail:Direct-to-consumer platforms with reduced shelf-space constraints enabling long-tail botanical positioning. California-based green chemistry compliance increasingly filters product availability.
- Pet Stores:Specialty retail with certification-driven procurement requiring organic supply chain documentation. German and French buyers exhibit most pronounced certification premiums.
- Veterinary Clinics:Professional endorsement pipelines sustaining premium pricing through dermatology protocol integration. FDA Center for Veterinary Medicine oversight applies to therapeutic positioning claims.
- Supermarkets:Mass-market placement competing on unit cost against synthetic sulfate alternatives. Limited botanical penetration due to price-sensitive consumer default behavior.
Pet specialty retail leads value capture. Online channels show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cologne anchors European procurement for botanical pet care, with specialty retailers along the Rhine corridor commanding premium shelf space for certified organic formulations. German veterinary clinics specify plant-based sensitive-skin protocols that cascade into neighboring markets.
United States
California's green chemistry legislation reclassifies botanical preservatives under extended producer responsibility frameworks, forcing reformulation investments. The FDA Center for Veterinary Medicine oversees antimicrobial claims while EPA regulates tea tree oil acaricidal thresholds. Los Angeles and San Francisco pet specialty chains drive zero-waste packaging mandates that accelerate solid shampoo bar adoption.
Germany
REACH registration requirements constrain chamomile and lavender essential oil imports, elevating compliance documentation burdens. The EU Cosmetics Regulation mandates safety assessments that push manufacturers toward certified organic supply chains. Cologne and Düsseldorf pet specialty retailers anchor continental demand, with veterinary dermatology protocols specifying neem and aloe vera formulations.
France
ANSM oversight of veterinary cosmetic claims creates dual-labeling requirements for cross-border distribution. Certification premiums in Paris and Lyon pet boutiques exceed neighboring markets by significant margins. French lavender oil producers face ECHA registration thresholds that compress margins for mid-tier formulators serving the companion animal sector.
United Kingdom
Post-BREXIT regulatory divergence from EU REACH frameworks creates parallel compliance tracks for essential oil imports. London specialty retailers demand USDA Organic certification documentation that mirrors German procurement standards. The Midlands distribution corridor consolidates import logistics for tea tree oil formulations sourced from Australian suppliers.
Australia
Tea tree oil harvest concentration in New South Wales exposes formulations to bushfire and drought risk that generates input price volatility. The TGA oversees therapeutic claims while state-level environmental regulations govern Melaleuca alternifolia cultivation permits. Sydney and Melbourne grooming salons anchor Asia-Pacific demand for high-terpinen-4-ol concentration formulations.
Herbal Pet Shampoo Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tier and distribution channel depth, with USDA Organic documentation commanding shelf placement premiums that synthetic alternatives cannot match. The vendor base fragments between integrated wellness conglomerates, veterinary channel specialists, and boutique organic certifiers. Three archetypes dominate: Ayurvedic ingredient network owners, professional endorsement pipeline operators, and zero-waste format innovators. Capacity expansion in solid shampoo bar production and strategic partnerships with European certification bodies represent the dominant competitive moves.
Within the integrated wellness tier, Himalaya Wellness Company anchors supply security through its established Ayurvedic sourcing infrastructure. SynergyLabs occupies the veterinary channel specialist position, while 4-Legger exemplifies the boutique organic certifier archetype through its USDA Organic positioning. These three companies represent distinct margin-capture strategies: backward integration into ingredient networks, professional endorsement pipelines, and certification-driven retail premiums.
| Leading Market Players |
|---|
| Himalaya Wellness Company |
| SynergyLabs |
| 4-Legger |
| Earthwhile Endeavors Inc. |
| Beaphar |
| Burt's Bees |
| Petkin Inc. |
| Bayer AG |
| World for Pets |
| Others |
Supply Flow & Price Mechanics
German pet specialty retailers' mandatory USDA Organic documentation requirements force ingredient suppliers to absorb REACH compliance costs, compressing mid-tier formulator margins while concentrating pricing power among certified organic network owners.
Pricing Analysis
USDA Organic certification commands the dominant value-based pricing anchor in premium channels, with three-tier pricing structure across premium, standard, and economy levels separating boutique-certified lines from mass-market synthetics. Price differentiation rests on certification grade and veterinary endorsement intensity, not raw material cost alone. Pricing pressure stems from essential oil harvest volatility in Australia and India. Mass-market supermarket buyers exhibit highest price sensitivity, while veterinary clinic procurement shows lowest elasticity.
Supply Chain Analysis
REACH registration and USDA Organic qualification gating exclude smaller suppliers from European and North American market access, concentrating viable sourcing among established certifiers. Geographic supply concentrates in India for neem and tulsi, Australia for tea tree oil, and Egypt for chamomile. Raw material dependencies center on essential oil distillates, aloe vera gel extracts, and saponified botanical bases. Supply chain risk manifests as single-source vulnerability for Australian tea tree oil exposed to bushfire disruption. Distribution runs through pet specialty retail chains, veterinary clinic networks, and direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over Ayurvedic ingredient networks and certification infrastructure determines margin capture. Players are pursuing backward integration into neem and tulsi cultivation regions to anchor supply security.
For Market Incumbents: Cement supply security through captive sourcing agreements in Indian botanical cultivation corridors. Lock in veterinary endorsement pipelines with dermatology protocol integration investments. Defend against solid shampoo bar entrants by accelerating zero-waste format capacity in European production facilities.
For New Entrants and Emerging Players: Solid shampoo bar technology offers the most penetrable wedge for bypassing established liquid-format incumbents. Target Scandinavian pet specialty chains with zero-waste compliance advantages. Pursue direct-to-consumer launch with subscription-based refill models to circumvent shelf-space barriers.
For Investors and Strategic Acquirers: The window for entry favors integrated wellness conglomerates with existing Ayurvedic sourcing infrastructure. Long-term viability hinges on certification moat durability and regulatory compliance automation capabilities. Watch for California green chemistry enforcement actions as inflection signal for preservative system reformulation costs.
| Strategic Initiative | Industry Significance |
|---|---|
| USDA Organic Certification Investment | Unlocks premium shelf placement in German and French pet specialty retail channels. |
| Ayurvedic Sourcing Network Expansion | Captures supply security for neem and tulsi extracts against climate volatility. |
| Solid Shampoo Bar Capacity Buildout | Addresses zero-waste mandates in California and Scandinavian retail specifications. |
| Veterinary Channel Partnership Development | Establishes professional endorsement pipelines sustaining premium pricing power. |
| REACH Compliance Automation | Reduces documentation burden for essential oil imports into European markets. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across formulation chemists, veterinary dermatologists, pet specialty retail buyers, and organic certification auditors. Secondary sources encompassed FDA Center for Veterinary Medicine guidance documents, ECHA REACH registration databases, EU Cosmetics Regulation safety assessment protocols, and USDA Organic handler certifications. Bottom-up volume estimates triangulated against top-down market sizing across product type, ingredient cluster, animal species, and distribution channel dimensions.
Data-stream reconciliation across shipment volumes, retail audit data, and certification body records informed the analytical framework throughout the projection horizon. Segmentation modeling incorporated formulation type, botanical active concentration tier, animal species pH requirements, and channel-specific compliance burden intensity. CAGRs derived from regression analysis of historical certification adoption curves and regulatory enforcement trajectory indicators, with veterinary protocol integration rates and zero-waste retail mandate propagation serving as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced regulatory reclassifications of botanical preservatives, extreme climate events disrupting Australian or Indian harvests, and synthetic surfactant price collapses accelerating mass-market substitution. Forecasts reflect documented assumptions about certification premium durability and REACH compliance cost trajectories. A model refresh is warranted upon material change in California green chemistry enforcement intensity or EU essential oil import threshold adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Cat Diffuser Market
Pet Care Products
Pet Corrector Spray Market
Pet Care Products
Pet Hotels Market
Pet Care Products
Smart Pet Supply Market
Pet Care Products
Dog Dental Chews Market
Pet Care Products
Dog Water Bottle Market
Pet Care Products
Disposable Absorbent Pet Pad Market
Pet Care Products
Small Breed Dog Food Market
Pet Care Products
UAE Cat Food Market
Pet Care Products
Pet Food Pulverizer Market
Pet Care Products
Dog Clothing and Accessories Market
Pet Care Products
UK Dog Food Market
Pet Care Products
Therapeutic Diet for Pet Market
Pet Care Products
United States Pet Care and Services Market
Pet Care Products
Germany Pet Food Market
Pet Care Products
Dog Clothes Market