
 Australia Facial Care Market | 2026-2036
Australia Facial Care Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Facial Care Market Intelligence
Aftermarket service revenue from personalized skin analysis and subscription replenishment programs is reshaping profit architecture across Australian facial care retail. L'Oreal S.A. leverages its dermatological testing infrastructure to sustain clinical credibility with pharmacy networks. Beiersdorf AG anchors its position through intensive R&D on barrier-repair formulations suited to Australia's high-UV climate. Procter & Gamble competes via mass-market cleanser volume and supermarket shelf-space dominance.
Facial care encompasses topical products designed for cleansing, hydrating, exfoliating, and treating facial skin, typically formulated with active ingredients such as hyaluronic acid, niacinamide, or retinoids at concentrations ranging from 0.5% to 10% depending on therapeutic intent. These products serve both cosmetic maintenance and dermatological support functions across consumer and clinical channels. Moisturizer and serum categories command the strongest margin pools due to higher per-unit pricing and repeat purchase frequency, while cleanser sales provide volume foundation through supermarket and pharmacy distribution. The sensitive skin segment exhibits the fastest structural growth as TGA-aligned ingredient transparency drives consumers toward hypoallergenic and fragrance-free formulations.
TGA cosmetic regulations, ACCC consumer protection standards, and ISO 16128 natural and organic cosmetics guidelines collectively shape product claims, ingredient safety thresholds, and market access requirements for facial care brands operating in Australia. Compliance with evolving sunscreen-claim overlap rules and preservative restriction schedules directly influences formulation costs and registration timelines for new product introductions. Stakeholders must monitor pending updates to Australian Industrial Chemicals Introduction Scheme categorization for imported active ingredients.
Market Dynamics
The TGA's escalating cosmetic ingredient disclosure mandates are compressing formulation cycles while elevating compliance costs for Australian facial care manufacturers importing active compounds under the Australian Industrial Chemicals Introduction Scheme.
Growth Catalysts
- Barrier-repair science:Melbourne and Sydney dermatology clinics are driving clinical validation for ceramide and niacinamide concentrates. Pharmacy networks now stock these formulations as first-line interventions for compromised skin barriers in high-UV environments.
- TGA transparency alignment:Evolving disclosure requirements for preservative systems and fragrance compounds are accelerating consumer migration toward hypoallergenic product lines. This regulatory pressure rewards brands with pre-existing clean-label infrastructure.
- Subscription replenishment models:Urban millennials across Brisbane and Perth are adopting automated serum and moisturizer resupply programs. Direct-to-consumer platforms capture recurring revenue streams previously dominated by pharmacy and supermarket channels.
Market Restraints
- Active ingredient import dependency:Australian formulators rely on concentrated hyaluronic acid, retinoids, and peptide complexes from South Korean and Swiss suppliers. Currency volatility and shipping disruptions compress margin stability.
- TGA-AIICS categorization friction:New active ingredients face extended safety assessment timelines under the Australian Industrial Chemicals Introduction Scheme. Registration delays stretch 18-24 months for novel compounds.
- Sunscreen-claim overlap complexity:Products combining facial care with SPF protection trigger dual TGA therapeutic and cosmetic classification requirements. This regulatory ambiguity increases legal review costs and launch risk.
Strategic Opportunities
- Queensland and Western Australia expansion:Facial care penetration in Brisbane, Gold Coast, and Perth remains below Sydney-Melbourne saturation levels. Regional pharmacy chains seek premium serum and exfoliator distribution partnerships.
- AI-driven skin analysis integration:Computer vision diagnostics paired with personalized formulation matching are creating subscription stickiness. Melbourne tech startups partner with established brands to deploy in-store and at-home assessment tools.
- ISO 16128 natural certification:Growing consumer preference for verifiable organic sourcing creates premium positioning for compliant brands. Certification investments differentiate products in crowded pharmacy and supermarket aisles.
Industry Challenges
- Formulation chemist scarcity:Australian universities produce limited graduates trained in TGA-compliant cosmetic chemistry. Brands compete for talent capable of navigating preservative restriction schedules and stability testing protocols.
- Clinical trial infrastructure gaps:Barrier-repair and sensitive skin claims require dermatological testing that exceeds in-house capabilities. Partnerships with Sydney and Melbourne research institutions extend validation timelines and increase R&D overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Facial Care Market |
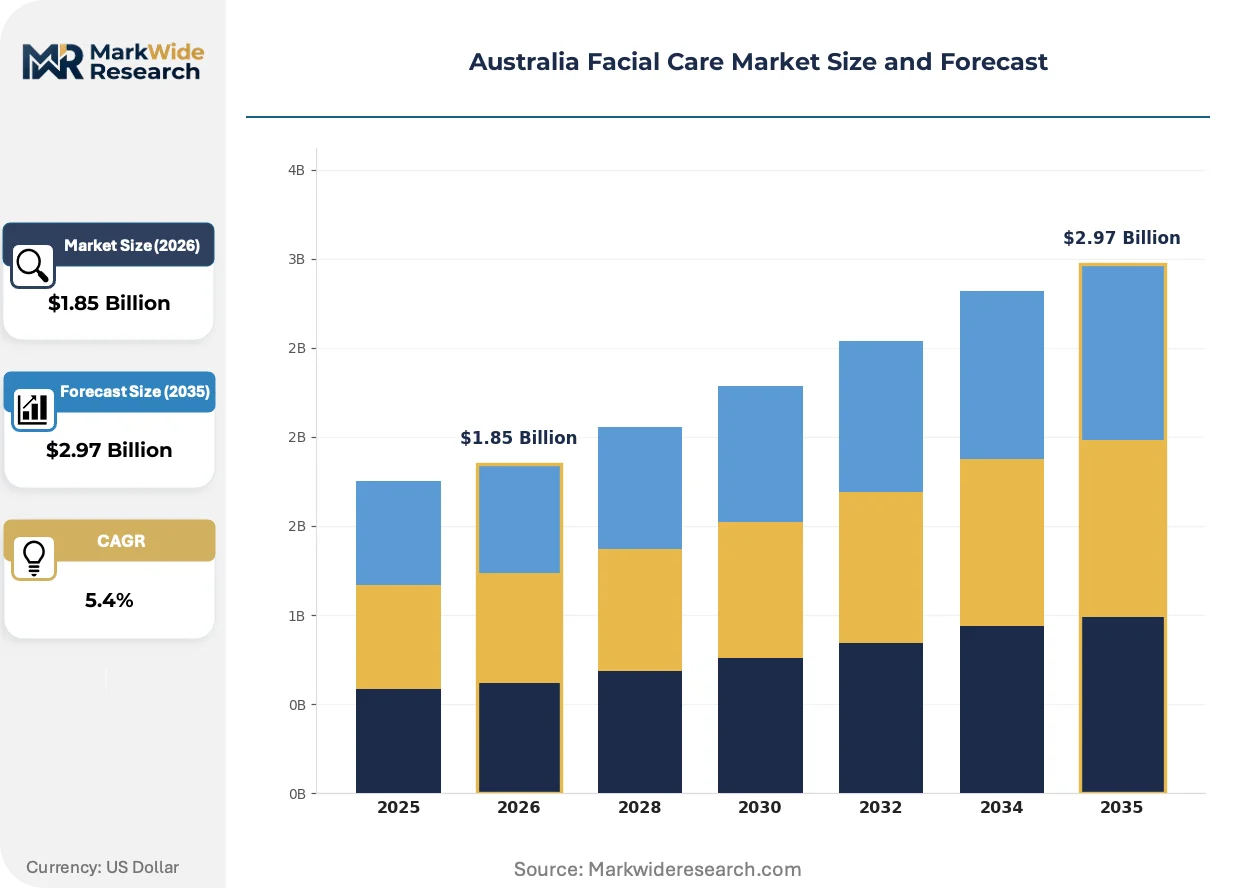
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cleanser, Moisturizer, Exfoliator, Serum Skin Type: Oily, Dry, Combination, Sensitive Age Group: Teens, Adults, Seniors, Age 35-50 Distribution Channel: Online, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | Johnson & Johnson, Beiersdorf AG, L'Oreal S.A., Revlon Inc., Kao Corporation, Procter & Gamble, The Estee Lauder Companies Inc, Cutera, Unilever PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Facial Care Market Strategic Shifts & Innovations
Biotechnology-derived actives and algorithmic personalization are compressing traditional product development cycles while fragmenting consumer loyalty across niche, clinically-positioned sub-brands.
Encapsulated retinoid delivery systems using lipid nanoparticle technology enable stabilized vitamin A release at concentrations previously associated with irritation. Melbourne-based dermatology clinics prescribe these formulations for melasma and photoaging protocols. Shelf-stable encapsulation is rendering obsolete conventional retinol products requiring refrigeration and rapid consumption windows.
TGA's 2024 updates to cosmetic ingredient labeling requirements mandate quantitative disclosure of fragrance allergens above 0.001% concentration. Manufacturers reformulate legacy products or withdraw SKUs exceeding compliance cost thresholds. The sensitive skin segment responds fastest, with Brisbane and Adelaide consumers switching to fragrance-free alternatives ahead of mandatory enforcement dates.
Pharmacy-supervised skin analysis is displacing self-directed online purchasing for premium serum categories. Sydney consumers complete in-store diagnostic sessions before committing to niacinamide or peptide concentrate regimens. This behavioral shift concentrates high-margin sales through Priceline and Chemist Warehouse consultation counters rather than pure-play e-commerce platforms.
Australia Facial Care Market Segmentation
Segmentation in Australian facial care reveals distinct service intensity patterns across product categories and retail channels. Subscription replenishment programs and pharmacy consultation services create divergent margin architectures that reward precise targeting.
Product Type:
After-sales service intensity varies dramatically across product types, with serum and moisturizer categories demanding sustained consumer education and replenishment support while cleansers operate on transactional volume models.
- Moisturizer:Barrier-repair formulations with ceramide and niacinamide concentrates dominate pharmacy shelves in Sydney and Melbourne. Dermatology clinic partnerships drive prescription-adjacent positioning for compromised skin in high-UV environments.
- Serum:High-concentration active delivery systems (0.5% to 10% therapeutic intent) command premium pricing and repeat purchase frequency. Urban millennials adopt automated resupply programs for hyaluronic acid and peptide complexes.
- Cleanser:Mass-market volume foundation through supermarket distribution.
- Exfoliator:Chemical and physical variants serving renewal-focused routines.
Moisturizer holds the largest share; momentum sits with serum.
Skin Type:
Cost tier stratification separates clinical-grade sensitive skin formulations from standard cosmetic maintenance products, with TGA-aligned transparency mandates accelerating premium migration.
- Sensitive:Hypoallergenic and fragrance-free formulations undergoing fastest structural expansion. TGA's 2024 fragrance allergen disclosure rules above 0.001% concentration accelerate consumer switching ahead of enforcement dates.
- Combination:Dual-zone targeting products capturing eastern seaboard demand concentration. Melbourne and Sydney consumers seek balanced hydration for T-zone and cheek differential treatment.
- Oily:Sebum-regulating cleansers and lightweight moisturizers.
- Dry:Intensive lipid-replenishment formulations for barrier-deficient profiles.
Sensitive skin commands premium tier expansion; combination skin shows steepest volume trajectory.
Age Group:
Application maturity distinguishes established adult routines from emerging teen prevention markets and clinical intervention needs among older demographics.
- Adults:Core revenue base with established multi-step routines across Brisbane and Perth. Subscription models capture recurring replenishment of niacinamide and retinoid concentrates.
- Age 35-50:Encapsulated retinoid delivery systems for melasma and photoaging protocols. Melbourne dermatology clinics prescribe lipid nanoparticle-stabilized vitamin A for this cohort.
- Teens:Entry-level cleansing and basic hydration establishing brand loyalty.
- Seniors:Intensive barrier repair and age-related concern targeting.
Adults retain volume dominance; Age 35-50 shows fastest value-per-user acceleration.
Distribution Channel:
Geography concentration separates metropolitan pharmacy consultation counters from mass-market supermarket penetration and direct-to-consumer platform expansion.
- Pharmacies:Priceline and Chemist Warehouse consultation counters concentrate high-margin serum sales. Sydney consumers complete in-store diagnostic sessions before committing to peptide concentrate regimens.
- Online:Direct-to-consumer platforms capture subscription replenishment previously dominated by physical retail. Brisbane and Perth urban millennials drive automated resupply adoption.
- Supermarkets:Mass-market cleanser volume and shelf-space competition.
- Specialty Stores:Curated premium positioning with experiential service.
Pharmacies hold margin concentration; online channels gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New South Wales and Victoria concentrate premium serum adoption through pharmacy consultation networks, while Queensland and Western Australia exhibit lower penetration but faster subscription-model uptake among younger demographics.
New South Wales
Sydney consumers drive pharmacy-supervised skin analysis adoption at Priceline and Chemist Warehouse consultation counters. TGA cosmetic ingredient disclosure requirements mandate quantitative fragrance allergen labeling above 0.001% concentration. North Sydney and Parramatta clusters concentrate dermatology clinic partnerships prescribing ceramide concentrates for barrier repair.
Victoria
Melbourne millennials anchor automated serum replenishment programs through direct-to-consumer platforms. The state's therapeutic goods regulator enforces preservative restriction schedules affecting formulation stability testing. Southbank and Docklands house biotechnology startups deploying AI-driven skin analysis tools paired with personalized niacinamide matching.
Queensland
Brisbane and Gold Coast consumers exhibit rising demand for exfoliator and serum categories previously underpenetrated compared to southern states. ACCC consumer protection standards govern subscription service transparency for automated resupply programs. Fortitude Valley retail clusters seek premium brand distribution partnerships as pharmacy networks expand facial care consultation services.
Western Australia
Perth's urban demographic accelerates adoption of encapsulated retinoid delivery systems for photoaging protocols. ISO 16128 natural and organic cosmetics guidelines create certification pathways for brands targeting verifiable sourcing preferences. Subiaco and Fremantle specialty retail clusters differentiate through curated sensitive skin formulations.
South Australia
Adelaide consumers respond fastest to TGA's 2024 fragrance allergen disclosure rules, switching to fragrance-free alternatives ahead of enforcement dates. The Australian Industrial Chemicals Introduction Scheme categorization affects import timelines for novel peptide complexes. Rundle Mall pharmacy networks stock hypoallergenic lines as first-line interventions for sensitive skin profiles.
Australia Facial Care Market Key Industry Players
Capability concentration sits with dermatological-testing and clinical-validation specialists; scale advantage sits with mass-market distribution incumbents. The market structures around three tiers: premium clinical-positioned brands, mass-market volume players, and emerging direct-to-consumer platforms. Two strategic archetypes dominate: laboratory-backed pharmacy channel specialists and supermarket shelf-space optimizers. Competitive moves concentrate on subscription platform development and regional pharmacy partnership expansion.
Within the clinical-validation tier, L'Oreal S.A. and Beiersdorf AG exemplify laboratory-backed positioning through dermatological testing infrastructure and barrier-repair formulation science. Procter & Gamble occupies the scale-driven mass-market vector with supermarket and pharmacy volume foundation. Johnson & Johnson represents diversified healthcare conglomerate structure spanning consumer and clinical channels. These three anchors illustrate the capability-scale tension shaping competitive dynamics.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Beiersdorf AG |
| L'Oreal S.A. |
| Revlon Inc. |
| Kao Corporation |
| Procter & Gamble |
| The Estee Lauder Companies Inc |
| Cutera |
| Unilever PLC |
| Others |
Cost & Logistics Intelligence
South Korean and Swiss active ingredient suppliers command disproportionate leverage over Australian facial care margin pools, with concentrated hyaluronic acid and peptide complex sourcing dictating where formulation economics accrue downstream.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement of imported actives, though spot purchasing persists for novel compounds facing TGA-AIICS registration delays. Three-tier pricing structure across premium clinical-positioned, standard pharmacy, and economy supermarket levels separates serum concentrates from mass-market cleansers. Pricing pressure stems from currency volatility against the won and franc, compressing margin stability for domestic formulators. Mass-market supermarket buyers exhibit highest price sensitivity, while pharmacy-supervised consultation patients accept clinical-grade premiums.
Supply Chain Analysis
Extended payment terms from Australian distributors to South Korean and Swiss suppliers strain working capital across mid-tier formulators. Active ingredient dependencies center on concentrated retinoids, ceramide complexes, and encapsulated peptide systems from East Asian and European suppliers. Single-source vulnerability runs through lipid nanoparticle encapsulation technology held by limited Swiss specialty houses. Distribution runs through pharmacy consultation counters for premium tiers, supermarket shelf-space for volume, and direct-to-consumer platforms for subscription replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
TGA-compliant cosmetic chemistry expertise represents a binding constraint across Australian facial care, with university pipeline output failing to match industry demand for formulation scientists versed in preservative restriction schedules and stability protocols.
For Market Incumbents: Pre-empt subscription platform consolidation by acquiring Melbourne and Brisbane direct-to-consumer operators with established automated replenishment infrastructure. Lock in exclusive pharmacy consultation partnerships before emerging clinical-positioned entrants capture Priceline and Chemist Warehouse shelf-space. Backward integration into captive encapsulation technology mitigates Swiss supplier concentration risk. For New Entrants and Emerging Players: Establish a beachhead in Queensland and Western Australia pharmacy networks, where serum and exfoliator penetration trails Sydney-Melbourne saturation by measurable distance. Target Brisbane's Fortitude Valley and Perth's Subiaco retail clusters seeking premium distribution partnerships. Lead with ISO 16128 natural certification as a differentiated entry credential against legacy brand reformulation lag. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed direct-to-consumer platforms possessing subscription data infrastructure but lacking clinical validation credibility. Long-term viability hinges on TGA-aligned transparency compliance and dermatology clinic partnership depth. Watch TGA-AIICS categorization rulings on novel peptide complexes as an inflection signal for formulation pipeline value.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Skin Analysis Integration | Melbourne tech startups partner with established brands to deploy diagnostic tools that personalize niacinamide matching. |
| Barrier-Repair Formulation R&D | Ceramide concentrate development addresses high-UV climate damage through dermatology clinic validation partnerships. |
| Subscription Platform Development | Automated replenishment captures recurring revenue streams previously dominated by pharmacy and supermarket channels. |
| ISO 16128 Natural Certification | Verifiable organic sourcing credentials differentiate products in crowded pharmacy and supermarket aisles. |
| Regional Pharmacy Partnership Expansion | Queensland and Western Australia networks seek premium serum distribution as consultation services proliferate. |
Research Approach
A standing panel of formulation chemists, pharmacy category managers, dermatology clinic directors, and TGA regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from TGA cosmetic ingredient disclosure filings, ACCC consumer protection rulings, Australian Industrial Chemicals Introduction Scheme categorization records, and ISO 16128 certification databases. Bottom-up segment sizing triangulated against top-down market value reconstruction.
Scenario-bracketing framed projections across the analysis window, with CAGRs derived from segment-level growth rate reconciliation against macroeconomic consumption indicators. Modeled dimensions spanned product type, skin type, age group, and distribution channel, with TGA regulatory timeline assumptions and AIICS import categorization velocity as industry-specific forecast inputs.
Sensitivities concentrate around TGA-AIICS registration timeline revisions, currency volatility against active supplier currencies, and subscription model adoption velocity among Brisbane and Perth demographics. Forecasts reflect documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
South America Hair Styling Products Market
Beauty & Personal Care
Cosmetics and Personal Care Stores Market
Beauty & Personal Care
Herbal Shampoo Market
Beauty & Personal Care
BB Cushions Market
Beauty & Personal Care
Elastomer Gel in Personal Care Market
Beauty & Personal Care
Middle East and Africa Hair Styling Products Market
Beauty & Personal Care
Advanced Night Repair Serum Market
Beauty & Personal Care
Men's Personal Care Market
Beauty & Personal Care
US Color Cosmetics Market
Beauty & Personal Care
Australia Beauty and Personal Care Products Market
Beauty & Personal Care
Spain Dermocosmetics Market
Beauty & Personal Care
Personal Care and Cosmetic Preservatives Market
Beauty & Personal Care
Foaming Hand Soaps Market
Beauty & Personal Care
Italy Beauty and Personal Care Products Market
Beauty & Personal Care
Online Cosmetics Market
Beauty & Personal Care
US Natural Personal Care Market