
 North America Automotive E-Commerce Market | 2026-2036
North America Automotive E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive E-Commerce Market Analytics
Aftermarket parts procurement is reconfiguring margin pools away from traditional brick-and-mortar channels toward digital platforms with integrated logistics. Amazon.com Inc leverages its fulfillment infrastructure to dominate same-day and next-day auto parts delivery across dense metropolitan zones. AutoZone Inc sustains competitive position through hybrid delivery models that blend curbside pickup with expanded digital catalog depth. O'Reilly Automotive Inc anchors its e-commerce strategy in professional installer relationships, capturing recurring fleet and repair shop demand.
North America Automotive E-Commerce encompasses the digital sale, financing, and fulfillment of vehicles, parts, and accessories through web-based platforms, mobile applications, and integrated dealer management systems that process VIN-specific fitment verification, real-time inventory synchronization, and multi-modal logistics coordination. The ecosystem serves consumers, commercial fleets, and repair professionals by collapsing search costs and expanding SKU availability beyond physical lot constraints. Parts and accessories command durable margin pools due to repeat purchase frequency and lower fulfillment complexity relative to whole-vehicle transactions. Online marketplaces capture disproportionate growth velocity by aggregating fragmented seller bases and standardizing buyer protection protocols. Fleet operators represent the fastest-expanding customer type as telematics-integrated procurement platforms replace manual reordering processes.
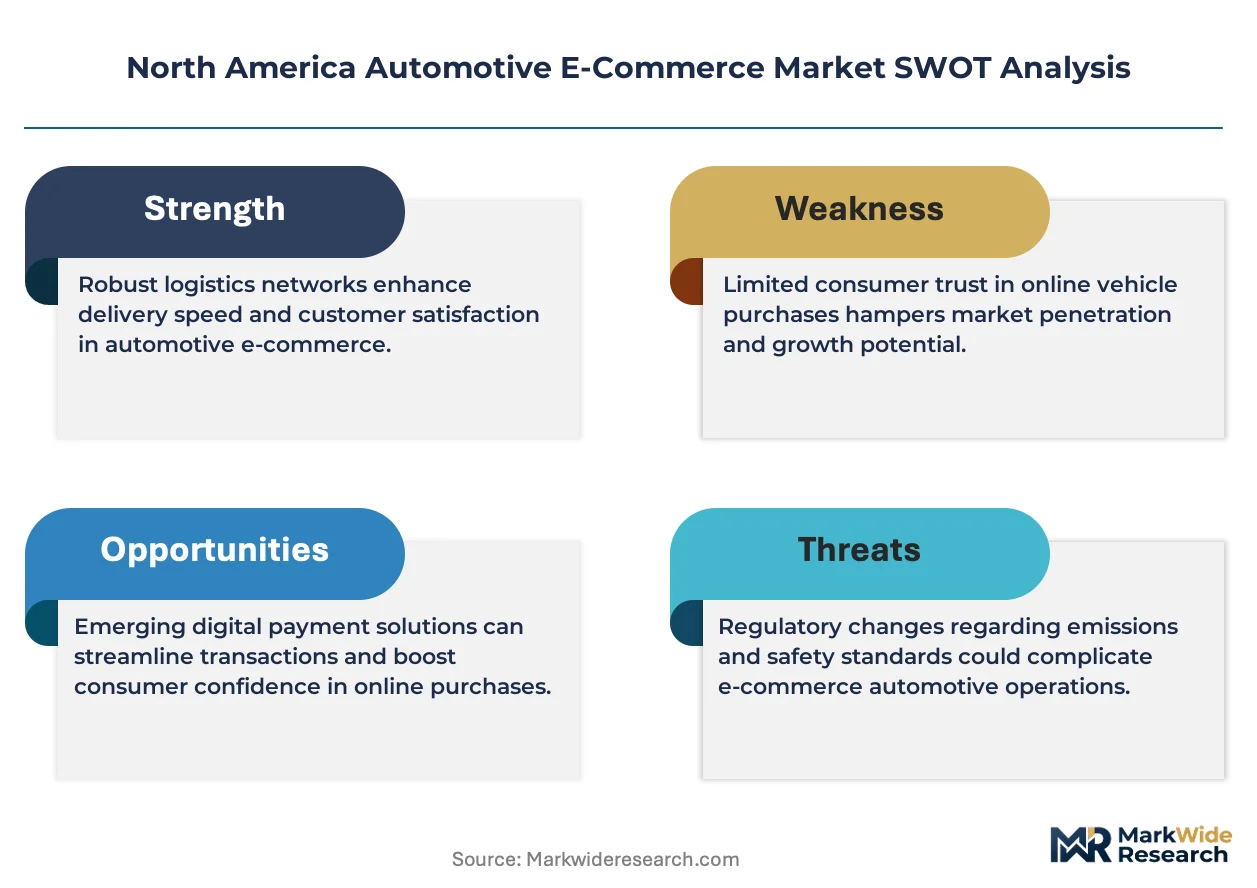
The US Federal Trade Commission's Combating Auto Retail Scams Rule reshapes online vehicle pricing disclosure requirements, compelling platforms to eliminate hidden fees and mandatory add-ons in digital transactions. EPA emissions certification standards for aftermarket performance parts create compliance filtering layers that favor established sellers with documented supply chain traceability. NHTSA recall data integration into e-commerce platforms shapes consumer safety purchasing decisions and seller liability exposure. Stakeholders must monitor how state-level dealer franchise laws evolve to either protect or erode direct-to-consumer vehicle sales channels.
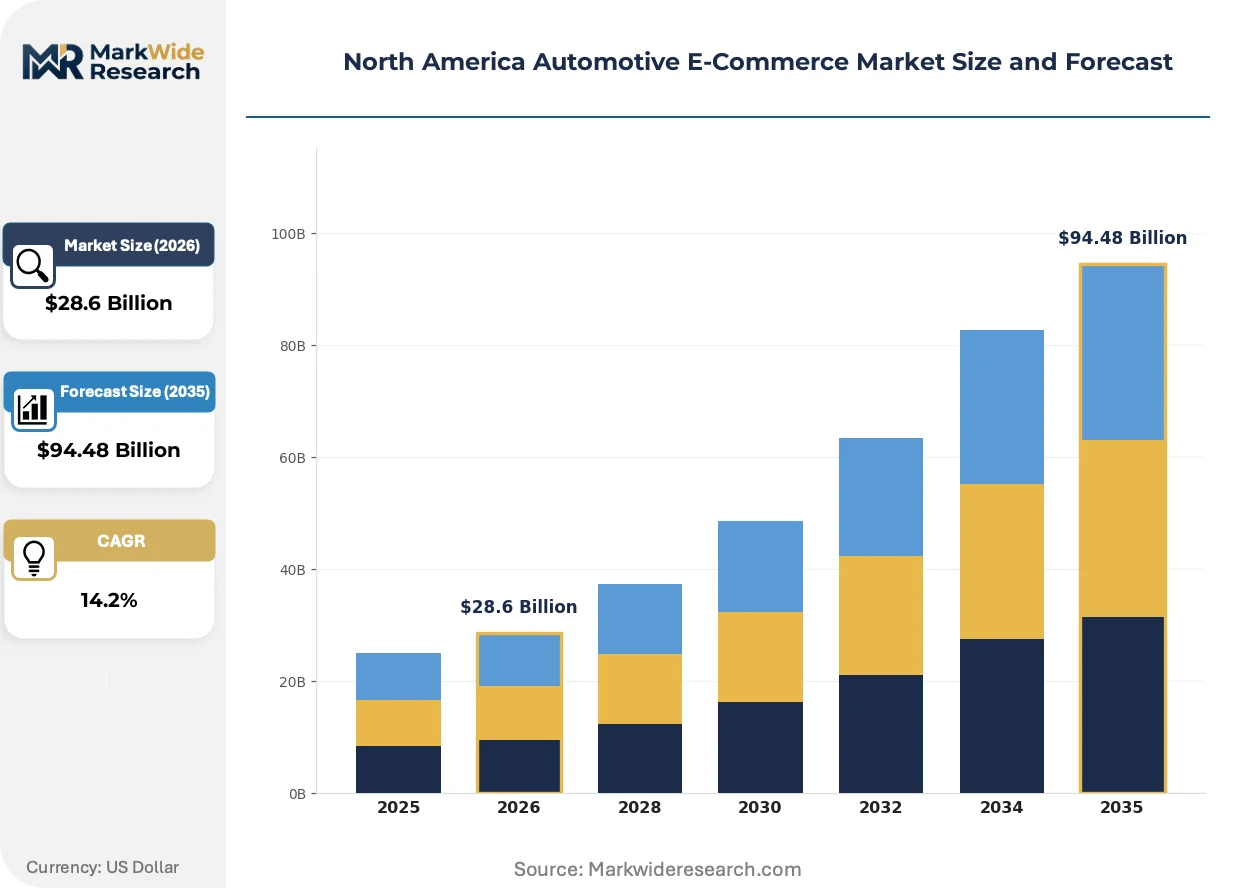
Market Dynamics
Fleet telematics integration is digitizing commercial vehicle procurement workflows, collapsing traditional reorder cycles into automated inventory-triggered purchasing that bypasses legacy dealer networks entirely.
Growth Catalysts
- US Inflation Reduction Act EV tax credits:Federal incentives reshape vehicle eligibility criteria and force online pricing transparency, accelerating platform adoption for electric vehicle transactions.
- Telematics-integrated procurement:Connected fleet management systems automate parts reordering based on real-time wear data, embedding e-commerce into operational workflows.
- Sun Belt dealer digitization:US southern states exhibit faster dealer management system upgrades, creating regional density effects that pull platform investment.
Market Restraints
- State franchise law fragmentation:Dealer protection statutes in Texas and Michigan create regulatory friction that blocks direct-to-consumer vehicle sales channels.
- Aftermarket parts certification complexity:EPA emissions standards for performance components favor established sellers with documented supply chains, raising barriers for new entrants.
- Same-day fulfillment cost structure:Dense metropolitan zone coverage requires capital-intensive warehouse networks that compress margins for pure-play platforms.
Strategic Opportunities
- Professional installer channel capture:Repair shop and fleet maintenance relationships offer recurring demand streams with higher lifetime value than consumer transactions.
- Mexico cross-border logistics integration:Manufacturing proximity creates white space for parts fulfillment networks serving US border states with compressed lead times.
- NHTSA recall data integration:Safety information embedding into purchase workflows creates differentiation for platforms that automate compliance filtering.
Industry Challenges
- VIN-specific fitment verification talent:Shortage of engineers capable of building real-time compatibility engines constrains catalog expansion velocity.
- Legacy dealer system integration:DMS synchronization with e-commerce platforms requires expensive API development and ongoing maintenance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive E-Commerce Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $94.48 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: New Vehicles, Used Vehicles, Parts, Accessories Sales Channel: Online Marketplaces, Direct Sales, Dealership Websites, Auction Sites Customer Type: Individual Buyers, Fleet Operators, Dealerships, Aftermarket Resellers Delivery Model: Home Delivery, Curbside Pickup, showroom Pickup, Hybrid Delivery |
| Companies Covered | Genuine Parts Co, eBay Inc, Advance Auto Parts Inc, CarParts.com Inc, Walmart Inc, AutoZone Inc, Amazon.com Inc, CARiD.com, O'Reilly Automotive Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive E-Commerce Market Evolving Landscape
Artificial intelligence and embedded connectivity are compressing search-to-purchase timelines while regulatory disclosure mandates reshape how platforms present total ownership costs.
Artificial intelligence-powered visual search is digitizing parts identification workflows. Fleet maintenance technicians and DIY consumers photograph damaged components, receiving instant VIN-matched replacement recommendations. Commercial repair shops adopt these tools fastest, cutting diagnostic time from hours to minutes and shifting parts discovery away from traditional catalog browsing.
The US FTC Combating Auto Retail Scams Rule mandates all-in pricing disclosure for online vehicle listings. Platforms must itemize fees, eliminate mandatory add-ons, and display total transaction costs upfront. Digital-native marketplaces adapt faster than legacy dealer sites, creating compliance-based competitive separation in used vehicle segments.
Subscription-based parts replenishment is displacing transactional purchasing among fleet operators. Telematics systems trigger automatic orders when wear thresholds breach, embedding e-commerce into preventive maintenance schedules. This pattern concentrates most visibly in long-haul trucking and last-mile delivery verticals where vehicle utilization rates demand minimal downtime.
North America Automotive E-Commerce Market Segmentation
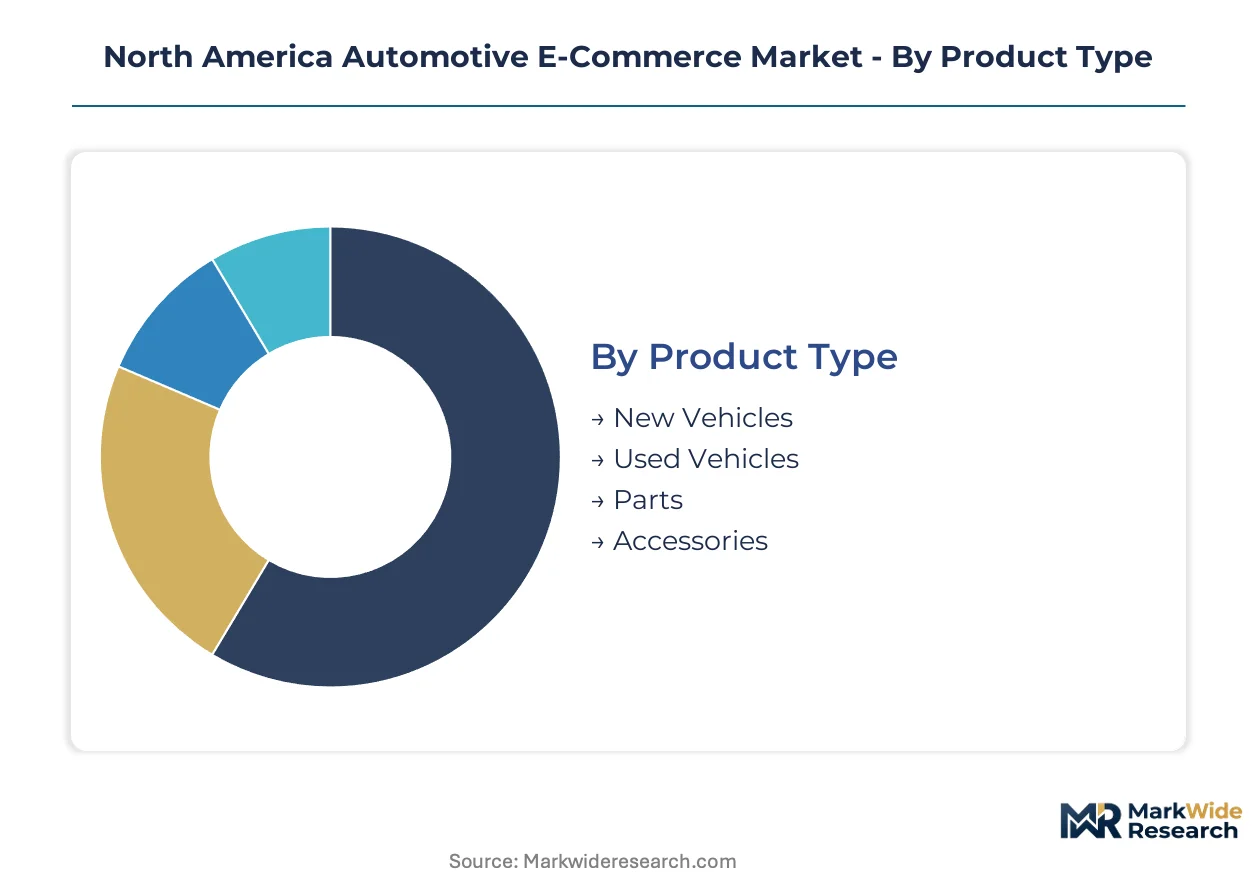
Automotive e-commerce segmentation reveals divergent margin structures and fulfillment requirements across transaction types. Parts and accessories command repeat purchase frequency that whole-vehicle sales cannot match, while fleet procurement digitization concentrates volume in B2B channels.
Product Type:
After-sales-service intensity varies dramatically across product categories, with consumable components generating recurring revenue streams that new vehicle transactions lack entirely.
- New Vehicles:Online configurators now process VIN-specific builds with real-time inventory synchronization across dealer networks. FTC disclosure mandates force itemized fee transparency that compresses margin opacity in digital transactions.
- Used Vehicles:Digital marketplaces aggregate fragmented seller bases while embedding vehicle history data and NHTSA recall alerts directly into search workflows. Certification programs create quality tiers that standardize buyer protection protocols.
- Parts:VIN-matched fitment verification engines reduce return rates and support same-day fulfillment networks in dense metropolitan zones.
- Accessories:Lower compatibility complexity enables broader SKU expansion with reduced engineering overhead relative to mechanical components.
Parts holds the largest share; momentum sits with used vehicles as platform transparency tools reshape consumer trust dynamics.
Sales Channel:
Channel selection determines capital intensity, with marketplace models aggregating third-party inventory against direct sales requiring captive fulfillment infrastructure.
- Online Marketplaces:Aggregator platforms standardize buyer protection and payment escrow while collapsing search costs across fragmented seller bases. Network effects concentrate transaction liquidity that individual dealer sites cannot replicate.
- Direct Sales:Manufacturer-controlled channels bypass franchise law constraints where state statutes permit, capturing full margin stack but requiring heavy logistics investment.
- Dealership Websites:Legacy DMS integration enables real-time lot inventory display, though user experience lags digital-native platforms.
- Auction Sites:Wholesale vehicle disposition channels serve dealer-to-dealer and fleet remarketing flows with compressed transaction timelines.
Online marketplaces dominate transaction volume; direct sales channels are climbing the fastest where regulatory frameworks accommodate manufacturer bypass.
Customer Type:
Procurement automation penetration separates institutional buyers from consumer segments, with fleet operators embedding e-commerce into telematics-triggered reorder workflows.
- Fleet Operators:Connected vehicle systems automate parts procurement based on real-time wear telemetry, collapsing traditional manual reorder cycles. Preventive maintenance scheduling embeds e-commerce into operational workflows with minimal human intervention.
- Individual Buyers:Consumer transactions remain event-driven with lower lifetime value but higher per-transaction research intensity and financing complexity.
- Dealerships:B2B parts procurement serves service bay operations with recurring demand patterns distinct from retail consumer behavior.
- Aftermarket Resellers:Professional installer relationships create channel capture opportunities with higher purchase frequency and technical specification requirements.
Fleet operators represent the steepest expansion trajectory; individual buyers retain the largest absolute transaction count.
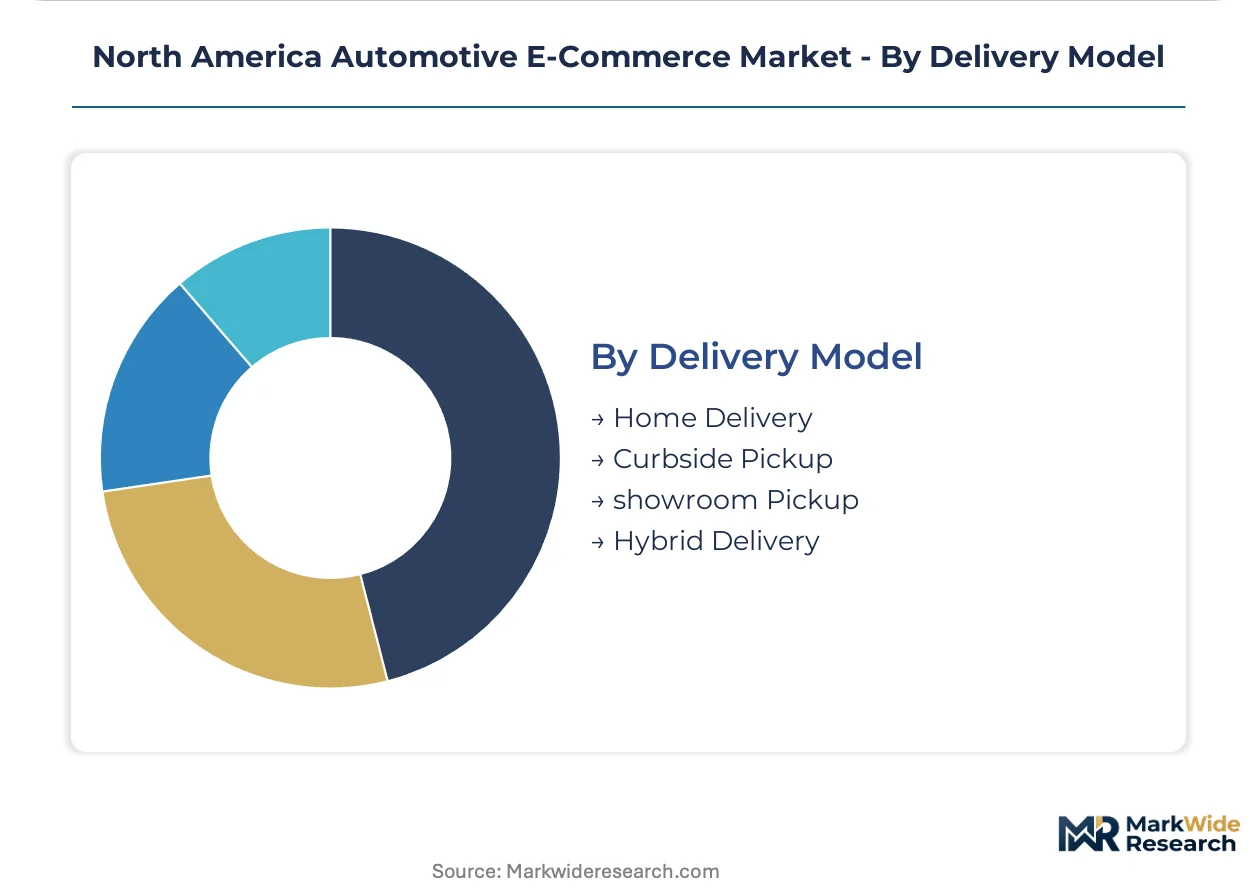
Delivery Model:
Fulfillment cost structures stratify by population density, with same-day coverage requiring capital-intensive warehouse networks that pure-play platforms struggle to sustain.
- Home Delivery:Last-mile logistics integration enables direct-to-consumer parts fulfillment in dense urban corridors where warehouse proximity supports compressed lead times.
- Curbside Pickup:Hybrid models blend digital catalog depth with physical location convenience, reducing last-mile cost burden while maintaining transaction velocity.
- Showroom Pickup:Whole-vehicle transactions require physical handoff for title transfer and inspection, limiting pure digital completion.
- Hybrid Delivery:Multi-modal coordination synchronizes online ordering with flexible fulfillment optionality based on inventory location and customer urgency.
Curbside pickup holds the largest share; home delivery is gaining share fastest as metropolitan warehouse density improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes automotive e-commerce through fleet-integrated procurement platforms, while Canada and Mexico exhibit divergent patterns shaped by cross-border logistics infrastructure and domestic dealer network density.
United States
Fleet telematics adoption and Sun Belt dealer digitization concentrate demand in southern states. The FTC Combating Auto Retail Scams Rule mandates all-in pricing disclosure for online vehicle transactions. Dallas-Fort Worth anchors same-day parts fulfillment networks serving dense metropolitan corridors.
Canada
Cross-border parts procurement from US distribution centers shapes Canadian consumption patterns. Environment Canada emissions certification requirements filter aftermarket performance parts availability. The Greater Toronto Area hosts concentrated e-commerce platform operations targeting Ontario's vehicle population.
Mexico
Manufacturing proximity to US border states enables compressed lead-time fulfillment networks. Mexican federal consumer protection standards govern digital transaction transparency for cross-border sales. Nuevo León's industrial corridor supports parts distribution infrastructure serving Texas and California markets.
North America Automotive E-Commerce Market Competitive Landscape
Capability concentration sits with specialized auto parts platforms possessing VIN-matched fitment engines; scale advantage sits with diversified e-commerce giants leveraging existing fulfillment infrastructure. The market structures around three tiers: pure-play automotive specialists, generalist marketplaces with auto verticals, and legacy retailers with hybrid digital-physical models. Dominant competitive moves include strategic partnerships with telematics providers and geographic expansion of same-day delivery networks.
Within the pure-play specialist tier, CarParts.com Inc and CARiD.com occupy positions defined by catalog depth and fitment verification capabilities. Among diversified marketplace operators, Amazon.com Inc and eBay Inc exemplify scale-driven models leveraging existing logistics infrastructure for automotive vertical penetration. Legacy retail specialists including AutoZone Inc, O'Reilly Automotive Inc, Advance Auto Parts Inc, and Genuine Parts Co anchor hybrid strategies blending physical location networks with digital catalog expansion.
| Leading Market Players |
|---|
| Genuine Parts Co |
| eBay Inc |
| Advance Auto Parts Inc |
| CarParts.com Inc |
| Walmart Inc |
| AutoZone Inc |
| Amazon.com Inc |
| CARiD.com |
| O'Reilly Automotive Inc |
| Others |
Value Network & Pricing Analysis
Overcapacity in US Sun Belt fulfillment centers compresses supplier margins while accelerating same-day delivery coverage wars among platform operators. Warehouse utilization rates below 60 percent in Phoenix and Dallas markets force providers to absorb fixed costs through promotional pricing, reshaping how parts distributors negotiate slotting fees and volume commitments with e-commerce marketplaces.
Pricing Analysis
Long-term offtake contracts dominate fleet procurement relationships, locking in volume-based pricing tiers that insulate large buyers from spot market volatility. Price differentiation hinges on VIN-specific fitment certification and same-day delivery eligibility, with certified fitment engines commanding 15-20 percent premiums over generic catalog listings. Cost compression in metropolitan same-day tiers is intensifying because Amazon and Walmart fulfillment infrastructure expansion erodes pure-play automotive specialists' geographic exclusivity. Fleet operators exhibit lowest price sensitivity due to embedded telematics procurement automation, while DIY consumers drive transactional discounting through comparison shopping across multiple platforms.
Supply Chain Analysis
Extended payment terms from 30 to 90 days characterize supplier financing arrangements as platform aggregators push working capital burdens upstream to parts manufacturers. Geographic supply concentration centers on Mexico for assembly components, Taiwan for semiconductor content, and China for aftermarket accessories and electronics. Raw material dependencies include lithium-ion battery cells, rare earth magnets for electric drivetrains, and aluminum casting feedstock. Single-source vulnerability in VIN-matched fitment databases creates concentration risk for platforms dependent on proprietary catalog providers. Distribution runs through hub-and-spoke warehouse networks with regional sortation centers feeding last-mile delivery stations in dense urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in automotive e-commerce are reaching an inflection as telematics-embedded procurement collapses traditional search-and-compare behavior into automated reorder workflows. Interoperability between fleet management systems and parts marketplaces is consolidating buyer liquidity around integrated platforms that control both data exhaust and transaction routing.
For Market Incumbents: Insulate core installer relationships through exclusive data-sharing agreements that embed your catalog into shop management system workflows. Defend against Amazon's same-day encroachment by expanding proprietary VIN fitment database coverage beyond competitive matching. Capacity addition in Nuevo León manufacturing corridors secures cross-border fulfillment advantage for Texas and California market penetration. For New Entrants and Emerging Players: Pursue white-space capture in professional installer channel software, where incumbent DMS integration lags and API openness creates platform insertion opportunity. Target Mexico-based fulfillment networks serving US border states as the most penetrable geography given manufacturing proximity and compressed lead-time advantage. Go-to-market through telematics provider partnerships embeds procurement triggers directly into vehicle operating systems. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet telematics-integrated procurement platforms, where subscription-based parts replenishment displaces transactional purchasing. Long-term viability favors acquirers of VIN-specific fitment engine technology and installer relationship networks over pure logistics plays. Signal to monitor: FTC enforcement patterns on all-in pricing disclosure and state franchise law preemption attempts that reshape direct-to-consumer vehicle sales permissibility.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Embedded procurement triggers in Samsara and Geotab systems collapse manual reorder cycles into automated inventory management. |
| VIN Fitment Engine Acquisition | Proprietary compatibility databases differentiate platform user experience and reduce return rate exposure. |
| Mexico Cross-Border Fulfillment Buildout | Manufacturing proximity enables same-day coverage of Texas and California markets with compressed landed costs. |
| Professional Installer Channel Partnership | Shop management system integration captures recurring B2B demand with higher lifetime value than consumer transactions. |
| FTC Compliance Infrastructure Investment | All-in pricing disclosure capabilities create regulatory separation from legacy dealer sites adapting to Combating Auto Retail Scams Rule mandates. |
Research Methodology
A standing panel of fleet procurement directors, aftermarket distributor operations heads, OEM platform engineers, and dealership digital strategy leads provided ongoing calibration against market developments. Primary interviews with Tier 1 supplier procurement teams and telematics provider product managers combined with secondary validation from NHTSA recall databases, EPA emissions certification filings, SEC 10-K disclosures from public auto parts retailers, and IHS Markit vehicle registration data. Bottom-up channel volume estimates triangulated against top-down consumer spending allocation models across the analysis window.
Scenario-bracketing around IRA EV credit phase-out schedules and state franchise law preemption probabilities bounded the projection horizon. Segmentation dimensions modeled include product type, sales channel architecture, customer procurement sophistication, and delivery model density. CAGRs derived from logistic curve adoption modeling for telematics-integrated fleet procurement, cross-referenced with historical e-commerce penetration patterns in adjacent industrial categories. Forecast inputs incorporated dealer management system upgrade cycles and FTC enforcement intensity projections.
Sensitivities concentrate around IRA credit extension decisions, Texas and Michigan franchise law litigation outcomes, and Amazon fulfillment network expansion pace. Forecasts reflect assumptions on telematics adoption curves and platform interoperability standards that could shift with regulatory or competitive dynamics. Macroeconomic contraction, accelerated FTC disclosure mandates, or breakthroughs in autonomous vehicle maintenance automation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Global B2B E-Commerce Market
E-Commerce Solutions
India D2C E-Commerce Market
E-Commerce Solutions
Taiwan E-Commerce Market
E-Commerce Solutions
North America FMCG B2B E-Commerce Market
E-Commerce Solutions
Alcohol E-Commerce Market
E-Commerce Solutions
South Korea Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
Asia Pacific B2B E-Commerce Market
E-Commerce Solutions
Vietnam E-Commerce Market
E-Commerce Solutions
North America Dropshipping Market
E-Commerce Solutions
Japan Same Day Delivery Market
E-Commerce Solutions
Poland E-Commerce Market
E-Commerce Solutions
Asia-Pacific E-Commerce Apparel Market
E-Commerce Solutions
Spain E-Commerce Logistics Market
E-Commerce Solutions
Italy Dropshipping Market
E-Commerce Solutions
T-Commerce Market
E-Commerce Solutions
Norway E-Commerce Market