
 Hotel Furniture and Furnishing Market | 2026-2036
Hotel Furniture and Furnishing Market Size, Share, and Industry Trends Forecast 2026-2036
Hotel Furniture and Furnishing Market Insights
REACH is hardening chemical disclosure requirements for foam and textile suppliers serving European hotel projects. Kimball Hospitality leverages captive North American manufacturing to bypass extended lead times from Asian upholstery mills. Bernhardt Hospitality anchors its position through dedicated hospitality design studios that bypass traditional furniture retail channels.
Hotel furniture and furnishing encompasses durable goods engineered for high-cycle commercial environments, typically incorporating fire-retardant foams, commercial-grade vinyls, and hardwood frames with reinforced joinery rated for institutional use. These products outfit guest rooms, lobbies, and food-service areas in properties where replacement cycles run seven to ten years under intensive daily use. Seating commands the largest revenue pool across product types due to frequent refresh cycles in public areas, while upholstered goods in luxury hotels carry the widest margin spreads because of custom fabric programs and designer licensing fees. Wood dominates material volumes for case goods and bed frames, though metal frames gain share in budget properties seeking lower total cost of ownership.
FDA oversight of antimicrobial surface claims affects textile marketing for healthcare-adjacent hospitality properties, while EPA regulations on formaldehyde emissions from composite wood products shape panel sourcing for case goods manufacturers. California's Bureau of Electronic and Appliance Repair monitors compliance with state-level flammability mandates that de facto set the North American standard for upholstered furniture. Stakeholders must track evolving extended producer responsibility frameworks in the European Union that will impose end-of-life collection obligations on furniture suppliers serving hotel renovation projects.
Market Dynamics
Boutique hotel chains in urban centers are expanding procurement budgets for custom interiors, compressing traditional seven-to-ten-year replacement cycles into five-year refreshes as experiential hospitality redefines competitive positioning.
Growth Catalysts
- California's TB 117-2013 flammability standards:These mandates have de facto standardized North American upholstered goods compliance, creating uniform material specifications that reduce cross-border friction for hospitality suppliers.
- Healthcare-adjacent hospitality properties:FDA oversight of antimicrobial surface claims is driving textile innovation for extended-stay and wellness-focused hotels seeking differentiation through certified hygiene protocols.
- Active hospitality construction pipelines:Concentrated development in the United States, China, and Germany sustains forward demand visibility for case goods and seating manufacturers with regional manufacturing footprints.
Market Restraints
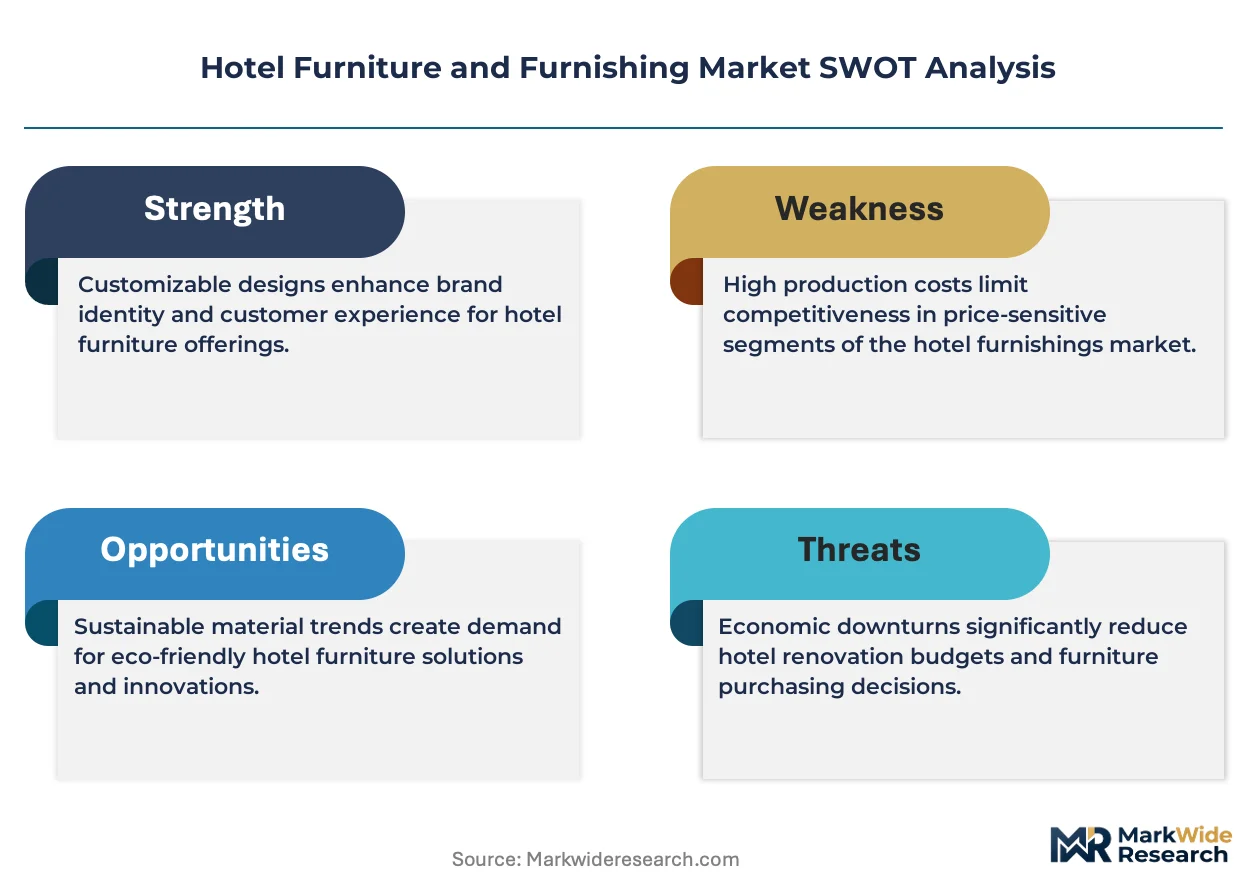
- REACH chemical disclosure hardening:ECHA requirements for foam and textile suppliers serving European hotel projects are elevating compliance documentation burdens and extending qualification timelines for new material introductions.
- Extended lead times from Asian upholstery mills:Ocean freight volatility and concentrated offshore production capacity create inventory risk for North American hotel developers with fixed opening dates.
- Formaldehyde emission regulations:EPA rules on composite wood products constrain panel sourcing flexibility for case goods manufacturers, particularly affecting budget property segments dependent on engineered substrates.
Strategic Opportunities
- Extended producer responsibility frameworks:EU end-of-life collection obligations on furniture suppliers create first-mover advantage for manufacturers with established refurbishment and take-back infrastructure serving hotel renovation projects.
- Captive North American manufacturing:Regional production bypasses offshore lead time exposure and qualifies suppliers for domestic content preferences in publicly financed hospitality developments.
- Metal frame bed construction:Budget properties seeking lower total cost of ownership are accelerating adoption of metal over wood, opening volume contracts for specialized fabrication capacity.
Industry Challenges
- Fire-retardant foam chemistry transitions:Reformulation to meet evolving state-level mandates without sacrificing performance durability requires sustained R&D coordination between chemical suppliers and upholstery manufacturers.
- Commercial-grade vinyl specification complexity:Designer licensing fees and custom fabric programs in luxury hotels create SKU proliferation that strains production scheduling and inventory management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hotel Furniture and Furnishing Market |
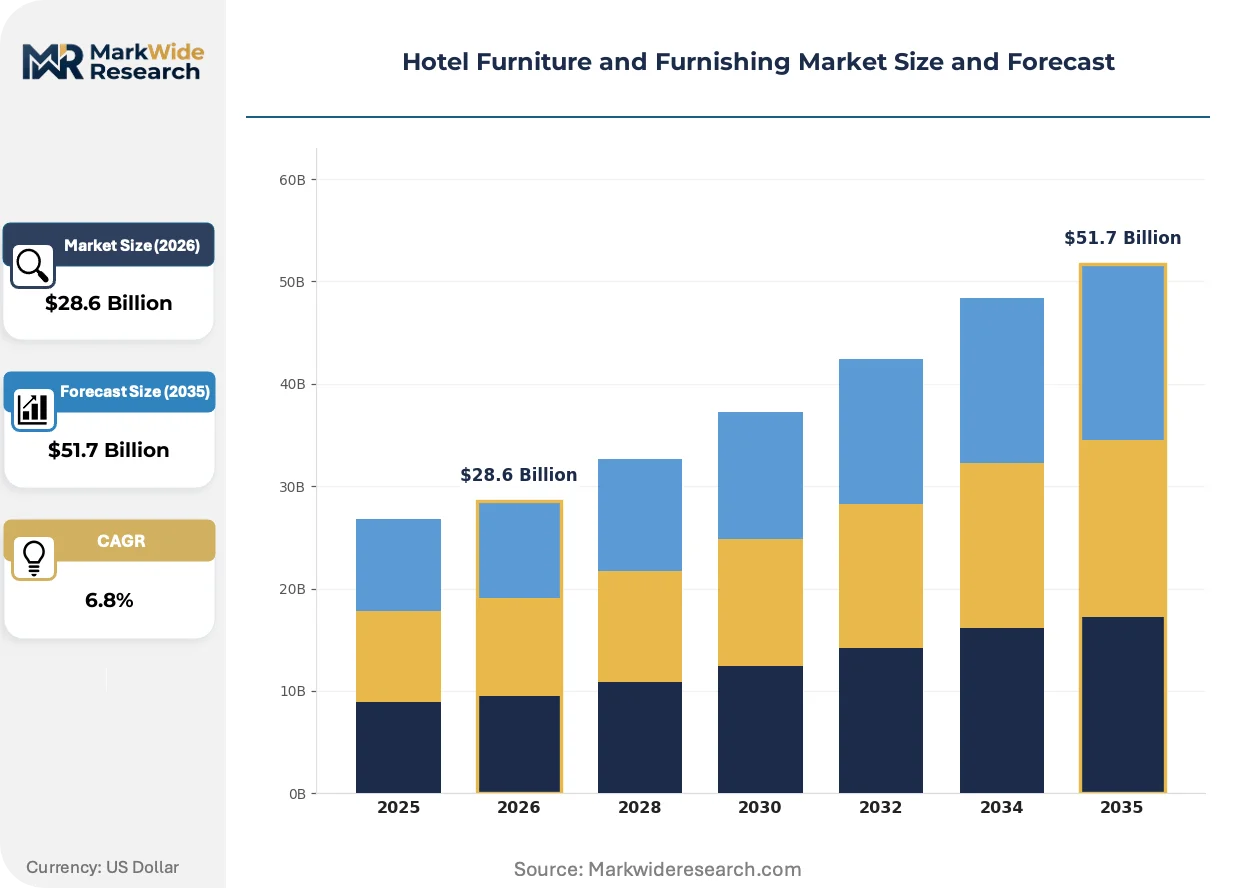
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seating, Tables, Beds, Storage Units Material: Wood, Metal, Upholstered, Plastic End User: Luxury Hotels, Budget Hotels, Resorts, Motels Style: Modern, Vintage, Contemporary, Rustic |
| Companies Covered | Kimball Hospitality, Artone Furniture, Sara Hospitality, Harman Furnishings, Bernhardt Hospitality, Beaufurn, Curve Hospitality, Northland Furniture, Dickson Furniture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hotel Furniture and Furnishing Market Trends and Innovations
Material science advances and regulatory stringency are converging to reshape how hospitality furnishings are specified, manufactured, and certified across property tiers.
Modular case goods systems with interchangeable veneer panels and hardware-standardized frames are overtaking fixed-configuration furniture in select-service hotels. Property operators in the United States are adopting these systems to enable in-house refresh capabilities without full replacement. The technology is compressing capital expenditure timing flexibility and reducing downtime during property renovations.
REACH chemical disclosure requirements for foam and textile suppliers are hardening disclosure thresholds for substances of very high concern. European hotel projects now demand full material passports extending through supply chain tiers. Upholstered goods manufacturers serving luxury hospitality in Germany and France are consolidating supplier bases to reduce documentation burden.
Direct specification relationships between hotel ownership groups and dedicated hospitality design studios are displacing traditional furniture retail intermediaries. Ownership entities with multi-property portfolios are centralizing procurement functions to extract volume leverage and standardize brand expression. This pattern concentrates most visibly in United States urban markets where boutique chains compete on interior distinctiveness.
Hotel Furniture and Furnishing Market Segmentation
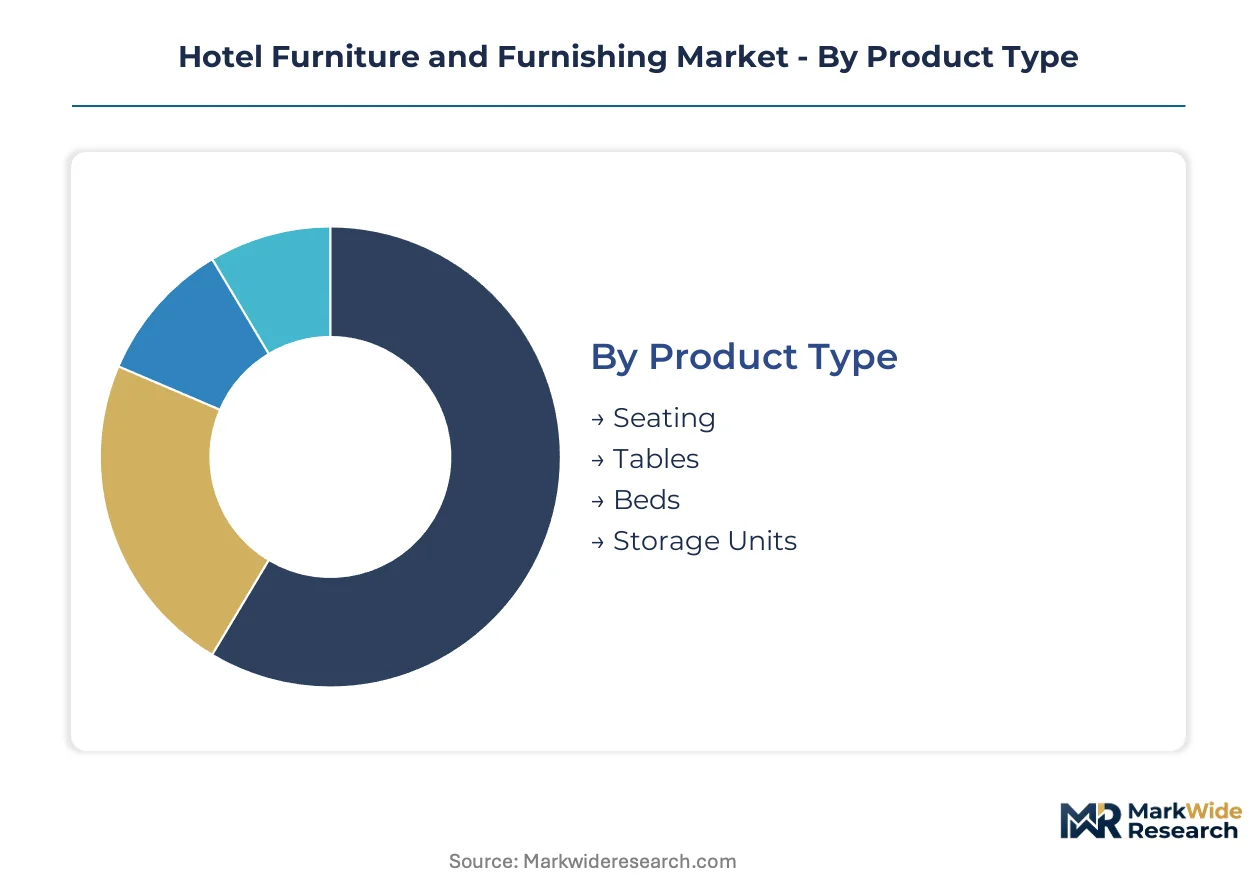
Segmentation in hotel furniture and furnishing reveals how procurement decisions split across durability requirements, aesthetic positioning, and property-tier economics. Specification patterns differ sharply between luxury properties pursuing custom designer programs and budget operators optimizing replacement cycles.
Product Type:
Specification intensity varies by traffic exposure and replacement frequency across guest-facing installations.
- Seating:Commercial-grade frames with reinforced joinery and fire-retardant foam cores dominate lobby and food-service specifications. Demand concentrates in United States urban boutique properties where five-year refresh cycles have displaced traditional seven-to-ten-year timelines.
- Beds:Platform frames with metal reinforcement or solid hardwood construction support intensive daily use requirements. Budget properties in Germany and China are accelerating metal frame adoption to reduce total cost of ownership over extended holding periods.
- Tables:Engineered substrates with commercial-grade laminates balance cost and durability for food-service and in-room work surfaces.
- Storage Units:Modular case goods with interchangeable veneer panels enable in-house refresh capabilities without full replacement.
Mature deployment sits with Seating. Newer deployment is concentrated in Storage Units.
Material:
Cost tier and compliance burden shape material selection across property categories and geographic markets.
- Upholstered:Fire-retardant foams and commercial-grade vinyls rated for institutional use comprise core specifications. California's TB 117-2013 standards have de facto standardized North American compliance, creating uniform material specifications that reduce cross-border friction.
- Wood:Hardwood frames with reinforced joinery dominate case goods and bed construction in luxury segments. EPA formaldehyde emission regulations constrain panel sourcing flexibility, particularly affecting budget properties dependent on engineered substrates.
- Metal:Specialized fabrication capacity serves budget hotel chains seeking durability at lower lifecycle cost.
- Plastic:Polymer composites address outdoor and high-moisture applications in resort properties.
Wood commands established specification share. Plastic is climbing the fastest as resort operators seek weather-resistant alternatives.
End User:
Customer type determines margin structure, customization depth, and procurement centralization patterns.
- Luxury Hotels:Custom fabric programs and designer licensing fees generate widest margin spreads through exclusive upholstery specifications. Direct relationships between ownership groups and dedicated hospitality design studios are displacing traditional furniture retail intermediaries in United States urban markets.
- Budget Hotels:Standardized SKUs and volume contracts prioritize total cost of ownership over aesthetic differentiation. Procurement functions centralize across multi-property portfolios to extract volume leverage.
- Resorts:Extended outdoor exposure and wellness-focused amenities drive antimicrobial textile innovation and weather-resistant material specifications.
- Motels:Limited-service properties with minimal public areas concentrate furniture spend on guest room durability.
Budget Hotels anchor volume demand. Luxury Hotels are gaining share fastest on boutique expansion in urban centers.
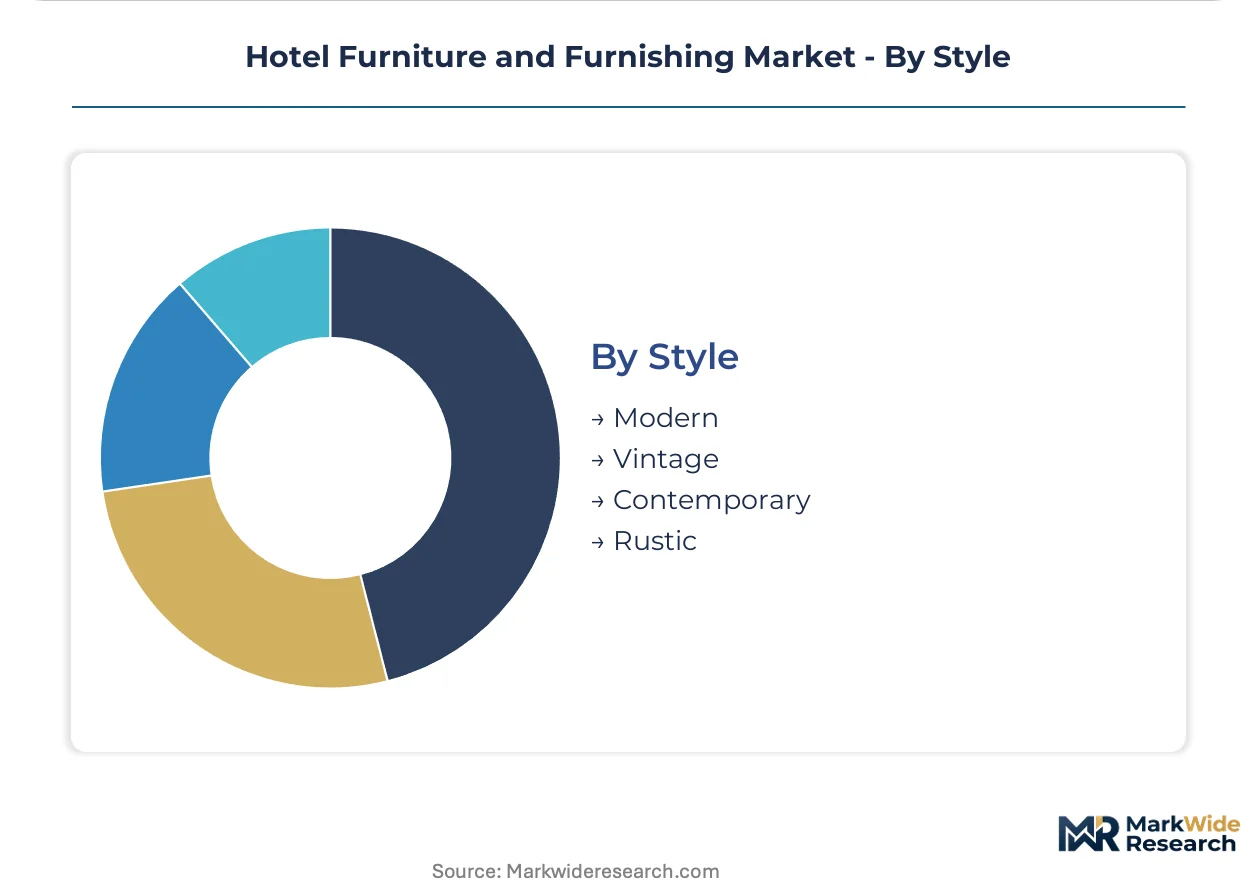
Style:
Aesthetic positioning maps to property brand architecture and target guest demographics.
- Modern:Clean lines and minimal ornamentation align with select-service and business-travel-focused properties in Germany and China.
- Contemporary:Updated interpretations of classic forms balance familiarity and freshness for mid-tier urban properties.
- Vintage:Period-accurate reproductions and curated antique integrations serve experiential hospitality positioning in United States boutique chains.
- Rustic:Natural materials and craft-oriented detailing target leisure travelers in resort and destination properties.
Contemporary styling holds established specification share. Vintage is expanding most quickly as experiential hospitality redefines competitive positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for hotel furniture and furnishing concentrates in the United States, China, and Germany where hospitality construction pipelines remain most active. Boutique hotel chains in urban centers across these markets are expanding procurement budgets for custom interiors. Regulatory fragmentation around flammability standards and chemical disclosure is reshaping supplier qualification requirements by geography.
United States
Boutique hotel chains in New York, Los Angeles, and Miami are compressing traditional seven-to-ten-year replacement cycles into five-year refreshes. California's Bureau of Electronic and Appliance Repair enforces TB 117-2013 flammability standards that de facto set the North American standard for upholstered furniture. Kimball Hospitality leverages captive North American manufacturing to bypass extended lead times from Asian upholstery mills serving these urban developments.
China
Hospitality construction in Shanghai, Beijing, and Shenzhen sustains forward demand visibility for case goods and seating manufacturers. The Ministry of Ecology and Environment (MEE) oversees dual carbon goals that shape material sourcing compliance for furniture exports. Guangdong and Zhejiang provinces host concentrated upholstery mill capacity serving both domestic hotel development and North American export contracts.
Germany
Luxury hospitality projects in Berlin, Munich, and Frankfurt drive specification intensity for custom fabric programs and designer licensing fees. ECHA requirements under REACH harden chemical disclosure thresholds for foam and textile suppliers serving European hotel projects. The Baden-Württemberg region anchors specialized fabrication capacity for metal frame bed construction gaining share in budget property segments.
United Kingdom
London's boutique hotel sector competes on interior distinctiveness through direct specification relationships with dedicated hospitality design studios. The UK's national standards body enforces product safety regulations that align with evolving EU chemical disclosure frameworks. Manchester and Birmingham are emerging as secondary hubs for hospitality refurbishment projects targeting experiential positioning.
United Arab Emirates
Dubai and Abu Dhabi hospitality developments prioritize antimicrobial textile innovation for wellness-focused amenities in extended-stay properties. MOHAP oversees product safety standards affecting furniture imports for healthcare-adjacent hospitality projects. The emirates' construction pipeline concentrates procurement demand for weather-resistant materials in resort properties along the coastline.
Hotel Furniture and Furnishing Market Competitive Landscape
North American producers anchor one tier; European and Asian specialists hold differentiated positions in material compliance and cost structure. The vendor base spans vertically integrated manufacturers with captive upholstery capacity, design-forward studios bypassing retail channels, and regional fabricators serving budget property segments. Three archetypes dominate: compliance-focused manufacturers with regulatory expertise, design-centric studios with direct ownership group relationships, and scale-driven operators with modular system platforms. M&A activity concentrates on upholstery capacity acquisition, while strategic partnerships target end-of-life collection infrastructure for EU extended producer responsibility compliance.
Among North American hospitality specialists, Kimball Hospitality, Bernhardt Hospitality, and Beaufurn occupy positions across the premium and mid-market tiers. Kimball Hospitality exemplifies the captive manufacturing archetype with regional production footprints qualifying for domestic content preferences. Bernhardt Hospitality represents the design-studio model through dedicated hospitality channels that bypass traditional furniture retail intermediaries. Beaufurn sits within the compliance-specialist category, navigating California's flammability mandates and FDA antimicrobial surface claim requirements for healthcare-adjacent properties.
| Leading Market Players |
|---|
| Kimball Hospitality |
| Artone Furniture |
| Sara Hospitality |
| Harman Furnishings |
| Bernhardt Hospitality |
| Beaufurn |
| Curve Hospitality |
| Northland Furniture |
| Dickson Furniture |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up hospitality specialists have consolidated fragmented regional fabricators, tightening pricing discipline through volume leverage while compressing supplier payment terms to offset raw material inflation. This ownership pattern concentrates procurement power among multi-property ownership groups in United States urban markets, forcing case goods and seating manufacturers to absorb freight volatility or risk contract loss.
Pricing Analysis
Premium pricing for sub-twelve-week lead times dominates contract negotiations, while spot inventory of standard SKUs clears at discounted rates. Three-tier pricing structure across premium, standard, and economy levels separates luxury properties with custom fabric programs from budget chains optimizing total cost of ownership. Pricing pressure stems from ocean freight volatility and concentrated Asian upholstery capacity, squeezing margins on fixed-price contracts. Budget hotel chains exhibit highest price sensitivity, while boutique luxury properties prioritize lead time certainty over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Guangdong and Zhejiang provinces in China, where concentrated upholstery mill capacity serves North American export demand. The supply chain draws from Malaysian hardwood, Chinese engineered substrates, and Texan fire-retardant foam chemistry. Tariff exposure on finished furniture imports creates inventory risk for developers with fixed opening dates. Distribution runs through ownership group procurement offices and dedicated hospitality design studios, bypassing traditional furniture retail intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from REACH documentation burdens and California flammability compliance costs will force sub-scale upholstery manufacturers toward exit or acquisition. Surviving players must build regulatory expertise and captive regional production to defend position.
For Market Incumbents: Cement market position through backward integration into fire-retardant foam chemistry and captive North American manufacturing capacity. Acquire distressed European upholstery specialists to secure REACH-compliant supplier bases before extended producer responsibility frameworks impose end-of-life collection obligations. Threat substitution from modular case goods systems demands R&D investment in interchangeable veneer panel technology. For New Entrants and Emerging Players: Capture white-space in metal frame bed construction for budget properties in Germany and China seeking lower lifecycle cost. Target refurbishment and take-back services for EU hotel renovation projects as first-mover advantage under emerging extended producer responsibility mandates. Go-to-market through direct relationships with multi-property ownership groups centralizing procurement functions. For Investors and Strategic Acquirers: ECHA enforcement actions against non-compliant foam suppliers are the leading indicator that regulatory capacity will become a scarce, defensible asset. Position for five-to-ten year viability by targeting mid-cap upholstery manufacturers with established North American production footprints and documented REACH compliance infrastructure. Watch for consolidation signals when private-equity ownership groups seek exit liquidity from rolled-up regional fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| Captive North American Manufacturing | Qualifies suppliers for domestic content preferences in publicly financed hospitality developments. |
| REACH-Compliant Supplier Consolidation | Reduces documentation burden for foam and textile suppliers serving European luxury hotel projects. |
| End-of-Life Collection Infrastructure | Positions manufacturers for EU extended producer responsibility obligations on hotel renovation contracts. |
| Fire-Retardant Chemistry R&D Partnership | Enables reformulation to meet California TB 117-2013 mandates without sacrificing foam performance durability. |
| Direct Ownership Group Relationships | Bypasses traditional furniture retail intermediaries in United States urban boutique hotel markets. |
Research Methodology
Multi-period observation of hospitality construction permits, upholstery mill capacity utilization, and ownership group procurement centralization anchored the trend analysis, supplemented by interviews with hotel development executives, procurement directors at multi-property portfolios, upholstery manufacturing plant managers, and dedicated hospitality design studio principals. Secondary validation drew from EPA formaldehyde emission filings, ECHA REACH substance registrations, California Bureau of Electronic and Appliance Repair compliance notices, and customs trade data on furniture imports. Bottom-up property-level demand estimates triangulated against top-down construction pipeline valuations.
Input-output matrices mapped case goods and seating demand to active hospitality construction in United States, China, and Germany across the analysis window. Segmentation dimensions modeled include product type, material composition, property tier, and regional regulatory cluster. CAGRs derived from curve-fitting historical replacement cycle compression and forward pipeline visibility. Industry-specific forecast inputs incorporated boutique hotel expansion rates and metal frame adoption trajectories in budget segments.
The model holds under stable regulatory enforcement intensity and continued ocean freight volatility; deviation in tariff policy or ECHA disclosure threshold tightening would shift supplier qualification timelines and pricing dynamics. Forecasts reflect documented assumptions regarding construction pipeline completion rates and ownership group consolidation patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hotels and Resorts
Philippines Tourism and Hotel Market
Hotels and Resorts
United Kingdom HRI Market
Hotels and Resorts
Global Floating Hotels Market
Hotels and Resorts
Hotel Armchair Market
Hotels and Resorts
Five Star Hotel Market
Hotels and Resorts
Europe Luxury Hotel Market
Hotels and Resorts
Spain HRI Market
Hotels and Resorts
Spa Resorts Market
Hotels and Resorts
India Luxury Hotel Market
Hotels and Resorts
Morocco Tourism Market
Hotels and Resorts
Boutique Hotels Market
Hotels and Resorts
Germany HRI Market
Hotels and Resorts
Global Beach Hotels Market
Hotels and Resorts
Cuba Tourism and Hotel Market
Hotels and Resorts
Hotels, Resorts, and Cruise Lines Market
Hotels and Resorts
Morocco Hospitality Market