
 North America Denim Jeans Market | 2026-2036
North America Denim Jeans Market Size, Share, and Industry Trends Forecast 2026-2036
North America Denim Jeans Market Insights
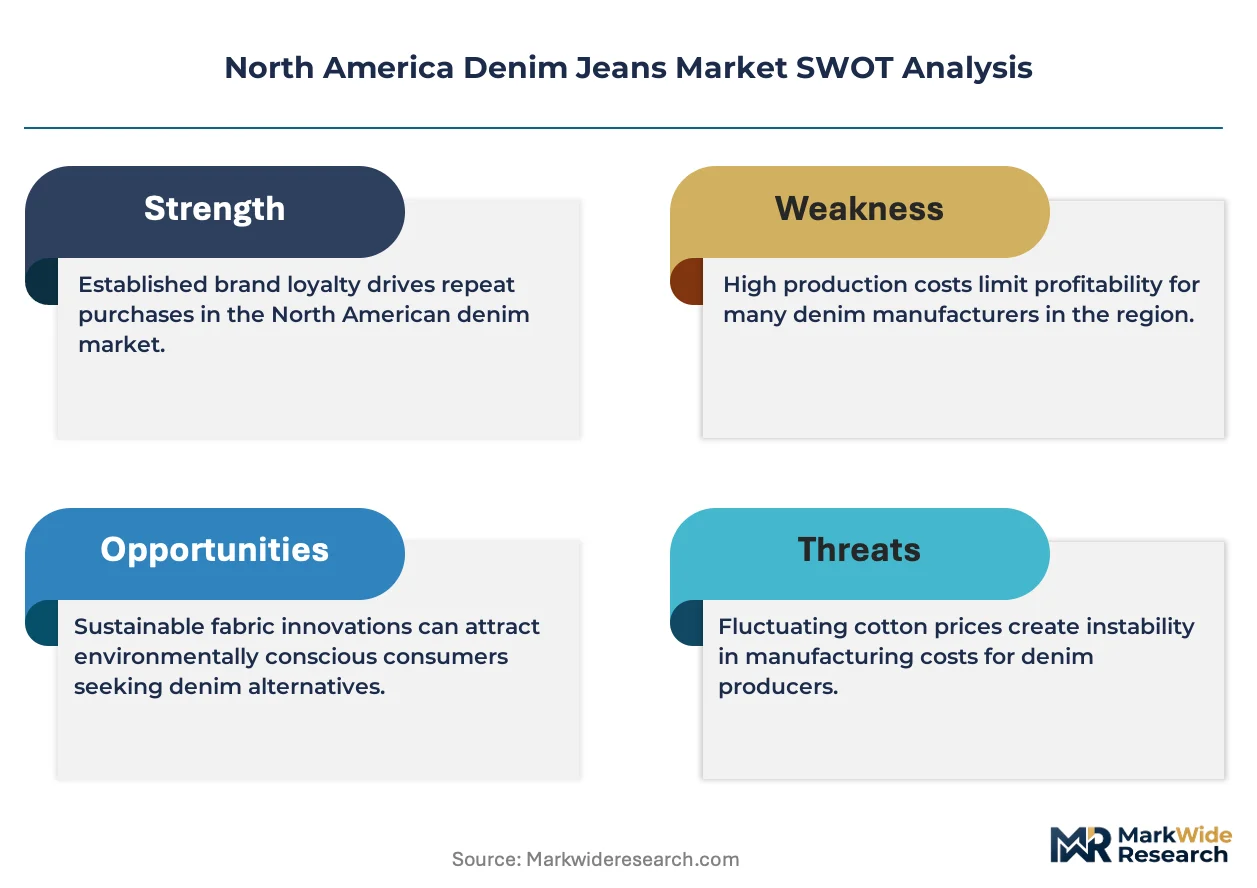
Premium selvedge and rigid raw denim is redrawing competitive boundaries in the North America denim jeans market. Levi Strauss & Co. leverages its vertical manufacturing heritage to command heritage pricing power across wholesale and direct-to-consumer channels. Kontoor Brands, Inc. anchors its Wrangler portfolio in workwear-adjacent denim, competing on durability specifications that sustain loyalty in rural and industrial buyer segments. American Eagle Outfitters Inc. specializes in stretch-innovated fits targeting younger demographics, extending its dominance in mall-based specialty retail.
Denim jeans are cotton twill trousers constructed with warp-faced weaving where indigo-dyed warp yarns cross undyed weft yarns, creating the characteristic diagonal ribbing and fade patterns that define the garment's aesthetic and functional appeal. The fabric typically incorporates elastane blends of two to four percent for stretch recovery, enabling form-fitting silhouettes without sacrificing structural integrity through repeated wear cycles. Women's denim leads volume contribution across gender segmentation, while premium and luxury price tiers concentrate margin pools as consumers trade upward on durability and provenance claims. Online distribution channels represent the fastest-growing outlet, though offline specialty stores retain outsized influence in fit verification and brand storytelling for full-price transactions.
The EPA enforces wastewater discharge standards under the Clean Water Act that constrain denim finishing operations, while California's Safer Consumer Products regulations mandate chemical hazard assessments affecting dye formulations and finishing treatments. FTC textile labeling rules govern fiber content disclosures, shaping how brands communicate sustainability credentials to avoid greenwashing liability. Stakeholders must monitor how state-level extended producer responsibility proposals and federal trade enforcement on cotton sourcing reshape cost structures and supply chain geography across the continent.
Market Dynamics
Waterless dyeing and laser finishing technologies are compressing the capital intensity gap between established mills and agile entrants across California's denim manufacturing corridor. The EPA's Clean Water Act enforcement is forcing operational choices that favor technology-forward suppliers.
Growth Catalysts
- EPA Wastewater Standards:The Clean Water Act's discharge limits are accelerating capital deployment into closed-loop dyeing systems. Mills adopting these technologies capture preferential supplier status with sustainability-focused brands.
- Stretch-Elastane Blends:Two-to-four-percent elastane integration enables form-fitting silhouettes without structural degradation. Women's fashion denim absorbs these innovations fastest, expanding average unit revenue per garment.
- Los Angeles Apparel Cluster:Concentrated sustainable manufacturing investment in Southern California creates supplier density that reduces logistics costs for West Coast distribution.
Market Restraints
- Cotton Price Volatility:Raw fiber input costs swing with climate-driven harvest uncertainty and trade enforcement on sourcing geography. Margin pressure concentrates in mid-tier price bands lacking pricing power.
- Mexican Nearshoring Concentration:Cut-make-trim capacity clustering in specific border zones exposes the supply base to localized disruption from logistics bottlenecks or labor actions.
- Finishing Chemistry Limitations:California's Safer Consumer Products regulations constrain potassium permanganate and other traditional distressing agents. Alternative chemistries extend processing timelines and raise unit costs.
Strategic Opportunities
- Canadian Market Underpenetration:Premium selvedge and rigid raw denim hold smaller share in Canadian specialty retail versus US comparable markets. Direct-to-consumer expansion targets Toronto and Vancouver urban corridors.
- Secondhand Channel Integration:Resale platform partnerships enable brands to capture margin from circular consumption without inventory risk. Authentication technology investments defend brand equity in peer-to-peer transactions.
- IRA Clean Manufacturing Credits:Domestic production incentives under the Inflation Reduction Act offset capital expenditure for solar-powered finishing facilities in qualifying US locations.
Industry Challenges
- Digital Pattern-Making Talent Scarcity:3D prototyping and virtual sampling require specialized technical skills that outpace vocational training pipeline output. Brands compete for limited candidates with software and gaming industries.
- Size-Inclusive Fit Complexity:Expanded size grading demands additional pattern development and fit testing cycles. Sampling costs multiply while speed-to-market expectations compress.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Denim Jeans Market |
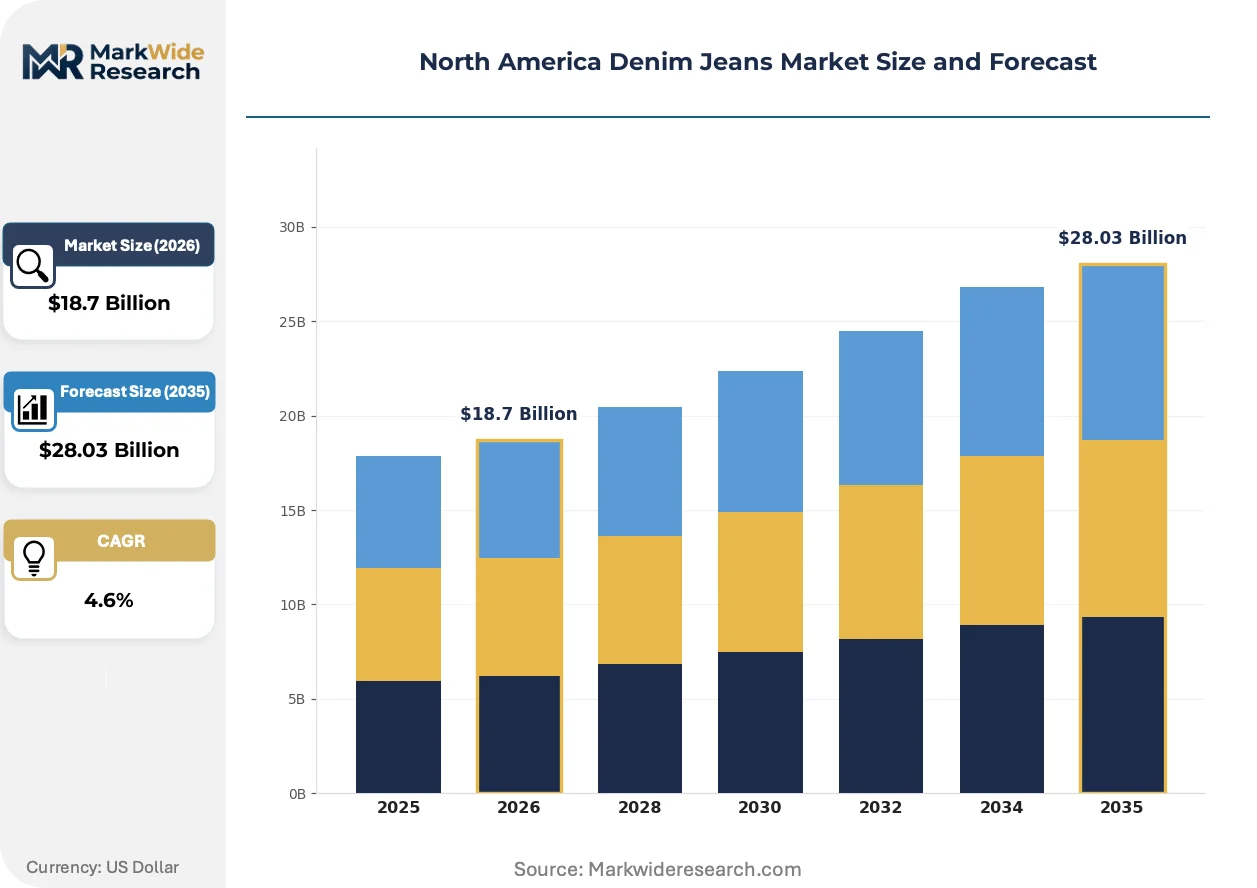
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skinny, Bootcut, Straight, Relaxed Gender: Men, Women, Boys, Girls Distribution Channel: Online, Offline, Department Stores, Specialty Stores Price Tier: Budget, Mid-range, Premium, Luxury |
| Companies Covered | Levi Strauss & Co., Kontoor Brands, Inc., PVH Corp., The Gap, Inc., American Eagle Outfitters Inc., VF Corporation, United States Polo Association, OTB Group, H&M Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Denim Jeans Market Trends and Innovations
Laser-based surface finishing and ozone washing are displacing water-intensive chemical processes across North American denim production. These shifts compress environmental compliance costs while enabling design precision that manual techniques cannot replicate.
Ozone finishing technology is miniaturizing from industrial tunnel configurations to modular cell units suitable for mid-scale vertical operations. Regional boutique manufacturers in California and Texas are adopting these systems to offer custom distressing services. The technology is miniaturizing capital barriers that previously locked small-batch production out of premium finishing capabilities.
The EPA's effluent limitation guidelines under the Clean Water Act are tightening discharge parameters for textile wet processing. Mills in Los Angeles County face enforcement priority that accelerates zero-liquid-discharge system adoption. Premium and heritage-tier brands with captive or preferred mill relationships absorb compliance costs most effectively, widening capability gaps against price-competitive imports.
Specialty retail's fit verification function is fragmenting across digital try-on tools and home trial programs. Younger demographics in US coastal metros lead adoption of augmented-reality sizing applications that reduce return rates. Mall-based specialty stores respond by emphasizing tactile fabric experience and alteration services that pure-play e-commerce cannot replicate.
North America Denim Jeans Market Segmentation
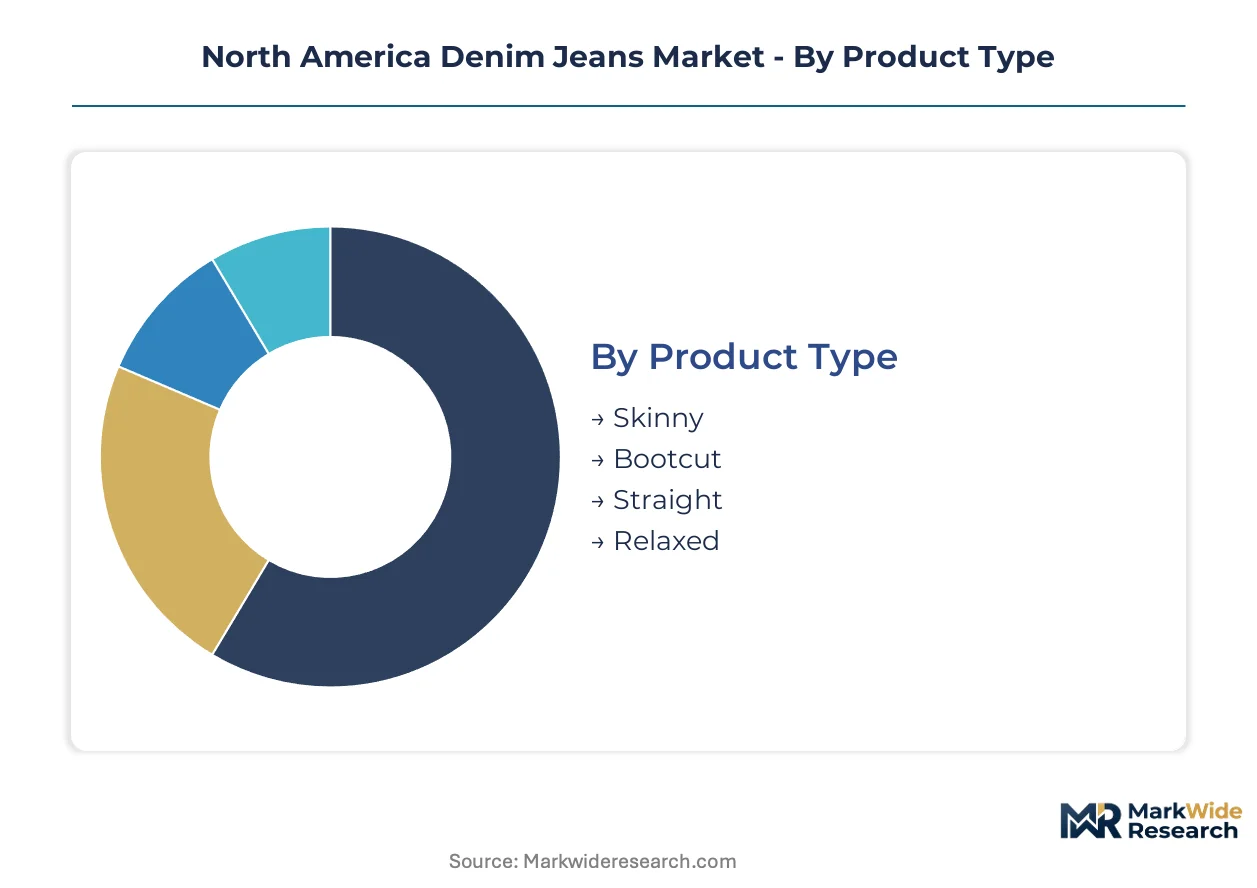
Denim jeans segmentation in North America tracks how fit preferences, gender-based styling, and channel economics fragment demand across distinct margin pools. Understanding these divisions reveals where stretch-innovation investments concentrate and which price tiers absorb sustainability premiums.
Product Type:
Channel mix varies sharply by silhouette, with skinny fits dominating online conversion while rigid styles depend on specialty retail for tactile verification.
- Skinny:High elastane content, typically two to four percent, enables compression fits that drive women's fashion denim volume. California's Los Angeles apparel cluster processes the bulk of stretch-denim finishing for this segment, with laser-based surface treatments reducing water intensity.
- Straight:Balanced warp-weft construction suits workwear-adjacent applications and cross-gender styling. Demand concentrates in Texas and Midwest industrial corridors where durability specifications outweigh stretch recovery preferences.
- Bootcut:Flared leg openings accommodate western and rodeo-adjacent styling traditions. Regional boutique manufacturers in border states serve this niche through small-batch vertical operations.
- Relaxed:Generous seat and thigh measurements prioritize comfort over form. This silhouette captures volume in rural and industrial buyer segments through mass-market department store channels.
Straight fits dominate installed base across age demographics. Skinny is where expansion concentrates, though growth rates are moderating as wide-leg alternatives gain traction.
Gender:
Margin structures diverge by gender, with women's denim commanding higher average unit revenue through faster fashion cycles and stretch-premium acceptance.
- Women:Fashion-forward styling demands drive seasonal refresh rates and premium pricing power. Toronto and Vancouver urban corridors in Canada show underpenetration versus US comparable markets, creating direct-to-consumer expansion targets.
- Men:Heritage and rigid raw denim loyalty sustains full-price transactions in specialty retail. EPA wastewater standards under the Clean Water Act favor suppliers with closed-loop dyeing systems that serve this durability-focused segment.
- Boys:Growth-out replacement cycles create volume concentration in back-to-school seasonal windows. Mass-market retailers capture this demand through private-label programs.
- Girls:Trend responsiveness matches women's segment dynamics at lower price points. Mall-based specialty stores retain outsized influence through in-store try-on and immediate gratification.
Women's denim dominates installed base by volume contribution. Girls' and boys' segments are where expansion concentrates through size-inclusive grading investments.
Distribution Channel:
Cost tier alignment shapes channel strategy, with premium and luxury price tiers avoiding department store dilution while budget segments depend on mass-market scale.
- Online:Pure-play e-commerce and brand direct-to-consumer sites represent the steepest expansion trajectory, driven by augmented-reality sizing tools that reduce return rates in US coastal metros. Authentication technology investments defend brand equity in peer-to-peer resale transactions.
- Specialty Stores:Tactile fabric experience and alteration services create defensible positioning against digital competitors. California's San Francisco apparel cluster feeds this channel with sustainable manufacturing credentials.
- Department Stores:Mid-range price tier concentration exposes this channel to cotton price volatility margin pressure. Consolidation among national chains is reshaping supplier negotiation leverage.
- Offline (Other):Factory outlets and off-price channels absorb excess inventory from full-price distribution. FTC textile labeling rules govern fiber content disclosures even in discounted transactions.
Specialty stores dominate installed base for full-price premium transactions. Online is where expansion concentrates, though fit verification friction persists for rigid selvedge purchases.
Price Tier:
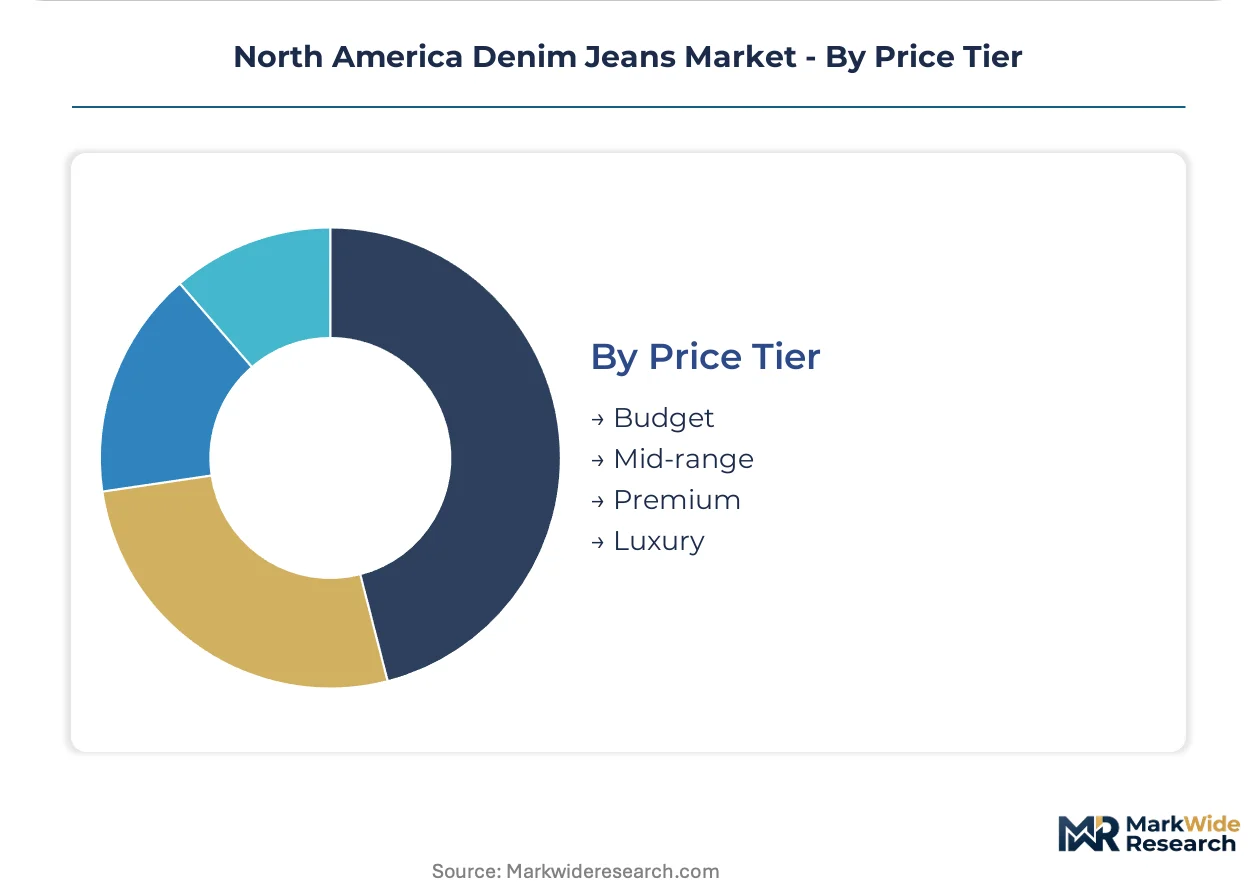
Supply concentration determines tier accessibility, with Los Angeles County mills capturing premium and luxury volume through zero-liquid-discharge compliance while price-competitive imports serve budget tiers.
- Premium:Selvedge construction and provenance claims justify heritage pricing power. Inflation Reduction Act clean manufacturing credits offset capital expenditure for solar-powered finishing facilities serving this tier.
- Mid-range:Stretch-elastane blends balance performance and accessibility. Mexican nearshoring concentration in specific border zones exposes this cost-optimized tier to localized logistics disruption.
- Luxury:Limited production runs and artisanal finishing command margin pools insulated from cotton price swings. California's Safer Consumer Products regulations constrain traditional distressing chemistries, extending processing timelines.
- Budget:Volume scale and standardized fits minimize sampling cost multiplication. Extended producer responsibility proposals at state level threaten to reshape cost structures for disposable-fashion economics.
Mid-range dominates installed base by unit volume. Premium is where expansion concentrates as consumers trade upward on durability claims and environmental compliance transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import flows from Mexican cut-make-trim facilities dominate supply to the United States, while Canadian demand draws from both domestic mills and cross-border wholesale channels. Export volumes from Los Angeles-based specialty manufacturers serve premium retail in Japan and Western Europe.
United States
California's Los Angeles and San Francisco apparel clusters absorb the bulk of sustainable manufacturing investment, with EPA Clean Water Act enforcement accelerating zero-liquid-discharge system adoption. The Inflation Reduction Act's clean manufacturing credits offset capital expenditure for solar-powered finishing facilities in qualifying locations. Texas and Midwest industrial corridors sustain demand for workwear-adjacent denim through durability-focused buyer segments.
Canada
Toronto and Vancouver urban corridors show underpenetration in premium selvedge and rigid raw denim versus comparable US markets, creating direct-to-consumer expansion targets. Health Canada's textile labeling regulations govern fiber content disclosures, shaping how brands communicate sustainability credentials. Ontario-based distribution centers serve as entry points for US heritage brands seeking to test Canadian demand without full market commitment.
Mexico
Nuevo León and Northern Border States concentrate cut-make-trim capacity that supplies US mass-market and mid-tier retailers with cost-optimized production. Localized logistics bottlenecks and labor actions expose this supply base to disruption risk. The country's proximity advantages sustain nearshoring momentum despite compliance cost gaps versus domestic US manufacturing.
North America Denim Jeans Market Competitive Landscape
Concentration sits with heritage-rooted vertically integrated specialists and agile direct-to-consumer specialists. The vendor base fragments across three tiers: premium heritage houses with captive mill relationships, mid-market mall-based specialty retailers, and fast-fashion volume players. Two strategic archetypes dominate competitive positioning: vertical manufacturing heritage leveraged for pricing power, and stretch-innovation specialists targeting younger demographics. Dominant competitive moves include strategic partnerships with resale platforms for circular channel integration and portfolio diversification into size-inclusive fit ranges.
Within the heritage-tier vector, Levi Strauss & Co. and Kontoor Brands, Inc. anchor positions defined by manufacturing lineage and workwear-adjacent durability claims respectively. American Eagle Outfitters Inc. occupies a position exemplifying stretch-innovation specialization and mall-based specialty retail density. These three entities collectively represent the archetype spectrum spanning vertical heritage, durability-focused workwear positioning, and youth-targeted fit innovation.
| Leading Market Players |
|---|
| Levi Strauss & Co. |
| Kontoor Brands, Inc. |
| PVH Corp. |
| The Gap, Inc. |
| American Eagle Outfitters Inc. |
| VF Corporation |
| United States Polo Association |
| OTB Group |
| H&M Group |
| Others |
Pricing and Supply Chain Analysis
EPA Clean Water Act discharge limits gate both mill qualification and price tier access simultaneously. Mills investing in zero-liquid-discharge systems capture preferential supplier status with sustainability-focused brands while commanding heritage pricing power that price-competitive imports cannot match.
Pricing Analysis
Industrial OEM buyers anchor durable workwear-adjacent denim pricing through volume commitments and durability specifications that sustain full-price transactions. Three-tier pricing structure across premium selvedge, mid-range stretch, and economy standardized fits stratifies by compliance transparency and provenance claims. Cost compression in mid-range bands intensifies because cotton price volatility concentrates margin pressure where pricing power is weakest. Mass-market retailers exhibit highest price sensitivity while luxury heritage houses absorb input swings through limited production premiums.
Supply Chain Analysis
US-Mexico border zone concentration underwrites nearshoring momentum for cost-optimized cut-make-trim capacity serving mid-tier retailers. Raw fiber inputs draw from US upland cotton regions, Mexican border state assembly corridors, and Los Angeles County finishing clusters. Single-source vulnerability runs through Nuevo León capacity concentration exposed to localized logistics disruption. Distribution feeds from Ontario-based entry points into Canadian urban corridors and direct-to-consumer fulfillment nodes in coastal US metros.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Activewear and secondhand resale platforms pose substitution threats that denim incumbents must navigate through circular channel integration and stretch-performance innovation.
For Market Incumbents: Compound captive mill relationships into closed-loop dyeing certification that locks out price-competitive imports. Deepen upstream control over Los Angeles County zero-liquid-discharge capacity to defend margin position against EPA enforcement acceleration. Absorb resale platform partnerships as inventory-risk-free circular revenue streams. For New Entrants and Emerging Players: Anchor in Toronto and Vancouver premium selvedge underpenetration where direct-to-consumer expansion faces weaker heritage brand density. Target size-inclusive fit ranges where sampling cost multiplication deters established players from rapid grading expansion. Lead with augmented-reality sizing tools that reduce return rate friction in online conversion. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed California vertical manufacturers holding EPA-compliant finishing capabilities. Five-to-ten year viability hinges on clean manufacturing credit capture and circular platform integration depth. Watch for Inflation Reduction Act incentive exhaustion as inflection signal for domestic production cost competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Dyeing Certification | EPA Clean Water Act compliance locks in preferential supplier status with sustainability-focused brands. |
| Resale Platform Partnership | Authentication technology investments capture circular consumption margin without inventory risk exposure. |
| Size-Inclusive Grading Expansion | Extended size ranges address underserved demand while sampling cost barriers deter fast-follower competition. |
| Laser Finishing Adoption | Waterless surface treatment reduces environmental compliance costs and enables design precision replication. |
| Direct-to-Consumer Geographic Expansion | Toronto and Vancouver urban corridors offer premium selvedge penetration gaps versus US comparable markets. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with denim brand managers, Los Angeles apparel cluster mill operators, and specialty retail category buyers; and secondary validation through customs trade records, EPA enforcement disclosures, and SEC apparel company filings. Bottom-up volume modeling triangulated against top-down category spend estimates derived from retail audit databases and regional production cluster surveys.
Across the projection horizon, the analytical framework modeled demand by product silhouette, gender segment, price tier, and distribution channel with regional granularity at US state and Canadian province level. CAGRs derived from segment-level growth rate assumptions calibrated to historical volume trajectories and regulatory enforcement acceleration timelines. Forecast inputs incorporated cotton futures volatility patterns and clean manufacturing credit qualification criteria.
Material uncertainties — tariff enforcement shifts on cotton sourcing geography, state-level extended producer responsibility passage, and resale platform authentication technology disruption — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as EPA effluent guideline tightening schedules and IRA credit renewal debates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Adaptive Shapewear Market
Apparel & Footwear
Global Shirt Market
Apparel & Footwear
Global Silk Pajamas Market
Apparel & Footwear
Europe Denim Jeans Market
Apparel & Footwear
Rugby Apparel Market
Apparel & Footwear
Chest Bags Market
Apparel & Footwear
Menswear Market
Apparel & Footwear
Loungewear Market
Apparel & Footwear
Fast Fashion Apparel Market
Apparel & Footwear
Decorated Apparel Market
Apparel & Footwear
Tennis (Apparel and Footwear) and Golf (Apparel and Footwear) Market
Apparel & Footwear
Multiple Toe Socks Market
Apparel & Footwear
Global Swimwear (Swimsuit) Market
Apparel & Footwear
Football Jerseys Market
Apparel & Footwear
Women's T-Shirts Market
Apparel & Footwear
Smart Heating Scarf Market