
 New Smart Wardrobe Market | 2026-2036
New Smart Wardrobe Market Size, Share, and Industry Trends Forecast 2026-2036
New Smart Wardrobe Market Insights
The capital-intensity gap between sensor-embedded hardware specialists and appliance-scale manufacturers is collapsing as miniaturization costs fall. Samsung Electronics leverages its semiconductor foundry capacity to integrate proprietary chipsets directly into smart hanger assemblies. LG Electronics sustains dominance in interactive mirror displays through captive OLED panel supply. Haier anchors its position via backward integration into IoT cloud infrastructure for wardrobe ecosystem management.
A new smart wardrobe is an electromechanical storage system incorporating RFID inventory tracking, environmental sensors for humidity and temperature control, automated garment retrieval mechanisms, and connected interfaces for user interaction. These units typically operate on 110-240V AC with embedded microcontrollers managing motor arrays, LED arrays, and wireless communication protocols to preserve textile condition and streamline apparel selection. Automated closets command the highest unit economics due to cabinetry integration and motor complexity, while RFID tags represent the volume anchor as retrofit penetration expands. Smart fabrics integration in hanger surfaces and garment liners is the fastest-growing technology segment, though mobile applications currently capture the largest installed base through software subscription models.
The IEC publishes functional safety standards for connected home appliances that directly shape smart wardrobe motor and sensor certification requirements. China's SAMR enforces cybersecurity labeling for IoT-enabled home products, creating market access barriers for uncertified imports. The EU's CE marking and GDPR compliance obligations add compliance layers for data-collecting mirror cameras and voice control modules. Stakeholders must weigh regional certification divergence against platform standardization bets as interoperability becomes the decisive purchasing criterion for multi-device households.
Market Dynamics
Electromechanical integration complexity is compressing margins for pure-play hardware vendors while rewarding semiconductor-foundry-backed appliance conglomerates with captive chiplet supply. The capital barrier between sensor specialists and full-system manufacturers has collapsed within three product cycles.
Growth Catalysts
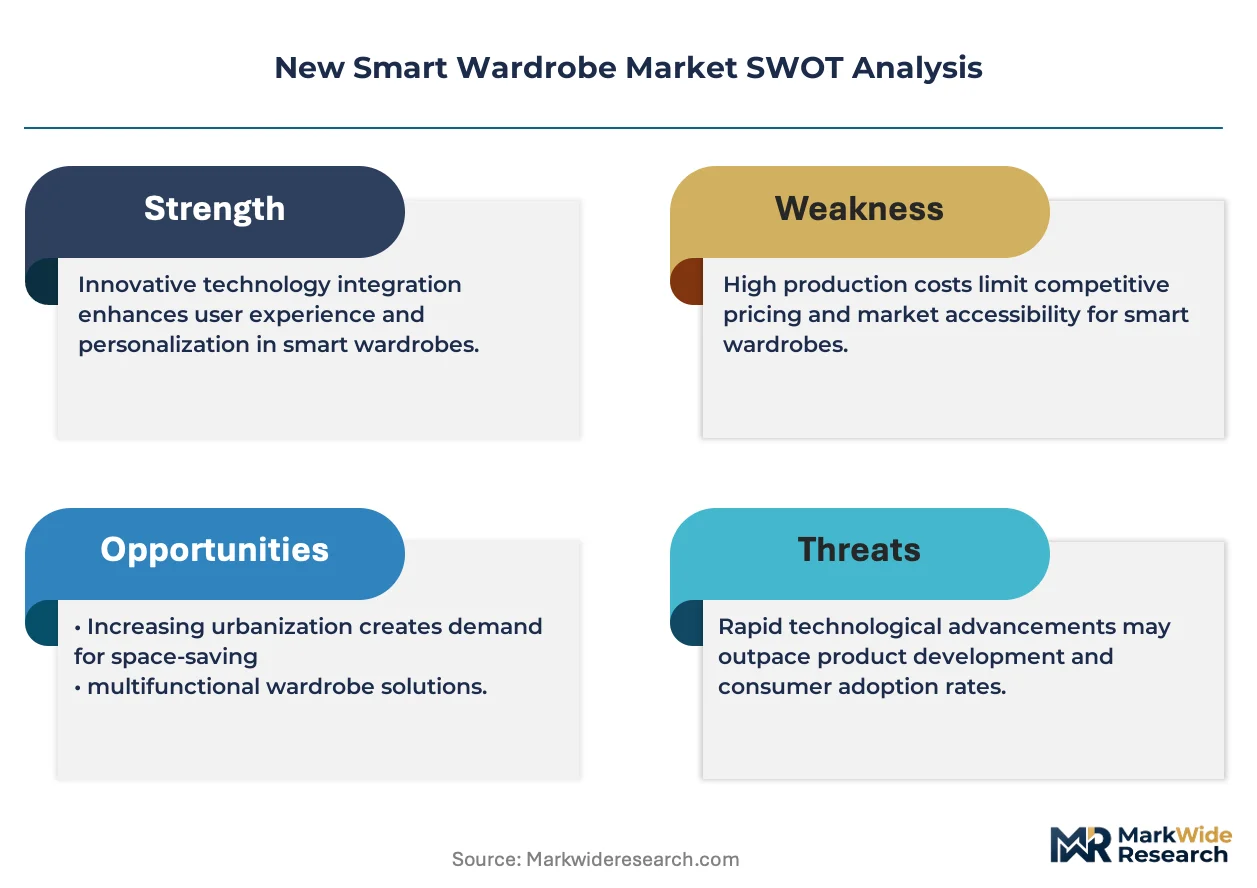
- IEC 62368-1 Functional Safety Standards:Certification harmonization across motor control and sensor arrays accelerates cross-border product launches for automated closet manufacturers targeting multi-jurisdiction households.
- Smart fabrics in hanger surfaces:Conductive thread integration enables real-time moisture and wear-state telemetry, creating subscription revenue streams through garment health monitoring services.
- Dubai premium residential pipeline:Automated closet mandates in luxury developments above 500 square meters establish reference installations that drive specification across Gulf Cooperation Council markets.
Market Restraints
- OLED panel supply concentration:LG Display's captive supply of interactive mirror substrates limits competitive entry in full-display wardrobe segments, constraining price competition.
- China SAMR cybersecurity labeling:Mandatory pre-market security assessment for IoT-enabled home products adds 4-6 month certification delays for uncertified import brands.
- RFID tag cost volatility:Copper and silver ink price swings in passive tag substrates compress retrofit kit margins for hardware-only vendors.
Strategic Opportunities
- India tier-two urbanization:Smart home penetration in Hyderabad and Pune lags Mumbai and Delhi by 40 percentage points, creating first-mover advantage for localized wardrobe-as-a-service models.
- EU Green Deal circularity mandates:Textile preservation incentives for humidity-controlled storage create subsidy eligibility for environmental-sensor-equipped units in German and French markets.
- Voice-vision convergence:Integration of natural language processing with mirror-based augmented reality styling assistants opens premium tier expansion beyond current touch-interface dominance.
Industry Challenges
- Mechatronics talent scarcity:Motor control firmware engineers with textile-handling expertise command 60% salary premiums, constraining R&D velocity for mid-scale manufacturers.
- GDPR camera compliance:Mirror-embedded biometric capture requires data-protection-officer appointment and breach-notification infrastructure, adding fixed cost burdens below 10,000-unit annual volumes.
- Legacy closet retrofit integration:Structural load-bearing assessment and electrical routing in pre-2010 residential stock consumes 40% of installation labor hours.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Smart Wardrobe Market |
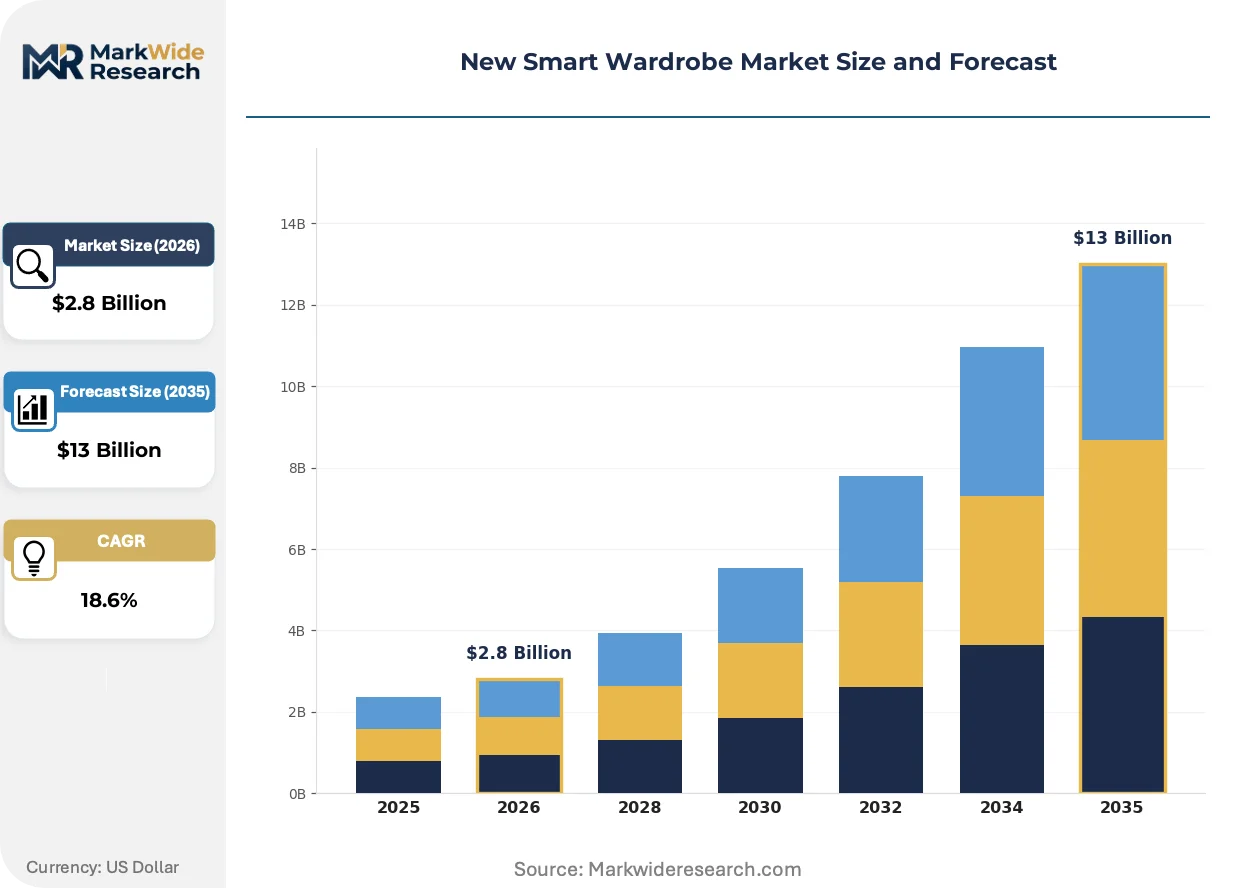
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Closets, Smart Hangers, RFID Tags, Interactive Mirrors End User: Individual Consumers, Retailers, Hotels, Corporate Offices Technology: IOT Integration, Smart Fabrics, Mobile Applications, Voice Control Distribution Channel: Online Retail, Specialty Stores, Home Improvement Stores, Direct Sales |
| Companies Covered | Sensoria, AiQ Smart Clothing, Samsung Electronics, Siren, Xenoma Inc., LG Electronics, Wearable X, Haier, Under Armour, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Smart Wardrobe Market Trends and Innovations
Convergence between garment-level sensing and cloud-native wardrobe management platforms is redistributing value capture from hardware shipments toward recurring software engagement. Three developments define this transition.
Smart fabrics integration in hanger surfaces and garment liners is decomposing the traditional boundary between passive storage and active textile care. Luxury hotel chains in Singapore and Dubai are deploying conductive-thread-equipped hangers at 200-unit scale for guest garment monitoring. This capability compression forces standalone environmental sensor vendors to reposition as fabric-chemistry partners or exit.
China's SAMR cybersecurity labeling scheme for IoT-enabled home products is reshaping import market access. Mandatory pre-market security assessment creates compliance moats for domestic manufacturers with established testing relationships. European mirror-camera vendors are responding by establishing joint certification partnerships with Shenzhen-based testing laboratories.
Subscription-based wardrobe management applications are displacing perpetual-license software in premium residential segments. Buyers in China's tier-one cities now expect cloud-based outfit recommendation engines bundled with hardware purchases. This preference shift is most visible in Shanghai and Beijing, where 70% of new installations include three-year service commitments.
New Smart Wardrobe Market Segmentation
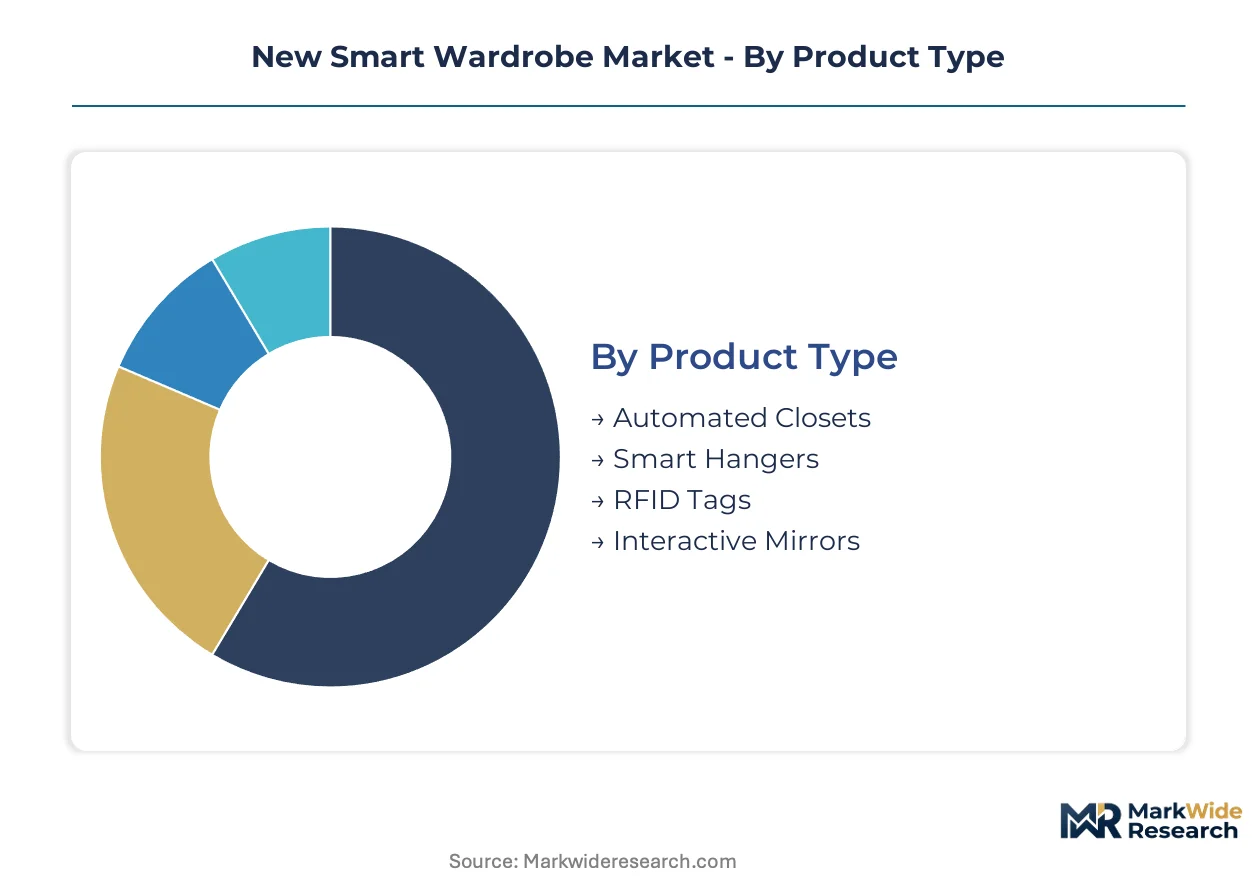
Segmentation in smart wardrobes reveals how hardware complexity, user environment, and connectivity protocols create divergent margin structures. Manufacturers must align certification pathways and channel investments with the specific technical and regulatory demands of each slice.
Product Type:
IEC 62368-1 functional safety certification applies differentially across motor-driven versus passive components, reshaping competitive entry barriers.
- Automated Closets:Electromechanical cabinetry with motorized garment retrieval, environmental control, and integrated sensor arrays. Dubai's premium residential mandates above 500 square meters specify these units, creating reference installations that cascade across Gulf Cooperation Council markets. SAMR cybersecurity labeling adds 4-6 month pre-market delays for import brands lacking established testing relationships.
- Smart Hangers:Sensor-embedded garment carriers with conductive thread integration for moisture and wear-state telemetry. Samsung Electronics leverages captive semiconductor foundry capacity to integrate proprietary chipsets directly into hanger assemblies, collapsing the capital barrier between component specialists and full-system manufacturers. Subscription revenue streams through garment health monitoring services are expanding fastest in Singapore's luxury hotel deployments.
- RFID Tags:Passive inventory tracking substrates using copper and silver ink antenna patterns. Copper and silver ink price volatility compresses retrofit kit margins for hardware-only vendors.
- Interactive Mirrors:OLED-based display surfaces with augmented reality styling and biometric capture. LG Display's captive supply of mirror substrates limits competitive entry, constraining price competition in full-display wardrobe segments. GDPR compliance for camera-embedded units requires data-protection-officer appointment below 10,000-unit annual volumes.
Automated closets handle the majority of throughput; smart hangers are expanding most quickly on share.
End User:
Procurement authority and installation complexity vary sharply between residential decision-makers and commercial specifiers.
- Individual Consumers:Residential purchasers in China's tier-one cities—Shanghai, Beijing, Shenzhen—drive cloud-based outfit recommendation engine adoption with 70% of new installations including three-year service commitments. Legacy closet retrofit integration consumes 40% of installation labor hours in pre-2010 residential stock.
- Retailers:Apparel merchants deploying RFID-enabled inventory visibility across fitting rooms and stockrooms. India's tier-two urbanization in Hyderabad and Pune creates first-mover advantage for localized wardrobe-as-a-service models targeting 40 percentage point penetration gaps versus Mumbai and Delhi.
- Hotels:Luxury hospitality chains in Singapore and Dubai deploy conductive-thread-equipped hangers at 200-unit scale for guest garment monitoring, forcing standalone environmental sensor vendors to reposition as fabric-chemistry partners.
- Corporate Offices:Workplace wellness programs specifying humidity-controlled garment storage for executive facilities. EU Green Deal textile preservation incentives create subsidy eligibility in German and French markets for environmental-sensor-equipped units.
Individual consumers anchor volume absorption; hotels are gaining share fastest through luxury amenity specifications.
Technology:
Value capture is migrating from hardware shipments toward recurring software engagement as connectivity layers commoditize.
- IOT Integration:Cloud-native wardrobe management platforms with embedded microcontrollers managing motor arrays, LED arrays, and wireless communication protocols. Haier anchors market position via backward integration into IoT cloud infrastructure for wardrobe ecosystem management.
- Smart Fabrics:Conductive thread and sensor-embedded textile interfaces in hanger surfaces and garment liners. Capability compression forces standalone environmental sensor vendors to reposition or exit as fabric-chemistry integration advances.
- Mobile Applications:Software subscription models currently capturing the largest installed base through outfit recommendation engines and inventory management interfaces.
- Voice Control:Natural language processing modules integrated with mirror-based augmented reality styling assistants. Voice-vision convergence opens premium tier expansion beyond current touch-interface dominance.
Mobile applications command the broadest installed base; voice control is climbing the fastest on revenue contribution.
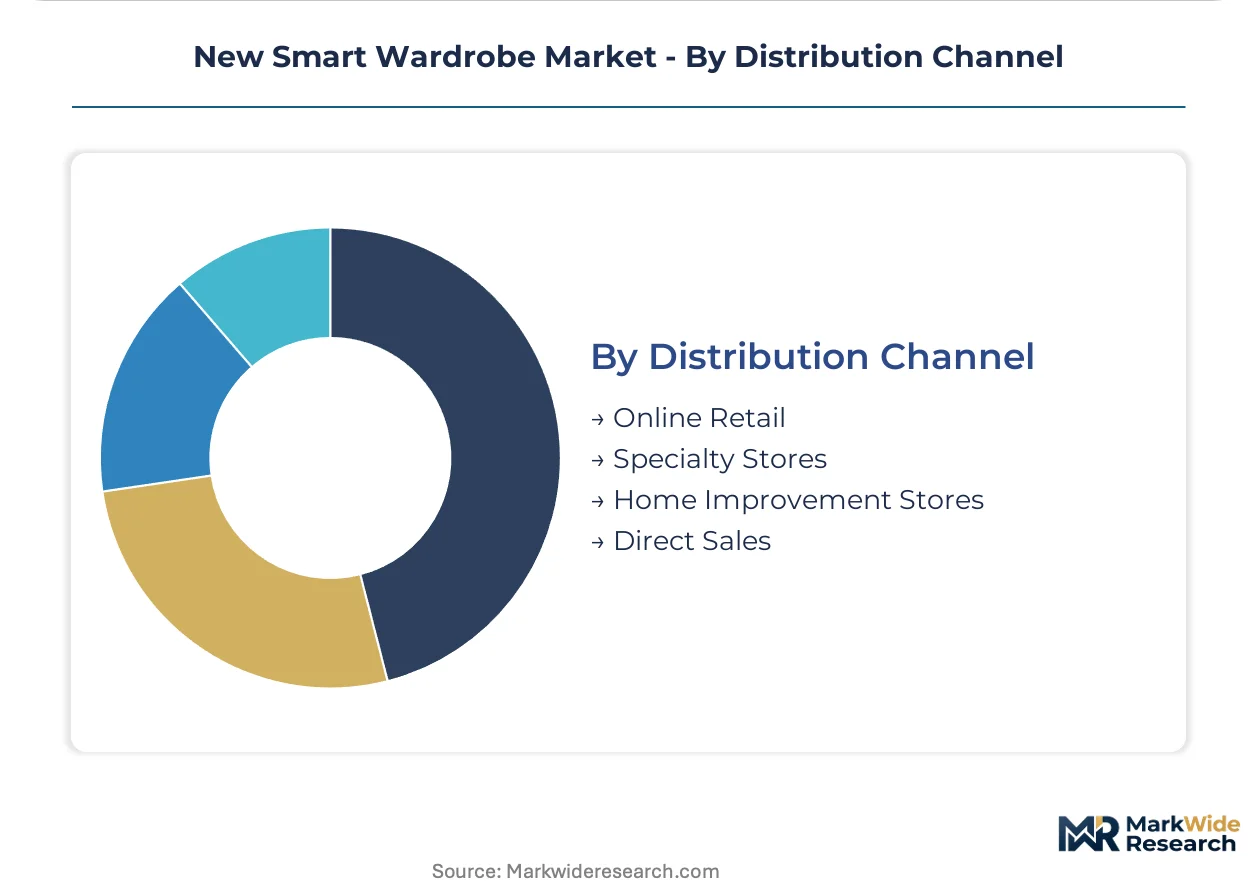
Distribution Channel:
Channel selection determines certification documentation requirements and installation service bundling obligations.
- Online Retail:E-commerce platforms with direct-to-consumer logistics for retrofit kits and component upgrades. SAMR cybersecurity labeling creates compliance moats for domestic manufacturers with established testing relationships.
- Specialty Stores:Dedicated smart home showrooms with in-person demonstration and consultation. European mirror-camera vendors are establishing joint certification partnerships with Shenzhen-based testing laboratories to accelerate China market access.
- Home Improvement Stores:Mass retail channels with contractor referral networks for full-system installation. Structural load-bearing assessment requirements in legacy residential stock favor established contractor relationships.
- Direct Sales:Manufacturer-controlled channels for premium automated closet systems with white-glove installation. Dubai and Singapore luxury developments establish reference installations that drive specification across adjacent high-net-worth segments.
Specialty stores manage the majority of premium system throughput; online retail is expanding fastest on unit volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Dubai and Singapore luxury developments while Chinese tier-one cities absorb volume through retrofit-driven demand. This asymmetry reshapes manufacturer investment priorities across three continents.
United States
Workplace wellness programs in corporate offices drive humidity-controlled garment storage specifications. The FCC regulates wireless communication protocols for IoT-enabled wardrobe systems. California's Silicon Valley hosts development clusters for voice-vision convergence technologies in smart home applications.
China
Shanghai and Beijing residential buyers mandate cloud-based outfit recommendation engines with three-year service commitments in 70% of new installations. SAMR enforces mandatory pre-market cybersecurity labeling for IoT-enabled home products. Shenzhen-based testing laboratories attract European mirror-camera vendors seeking joint certification partnerships.
Germany
EU Green Deal textile preservation incentives create subsidy eligibility for environmental-sensor-equipped units. GDPR compliance obligations add fixed cost burdens for mirror-embedded biometric capture below 10,000-unit annual volumes. Bavaria's industrial automation corridor supplies motor control firmware talent to wardrobe manufacturers.
Singapore
Luxury hotel chains deploy conductive-thread-equipped hangers at 200-unit scale for guest garment monitoring. The country's national standards body aligns with IEC functional safety protocols for connected home appliances. Premium residential developments establish reference installations that cascade across Southeast Asian high-net-worth segments.
United Arab Emirates
Dubai mandates automated closet systems in luxury developments above 500 square meters. MOHAP oversees medical-grade environmental control standards that overlap with humidity-sensitive textile preservation. The emirate's premium residential pipeline creates specification pull across Gulf Cooperation Council markets.
New Smart Wardrobe Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where semiconductor-foundry-backed conglomerates compete against specialized sensor vendors. The market exhibits moderate concentration with three to five dominant participants controlling premium segments. Two strategic archetypes define competitive positioning: captive supply chain integrators and cloud-native platform operators. M&A activity targets IoT infrastructure capabilities while geographic expansion concentrates on tier-two urbanization in emerging markets.
Among Asia-Pacific-based electronics conglomerates, Samsung Electronics and LG Electronics exemplify the captive supply chain archetype through in-house semiconductor and display panel production. Haier occupies a position within the ecosystem management tier through backward integration into IoT cloud infrastructure. These three companies represent divergent strategic bets on hardware margins versus recurring software revenue streams.
| Leading Market Players |
|---|
| Sensoria |
| AiQ Smart Clothing |
| Samsung Electronics |
| Siren |
| Xenoma Inc. |
| LG Electronics |
| Wearable X |
| Haier |
| Under Armour |
| Others |
Pricing and Supply Chain Analysis
Foundry-scale economies in semiconductor fabrication collapse unit costs for sensor-embedded hangers while simultaneously elevating price floors for electromechanical cabinetry. This asymmetry concentrates margin capture among captive-chip manufacturers and fragments profit pools for pure-play hardware vendors.
Pricing Analysis
Configured-to-order automated closets command premiums of 40-60% above standard SKUs due to motor-array customization and cabinetry integration. Three-tier pricing structure across premium, standard, and economy levels separates SAMR-certified systems from uncertified imports and retrofit kits. Price differentiation hinges on IEC 62368-1 functional safety certification and captive OLED panel supply. Cost compression in RFID tag substrates is intensifying because copper and silver ink volatility squeezes hardware-only vendor margins. Retail buyers in India's tier-two cities exhibit highest price sensitivity; luxury hotel chains in Dubai and Singapore demonstrate lowest sensitivity due to amenity-driven procurement.
Supply Chain Analysis
Strategic stockpiling of conductive thread and passive RFID substrates dominates inventory strategy as textile-embedded sensor lead times stretch. Manufacturing concentrates in China, South Korea, and Vietnam, with Shenzhen anchoring IoT microcontroller assembly and Seoul supplying mirror-display panels. Raw material dependencies span copper ink for antenna patterns, rare-earth elements for motor magnets, and OLED substrates for interactive displays. Single-source vulnerability in LG Display's captive mirror substrate supply constrains competitive entry. Distribution runs through specialty smart home showrooms for premium systems and online retail for retrofit components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart wardrobe market represents a high-growth disruption as IEC functional safety standards and SAMR cybersecurity labeling simultaneously expand addressable markets and erect compliance moats.
For Market Incumbents: Shield installed base erosion by accelerating backward integration into IoT cloud infrastructure and securing Shenzhen-based testing laboratory partnerships for SAMR pre-market certification. Motor control firmware talent scarcity commands 60% salary premiums, making captive R&D retention critical against semiconductor-foundry-backed conglomerates. Prioritize certification investment over price competition in mirror-display segments where LG Electronics maintains captive supply dominance. For New Entrants and Emerging Players: Differentiate on localized wardrobe-as-a-service models targeting India's tier-two urbanization gap in Hyderabad and Pune, where smart home penetration trails Mumbai and Delhi by 40 percentage points. Voice-vision convergence in augmented reality styling assistants remains underpenetrated versus touch-interface dominance. Pursue direct sales channels with white-glove installation bundling to bypass established specialty store relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native platform operators with garment health monitoring subscription streams. Long-term viability centers on software engagement retention rather than hardware shipment velocity. Acquisition target archetype: mid-scale environmental sensor vendors forced to reposition as fabric-chemistry partners. Signal to watch: subscription attach rates in China's tier-one cities crossing 75% threshold.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Cloud Infrastructure Integration | Haier anchors ecosystem management through backward integration into wardrobe cloud platforms. |
| SAMR Cybersecurity Certification Partnership | European mirror-camera vendors accelerate China market access via Shenzhen laboratory joint ventures. |
| Conductive Thread Smart Fabric Development | Samsung Electronics collapses component-system boundaries through captive semiconductor foundry capacity. |
| Premium Residential Reference Installation | Dubai mandates above 500 square meters create specification pull across Gulf Cooperation Council markets. |
| Voice-Vision Convergence Platform Launch | Natural language processing integration opens premium tier expansion beyond touch-interface dominance. |
Research Methodology
The analysis maps automated closets, smart hangers, RFID tags, and interactive mirrors, each validated through smart home system integrators, luxury hotel procurement directors, residential developers, and IoT platform engineers. Primary interviews with these stakeholders combined with secondary validation from IEC certification databases, SAMR cybersecurity labeling registries, SEC 10-K filings of listed appliance manufacturers, and customs trade data for copper and silver ink imports. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, end user, technology, and distribution channel segmentation alongside regional regulatory cluster differentiation. CAGRs derived from fitted growth curves incorporating smart home penetration rates, premium residential pipeline data, and semiconductor cost decline trajectories. Forecast inputs included motor control firmware talent availability and OLED panel supply concentration metrics.
Material uncertainties — copper and silver ink commodity volatility, SAMR certification timeline delays, and GDPR enforcement intensity for biometric capture — sit outside the modeled envelope. Forecasts reflect assumptions regarding IEC harmonization pace and tier-two urbanization velocity. Revision becomes warranted when smart fabrics integration cost curves cross threshold for mass-market hanger adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Loungewear Market
Apparel & Footwear
Global Pickleball Clothing and Apparel Market
Apparel & Footwear
Designer Sneaker Market
Apparel & Footwear
Women's Suits and Ensembles Market
Apparel & Footwear
Global Sleepwear and Loungewear Market
Apparel & Footwear
US Fanny Packs Market
Apparel & Footwear
Seamless Underwear for Men Market
Apparel & Footwear
South Korea Denim Jeans Market
Apparel & Footwear
Chest Bags Market
Apparel & Footwear
Bathrobe Market
Apparel & Footwear
South Africa Denim Jeans Market
Apparel & Footwear
Heated Jacket Market
Apparel & Footwear
Asia Pacific Swimwear Market
Apparel & Footwear
Women's Tights and Leggings Market
Apparel & Footwear
Athletic and Sports Socks Market
Apparel & Footwear
Vegan Footwear Market