
 Outdoor Apparel Market | 2026-2036
Outdoor Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Apparel Market Outlook
Aftermarket repair and resale revenue is fragmenting across direct-to-consumer channels, vintage platforms, and brand-certified refurbishment programs. Patagonia sustains its market position through the Worn Wear initiative and supply chain transparency commitments. Columbia Sportswear Company competes via geographic diversification across North American wholesale and Asian retail networks. Fjällräven differentiates through material innovation in G-1000 waxed cotton and heritage positioning in European markets.
Outdoor apparel encompasses engineered garments designed for environmental protection during wilderness and adventure activities, typically incorporating waterproof-breathable membranes such as ePTFE or polyurethane laminates, taped seams, and durable water repellent finishes to manage moisture, wind, and thermal regulation. These products serve recreational users, professional guides, and military personnel operating in variable climates. Polyester dominates material demand due to its strength-to-weight ratio and compatibility with recycled feedstocks, while nylon commands premium positioning in alpine and climbing applications where abrasion resistance determines product lifespan. Activity-based segmentation shows hiking as the volume anchor, with climbing apparel capturing higher unit margins through technical specification requirements.
REACH restrictions on perfluorinated chemicals in Europe and state-level PFAS prohibitions in the United States compel reformulation of durable water repellent chemistries across supplier networks. The EU Green Deal's textile strategy mandates extended producer responsibility and recycled content thresholds, reshaping sourcing decisions for brands serving European consumers. Stakeholders must monitor regulatory divergence between jurisdictions while accelerating bio-based and fluorine-free alternative development to maintain product performance claims and market access.
Market Dynamics
REACH restrictions on perfluorinated chemicals are forcing wholesale reformulation of durable water repellent chemistries across European supply chains, while state-level PFAS prohibitions in the United States create parallel compliance obligations that fragment R&D investment.
Growth Catalysts
- EU Green Deal textile mandates:Extended producer responsibility requirements and recycled content thresholds redirect capital toward circular material platforms, creating first-mover advantages for brands with certified supply chains.
- Thru-hiking community expansion:Long-distance trail completion rates in Germany's Alpine corridor and Scandinavian design hubs drive technical outerwear replacement cycles and premium positioning.
- Bio-based membrane development:Polyurethane laminates derived from castor oil feedstocks achieve waterproof-breathable performance parity, opening substitution pathways for petroleum-based ePTFE.
Market Restraints
- Petrochemical feedstock volatility:Polyester and nylon resin prices fluctuate with crude oil derivatives, compressing margin predictability for mid-tier manufacturers without long-term offtake agreements.
- Fluorine-free performance gap:Current DWR alternatives fail to match perfluorinated durability in sustained precipitation, limiting technical credibility for alpine and military applications.
- Asian dyehouse concentration:Textile wet processing clusters in specific coastal provinces create single-point vulnerability for color consistency and effluent compliance.
Strategic Opportunities
- Certified refurbishment channels:Brand-controlled resale platforms capture margin otherwise lost to vintage marketplaces, with authentication services building direct customer relationships.
- Military and professional guide contracts:Institutional procurement for variable climate operations demands durability specifications that consumer lines cannot meet.
- Wax-impregnated cotton revival:Heritage material platforms like G-1000 offer repairability narratives that differentiate against disposable synthetic alternatives in European markets.
Industry Challenges
- Polymer chemist scarcity:Fluorine-free formulation expertise concentrates in specialty chemical firms, creating hiring competition for apparel brands building in-house materials science teams.
- Multi-jurisdiction compliance timelines:Divergent PFAS phase-out schedules between EU REACH and US state laws force parallel product line maintenance or lowest-common-denominator design.
- Legacy seam taping equipment:Existing factory infrastructure optimized for solvent-based adhesives requires capital-intensive retooling to process bio-based alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outdoor Apparel Market |
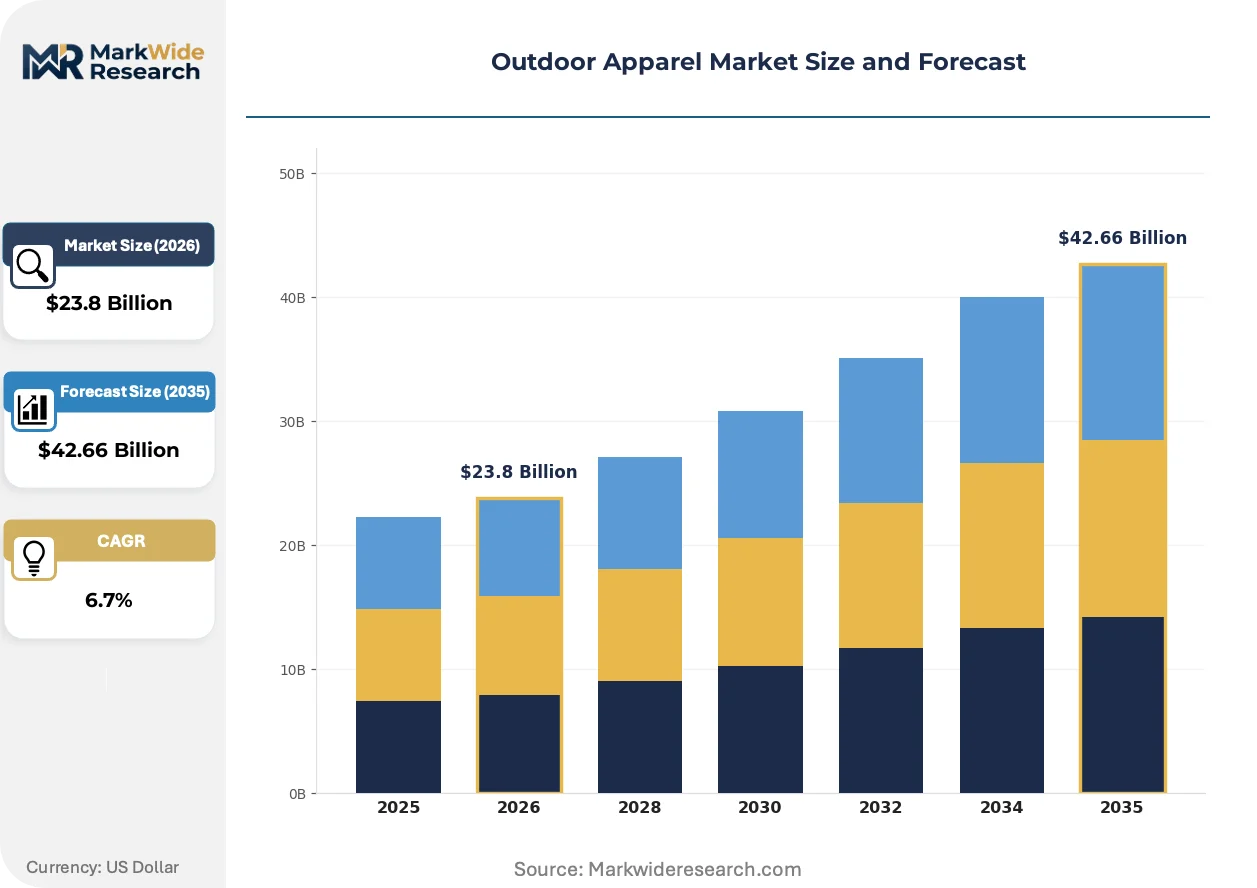
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $42.66 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jackets, Pants, Shirts, Shorts Material: Polyester, Nylon, Wool, Cotton Activity Type: Hiking, Camping, Climbing, Fishing Customer Type: Men, Women, Kids, Others |
| Companies Covered | Arc'teryx, Peak Performance, Patagonia, Filson, Craghoppers, The North Face, Fjällräven, Mountain Hardwear, Columbia Sportswear Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Apparel Market Strategic Shifts
Material science breakthroughs and regulatory phase-outs are compressing traditional product development cycles while opening substitution pathways across membrane, insulation, and surface treatment categories.
Mechanically recycled polyester from post-consumer ocean plastics is collapsing the price premium for sustainable feedstocks as chemical recycling scales achieve virgin-equivalent fiber performance. Thru-hikers and alpine guides now specify recycled content as baseline expectation rather than upgrade option. This convergence eliminates the green premium that previously subsidized sustainable line development.
REACH Annex XVII restrictions on perfluorinated substances compel reformulation of durable water repellent finishes across supplier networks serving European consumers. Chemical manufacturers face accelerated registration timelines for fluorine-free alternatives while brands absorb retesting costs for existing product lines. Alpine and climbing categories experience the steepest compliance burden due to performance certification requirements.
Direct repair services are displacing traditional warranty replacement models as brands deploy mobile seam-sealing units and regional refurbishment hubs. Patagonia's Worn Wear initiative established the operational template; competitors now replicate the logistics infrastructure across North American and European retail networks. Germany's Alpine manufacturing corridor hosts the densest concentration of these service points due to proximity to core hiking populations.
Outdoor Apparel Market Segmentation
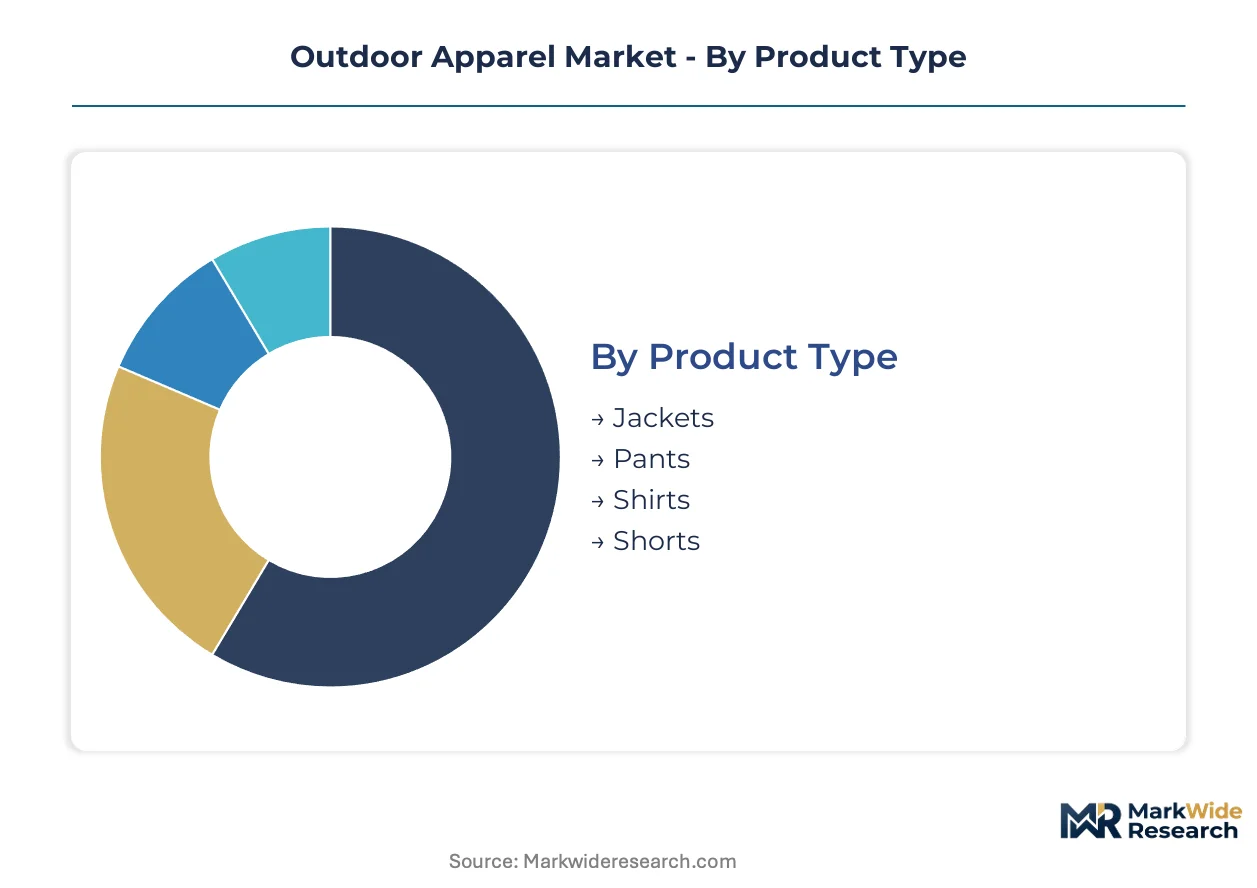
Segmentation in outdoor apparel reveals divergent margin structures across material technologies and activity intensities. Product architecture, fiber selection, and end-use severity collectively determine pricing power and replacement frequency for manufacturers serving alpine, coastal, and desert environments.
Product Type:
Mature outerwear categories dominate revenue concentration while emerging base-layer formats capture technical specification premiums.
- Jackets:Waterproof-breathable membranes such as ePTFE or polyurethane laminates with fully taped seams define technical performance. Demand concentrates in Germany's Alpine corridor where thru-hikers and professional guides require storm-grade protection during multi-day traverses.
- Pants:Abrasion-resistant face fabrics with articulated knee construction and reinforced instep panels address scrambling and rock contact. Scandinavian design hubs drive premium positioning through heritage waxed cotton alternatives that differentiate against synthetic competitors.
- Shirts:Moisture-wicking knit constructions with UPF ratings and odor-control treatments serve high-output aerobic activities.
- Shorts:Lightweight woven or softshell fabrics with integrated belt systems and thigh pocket configurations target warm-weather trail use.
Jackets handle the majority of throughput; pants are expanding most quickly on share as consumers invest in complete kit systems.
Material:
Cost tier stratification separates commodity feedstocks from performance polymers with certified recycled content or bio-based origin stories.
- Polyester:Dominates volume through strength-to-weight ratio and compatibility with mechanically recycled ocean plastic feedstocks. REACH restrictions on perfluorinated chemicals accelerate fluorine-free DWR formulation on polyester face fabrics for European market access.
- Nylon:Commands alpine and climbing applications where abrasion resistance determines product lifespan. High-tenacity ripstop variants with Cordura reinforcement sustain premium pricing in technical categories.
- Wool:Merino and merino-blend knitwear delivers temperature regulation and natural odor resistance for extended backcountry use.
- Cotton:Heritage wax-impregnated platforms like G-1000 offer repairability narratives that differentiate against disposable synthetic alternatives in EU markets.
Polyester anchors volume throughput; nylon claims the steepest expansion trajectory as climbing participation accelerates.
Activity Type:
Application severity creates tiered performance requirements from casual trail use to expedition-grade exposure.
- Hiking:Volume anchor segment spanning day-hiking through thru-hiking with modular layering systems. Germany's Alpine manufacturing corridor hosts dense brand presence serving core hiking populations with direct repair infrastructure.
- Camping:Versatile mid-layers and weather-resistant outerwear for static thermal management and fire-spark protection.
- Climbing:Harness-compatible designs with minimal bulk and maximum mobility command highest unit margins. EU Green Deal textile mandates redirect capital toward circular material platforms for brands with certified supply chains.
- Fishing:Specialized wading apparel with integrated gravel guards and corrosion-resistant hardware for freshwater and saltwater environments.
Hiking absorbs the majority of unit volume; climbing is gaining share fastest through technical specification premiums.
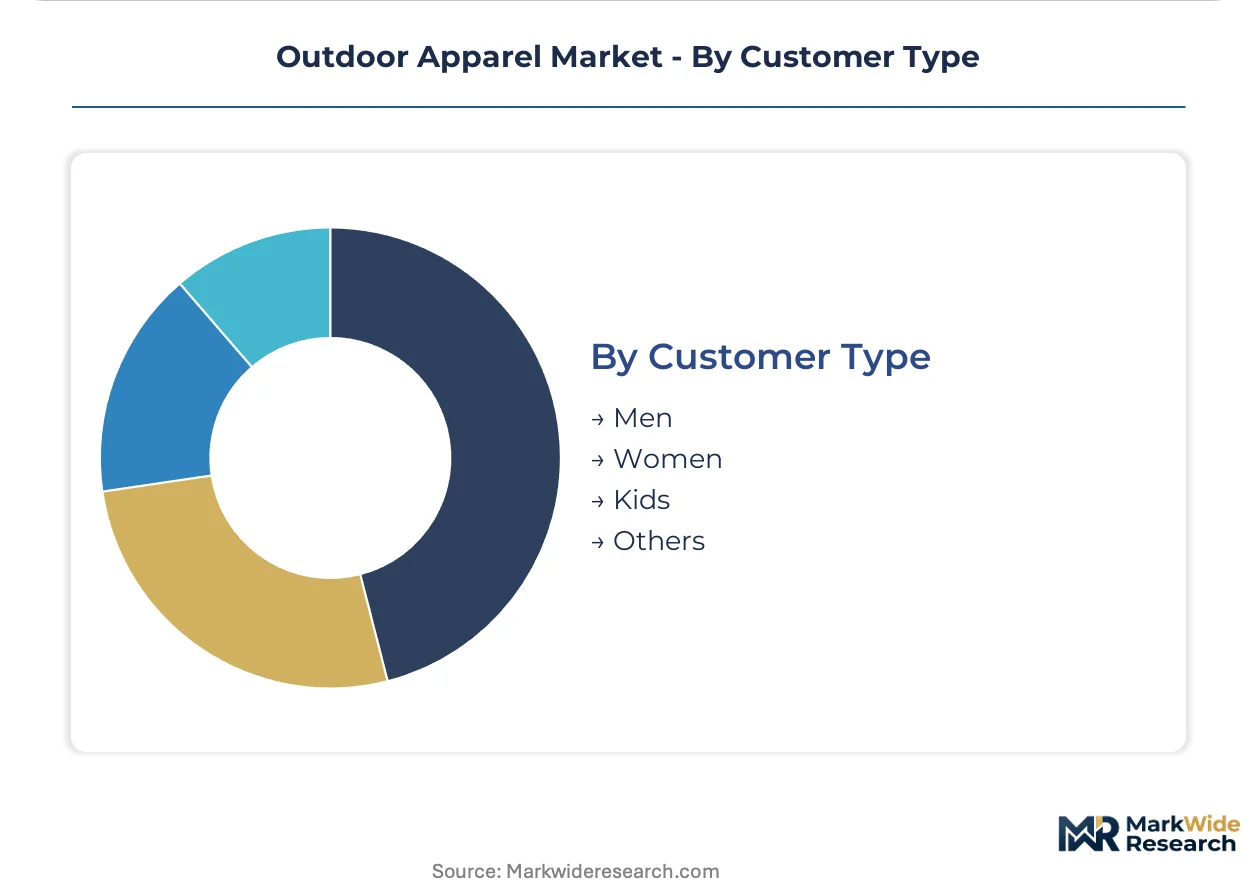
Customer Type:
Customer archetype determines fit engineering complexity and marketing channel allocation across gendered and age-based lines.
- Men:Established size-run standards with extended tall and big-and-tall variants serve the largest addressable base.
- Women:Technical patterning with adjusted rise, torso length, and shoulder articulation addresses anatomical fit requirements. State-level PFAS prohibitions in the United States create parallel compliance obligations that fragment R&D investment across women's technical lines.
- Kids:Growth-accommodating features and reinforced high-wear zones address rapid size turnover and rough-use durability.
- Others:Unisex and gender-neutral sizing expands alongside inclusive design practices in European and North American markets.
Men's lines handle the majority of throughput; women's technical categories are climbing the fastest on share expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German thru-hikers absorb technical premiums for storm-grade protection, while price-sensitive segments in emerging markets prioritize entry-level polyester shells. Scandinavian buyers pay heritage markups for waxed cotton repairability narratives.
United States
State-level PFAS prohibitions in Maine, Washington, and California force parallel compliance tracks for brands serving multi-state distribution. EPA scrutiny of long-chain fluorinated chemicals accelerates reformulation timelines for DWR chemistries. Denver-Boulder corridor hosts dense brand presence and direct-to-consumer repair infrastructure serving Rocky Mountain hiking populations.
Germany
Bavarian Alpine manufacturing clusters anchor technical outerwear production for thru-hiking communities traversing the Alps. EU Green Deal textile mandates impose extended producer responsibility and recycled content thresholds. Munich and Innsbruck-adjacent facilities concentrate seam-sealing repair hubs and circular material R&D.
Sweden
Scandinavian design heritage commands premium positioning for wax-impregnated cotton platforms and modular layering systems. REACH Annex XVII restrictions on perfluorinated substances drive fluorine-free DWR development in supplier networks. Stockholm and Åre host heritage brand headquarters and alpine testing facilities.
Japan
Technical specification demands from alpine guides and ski mountaineers sustain premium pricing for high-tenacity nylon and ePTFE membranes. METI circular economy guidelines pressure brands toward certified refurbishment channels. Osaka-Kobe industrial corridor concentrates textile wet processing and dyehouse compliance infrastructure.
Canada
Extended backcountry seasons and variable climate exposure drive replacement cycles for waterproof-breathable outerwear. Health Canada and PMRA coordinate with EPA on PFAS risk assessment timelines affecting cross-border product lines. Vancouver and Calgary anchor brand logistics for Pacific Northwest and Rocky Mountain retail networks.
Outdoor Apparel Market Competitive Environment
Capability concentration sits with heritage specialists commanding materials science expertise; scale advantage sits with diversified apparel conglomerates with geographic footprint. The vendor base stratifies across three tiers: premium technical specialists with vertical membrane control, mid-market brands competing on recycled content certification, and private-label suppliers serving retail channel partners. Dominant competitive moves include certified refurbishment platform deployment and bio-based material partnership structures.
Within the heritage-technical tier, Fjällräven occupies a position exemplifying waxed cotton repairability narratives and Scandinavian design positioning. Columbia Sportswear Company represents scale-driven geographic diversification across wholesale and retail networks. Patagonia anchors the circular economy archetype through supply chain transparency and direct repair service infrastructure.
| Leading Market Players |
|---|
| Arc'teryx |
| Peak Performance |
| Patagonia |
| Filson |
| Craghoppers |
| The North Face |
| Fjällräven |
| Mountain Hardwear |
| Columbia Sportswear Company |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp freight corridors transmit petrochemical feedstock volatility directly into European manufacturing costs, compressing margin buffers for mid-tier brands while enabling Alpine corridor specialists to command storm-grade premiums through proximity to Germany's thru-hiking communities.
Pricing Analysis
Long-term offtake agreements dominate resin procurement for volume manufacturers, insulating against polyester and nylon price swings while spot-market exposure concentrates among private-label suppliers. Price differentiation separates GORE-TEX-certified membrane tiers from fluorine-free alternatives, with heritage waxed cotton platforms capturing repairability markups in Scandinavian markets. Cost compression runs through mid-market polyester shells as recycled feedstock premiums collapse. Day-hikers exhibit highest price sensitivity; alpine guides and military contractors absorb technical premiums for durability specifications.
Supply Chain Analysis
Extended payment terms from Vietnamese and Bangladeshi cut-and-sew contractors strain working capital for European brands, accelerating supply-chain finance facility adoption. Raw material sourcing draws from Chinese petrochemical complexes for polyester resin, Taiwanese textile mills for high-tenacity nylon, and Portuguese dyehouses for REACH-compliant wet processing. Single-source vulnerability concentrates in GORE-TEX membrane supply and Alpine seam-taping equipment. Distribution runs through German wholesale networks, Scandinavian flagship retail, and North American direct-to-consumer repair hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluorine-free polymer chemistry expertise has become the binding constraint on product development timelines, with fewer than a dozen specialty chemical firms capable of formulating PFAS-compliant DWR finishes that meet alpine performance thresholds.
For Market Incumbents: Pre-empt regulatory divergence by maintaining parallel product lines for EU REACH and US state PFAS schedules, or converge on lowest-common-denominator fluorine-free designs. Secure backward integration into bio-based polyurethane membrane production through castor oil feedstock partnerships. Channel control via certified refurbishment platforms defends margin position against vintage marketplace fragmentation. For New Entrants and Emerging Players: Pursue white-space opportunities in military and professional guide procurement, where durability specifications exceed consumer line capabilities and institutional budgets absorb premium pricing. Women's technical categories offer fastest share expansion with unmet fit engineering demands. Go-to-market leverage rests on direct repair service infrastructure rather than wholesale distribution. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified apparel conglomerates with underperforming outdoor divisions lacking circular economy certification. Long-term viability over a decade horizon favors brands with captive membrane technology or heritage material platforms like waxed cotton. Watch for inflection when fluorine-free DWR achieves performance parity with perfluorinated chemistries in sustained precipitation testing.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Refurbishment Platform | Patagonia's Worn Wear model captures margin from vintage marketplaces while building direct customer relationships. |
| Bio-Based Membrane Partnership | Castor oil-derived polyurethane laminates open substitution pathways for petroleum-based ePTFE in European markets. |
| Alpine Repair Hub Network | Germany's Bavarian corridor hosts dense service infrastructure reducing warranty replacement costs for technical outerwear. |
| Heritage Material Revival | Fjällräven's G-1000 waxed cotton differentiates against disposable synthetics through repairability narratives. |
| Military Procurement Contract | Institutional variable-climate specifications demand durability certifications that consumer lines cannot meet. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with brand materials science directors, Alpine manufacturing facility managers, European dyehouse compliance officers, and thru-hiking community gear specialists. Secondary validation drew from ECHA REACH registration databases, EU Green Deal textile strategy documentation, US EPA PFAS risk assessments, and customs trade data on polyester and nylon resin flows. Bottom-up demand modeling across activity segments triangulated against top-down market sizing from certified supply chain disclosures.
Calibration against historical replacement cycles for waterproof-breathable outerwear anchored volume projections across the analysis window. Segmentation dimensions modeled include product architecture, fiber technology tier, activity intensity, and regional regulatory cluster. CAGRs derived from elasticity-adjusted adoption curves for fluorine-free alternatives and circular material platforms. Key inputs incorporated REACH Annex XVII enforcement timelines and state-level PFAS prohibition schedules.
Sensitivities concentrate around regulatory acceleration or delay in perfluorinated chemical phase-outs, bio-based membrane performance validation, and military procurement budget cycles. Forecasts embed assumptions on recycled content threshold compliance and seam-taping equipment retooling rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Children's Dresses and Skirts Market
Apparel & Footwear
Body Shaper Market
Apparel & Footwear
Women's Blazer Market
Apparel & Footwear
Decorated Apparel Market
Apparel & Footwear
Tennis (Apparel and Footwear) and Golf (Apparel and Footwear) Market
Apparel & Footwear
Thermal Underwear Market
Apparel & Footwear
Southeast Asia Lingerie Market
Apparel & Footwear
Asia-Pacific Denim Jeans Market
Apparel & Footwear
Menswear Market
Apparel & Footwear
Jeans Market
Apparel & Footwear
Streetwear Market
Apparel & Footwear
Online Apparel Market
Apparel & Footwear
Plus Size Women's Clothing Market
Apparel & Footwear
Premium Denim Jeans Market
Apparel & Footwear
Global Adaptive Clothing Market
Apparel & Footwear
Compression and Shapewear Market