
 Asia-Pacific Denim Jeans Market | 2026-2036
Asia-Pacific Denim Jeans Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Denim Jeans Market Insights
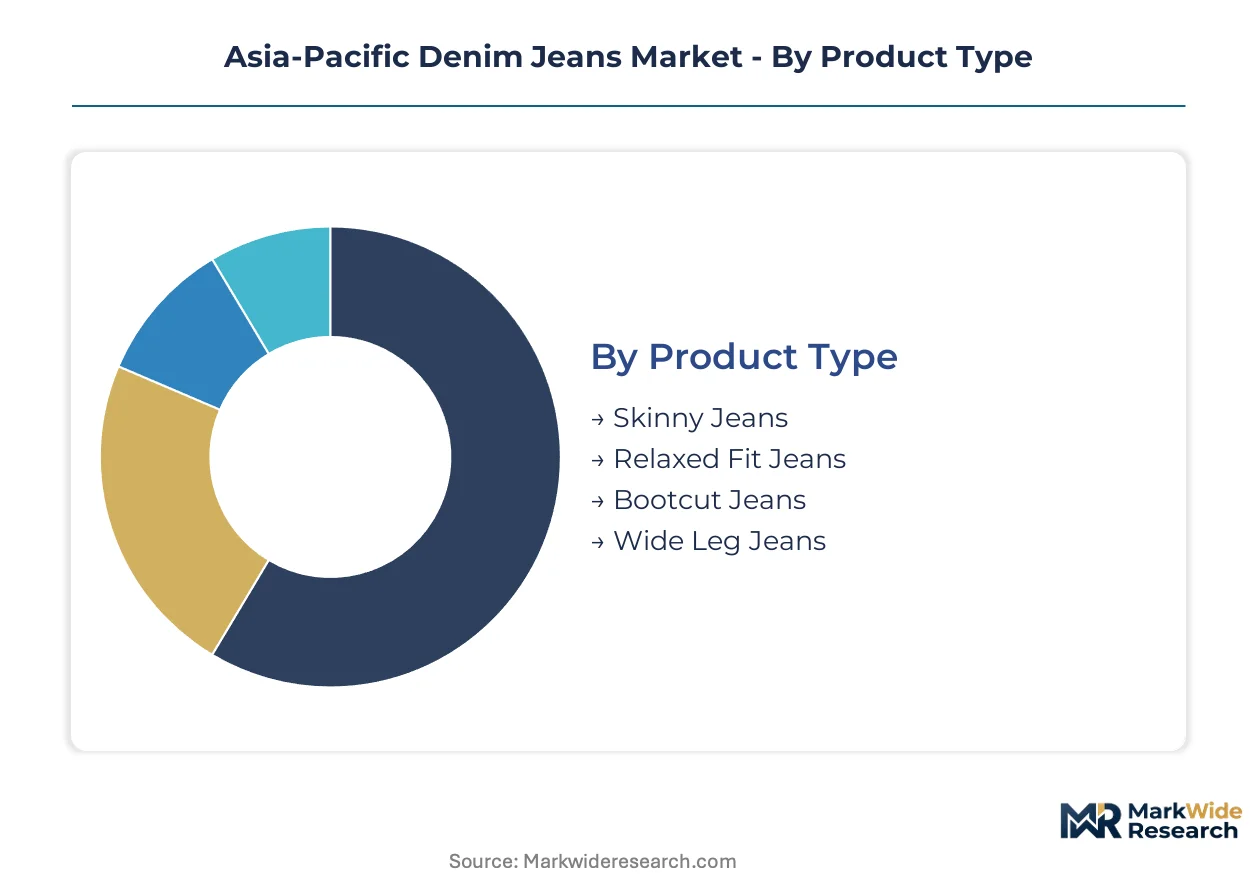
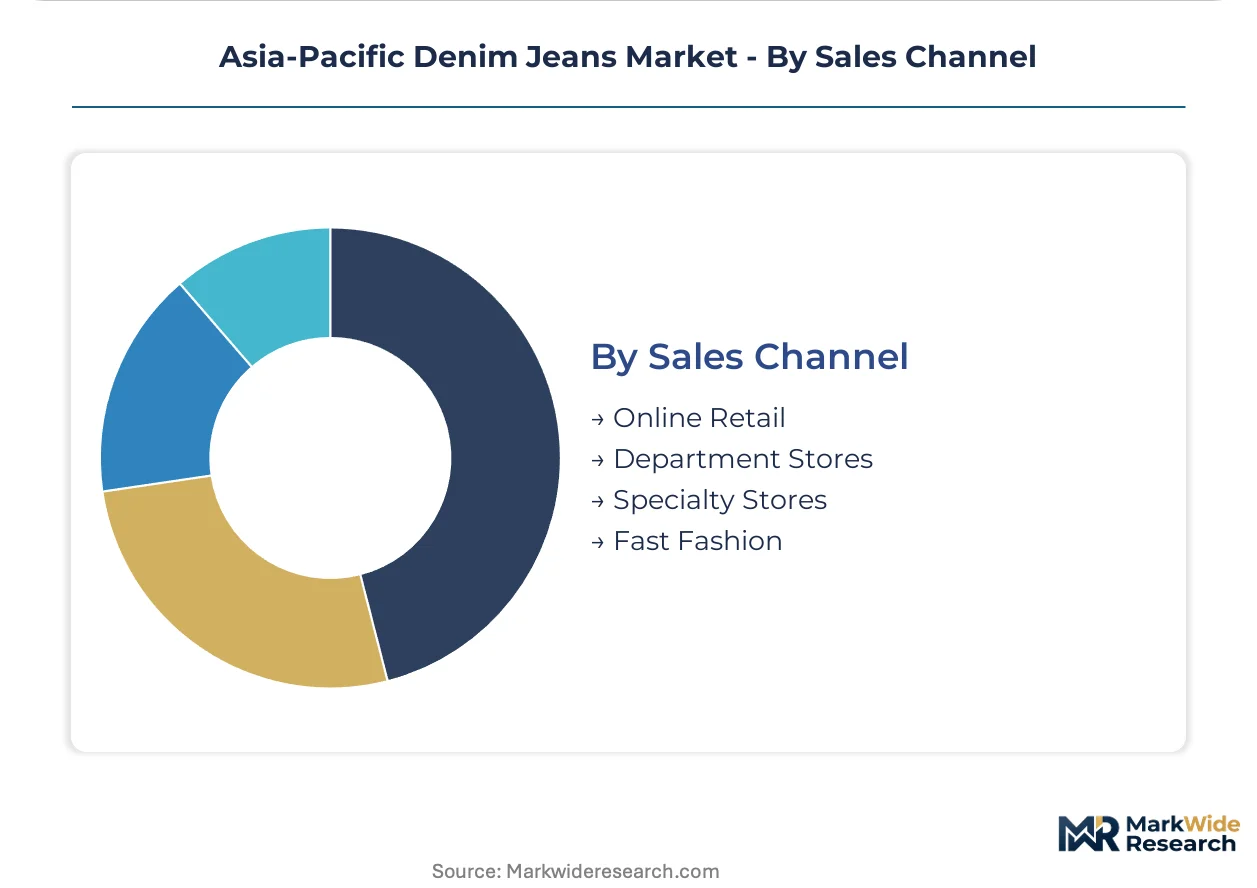
The EU Green Deal's extraterritorial reach into Asian textile supply chains is repositioning procurement standards for denim exporters. Levi Strauss & Co. leverages its Water Denim jeans in the Asia-Pacific context constitute twill-woven cotton garments distinguished by indigo-dyed warp threads and white weft, typically constructed from 10–14 oz fabric weights with rivet-reinforced stress points for durability. The primary commercial purpose spans casual apparel, workwear, and fashion retail across mass-market and premium tiers. Skinny jeans and relaxed fit variants dominate volume sales through fast fashion channels, while selvedge denim and organic cotton fabric types command margin concentration in Japanese and South Korean specialty retail. Online retail sustains the fastest trajectory, displacing department store foot traffic across Indonesian and Vietnamese consumer bases. India's BIS enforces mandatory fiber content labeling and colorfastness standards for imported denim, tightening market access for unverified suppliers. China's SAMR monitors GB standards for formaldehyde limits and azo dye restrictions under evolving environmental enforcement protocols. METI in Japan administers JIS quality benchmarks that privilege domestic mills and certified regional partners. Stakeholders must track regulatory divergence between export-oriented manufacturing hubs and destination-market compliance requirements to anticipate cost and timeline impacts. The EU Green Deal's extraterritorial reach is forcing denim exporters across Bangladesh, Vietnam, and China to reconfigure finishing processes and chemical sourcing before products reach European retail shelves. Get the full picture before you read further. Download a free sample with table of contents, companies, segments, and methodology. Laser finishing and ozone washing are displacing traditional water-intensive processes across Asia-Pacific manufacturing clusters, compressing environmental footprints while accelerating style-cycle turnaround. Laser abrasion technology is integrating robotic precision into surface distressing, eliminating manual sandblasting health hazards. Fast fashion retailers in Guangzhou and Dhaka are adopting these systems to compress prototype-to-production timelines from weeks to days. The technology is integrating design flexibility with compliance documentation, enabling real-time audit trails for EU importer due diligence. China's SAMR is tightening GB standards for azo dye restrictions and wastewater discharge under evolving MEE environmental protocols. Mills in Zhejiang and Jiangsu provinces face facility closures or costly effluent treatment upgrades. Premium denim exporters are responding by relocating finishing capacity to Vietnamese industrial zones with newer infrastructure. Direct-to-consumer subscription models are fragmenting traditional wholesale relationships in Australian and South Korean urban markets. Younger cohorts in Sydney and Seoul now expect personalized fit algorithms and home try-on programs, displacing department store denim floors. This channel rotation is most visible in Tokyo's Shibuya and Harajuku districts, where flagship experiential retail now serves as marketing rather than volume fulfillment. Denim jeans segmentation in the Asia-Pacific region reflects divergent upgrade cycles across consumer cohorts. Fabric innovation and channel fragmentation are redefining how manufacturers prioritize SKU investment and geographic rollout sequencing. Replacement frequency varies sharply by silhouette, with form-fitting styles demanding faster turnover due to stretch degradation and shape loss. Volume placements concentrate in Relaxed Fit Jeans; the faster expansion belongs to Wide Leg Jeans. Customer lifetime value calculations favor cohorts with higher per-unit spend and lower return rates, reshaping marketing allocation across the region. Women's segment commands absolute volume; Unisex is climbing the fastest as brand positioning shifts. Raw material certification tiers are creating pricing stratification that separates premium positioning from mass-market competition. Stretch Denim maintains volume dominance; Selvedge Denim shows steepest expansion trajectory in per-unit value terms. Channel economics are inverting as logistics infrastructure and payment systems mature in previously underserved geographies. Fast Fashion retains volume concentration; Online Retail is gaining share fastest across Indonesian and Vietnamese consumer bases. Need this report tailored to your region? Request specific countries, segments, or companies — tailored to your requirements. Guangzhou's manufacturing corridor dominates Asia-Pacific denim production, feeding fast fashion networks across Southeast Asian retail channels with compressed design-to-shelf timelines. Urban professionals in Shanghai and Beijing drive premium denim adoption through workplace casualization policies. SAMR enforces stricter GB standards for formaldehyde limits and azo dye restrictions under dual carbon protocols. Zhejiang and Jiangsu mill clusters face facility closures or costly effluent treatment upgrades, pushing finishing capacity toward Vietnamese industrial zones. Tier-one cities Mumbai and Delhi sustain selvedge and raw denim demand among male consumers with 18-24 month replacement cycles. BIS mandates mandatory fiber content labeling and colorfastness standards for imported denim, squeezing gray-market competitors from Pakistani informal channels. Ahmedabad and Surat textile clusters retool for certified cotton traceability to capture premium positioning. Tokyo's Shibuya and Harajuku districts anchor experiential flagship retail serving marketing rather than volume fulfillment. METI administers JIS quality benchmarks that privilege domestic mills and certified regional partners. Okayama and Kojima mill clusters leverage heritage selvedge craftsmanship for margin concentration against mass-market imports. Seoul's Gangnam and Hongdae retail corridors drive wide-leg and unisex silhouette adoption among fashion-forward segments. Younger cohorts expect personalized fit algorithms and home try-on programs, fragmenting traditional wholesale relationships. Busan-Ulsan manufacturing zones supply stretch-dominant fabrics for 8-14 month replacement cycles across women's casual wear. Jakarta's urban professional cohorts expand weekday denim rotation beyond weekend wear through workplace dress code relaxation. Tokopedia and Shopee logistics networks open tier-two cities previously unreachable by department store distribution. Bandung and Surabaya manufacturing clusters feed fast fashion channels with heat-tolerant relaxed fit constructions. Premium-margin players sit above commodity-margin players across certification tier and finishing technology differentiation. The vendor base stratifies between heritage selvedge houses, vertically integrated mass manufacturers, and platform-native direct-to-consumer brands. Three archetypes dominate: JIS-certified Japanese mills, Water Within the heritage certification tier, Edwin Co., Ltd. exemplifies selvedge authenticity positioning, while Levi Strauss & Co. anchors resource-efficient technology licensing across Bangladeshi contract facilities. PVH Corp. occupies a position bridging premium distribution network scale with Calvin Klein and Tommy Hilfiger brand architecture in Shanghai and Tokyo retail corridors. Heritage certification ladders create sharp bifurcation between Japanese selvedge houses commanding margin premiums and Bangladeshi mass manufacturers absorbing cost compression, with EU Green Deal compliance costs filtering through to wholesale pricing while procurement teams reconfigure chemical sourcing and finishing capacity placement.
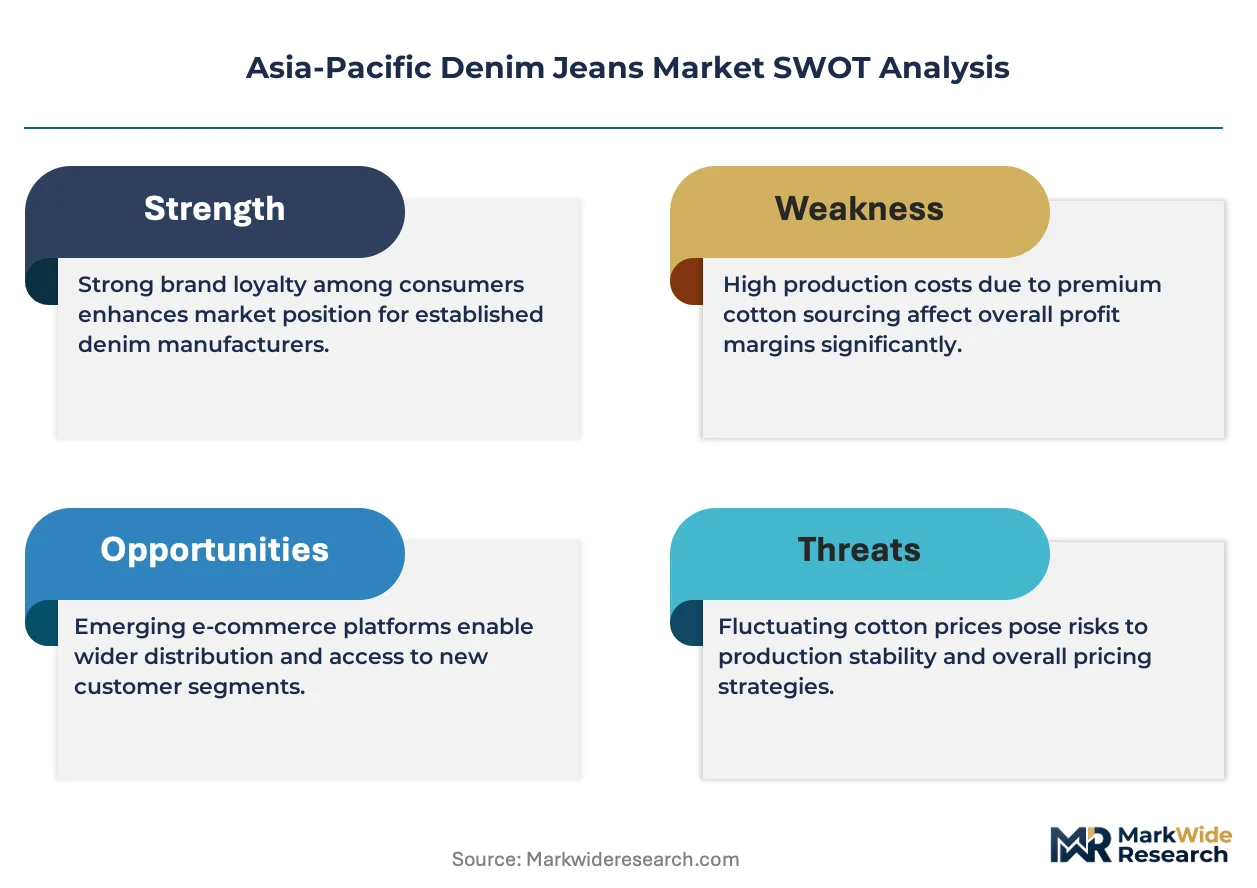
Value-based pricing anchors to JIS heritage certification and Water Certification gating through BIS fiber labeling, GB formaldehyde limits, and EU Green Deal chemical restrictions fragments supplier eligibility across Bangladesh, Vietnam, and China. Raw material sourcing draws from Turkish and Indian organic cotton clusters, Japanese indigo dye specialists, and petroleum-based elastane producers. Single-source vulnerability concentrates in shuttle-loom selvedge capacity at Okayama and Kojima mills. Distribution runs through platform-native e-commerce networks in Indonesia and experiential flagship corridors in Tokyo and Seoul. Get the full picture before you read further. Download a free sample with table of contents, companies, segments, and methodology. This market functions as a vertical-integration race where control over certified cotton traceability and laser finishing capacity determines margin capture, with upstream chemical compliance and downstream channel access as the contested levers. For Market Incumbents: Hedge against EU Green Deal cost pass-through by securing captive organic cotton supply from Indian and Turkish certified growers. Reinforce positioning through backward integration into laser finishing equipment and effluent treatment infrastructure. Defend against platform-native entrants by locking exclusive shelf space with Tokopedia and Shopee category managers. For New Entrants and Emerging Players: Direct-to-consumer algorithmic fit specialists offer the most penetrable entry vector, targeting Australian and South Korean urban cohorts with personalized home try-on programs. White-space exists in unisex gender-fluid positioning with neutral sizing reducing SKU complexity. Launch through Instagram-native and TikTok commerce integration before legacy wholesale relationships solidify. For Investors and Strategic Acquirers: Re-rating potential sits with JIS-certified Japanese mill clusters given blockchain-cotton traceability convergence as a catalyst. Long-term viability favors heritage authenticity positioning over commodity stretch manufacturing. Watch for METI certification expansion announcements as inflection signals for margin expansion. Trade statistics from customs authorities, textile industry association publications, and regulatory filing databases formed the secondary backbone, cross-referenced with primary interviews spanning denim mill operations directors, fast fashion procurement leads, specialty retail category buyers, and METI certification administrators. Bottom-up volume modeling triangulated against top-down value estimates derived from retail audit data and channel shipment reports. Historical trendline analysis established baseline growth patterns across the projection horizon, with segmentation modeling incorporating product type, fabric certification tier, target customer cohort, and sales channel dimensions. CAGRs were derived from fitted growth curves applied to verified baseline values, incorporating EU Green Deal compliance cost trajectories and e-commerce penetration curves as industry-specific forecast inputs. Caveats apply where BIS enforcement intensity, SAMR facility closure decisions, or EU Green Deal chemical restriction expansion could materially shift the outlook. Forecasts reflect documented assumptions regarding organic cotton supply availability and laser technology adoption rates. A model refresh is warranted upon material change in METI certification scope or major platform e-commerce logistics network expansion.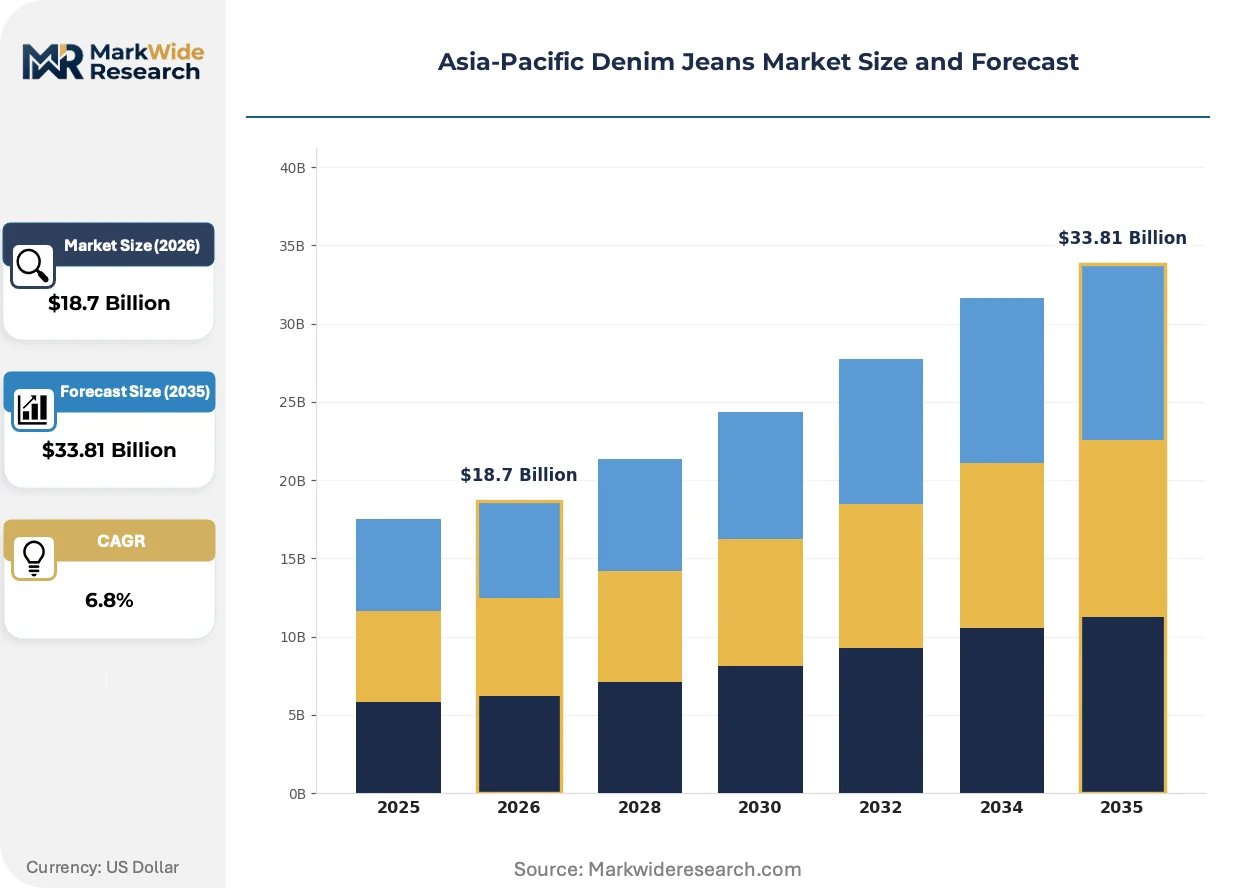
Market Dynamics
Growth Catalysts
Market Restraints
Strategic Opportunities
Industry Challenges
Report Scope
MarkWide ResearchAttributes Details Report Title Asia-Pacific Denim Jeans Market Market Size in 2026 $18.7 Billion Market Size in 2035 $33.81 Billion CAGR (2026 – 2036) 6.8% Historical Year 2020-2024 Base Year 2025 Forecast Period 2026-2036 Segmentation Companies Covered PVH Corp., Edwin Co., Ltd., Levi Strauss & Co., Diesel, H&M Group, Uniqlo, VF Corporation, TAL Apparel, Gap Inc., Others Regions Covered Asia-Pacific Denim Jeans Market Trends and Innovations
Asia-Pacific Denim Jeans Market Segmentation
Product Type:
Target Customer:
Fabric Type:
Sales Channel:
Regional Outlook
China
India
Japan
South Korea
Indonesia
Asia-Pacific Denim Jeans Market Competitive Landscape
Leading Market Players PVH Corp. Edwin Co., Ltd. Levi Strauss & Co. Diesel H&M Group Uniqlo VF Corporation TAL Apparel Gap Inc. Others Pricing and Supply Chain Analysis
Pricing Analysis
Supply Chain Analysis
Analyst Recommendations
Strategic Initiative
Industry Significance
Blockchain-Cotton Traceability Integration
Farm-to-retail digital verification commands shelf-space premiums in Australian specialty retail.
Laser Finishing Capacity Expansion
Robotic precision surface distressing eliminates manual sandblasting hazards while compressing prototype timelines.
Direct-to-Consumer Channel Launch
Algorithmic fit matching fragments traditional wholesale relationships in Seoul and Sydney urban markets.
Heritage Certification Investment
METI-backed JIS standards create pricing power for Okayama mills against mass-market imports.
Sustainability Repositioning
Water Research Methodology
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Hats Market
Apparel & Footwear
Asia Pacific Swimwear Market
Apparel & Footwear
Outdoor Apparel and Accessories Market
Apparel & Footwear
Women's Coats and Jackets Market
Apparel & Footwear
Men Shirts Market
Apparel & Footwear
Fast Fashion Apparel Market
Apparel & Footwear
Global Swimwear (Swimsuit) Market
Apparel & Footwear
Luxury Fashion Market
Apparel & Footwear
France Denim Jeans Market
Apparel & Footwear
Polo Shirt Market
Apparel & Footwear
Global Sleepwear and Loungewear Market
Apparel & Footwear
Compression Wear and Shapewear Market
Apparel & Footwear
Europe Denim Jeans Market
Apparel & Footwear
Sports Apparel Embellishment Market
Apparel & Footwear
Golf Apparel Market
Apparel & Footwear
Rugby Apparel Market