
 Middle East and Africa Smart Home Market | 2026-2036
Middle East and Africa Smart Home Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Smart Home Market Insights
Energy efficiency certification tiers is redrawing competitive positioning across the Middle East and Africa Smart Home Market. Samsung Electronics Co., Ltd. leverages its integrated appliance ecosystem to dominate premium residential installations in Gulf markets. Schneider Electric SE anchors its position through building management convergence, while ABB Ltd. specializes in industrial-grade automation repurposed for luxury home segments.
A smart home comprises interconnected devices, sensors, and control systems that automate environmental management, security, entertainment, and energy functions through centralized or distributed network architectures. These systems typically operate on communication protocols including Zigbee mesh networks, Wi-Fi infrastructure, and Z-Wave low-power radio to enable real-time data exchange and remote command execution. Security Systems command substantial margin pools due to escalating safety investments across gated communities and commercial complexes. HVAC automation exhibits the fastest structural expansion as Gulf nations enforce stringent building energy codes. Professional installation channels retain premium pricing power where retrofit complexity demands certified integration expertise.
Saudi Arabia's national regulator and the UAE's telecommunications authority shape device certification, data localization requirements, and interoperability standards that determine market access across Gulf markets. South Africa's national standards body and Nigeria's communications commission impose additional compliance layers for wireless spectrum allocation and electrical safety. Stakeholders must monitor evolving cybersecurity mandates and cross-border data governance frameworks as these jurisdictions deepen digital infrastructure sovereignty requirements.
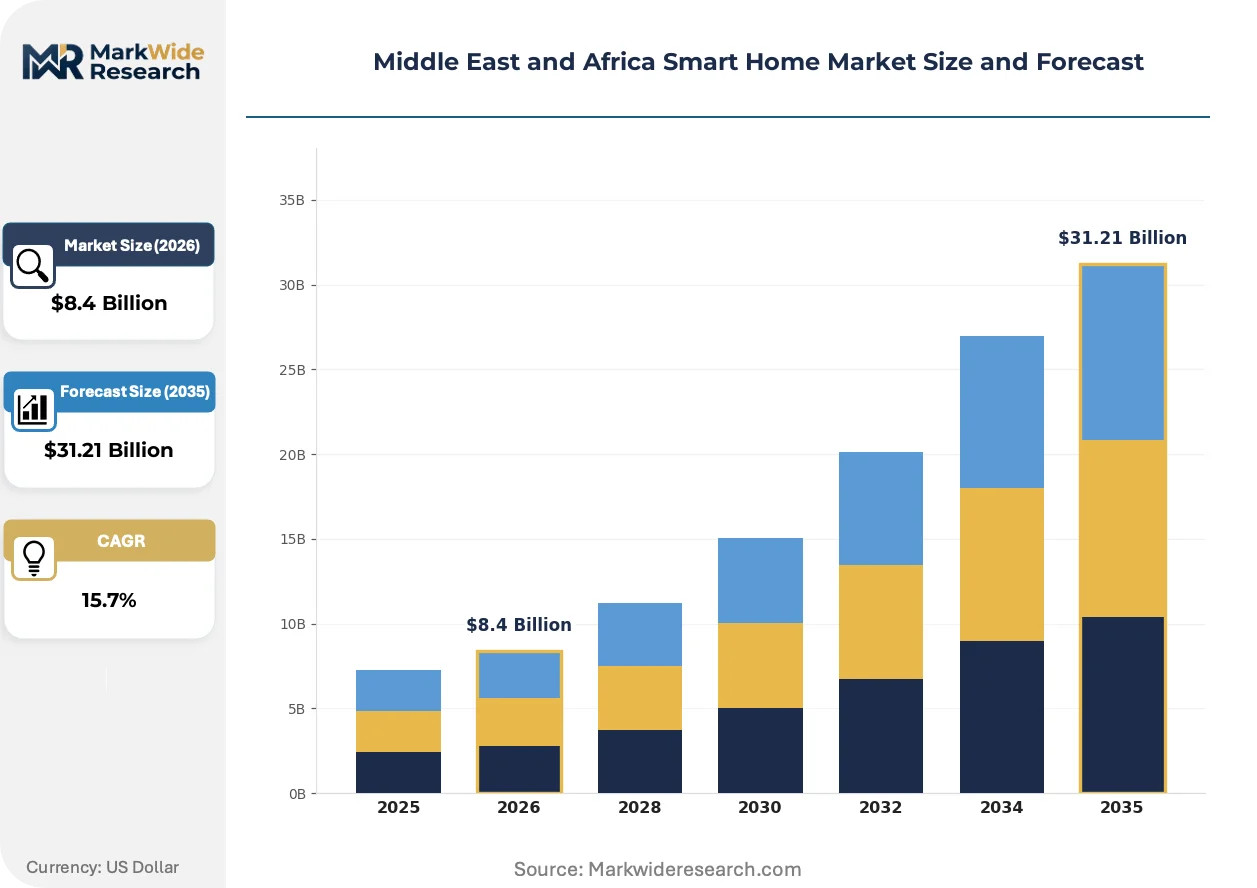
Market Dynamics
Energy efficiency mandates from Saudi Arabia's national regulator and the UAE's telecommunications authority are compressing deployment timelines for integrated automation systems across Gulf residential developments.
Growth Catalysts
- HVAC Automation:Gulf nations enforce stringent building energy codes that mandate climate control optimization in new construction, accelerating system retrofit mandates.
- Saudi Smart City Framework:National building efficiency standards require integrated automation in government-backed residential developments, creating procurement pull-through.
- Mesh Network Protocols:Zigbee and Z-Wave infrastructure deployment enables real-time device coordination without proprietary lock-in, lowering integration barriers for mid-market installers.
Market Restraints
- Semiconductor Supply Concentration:Chip fabrication bottlenecks in East Asian foundries delay controller and sensor shipments to MEA distribution channels.
- Data Localization Requirements:Cross-border data governance frameworks in the UAE and Saudi Arabia impose server infrastructure costs that inflate SaaS pricing for cloud-dependent platforms.
- Wireless Spectrum Fragmentation:Nigeria's communications commission and South Africa's national standards body maintain non-harmonized frequency allocations, forcing hardware variants.
Strategic Opportunities
- Nigeria Urban Housing:Lagos and Abuja master-planned communities remain underpenetrated for integrated security and energy management relative to Gulf saturation.
- Professional Installation Channel:Certified integration expertise commands premium pricing where retrofit complexity exceeds consumer DIY capacity in heritage building stock.
- MOHAP Device Certification:UAE health-adjacent wellness monitoring devices gain accelerated approval pathways, opening medical-grade environmental sensing for residential deployment.
Industry Challenges
- Cybersecurity Skill Scarcity:Network security architecture expertise for IoT device hardening concentrates in Dubai and Riyadh consulting pools, leaving secondary cities underserved.
- Interoperability Certification Delays:Multi-protocol gateway testing against SFDA and national standards body requirements extends product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Smart Home Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $31.21 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lighting, Security Systems, HVAC, Appliances Technology: Wi-Fi, Zigbee, Bluetooth, Z-Wave End User: Residential, Commercial, Hospitality, Healthcare Installation: DIY, Professional, Retrofit, New Build |
| Companies Covered | Schneider Electric SE, Honeywell International Inc., ABB Ltd., Siemens AG, Johnson Controls International plc, Samsung Electronics Co., Ltd., Google LLC, Amazon.com, Inc., LG Electronics Inc., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Smart Home Market Trends and Innovations
Protocol standardization and regulatory convergence are compressing the gap between industrial-grade building management and residential automation across Middle East and Africa markets.
Matter-over-Thread connectivity is bifurcating the installed base between legacy Z-Wave estates and next-generation IP-native devices. Premium developers in Dubai's mega-developments adopt Thread-native hardware for greenfield construction. This technology is bifurcating supplier tiers between IP-capable manufacturers and protocol-locked incumbents facing margin compression.
SFDA cybersecurity mandates for connected medical-adjacent devices now extend to wellness sensors in Saudi residential deployments. Hardware manufacturers must embed encryption modules that comply with national data sovereignty requirements. HVAC automation suppliers face the steepest compliance cost escalation as environmental sensors fall under expanded medical-device classification.
Developer-led specification is displacing end-user choice in Gulf Cooperation Council luxury residential procurement. Emaar and Aldar master developments pre-install integrated automation stacks, removing consumer brand selection. This concentration is most visible in Dubai's premium tower segment where buyer customization extends only to finish packages, not core infrastructure.
Middle East and Africa Smart Home Market Segmentation
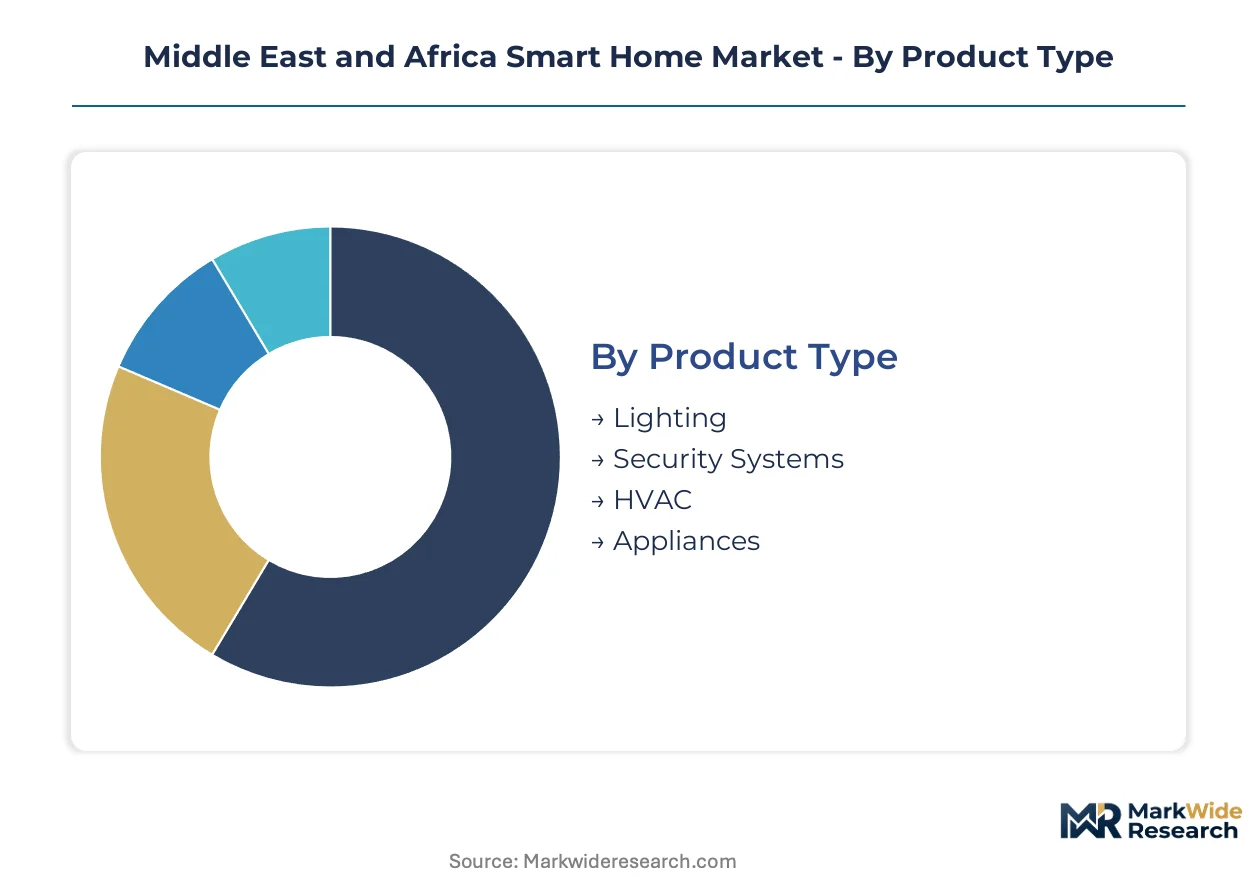
Segmentation in the Middle East and Africa Smart Home Market reveals how procurement authority, technical architecture, and installation constraints reshape vendor access. Gulf regulatory frameworks and construction cycles concentrate margin pools in distinct configuration clusters.
Product Type:
Margin pools concentrate in systems commanding recurring monitoring revenue and energy code compliance leverage.
- Security Systems:Integrated surveillance, access control, and intrusion detection platforms generate substantial service attach rates across gated communities in Dubai and Riyadh. Saudi Arabia's building efficiency mandates and UAE safety investments for commercial complexes sustain premium pricing for certified installations.
- HVAC:Climate control automation exhibits the steepest expansion trajectory as Gulf nations enforce stringent energy codes in new construction. Saudi Smart City developments and Dubai mega-projects mandate integrated environmental management, accelerating retrofit requirements in existing stock.
- Lighting:Connected luminaire systems with occupancy sensing and daylight harvesting reduce operational expenditure in commercial towers across Abu Dhabi master-planned communities.
- Appliances:Interconnected white goods leverage ecosystem lock-in for premium residential developments where developer specification overrides consumer brand selection.
Security Systems hold installed capacity. HVAC is rotating up the share rankings.
Technology:
Protocol selection determines hardware cost structures, interoperability certification timelines, and installer skill requirements across fragmented national standards.
- Zigbee:Mesh network architecture enables real-time device coordination without proprietary lock-in, lowering integration barriers for mid-market installers serving Saudi residential developments. The protocol's low-power radio characteristics suit battery-operated sensor deployments in heritage building retrofits.
- Wi-Fi:IP-native infrastructure dominates greenfield construction in Dubai premium towers where Thread-over-Wi-Fi convergence accelerates, though power consumption limits sensor battery life.
- Z-Wave:Sub-GHz spectrum penetration through concrete structures supports multi-dwelling unit deployments in older Abu Dhabi and Jeddah residential compounds.
- Bluetooth:Low-energy beacon protocols enable proximity-based automation triggers for hospitality guest room management in UAE luxury hotel developments.
Zigbee maintains protocol share leadership. Wi-Fi is climbing the fastest in new construction specification.
End User:
Procurement authority concentrates with developers and facilities managers rather than individual consumers across high-value installation clusters.
- Residential:Luxury segment demand anchors in UAE mega-developments where Emaar and Aldar pre-install integrated automation stacks, removing buyer customization for core infrastructure. Saudi national housing programs mandate efficiency standards that pull through system procurement.
- Commercial:Office and retail complexes in Dubai International Financial Centre and Riyadh King Abdullah Financial District prioritize building management convergence for operational cost reduction.
- Hospitality:Guest experience automation and energy management systems serve UAE and Saudi hotel construction pipelines targeting international brand standards.
- Healthcare:MOHAP wellness device certification pathways in UAE enable medical-grade environmental sensing for residential deployment, extending into aged care facilities.
Residential commands volume scale. Commercial is gaining share fastest in retrofit mandates.
Installation:
Channel structure determines pricing power through technical complexity barriers and certification requirements.
- Professional:Certified integration expertise commands premium pricing where retrofit complexity exceeds consumer capacity in heritage building stock across Jeddah and older Dubai districts. SFDA and national standards body testing extends gateway product launch timelines, reinforcing specialist installer moats.
- New Build:Developer-led specification in Gulf Cooperation Council luxury residential procurement removes end-user choice, concentrating volume with systems integrators holding master development relationships.
- DIY:Consumer self-installation concentrates in entry-level Wi-Fi devices for apartment segments in South Africa and Nigeria urban housing.
- Retrofit:Wireless protocol deployment enables automation in existing structures without structural modification, though mesh network planning demands professional commissioning for reliable performance.
Professional installation holds margin concentration. New Build is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in Gulf Cooperation Council markets where developer-led procurement and national efficiency mandates compress deployment timelines. Saudi Arabia and the United Arab Emirates anchor regional demand through smart city frameworks and mega-development pipelines. Secondary markets in Nigeria and South Africa present contrasting growth profiles shaped by infrastructure gaps and wireless spectrum fragmentation.
United Arab Emirates
Dubai's mega-developments and Abu Dhabi's master-planned communities drive premium smart home specification through developer-led procurement. MOHAP certification pathways for wellness monitoring devices accelerate medical-grade environmental sensing deployment. Emaar and Aldar developments in Dubai Marina and Saadiyat Island pre-install integrated automation stacks, removing end-user customization for core infrastructure.
Saudi Arabia
National smart city frameworks and building efficiency mandates reshape procurement standards across government-backed residential developments. The Saudi Food and Drug Authority extends cybersecurity requirements to connected wellness sensors, embedding encryption modules for data sovereignty compliance. NEOM and Riyadh master developments mandate integrated HVAC automation under national energy codes.
South Africa
Urban housing retrofits and commercial building efficiency programs sustain mid-market demand for wireless automation systems. The national standards body imposes additional compliance layers for wireless spectrum allocation and electrical safety certification. Johannesburg and Cape Town heritage building stock drives professional installation channels where retrofit complexity exceeds consumer DIY capacity.
Nigeria
Lagos and Abuja master-planned communities remain underpenetrated for integrated security and energy management relative to Gulf market saturation. The country's communications commission maintains non-harmonized frequency allocations, forcing hardware variants and extending product launch timelines. Victoria Island and Ikoyi luxury residential clusters present concentrated demand for gated community security platforms.
Middle East and Africa Smart Home Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle East and Africa Smart Home Market. Industrial automation specialists and consumer electronics conglomerates anchor distinct tier positions, while building management convergence creates overlapping competitive territory. Three archetypes dominate: integrated appliance ecosystem providers, industrial-grade automation repurposers, and cloud-native platform operators. Strategic moves concentrate on developer partnership lock-ins and certification acceleration to compress interoperability testing timelines.
Within the industrial automation tier, Schneider Electric SE and ABB Ltd. occupy positions shaped by building management convergence capabilities. Samsung Electronics Co., Ltd. anchors the consumer-facing segment through integrated appliance ecosystems. These three entities exemplify how Gulf market procurement authority concentrates with developers rather than end-users, privileging players with master development relationship infrastructure.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Honeywell International Inc. |
| ABB Ltd. |
| Siemens AG |
| Johnson Controls International plc |
| Samsung Electronics Co., Ltd. |
| Google LLC |
| Amazon.com, Inc. |
| LG Electronics Inc. |
| Others |
Pricing and Supply Chain Analysis
SFDA cybersecurity mandates and MOHAP device certification pathways gate both supply qualification and price differentiation across Middle East and Africa smart home procurement. Compliance investment requirements stratify vendor tiers while developer-led specification in Gulf mega-developments concentrates pricing power with certified integrators.
Pricing Analysis
SFDA and MOHAP certification tiers dictate the pricing tier structure across security and wellness monitoring segments. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade encrypted hardware from commercial-grade and unlicensed alternatives. Cost compression in mid-market Wi-Fi devices intensifies because East Asian chip fabrication bottlenecks extend controller lead times. DIY apartment buyers in South Africa and Nigeria urban housing exhibit highest price sensitivity; Emaar and Aldar master development procurement shows lowest sensitivity due to specification lock-in.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for Zigbee and Thread protocol chipsets serving Gulf automation deployments. China and Vietnam feed assembly capacity for sensor housings and gateway enclosures. Semiconductor supply draws from concentrated East Asian foundries, creating single-source vulnerability when geopolitical friction disrupts shipping lanes through the Strait of Malacca. Distribution runs through Dubai-based systems integrators holding master development relationships with Saudi and UAE developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment creates durable defensive moats in this market. Certification timelines and developer specification lock-in protect incumbent positions against price-based disruption.
For Market Incumbents: Secure master development partnership renewals in NEOM and Riyadh master developments before Matter-over-Thread protocol shifts displace Z-Wave legacy estates. Deepen backward integration into encrypted module production to deflect SFDA compliance cost escalation. Channel control through certified installer networks remains the critical lever against cloud-native platform entrants. For New Entrants and Emerging Players: Differentiate on Nigerian and South African wireless spectrum fragmentation by offering multi-frequency hardware variants that incumbent protocol-locked suppliers cannot match. Lagos and Abuja master-planned communities present the most penetrable white space. Direct contractor relationships bypass developer specification barriers in heritage building retrofits. For Investors and Strategic Acquirers: UAE health-adjacent wellness monitoring certification reshapes the acquisition landscape toward medical-grade environmental sensing capabilities. Long-term viability favors players with embedded encryption module expertise and data sovereignty architecture. The signal to watch is MOHAP pathway acceleration for residential medical device classification.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Acceleration Investment | SFDA and MOHAP pre-approval compresses gateway launch timelines by 8-14 months. |
| Master Development Partnership Lock-in | Emaar and Aldar specification concentration removes end-user brand competition. |
| Multi-Protocol Hardware Engineering | Zigbee-Z-Wave-Thread convergence addresses Nigerian and South African spectrum fragmentation. |
| Encrypted Module Backward Integration | In-house production of data sovereignty-compliant components deflects compliance cost escalation. |
| Professional Installer Channel Control | Certified integration expertise commands premium pricing in Jeddah and older Dubai districts. |
Research Methodology
Operator-level perspectives from smart home systems integrators, facilities managers at Emaar and Aldar developments, SFDA regulatory affairs specialists, and Nigerian communications commission spectrum planners anchored the qualitative base. Secondary validation drew from Saudi building efficiency mandate filings, UAE telecommunications authority device certification databases, Dubai customs import records for automation hardware, and SEC 10-K disclosures from listed industrial automation suppliers. Bottom-up installation volume estimates and top-down construction pipeline valuations were triangulated to cross-check market sizing.
Sensitivity analysis tested forecast outputs against variable adoption rates for Matter-over-Thread protocol migration and divergent Saudi Smart City deployment timelines. Segmentation dimensions modeled include product type, communication protocol, end-user vertical, and installation channel across the analysis window. HVAC automation growth trajectories were derived from national energy code enforcement intensity. Pricing elasticity assumptions incorporated developer specification concentration effects.
The analysis sits within stated boundaries; outcomes outside sustained Gulf construction pipeline execution or escalated East Asian semiconductor supply disruption would require recalibration. Forecasts reflect documented assumptions regarding regulatory compliance timeline stability and mesh network protocol convergence patterns. Recalibration cycles align with material shifts in SFDA cybersecurity mandate scope and MOHAP wellness device classification expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
GCC Perfume and Fragrance Market
Consumer Goods
Water Color Palette Market
Consumer Goods
Pet Noise Anxiety Market
Consumer Goods
Decorative Accessories Market
Consumer Goods
Tobacco Products Market
Consumer Goods
Incense Market
Consumer Goods
GCC School Stationery Supplies Market
Consumer Goods
Camping Equipment Market
Consumer Goods
Electric Hedge Trimmer Market
Consumer Goods
Bounce House Market
Consumer Goods
North America Functional Pet Treat Market
Consumer Goods
Neck Pillows Market
Consumer Goods
Mexico Cookware Market
Consumer Goods
Paw Plunger Market
Consumer Goods
Europe Household Appliances Market
Consumer Goods
Gulf Cooperation Council Fragrance and Perfumes Market