
 GCC Halal Cosmetics Market | 2026-2036
GCC Halal Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Halal Cosmetics Market Intelligence
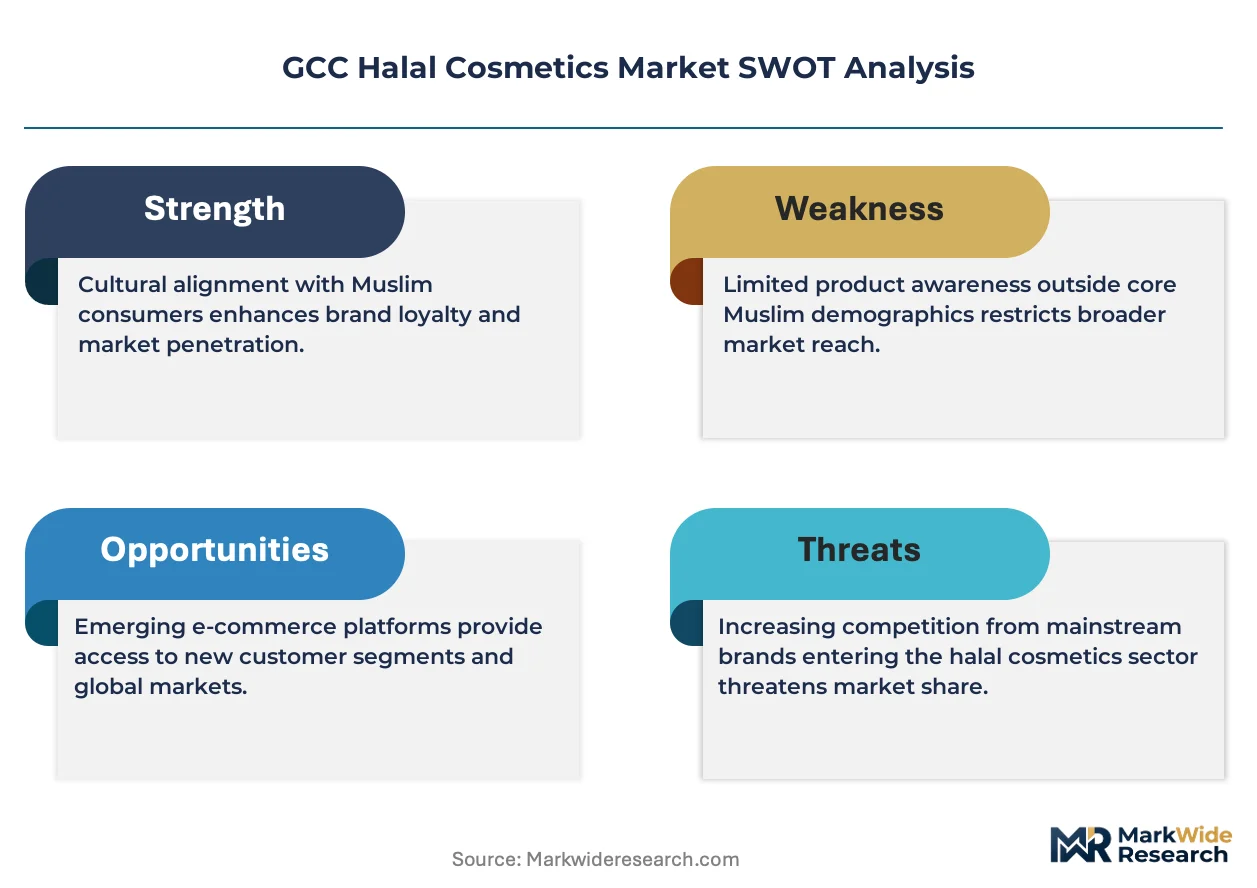
Saudi Arabia is reconfiguring GCC halal cosmetics manufacturing through new dedicated production zones and regulatory infrastructure. Amara Halal Cosmetics leverages its regional formulation expertise to dominate the Middle Eastern halal beauty landscape. Clara International Beauty Group sustains competitive positioning through specialized salon-grade halal product lines. Wardah Cosmetics anchors its GCC presence via extensive pharmacy and specialty store distribution networks.
Halal cosmetics encompass beauty and personal care products manufactured without alcohol, pork derivatives, or other haram substances, verified through Islamic certification processes that audit ingredient sourcing, production equipment, and supply chain integrity. These products serve Muslim consumers seeking faith-aligned personal care while expanding into broader ethical beauty markets. Skincare leads product type revenue pools due to higher per-unit pricing and repeat purchase frequency across Gulf climates. Online retail competes aggressively with brick-and-mortar channels as digital-native consumers in the GCC shift discovery and purchase behavior toward e-commerce platforms and social commerce.
ESMA in the UAE, SASO in Saudi Arabia, and GSO standards across the Gulf collectively enforce halal certification requirements that determine market access and consumer trust. These frameworks mandate ingredient transparency, production facility audits, and supply chain traceability that raise compliance costs but filter non-compliant imports. Stakeholders must monitor certification reciprocity agreements between Gulf states and emerging halal certification bodies in Southeast Asia that could reshape competitive dynamics.
Market Dynamics
ESMA's halal certification mandate in the UAE is compressing product development timelines and forcing reformulation investments across GCC manufacturing bases. This regulatory pressure cascades through supply chains as brands race to secure compliant ingredient sourcing before enforcement deadlines.
Growth Catalysts
- Social commerce penetration:Young Saudi consumers discover halal beauty products through Instagram and TikTok storefronts, converting engagement directly into purchase intent without traditional retail intermediaries.
- SASO regulatory harmonization:Saudi Arabia's standardization body is aligning national halal cosmetics rules with GSO frameworks, reducing cross-border compliance friction for manufacturers operating across multiple Gulf states.
- Pharmacy channel expansion:UAE and Saudi pharmacy chains are dedicating premium shelf space to certified halal skincare, treating these products as differentiated health-adjacent offerings rather than commodity beauty.
Market Restraints
- Halal ingredient scarcity:Certified alcohol-free preservatives and plant-derived alternatives to porcine emulsifiers command 40-60% price premiums over conventional inputs, squeezing gross margins for mid-market brands.
- Single-source certification dependency:ESMA and SASO currently recognize limited third-party certifiers, creating bottlenecks where audit capacity constraints delay product launches by 8-14 months.
- Technical formulation barriers:Substituting haram ingredients without compromising product stability or shelf life requires specialized R&D capabilities that remain concentrated in Malaysia and Indonesia.
Strategic Opportunities
- Men's grooming white space:Saudi Arabia's male consumer segment shows minimal halal cosmetics penetration relative to female categories, presenting first-mover advantage for beard care and fragrance lines targeting faith-aligned masculinity.
- Oman and Bahrain expansion:These smaller GCC markets lack domestic halal cosmetics manufacturing, creating import substitution opportunities for Saudi and UAE producers with excess certified capacity.
- Blockchain traceability integration:Combining halal certification with supply chain transparency technology addresses consumer skepticism about ingredient provenance, particularly for premium skincare positioned as ethically sourced.
Industry Challenges
- Formulation chemist scarcity:GCC universities produce minimal graduates trained in both cosmetic chemistry and Islamic jurisprudence, forcing brands to recruit expensive expatriate talent from Southeast Asian markets.
- Certification timeline compression:ESMA's accelerated audit schedules are straining laboratory testing capacity for ingredient verification, creating backlogs that delay product launches during peak seasonal demand windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Halal Cosmetics Market |
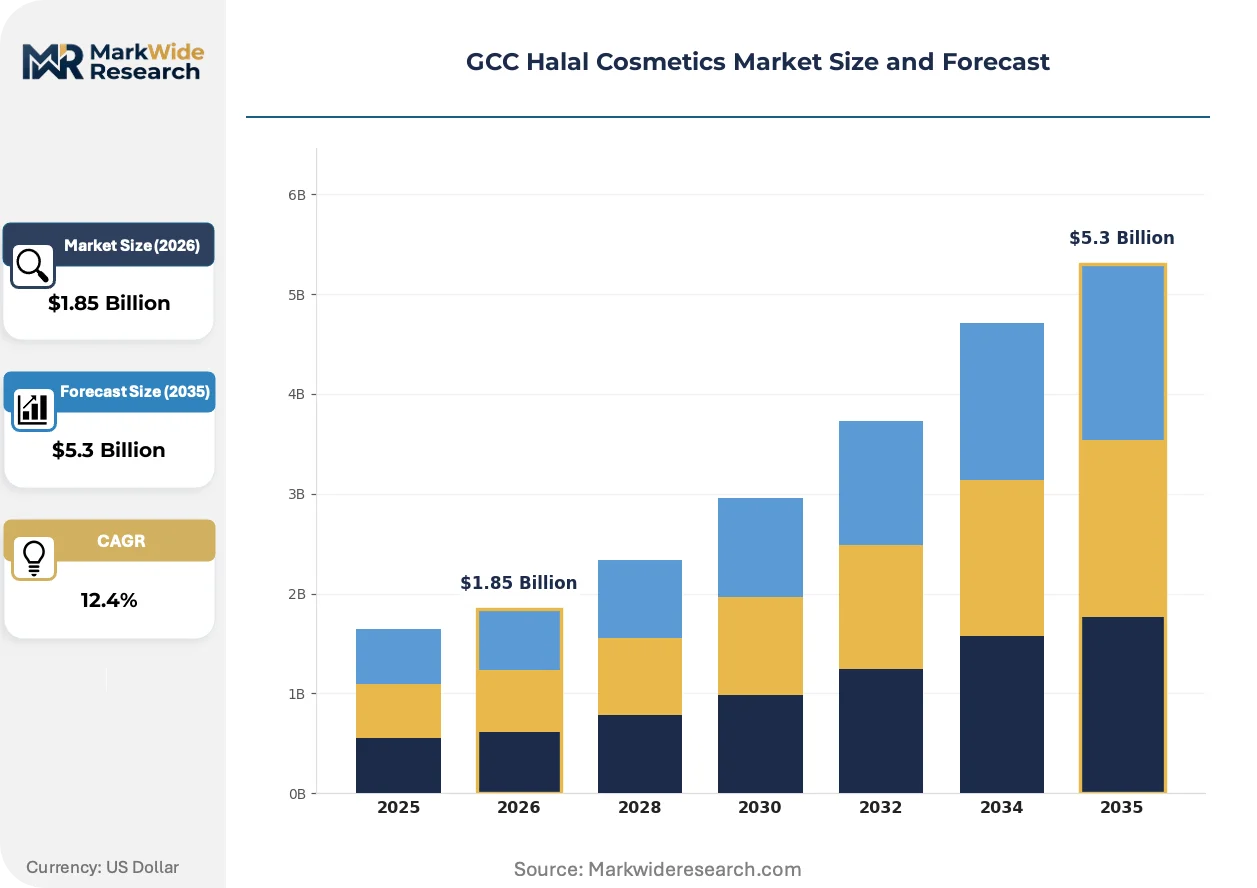
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.3 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Makeup, Haircare, Fragrance Certification Type: Halal Certified, Vegan, Organic, Cruelty-Free Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies Customer Type: Retail Consumers, Professional Salons, Grocery Chains, E-commerce Platforms |
| Companies Covered | Lush, PHB Ethical Beauty Ltd., Amara Halal Cosmetics, The Halal Cosmetics Company, Sampure Minerals, Clara International Beauty Group, OnePure LLC, Wardah Cosmetics, Iba Cosmetics, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Halal Cosmetics Market Strategic Shifts & Innovations
Digital verification tools and AI-driven formulation platforms are compressing the gap between concept and certified product in GCC halal cosmetics. These technologies intersect with tightening regulatory scrutiny to reshape how brands build consumer trust and operational compliance simultaneously.
Blockchain-based halal traceability systems are digitizing supply chain documentation from raw material sourcing through retail shelf placement. UAE-based manufacturers are piloting these platforms to provide real-time ingredient verification to discerning consumers. This transparency infrastructure is digitizing the relationship between certification bodies and end-users, reducing reliance on static paper documentation.
SASO's forthcoming cosmetics regulation amendments will mandate digital product registration and batch-level tracking for all imported halal beauty products entering Saudi Arabia. Manufacturers must reconfigure quality management systems to generate compliant data formats. The skincare segment faces the steepest compliance burden due to complex multi-ingredient formulations and shorter product lifecycles.
Subscription-based replenishment models are displacing traditional pharmacy and department store purchasing for core halal skincare routines. Saudi digital-native consumers prioritize convenience and personalization over in-person consultation. This channel shift concentrates most visibly in Riyadh and Jeddah, where same-day delivery infrastructure supports just-in-time inventory models for premium halal beauty brands.
GCC Halal Cosmetics Market Segmentation
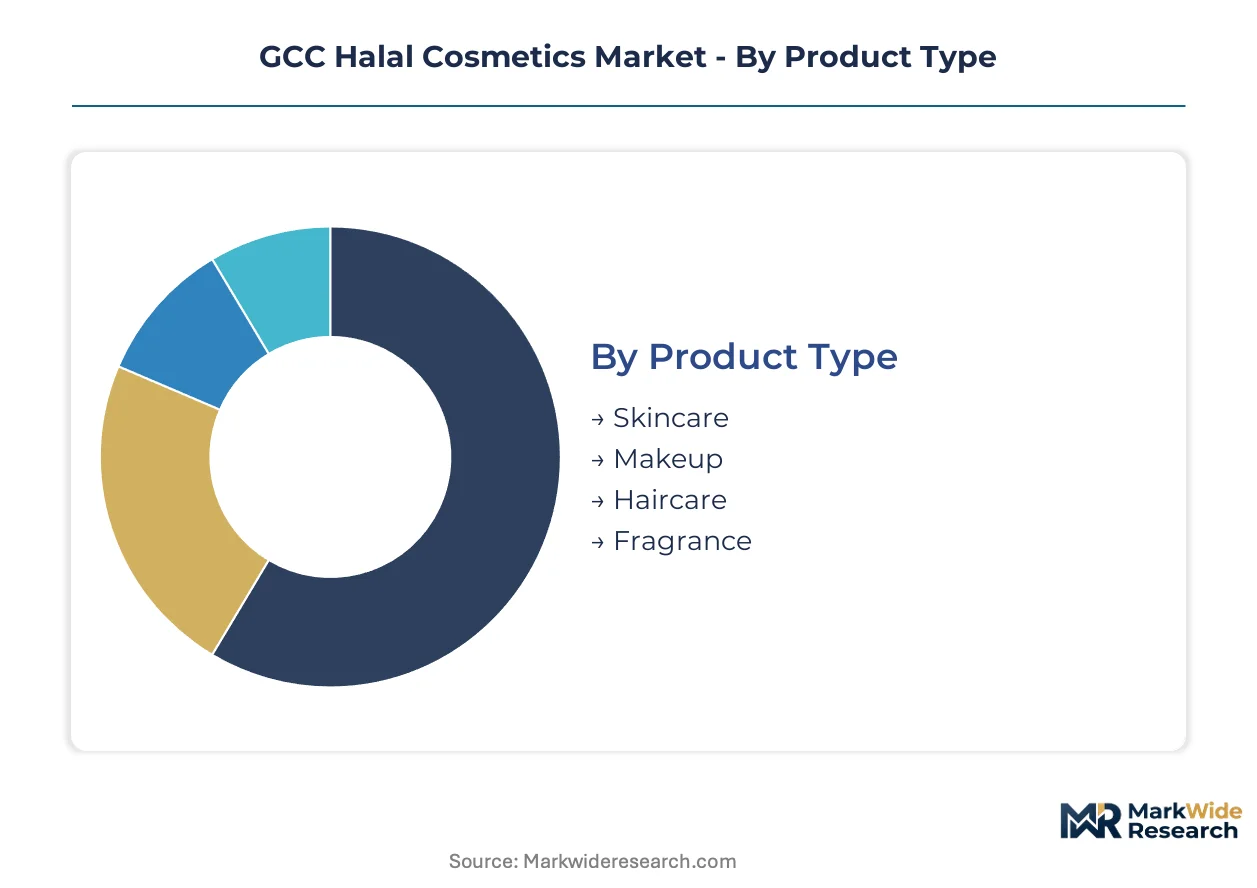
Segmentation in the GCC halal cosmetics market reveals distinct service intensity profiles across product categories. Certification complexity and channel-specific compliance requirements create divergent margin structures that reward specialized positioning.
Product Type:
After-sales service intensity varies sharply across product categories, with skincare demanding formulation guidance and repeat consultation while fragrance relies on sensory validation.
- Skincare:Multi-step regimens with ingredient-sensitive formulations require ongoing consumer education and repurchase support. Demand concentrates in Saudi Arabia's premium urban centers where dermatological consultation integrates with halal certification verification.
- Makeup:Color-matching services and shade compatibility testing drive higher touchpoint frequency than other categories. Professional salon channels in Dubai and Riyadh generate concentrated demand for long-wear, climate-adapted formulations.
- Haircare:Scalp treatment protocols and ingredient transparency requests dominate consumer inquiries.
- Fragrance:Alcohol-free formulation alternatives command sustained technical explanation at point of sale.
By volume, skincare leads. By growth pace, fragrance is ahead.
Certification Type:
Cost tier stratification separates premium-positioned multi-certification products from baseline halal-only offerings, with compliance stacking driving price architecture.
- Halal Certified:The foundational credential mandated by ESMA and SASO for market access, requiring facility audits and supply chain documentation. Saudi manufacturing zones report concentrated demand as brands localize production to satisfy domestic certification requirements.
- Vegan:Plant-derived formulation standards overlap with but exceed halal parameters, appealing to ethically motivated consumers beyond faith-aligned segments. UAE pharmacy chains dedicate expanding shelf space to dual-certified skincare lines.
- Organic:Agricultural input traceability adds cost premiums and sourcing complexity.
- Cruelty-Free:Animal testing prohibitions align with halal ethics while requiring separate audit protocols.
By volume, halal certified leads. By margin expansion, vegan is climbing fastest.
Distribution Channel:
Customer type concentration shapes channel investment priorities, with professional buyers demanding bulk certification documentation and end consumers prioritizing discovery convenience.
- Online Retail:Digital-native discovery platforms integrate ESMA verification badges with influencer-driven content. Saudi social commerce penetration concentrates demand in Riyadh and Jeddah where same-day delivery infrastructure supports subscription replenishment models.
- Specialty Stores:Curated assortment and trained staff consultation justify premium positioning. Dubai's mall-based beauty retailers generate concentrated demand for exclusive halal brand launches.
- Supermarkets:Mass-market price points and limited shelf space compress certification visibility.
- Pharmacies:Health-adjacent positioning elevates ingredient transparency expectations.
By volume, specialty stores lead. By channel shift velocity, online retail is expanding most quickly.
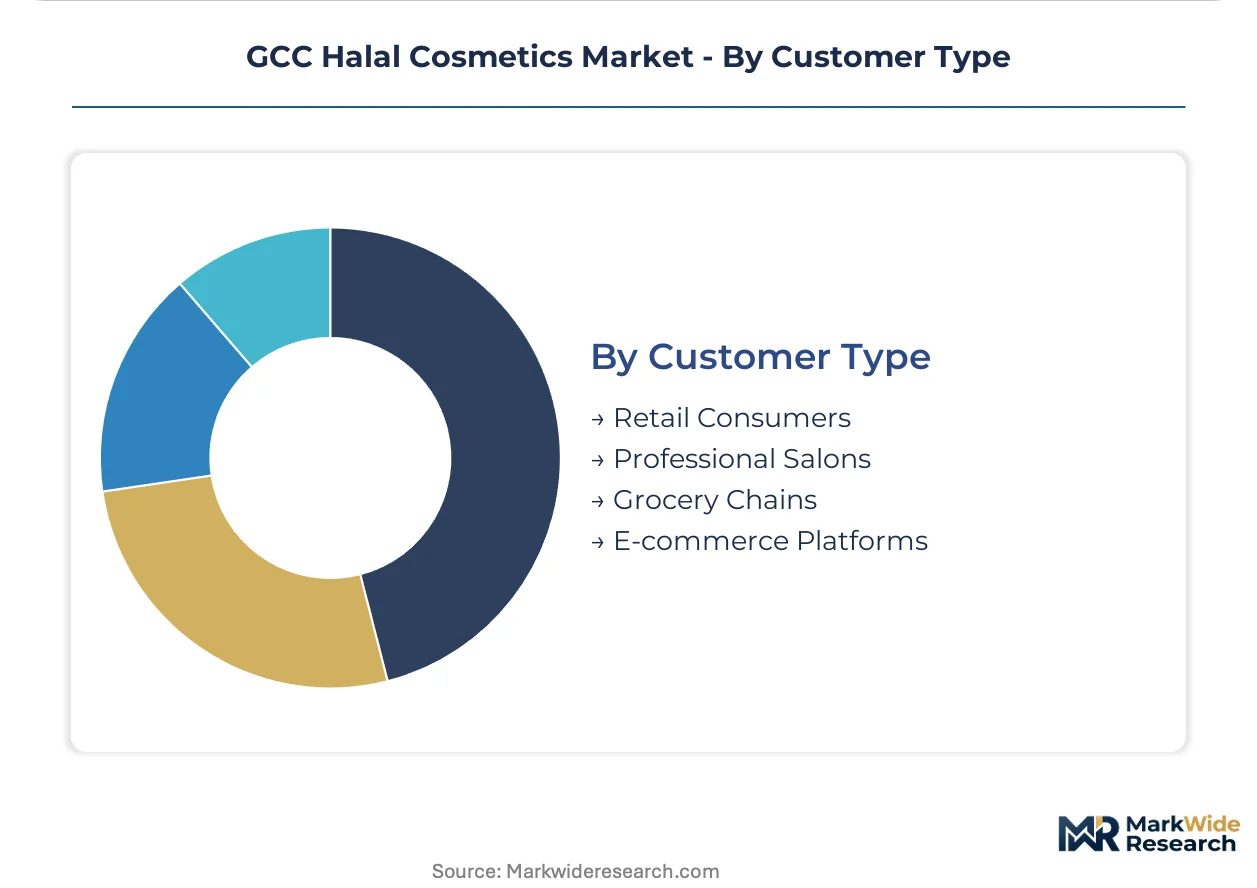
Customer Type:
Application maturity separates established professional channels from emerging platform intermediaries, with procurement sophistication dictating certification depth requirements.
- Retail Consumers:Individual purchasers prioritize verification accessibility and digital discovery tools. Saudi Arabia's young female demographic drives concentrated demand for Instagram-validated halal beauty routines.
- Professional Salons:Bulk procurement and treatment protocol integration require batch-level certification documentation. UAE salon chains mandate supplier halal compliance as a contractual condition.
- Grocery Chains:Category management constraints limit SKU depth for certified products.
- E-commerce Platforms:Marketplace verification infrastructure and seller onboarding standards create certification gatekeeping functions.
By volume, retail consumers lead. By procurement formalization, professional salons are advancing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters along the Gulf's western coastline where SASO and ESMA regulatory frameworks intersect. Saudi Arabia and the UAE absorb the majority of formulation investment as certification reciprocity agreements streamline cross-border distribution.
Saudi Arabia
Riyadh's young female demographic drives Instagram-validated halal skincare routines through social commerce channels. SASO harmonizes national halal cosmetics standards with GSO frameworks, reducing compliance friction for multi-state operators. Jeddah's Red Sea port infrastructure supports import substitution manufacturing for Oman and Bahrain markets.
United Arab Emirates
Dubai mall-based beauty retailers generate concentrated demand for exclusive halal brand launches across premium segments. ESMA mandates facility audits and supply chain documentation that compress product development timelines for entering manufacturers. Abu Dhabi's Khalifa Industrial Zone anchors dedicated production capacity serving pharmacy chain distribution networks.
Kuwait
Pharmacy channel expansion treats certified halal skincare as differentiated health-adjacent offerings rather than commodity beauty. The country's national standards body recognizes ESMA certification reciprocity, eliminating duplicate audit requirements for UAE-sourced products. Kuwait City's retail corridor concentrates specialty store presence for curated halal beauty assortments.
Qatar
Professional salon procurement mandates supplier halal compliance as contractual conditions across Doha's hospitality sector. The national health regulator aligns import requirements with Saudi and UAE frameworks to facilitate regional trade flows. Lusail's emerging commercial district attracts distribution investment targeting FIFA legacy tourism segments.
Oman
Minimal domestic halal cosmetics manufacturing creates import substitution opportunities for Saudi producers with excess certified capacity. Consumer skepticism about ingredient provenance drives interest in blockchain traceability integration for premium positioning. Muscat's port modernization supports direct shipping routes from Southeast Asian formulation centers.
GCC Halal Cosmetics Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in ingredient supply and certification services. The vendor base stratifies between full-range beauty houses and focused halal-native brands, with regulatory compliance capabilities serving as the primary segmentation mechanism. Three archetypes dominate: Southeast Asian formulators with jurisprudence-trained chemist pools, Gulf-based manufacturers leveraging proximity certification advantages, and European ethical beauty houses extending vegan-cruelty-free positioning into halal-adjacent segments. Competitive moves concentrate on M&A for certification capacity and strategic partnerships with pharmacy chains for shelf-space security.
Among regional specialists, Amara Halal Cosmetics and Clara International Beauty Group exemplify the formulation-expertise archetype, while Wardah Cosmetics anchors the pharmacy-distribution vector. These three occupy positions that bridge Southeast Asian technical capabilities with Gulf market access requirements, representing distinct pathways for scaling certified production without sacrificing Islamic jurisprudence rigor in ingredient verification protocols.
| Leading Market Players |
|---|
| Lush |
| PHB Ethical Beauty Ltd. |
| Amara Halal Cosmetics |
| The Halal Cosmetics Company |
| Sampure Minerals |
| Clara International Beauty Group |
| OnePure LLC |
| Wardah Cosmetics |
| Iba Cosmetics |
| Others |
Cost & Logistics Intelligence
Jeddah's Red Sea port manufacturing cluster concentrates certified halal cosmetics production capacity, feeding downstream pricing power to Saudi and UAE brands that control formulation IP and ESMA-compliant certification. This geographic concentration lets incumbent producers extract premium positioning while mid-market entrants absorb margin compression from scarce halal-certified ingredient inputs.
Pricing Analysis
ESMA and SASO certification mandates dictate the pricing tier structure across the GCC halal cosmetics landscape. Three-tier pricing separates premium multi-certification skincare from standard halal-only formulations and economy mass-market offerings, with vegan and organic stacking driving 25-40 point markups at each level. Pricing pressure stems from 40-60 point input cost premiums for alcohol-free preservatives and porcine-free emulsifiers, squeezing mid-market brands most severely while pharmacy-channel buyers show lowest price sensitivity due to health-adjacent positioning.
Supply Chain Analysis
Malaysian and Indonesian contract manufacturers hold concentrated technical formulation capacity for halal-compliant cosmetic chemistry, with UAE-based toll producers scaling rapidly to serve ESMA audit requirements. Raw material dependencies center on Southeast Asian palm-derived emulsifiers, Indian plant-based active ingredients, and European alcohol-free fragrance compounds. Single-source certification vulnerability creates launch delays when ESMA laboratory testing backlogs extend audit timelines. Distribution runs through Dubai's Khalifa Industrial Zone for pharmacy chain fulfillment and Riyadh's same-day delivery hubs for direct-to-consumer subscription models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC halal cosmetics sector sits at an inflection where blockchain traceability integration and AI-driven formulation platforms are compressing product development cycles while ESMA's accelerated audit schedules strain verification capacity.
For Market Incumbents: Entrench certification reciprocity advantages by deepening backward integration into captive halal ingredient sourcing from Southeast Asian suppliers, insulating margin structures from 40-60 point input cost volatility. Secure pharmacy chain shelf-space exclusivity through batch-level documentation protocols that emerging players cannot replicate, while investing in Riyadh and Jeddah same-day delivery infrastructure to capture subscription replenishment velocity. For New Entrants and Emerging Players: Oman's minimal domestic manufacturing base offers import substitution white space for Saudi producers with excess ESMA-certified capacity, particularly in premium skincare where blockchain traceability addresses Muscat consumer skepticism about ingredient provenance. Bahrain's underserved pharmacy channel presents parallel entry opportunity. Target professional salon procurement in Doha's hospitality sector with bulk certification documentation that incumbent beauty houses underinvest in. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because ESMA and SASO audit capacity constraints create durable moats around certified producers while digital verification infrastructure rewards scaled platform investment. Acquisition focus should center on Southeast Asian formulators with jurisprudence-trained chemist pools and established GSO compliance records. Monitor ESMA-SASO reciprocity expansion announcements as signal for competitive intensity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Capacity Acquisition | ESMA audit bottlenecks make certified manufacturing slots scarce and defensible. |
| Blockchain Traceability Integration | UAE pilot programs digitize halal verification for premium skincare positioning. |
| Pharmacy Channel Partnership | Saudi and UAE chains treat halal skincare as health-adjacent, not commodity beauty. |
| Men's Grooming Line Launch | Saudi male segment shows minimal halal penetration relative to female categories. |
| Oman-Bahrain Distribution Buildout | Import substitution opportunity for Saudi producers with excess certified capacity. |
Research Approach
Desk research of ESMA regulatory filings, SASO standardization notices, GSO framework documentation, and GCC customs trade data preceded structured interviews with halal certification body auditors, cosmetic formulation chemists, pharmacy chain category buyers, and professional salon procurement managers. Primary fieldwork across Riyadh, Dubai, and Jeddah validated secondary estimates of manufacturing capacity and channel shift velocity. Bottom-up SKU-level modeling triangulated against top-down macroeconomic projections for Gulf consumer spending.
Forecasts assume continued ESMA-SASO regulatory harmonization and stable Southeast Asian ingredient supply relationships across the projection horizon. Segmentation modeling incorporated product type complexity, certification tier stacking, distribution channel compliance burden, and customer procurement sophistication. CAGRs derived from trend extrapolation of social commerce penetration, pharmacy shelf-space allocation, and subscription replenishment adoption curves, cross-checked against historical elasticity of GCC premium beauty spending.
The forecast holds incumbent behavior within observed patterns; aggressive certification capacity expansion by Southeast Asian formulators or sudden ESMA audit timeline relaxation would shift competitive outcomes. Quarterly review of ESMA laboratory testing backlog durations, SASO digital registration system deployment milestones, and blockchain traceability platform adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Russia Lip Care Products Market
Cosmetics & Skincare
Anti-Fatigue Cosmetics Market
Cosmetics & Skincare
Qatar Cosmetic Products Market
Cosmetics & Skincare
Chile Cosmetics Products Market
Cosmetics & Skincare
Natural Cosmetic Color Market
Cosmetics & Skincare
Foundation Cream Market
Cosmetics & Skincare
Eye Shadow Stick Market
Cosmetics & Skincare
Global Cosmetic Applicator Foam Market
Cosmetics & Skincare
Microbiome Cosmetic Products Market
Cosmetics & Skincare
Mascara Applicators Market
Cosmetics & Skincare
Moisturizing Spray Market
Cosmetics & Skincare
E Commerce Cosmetic and Fragrance Market
Cosmetics & Skincare
K-Beauty Products Market
Cosmetics & Skincare
Cosmetics OEM and ODM Services Market
Cosmetics & Skincare
Organic Soaps Market
Cosmetics & Skincare
Europe Bath Soap Market