
 Yoga Clothing Market | 2026-2036
Yoga Clothing Market Size, Share, and Industry Trends Forecast 2026-2036
Yoga Clothing Market Intelligence
The EU's Corporate Sustainability Reporting Directive (CSRD) is hardening the requirement for transparent material sourcing and lifecycle reporting in apparel. Lululemon leverages its strong brand identity and extensive direct-to-consumer channels to command premium pricing. Alo Yoga differentiates through its distinct studio-to-street aesthetic, targeting both fitness and lifestyle segments. Meanwhile, Vuori positions its versatile performance apparel for a broader active lifestyle well beyond just yoga.
Yoga clothing encompasses performance apparel specifically engineered for flexibility, comfort, and moisture management during physical practice. Key garments incorporate four-way stretch fabrics with high elastane content and flatlock seams to minimize chafing and maximize range of motion. Leggings remain the dominant product type, while fabric technologies featuring moisture-wicking and anti-odor properties command higher margins. Online retailers are the fastest-growing sales channel, displacing volume from traditional department stores.
Compliance with textile labeling rules from the US Federal Trade Commission (FTC) is a baseline requirement for market entry. The EU's REACH regulation governs chemical use in fabrics, while China's GB standards dictate performance and safety criteria for apparel sold domestically. Brand survival now depends on navigating the complex trade-offs between sustainable material innovation and maintaining accessible price points for a diverse consumer base.
Market Dynamics
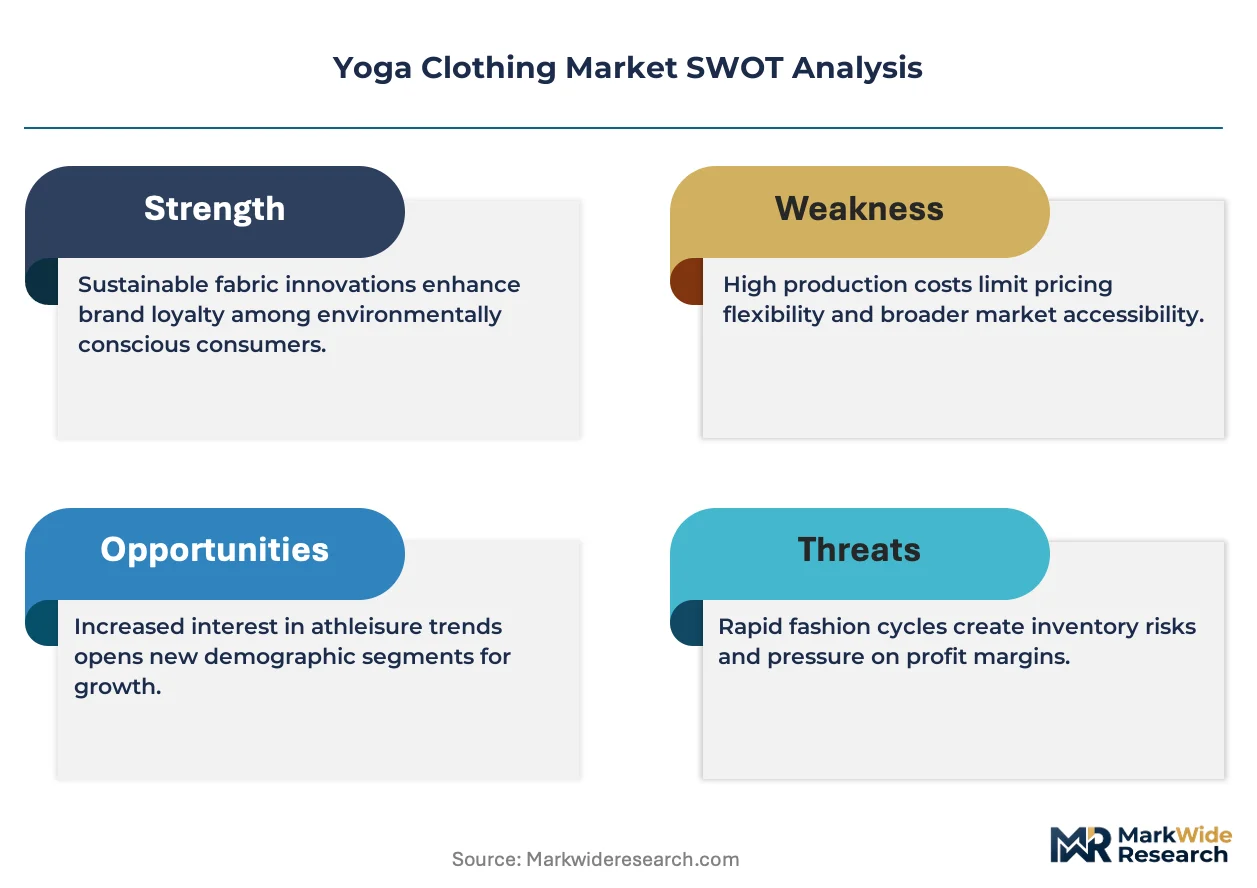
The yoga clothing market's primary dynamic is the structural tension between escalating regulatory demands for material transparency and the consumer expectation of accessible pricing. Sustainability mandates, exemplified by the EU's Corporate Sustainability Reporting Directive, are forcing a shift towards traceable, eco-conscious materials.
Growth Catalysts
- Wellness Tourism:Demand from participants at wellness retreats in destinations like Australia and Canada creates a concentrated customer base seeking high-performance, premium apparel for immersive experiences.
- Material Innovation:The development and commercialization of recycled polyester and bio-based nylons provide a tangible sustainability narrative that appeals to environmentally conscious consumers and supports premium pricing.
- Digital Fitness Platforms:The proliferation of online yoga classes and fitness apps expands the addressable market beyond physical studios, exposing a wider audience to the need for specialized apparel.
Market Restraints
- Input Cost Volatility:Price fluctuations for recycled polyethylene terephthalate (rPET) flake, a key raw material for recycled polyester, create margin pressure and complicate long-term financial planning for apparel manufacturers.
- Substitution from Athleisure:General-purpose athletic wear, while not optimized for yoga, presents a significant substitution threat, capturing a large segment of casual users unwilling to pay a premium for specialized garments.
- Complex Regulatory Compliance:Navigating the patchwork of international standards, including the EU's REACH chemical regulations and China's GB standards for textiles, increases administrative overhead and time-to-market.
Strategic Opportunities
- Adaptive and Inclusive Sizing:There is a significant market opportunity in developing and marketing extended size ranges and adaptive clothing designs for practitioners with diverse body types and physical abilities.
- Circular Business Models:Implementing take-back programs, repair services, and resale platforms offers a new revenue stream while strengthening brand loyalty and meeting consumer demand for circularity.
- Men's Yoga Apparel Segment:The men's category remains comparatively underdeveloped, presenting a white-space opportunity for brands to create targeted product lines and marketing campaigns that resonate with male practitioners.
Industry Challenges
- Greenwashing Scrutiny:Brands face the challenge of substantiating sustainability claims with credible, third-party certifications to avoid consumer backlash and regulatory penalties for misleading environmental marketing.
- Supply Chain Traceability:Establishing end-to-end visibility from raw fiber to finished garment is an operationally complex and costly challenge, yet it is becoming a prerequisite for regulatory compliance and brand authenticity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yoga Clothing Market |
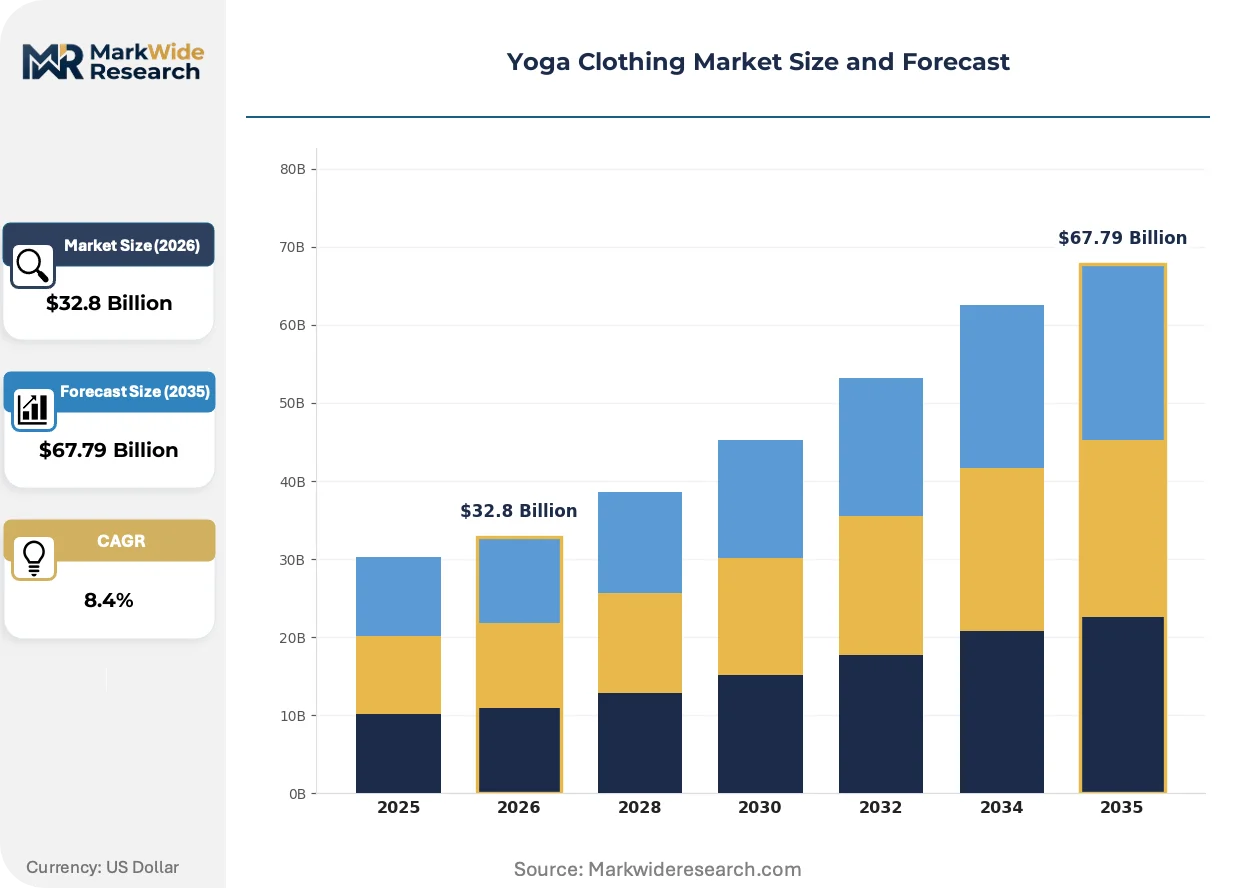
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $67.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leggings, Tops, Jackets, Shorts, Sports Bras, Sweatpants Fabric Technology: Moisture-Wicking, Breathable Mesh, Compression, Anti-Odor, UV Protection, Thermal Insulation End User: Professional Instructors, Fitness Enthusiasts, Gym Members, Wellness Retreat Participants Sales Channel: Specialty Stores, Online Retailers, Department Stores, Fitness Centers, Boutique Shops |
| Companies Covered | Vuori, Athleta, Lululemon, Outdoor Voices, Under Armour, Alo Yoga, Gymshark, Girlfriend Collective, Nike, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yoga Clothing Market Strategic Shifts & Innovations
The convergence of material science and digital technology is fundamentally altering product capabilities and consumer engagement within the yoga apparel market. This evolution pushes garments beyond passive attire into active components of a connected wellness ecosystem, driven by data and personalization.
Smart textiles incorporating biometric sensors represent a significant product evolution. These fabrics can monitor metrics like muscle engagement or body temperature, providing real-time feedback during a yoga session. While adoption is currently concentrated among dedicated practitioners and in the premium market segment, the integration of data into the practice itself is electrifying the link between apparel and performance outcomes.
Regulatory frameworks are increasingly focused on the entire lifecycle of apparel. The EU's Corporate Sustainability Reporting Directive (CSRD) compels companies to provide detailed disclosures on their supply chains and environmental impact. This is forcing brands selling into the European Union to invest heavily in traceability systems and transparent sourcing partnerships to meet public reporting requirements and avoid non-compliance penalties.
A distinct shift in purchasing behavior sees consumers moving away from seasonal collections toward a more fluid, 'buy-now' model influenced by social media. This trend disrupts the traditional wholesale-to-retail calendar, favoring agile direct-to-consumer brands that can respond quickly to micro-trends. This dynamic is most visible in North American and European markets where social commerce is deeply integrated into consumer shopping habits.
Yoga Clothing Market Segmentation
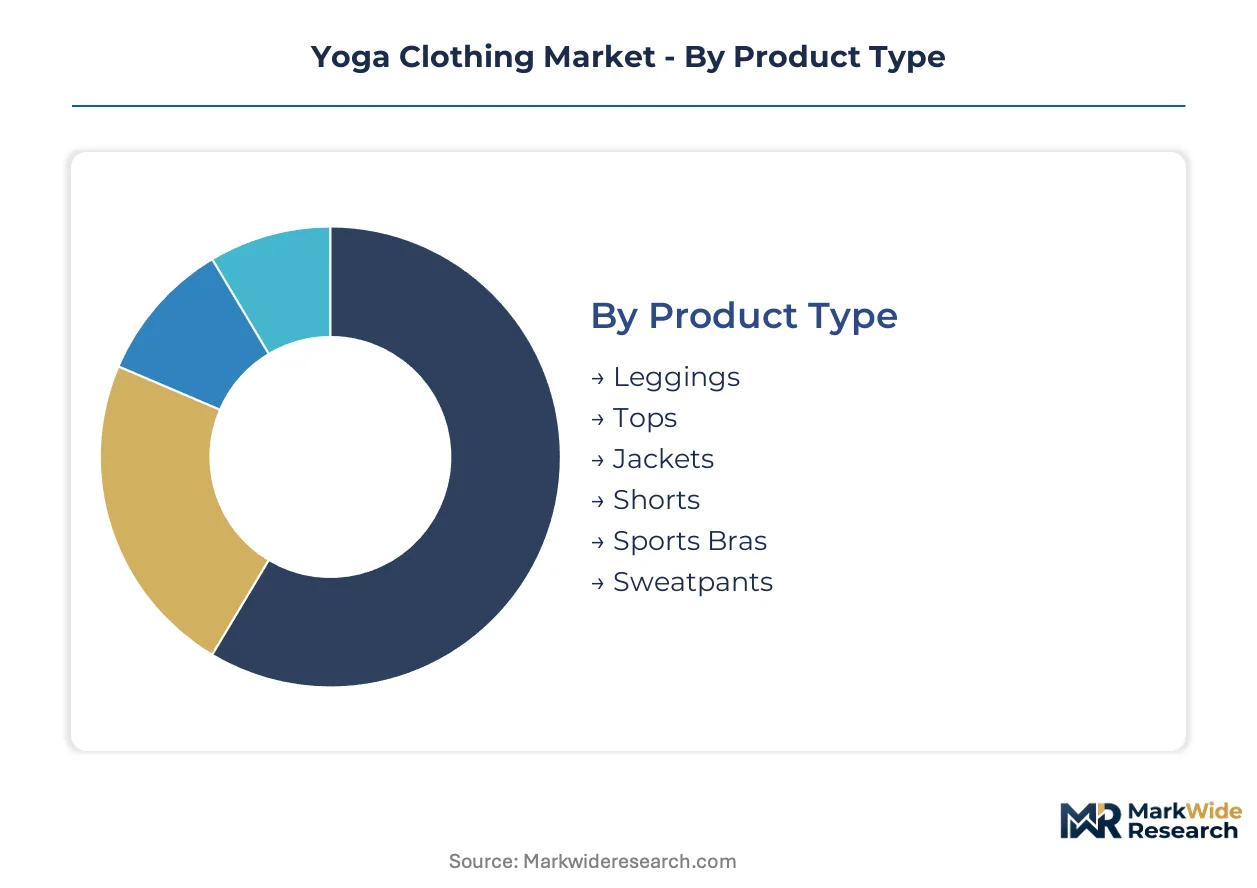
Segmentation analysis for the yoga clothing market reveals distinct product characteristics and consumer behaviors influencing purchasing decisions. Understanding these segments enables brands to tailor product development, marketing strategies, and distribution efforts effectively. This granular view highlights areas of concentration and emerging opportunities within the industry.
Product Type:
The product type segmentation for yoga clothing reflects a spectrum from highly standardized core garments to specialized items catering to specific practice needs.
- Leggings:These garments are the market's dominant product, engineered with four-way stretch fabrics and high elastane content for maximum flexibility and comfort. Demand for leggings concentrates globally, driven by their versatility for both yoga practice and broader athleisure wear.
- Sports Bras:Essential for support during physical activity, sports bras incorporate specialized construction and moisture-wicking materials to manage impact and maintain comfort. Premium sports bras command higher price points due to their technical design and performance features, particularly in markets like the United States and Europe.
- Tops:This category includes various styles such as tanks, tees, and long-sleeved shirts, often featuring breathable and moisture-wicking properties for comfort during practice.
- Jackets:Designed for layering, yoga jackets provide warmth and protection for outdoor sessions or during cool-downs, often using lightweight, flexible materials.
- Shorts:Preferred in warmer climates or for specific yoga styles, shorts offer increased freedom of movement and ventilation during intense physical activity.
- Sweatpants:Primarily worn for comfort before and after practice, or for restorative yoga, sweatpants prioritize softness and relaxed fits over technical performance.
Most installed capacity flows through Leggings. Expansion is steepest in Sports Bras.
Fabric Technology:
Fabric technology differentiation often dictates cost tiers, influencing both material sourcing and final product pricing.
- Moisture-Wicking:This technology draws sweat away from the body to the fabric's surface, facilitating rapid evaporation and keeping the wearer dry. Garments featuring advanced moisture-wicking command higher margins and are essential for performance apparel across all geographies.
- Anti-Odor:Incorporating antimicrobial treatments or natural fibers, anti-odor technology inhibits bacterial growth to prevent unpleasant smells, enhancing garment longevity and hygiene. This feature is particularly valued by consumers in densely populated urban markets and among frequent practitioners.
- Breathable Mesh:Strategically placed mesh panels enhance airflow and ventilation, preventing overheating during rigorous yoga sessions.
- Compression:Compression fabrics provide gentle pressure to muscles, supporting circulation and potentially aiding in recovery after strenuous activity.
- UV Protection:Fabrics treated with UV-blocking agents offer protection from harmful sun rays, critical for outdoor yoga practices in sunny regions like Australia and California.
- Thermal Insulation:Designed for cooler environments, thermal insulation fabrics retain body heat, ensuring comfort during outdoor or cold-weather yoga.
Consumer demand for enhanced comfort and hygiene concentrates within Moisture-Wicking and Anti-Odor technologies.
End User:
End-user segmentation highlights distinct purchasing motivations, ranging from professional requirements to casual lifestyle integration.
- Wellness Retreat Participants:This segment comprises individuals attending immersive wellness experiences, often seeking high-performance, premium apparel specifically for their intensive practice. Demand is particularly concentrated in destinations like Australia and Canada, where wellness tourism is robust.
- Fitness Enthusiasts:This broad category includes individuals who regularly engage in various fitness activities, including yoga, and prioritize versatile, comfortable, and durable activewear. Fitness enthusiasts represent a significant volume driver across all major markets.
- Professional Instructors:Instructors require durable, comfortable, and often branded apparel that withstands frequent washing and extended wear during teaching sessions.
- Gym Members:This segment includes individuals who practice yoga as part of a broader fitness routine within a gym setting, often opting for general athletic wear that can double as yoga attire.
The expanding wellness tourism sector drives demand among Wellness Retreat Participants, while Fitness Enthusiasts represent the largest volume segment.
Sales Channel:
Sales channel analysis reveals evolving distribution patterns, with volume shifting towards digitally-native platforms.
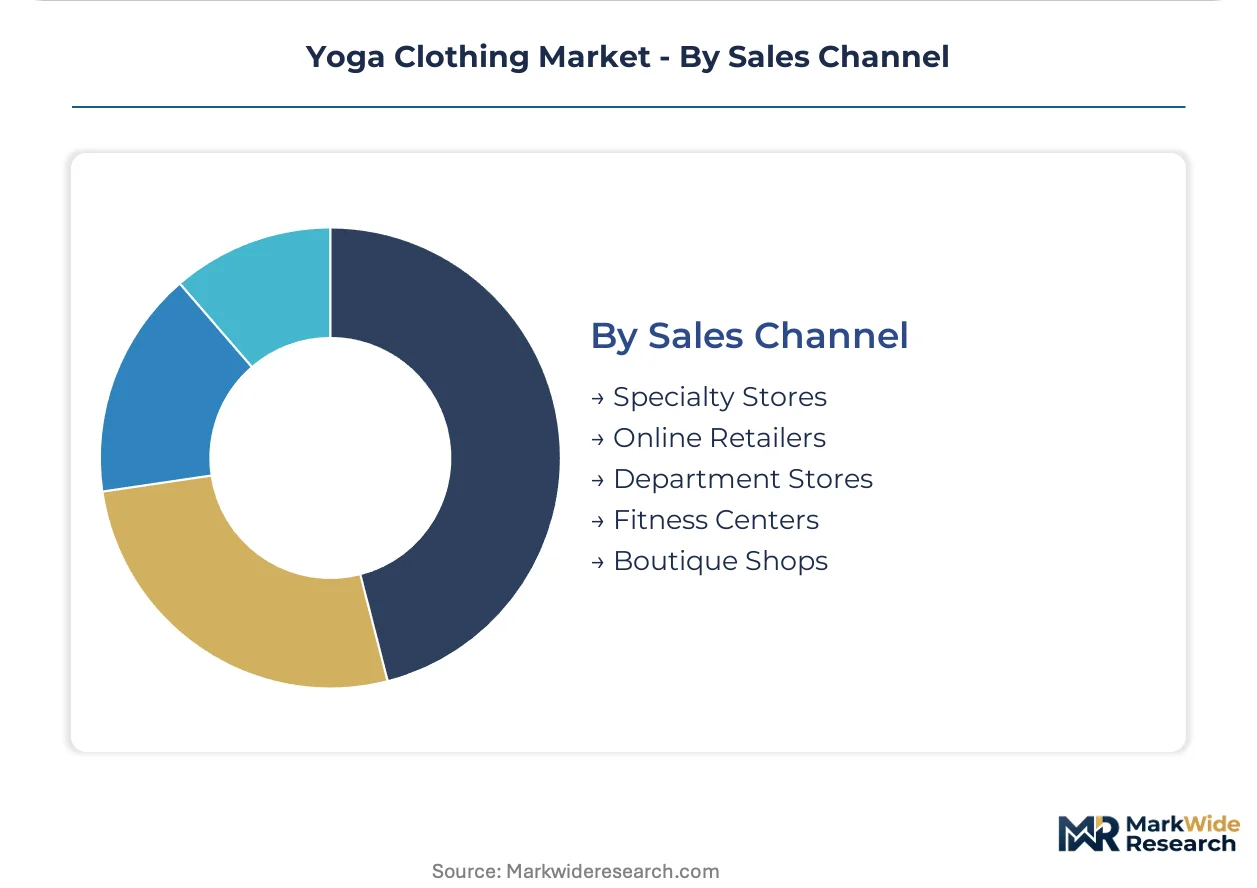
- Online Retailers:This channel includes brand-specific websites, multi-brand e-commerce platforms, and social commerce, representing the fastest-growing sales channel. Online retailers offer convenience, broader product selection, and competitive pricing, displacing volume from traditional department stores globally.
- Specialty Stores:These dedicated retail spaces offer a curated selection of yoga clothing, often providing personalized fitting services and a strong brand experience. Specialty stores maintain robust customer loyalty for premium brands in markets like the United States and Western Europe.
- Department Stores:Traditional retail outlets that carry yoga clothing as part of their broader activewear or sportswear sections, department stores face declining foot traffic and market share.
- Fitness Centers:Many yoga studios and fitness centers sell apparel directly to their members, offering convenience and promoting specific brands or their own branded merchandise.
- Boutique Shops:Smaller, independent retailers that often focus on niche, ethically sourced, or artisan-crafted yoga apparel, catering to a specific consumer aesthetic.
Online Retailers are rapidly gaining market share, while Specialty Stores maintain a strong position for premium brand engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Talent concentrations in design and manufacturing anchor key regions for yoga clothing. This market sees significant purchasing activity driven by wellness trends and active lifestyles. Regulatory frameworks also shape production and market entry across diverse geographies.
United States
Consumer demand for performance apparel drives the United States market, particularly among fitness enthusiasts. The US Federal Trade Commission (FTC) enforces textile labeling rules, ensuring product transparency for consumers. California's active lifestyle culture supports a concentration of innovative yoga wear brands and retail outlets.
Canada
Wellness retreat participants and a strong outdoor culture fuel demand in Canada for specialized yoga apparel. Health Canada oversees product safety standards for textiles, impacting market entry for new brands. Vancouver serves as a hub for premium activewear design and distribution, catering to discerning consumers.
Australia
Robust wellness tourism and a strong emphasis on outdoor activities generate substantial demand for UV-protective yoga clothing in Australia. The Australian Competition and Consumer Commission (ACCC) monitors product claims, ensuring accuracy in marketing. Sydney's coastal lifestyle fosters a vibrant market for sustainable and high-performance activewear brands.
Germany
Growing interest in holistic wellness practices drives demand for comfortable and sustainable yoga wear across Germany. The EU's REACH regulation rigorously controls chemical substances in textile manufacturing, impacting material sourcing. Munich's strong fitness community supports a concentration of specialized yoga studios and apparel boutiques.
China
Expanding fitness participation among urban populations boosts demand for versatile yoga apparel in China. China's GB standards dictate performance and safety criteria for all apparel sold domestically. Shanghai's fashion industry serves as a manufacturing and innovation hub for activewear brands targeting the domestic and export markets.
Yoga Clothing Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the yoga clothing market. This landscape exhibits a tiered structure, with established athletic brands alongside specialized yoga apparel companies. Strategic archetypes include performance-focused innovators and lifestyle-driven brands. Companies pursue geographic expansion and portfolio diversification to capture market share.
Within the specialized yoga apparel segment, Lululemon exemplifies a brand leveraging direct-to-consumer channels and a strong identity to command premium pricing. This Canadian-based company has cultivated a loyal customer base through its focus on quality and community engagement. Vuori occupies a distinct position as a provider of versatile performance apparel, targeting a broader active lifestyle segment beyond just yoga. This approach allows Vuori to appeal to consumers seeking comfort and style across various activities. Alo Yoga represents another key player, differentiating itself through a distinct studio-to-street aesthetic. The brand appeals to both fitness and lifestyle consumers, often through extensive social media presence and celebrity endorsements.
| Leading Market Players |
|---|
| Vuori |
| Athleta |
| Lululemon |
| Outdoor Voices |
| Under Armour |
| Alo Yoga |
| Gymshark |
| Girlfriend Collective |
| Nike |
| Others |
Cost & Logistics Intelligence
Skilled textile manufacturing workforces in Asian production hubs influence pricing tiers, connecting labor-cost differentials directly to accessible and premium apparel segments.
Pricing Analysis
Value-based pricing stratifies the yoga clothing market, reflecting brand identity and material innovation. Price differentiation stems from specialized fabric technologies like moisture-wicking and anti-odor properties, alongside brand reputation. Pricing pressure stems from input cost volatility for recycled polyethylene terephthalate (rPET) flake. Fitness Enthusiasts exhibit higher price sensitivity compared to Wellness Retreat Participants, who prioritize premium performance.
Supply Chain Analysis
Compliance with textile labeling rules from the US Federal Trade Commission (FTC) and the EU's REACH regulation gates market entry for apparel manufacturers. The supply chain concentrates manufacturing in countries like China, Vietnam, and Bangladesh, drawing heavily from recycled polyester and bio-based nylons. Complex regulatory compliance across international standards represents a significant structural risk. Distribution runs through a rapidly expanding network of online retailers, displacing traditional department store volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The yoga clothing market exhibits characteristics of a late-cycle quality story, driven by a pronounced demand shift towards premium, sustainably sourced materials and enhanced performance specifications.
For Market Incumbents: Cement brand loyalty through transparent material sourcing and credible third-party certifications. Incumbents must invest in end-to-end supply chain traceability to meet escalating regulatory demands like the EU's CSRD, mitigating greenwashing scrutiny. Diversifying material inputs beyond rPET flake can alleviate input cost volatility. Leverage extensive direct-to-consumer channels to maintain premium pricing against athleisure substitution threats.
For New Entrants and Emerging Players: Practitioners with diverse body types represent a significant underserved buyer archetype. Developing and marketing adaptive and inclusive sizing ranges offers a white-space opportunity. The men's yoga apparel segment remains comparatively underdeveloped, presenting another clear target for specialized product lines. Agile direct-to-consumer models, amplified by social commerce, provide an effective go-to-market angle for rapid penetration.
For Investors and Strategic Acquirers: Established athletic apparel conglomerates are the most active acquirers in this space, seeking portfolio diversification. The market offers long-term viability, driven by sustained wellness trends and digital fitness platform expansion. Acquisition targets include brands with strong direct-to-consumer channels, distinct studio-to-street aesthetics, or advanced material innovation capabilities. The commercialization success of bio-based nylons and other sustainable textiles serves as a critical inflection indicator to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Implement Circular Business Models | Strengthens brand loyalty and generates new revenue streams through take-back and resale platforms. |
| Expand Adaptive and Inclusive Sizing | Captures significant market share from underserved practitioners with diverse body types. |
| Integrate Biometric Sensor Technology | Elevates apparel from passive attire to active components in a connected wellness ecosystem. |
| Accelerate Sustainable Material R&D | Meets escalating regulatory demands and consumer preference for eco-conscious recycled polyester fabrics. |
| Optimize Direct-to-Consumer Channels | Responds agilely to micro-trends and displaces volume from traditional department stores. |
Research Approach
Multiple input streams — primary interviews, secondary validation, and proprietary databases — were reconciled to construct a robust market view. Conversations with brand managers, material scientists, retail buyers, and professional yoga instructors provided crucial primary insights. Secondary data sources included regulatory filings with the US FTC and EU REACH, industry reports, and company disclosures. Bottom-up data aggregation and top-down market sizing ensured comprehensive triangulation.
Historical data trends were cross-referenced against expert panel input to project market trajectories over the projection horizon. Segmentation dimensions modeled included Product Type, Fabric Technology, End User, Sales Channel, and regional purchasing concentration. Compound annual growth rates were derived from a synthesis of historical performance and anticipated market dynamics. Key forecast inputs included raw material pricing for rPET flake and digital fitness platform adoption rates.
Underlying measurement precision varies by segment; Leggings and Online Retailers carry tighter precision than specialized Jackets or Boutique Shops. Forecasts reflect assumptions regarding evolving consumer preferences and regulatory compliance. A model refresh is warranted upon material change in sustainable material commercialization or international trade policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Mister Cap Market
Apparel & Footwear
Plus Size Women's Clothing Market
Apparel & Footwear
Fast Fashion Market
Apparel & Footwear
Women Apparel Market
Apparel & Footwear
Sports Inspired Clothing Market
Apparel & Footwear
Adaptive Shapewear Market
Apparel & Footwear
Lingerie Market
Apparel & Footwear
Denim Jeans Market
Apparel & Footwear
Men Shirts Market
Apparel & Footwear
New Smart Wardrobe Market
Apparel & Footwear
Sleepwear Market
Apparel & Footwear
Golf Outfit Market
Apparel & Footwear
Maternity Apparels Market
Apparel & Footwear
Men Jeans Market
Apparel & Footwear
Heated Jacket Market
Apparel & Footwear
Gym Apparel Market