
 United Kingdom Public Relation Services Market | 2026-2036
United Kingdom Public Relation Services Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Public Relation Services Market Insights
Strategic counsel revenue is fragmenting across project-based digital engagements and long-term retainer relationships. Edelman leverages its integrated global network to anchor complex corporate reputation mandates for FTSE-listed clients. WPP sustains scale advantages through cross-agency media buying synergies that smaller competitors cannot replicate. Berkeley Communications Group specializes in technology sector storytelling, occupying a differentiated position among mid-sized London agencies.
Public relation services encompass strategic communication management that shapes organizational reputation through earned media placement, stakeholder engagement, and narrative architecture delivered across traditional and digital channels. The discipline employs message testing protocols, sentiment analytics, and multi-channel distribution frameworks to influence public perception and behavior. Crisis Management commands premium pricing due to compressed response timelines and specialized legal-communications coordination requirements. Digital PR represents the fastest-expanding service category as search-engine visibility and influencer network activation displace conventional press release distribution. The Agency delivery model retains dominant share, though Hybrid structures are gaining traction as corporates blend captive strategy teams with external creative execution.
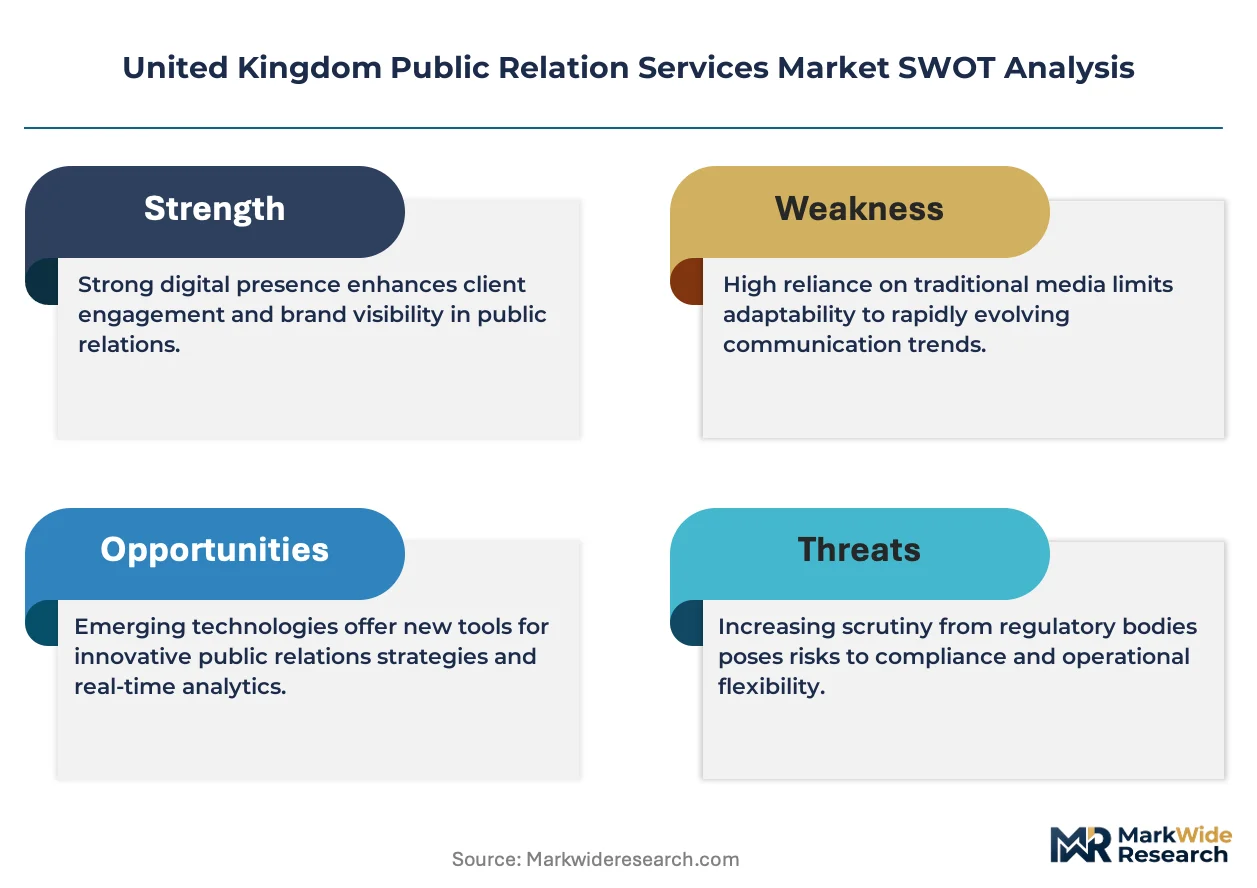
The Advertising Standards Authority enforces truth-in-advertising standards that extend to influencer disclosure and native content labeling, directly shaping campaign design workflows. Ofcom's evolving online safety duties impose content moderation obligations on platforms and their PR partners, creating compliance-driven demand for risk assessment services. The UK Information Commissioner's Office GDPR enforcement actions raise the stakes for data-driven audience targeting in earned media strategies. Stakeholders must decide whether to build in-house regulatory monitoring capabilities or deepen reliance on agency compliance infrastructure as rulemaking accelerates across digital communication channels.
Market Dynamics
The UK Online Safety Bill and evolving ASA guidelines are compressing campaign timelines and forcing agencies to embed compliance infrastructure directly into creative workflows, fundamentally restructuring how retainer contracts allocate risk and resource.
Growth Catalysts
- Digital PR service expansion:Search-engine visibility and influencer network activation are displacing conventional press release distribution, driving retainer contract growth among technology sector buyers.
- GDPR enforcement intensification:The UK Information Commissioner's Office actions raise stakes for data-driven audience targeting, creating compliance-driven demand for risk assessment services.
- London-Manchester corridor concentration:Corporate communications clusters in London and Manchester's growing digital PR hub concentrate specialized talent and client proximity advantages.
Market Restraints
- Regulatory friction from Ofcom duties:Evolving online safety obligations impose content moderation costs on platforms and their PR partners, compressing margins on high-volume campaigns.
- Talent concentration risk:Specialist crisis management and legal-communications coordination skills concentrate in London, creating geographic supply bottlenecks for regional clients.
- Input cost volatility in sentiment analytics:Third-party data licensing for message testing protocols faces pricing pressure from platform API restrictions and data scarcity.
Strategic Opportunities
- Underpenetrated Manchester digital hub:Manchester's growing technology sector presence offers expansion terrain for mid-sized agencies seeking distance from London saturation.
- Regulatory tailwind from ASA influencer rules:Truth-in-advertising enforcement extending to native content labeling creates recurring compliance advisory revenue streams.
- AI-enabled narrative architecture:Convergence of generative language models and multi-channel distribution frameworks enables automated personalization at scale for FTSE-listed clients.
Industry Challenges
- Skills gap in legal-communications coordination:Crisis management mandates require compressed-response specialists with simultaneous regulatory and media expertise, creating recruitment friction.
- Hybrid model integration complexity:Corporates blending captive strategy teams with external creative execution face workflow fragmentation and IP ownership disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Public Relation Services Market |
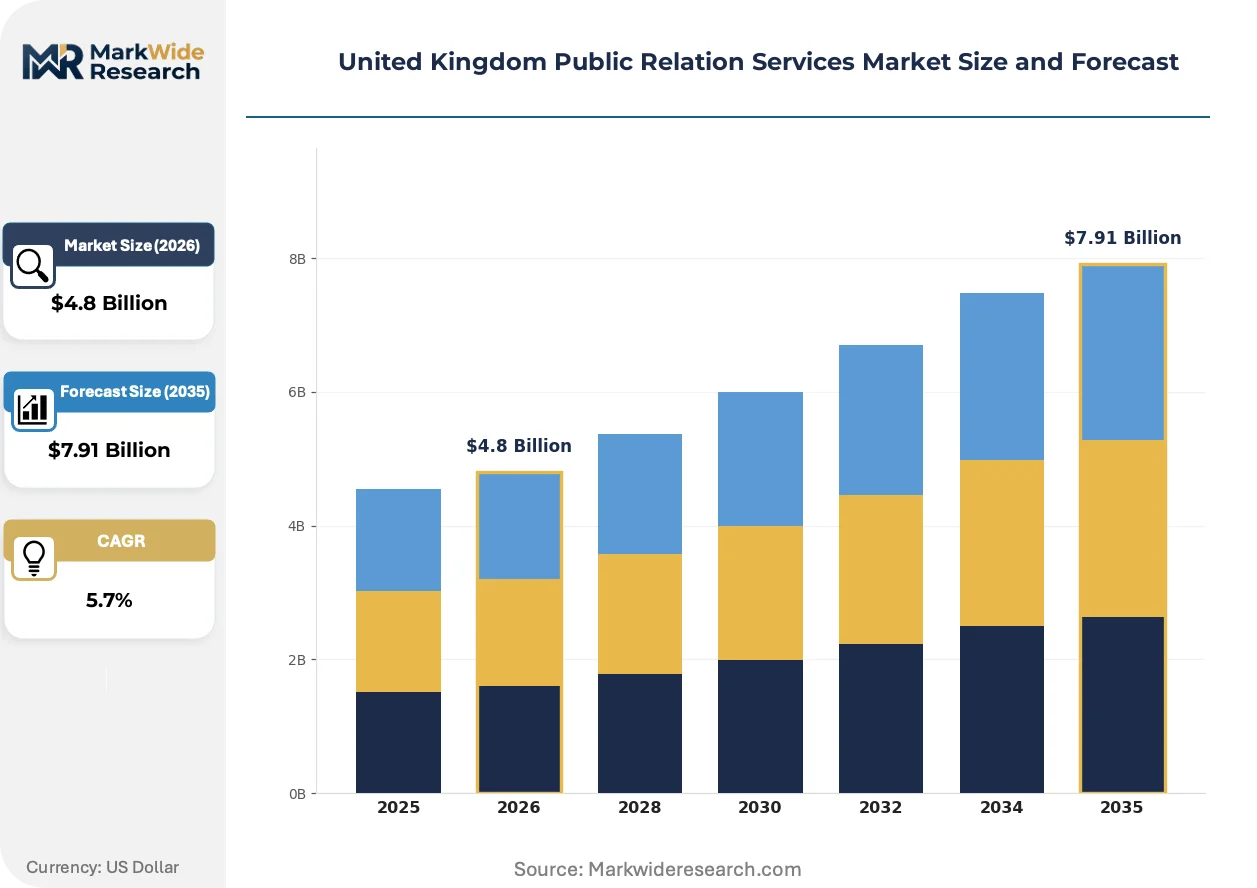
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Media Relations, Crisis Management, Digital PR, Event Management Client Type: Corporates, Non-Profits, Government Agencies, Startups Delivery Model: In-House, Agency, Freelance, Hybrid Engagement Type: Retainer, Project-based, Consultancy, Advisory |
| Companies Covered | Edelman, BCW, Weber Shandwick, Hill+Knowlton Strategies, WPP, Omnicom Group, Berkeley Communications Group, MHP Communications, PRLab, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Public Relation Services Market Trends and Innovations
Artificial intelligence tools are restructuring how UK agencies construct narratives, test messages, and distribute content across earned and owned channels, compressing traditional creative cycles while raising new compliance stakes.
Generative language models are virtualizing the narrative architecture function that previously required senior strategist hours. Technology sector buyers are adopting these tools fastest, embedding AI-assisted drafting into retainer workflows within six-month procurement cycles. This virtualization is compressing headcount ratios on mid-tier accounts while elevating premium pricing for human-led strategic counsel on complex corporate reputation mandates.
The Advertising Standards Authority's expanded influencer disclosure requirements are reshaping campaign design workflows across native content and paid partnership categories. Enforcement actions now extend to platform algorithms and agency creative briefs, raising liability exposure. Technology and consumer goods verticals are responding by building dedicated compliance review stages before any content activation.
Retainer structures are fragmenting into modular components as corporates unbundle strategy from execution. Buyers are segmenting engagements into discrete project-based digital activations and long-term advisory relationships, with procurement teams demanding clearer outcome attribution. This unbundling is most visible among FTSE-listed clients with mature in-house communications functions seeking external creative capacity without strategic dependency.
United Kingdom Public Relation Services Market Segmentation
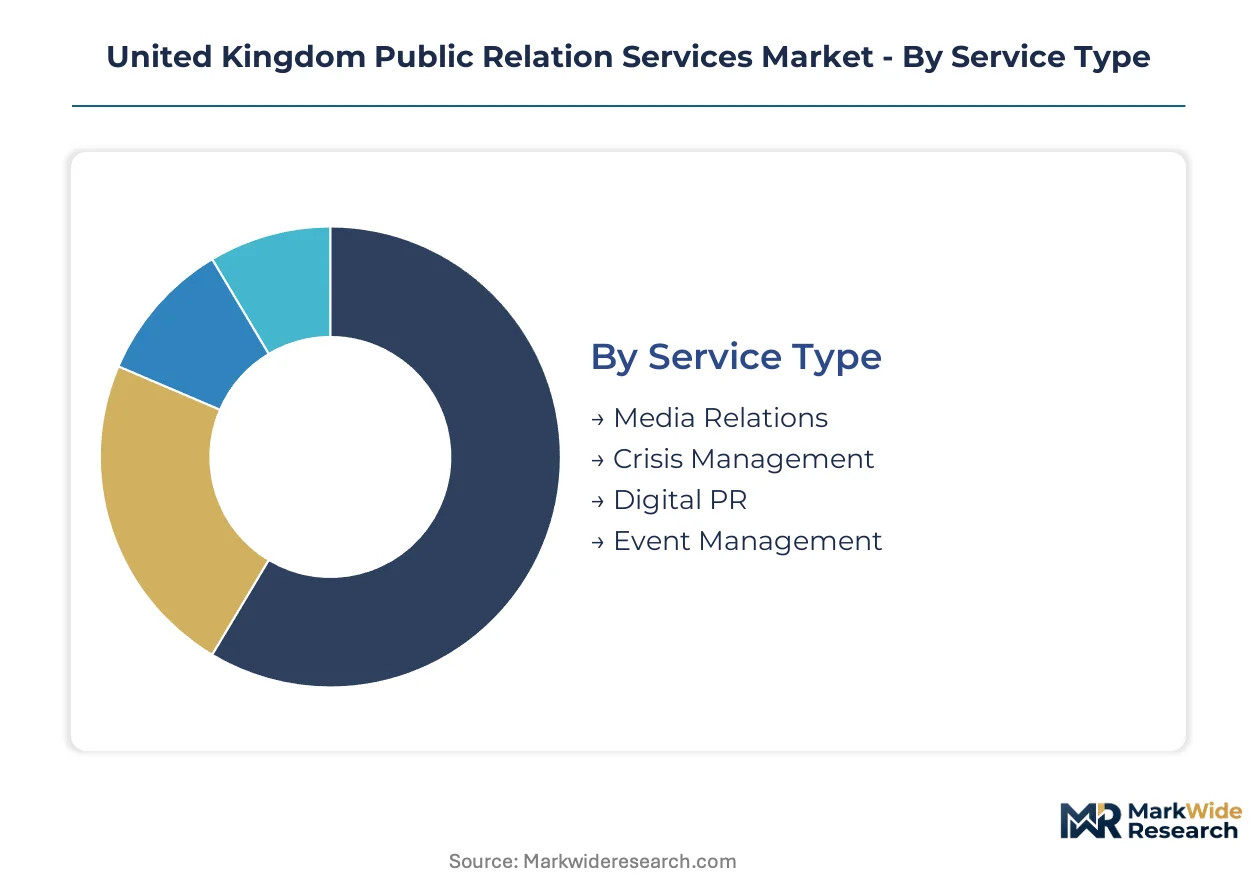
Segmentation reveals how UK PR services fragment across service specializations, client sophistication levels, and contractual structures. Each dimension shapes pricing power, talent requirements, and regulatory exposure differently.
Service Type:
After-sales intensity varies sharply across service lines, with ongoing reputation monitoring and rapid-response standby obligations defining contractual premiums.
- Media Relations:Traditional journalist outreach and press placement services anchor established agency revenue streams. London-based FTSE-listed corporates sustain demand for broadcast and national newspaper access, though digital displacement compresses volume-based pricing.
- Crisis Management:Compressed-timeline response protocols and legal-communications coordination command premium retainers. Regulatory enforcement actions from the Advertising Standards Authority and Ofcom duties intensify demand for specialist standby arrangements among technology and financial services clients.
- Digital PR:Search-engine visibility optimization and influencer network activation displace conventional distribution. Manchester's technology sector cluster drives fastest adoption of SEO-integrated storytelling and native content placement.
- Event Management:Physical and virtual stakeholder convening requires logistics-creative hybrid capabilities. Corporate hospitality budgets face procurement scrutiny, pushing volume toward project-based rather than retainer structures.
Crisis Management holds the largest share; momentum sits with Digital PR.
Client Type:
Cost-tier stratification separates enterprise-grade advisory from high-volume, standardized execution mandates.
- Corporates:FTSE-listed and large private companies sustain the deepest retainer relationships. Complex stakeholder matrices and regulatory disclosure obligations in London's financial district demand integrated strategic counsel across multiple jurisdictions.
- Government Agencies:Public sector procurement frameworks prioritize compliance and audit trails over creative risk-taking. Central and local government contracts concentrate in approved supplier frameworks with extended payment terms.
- Non-Profits:Charitable foundations and advocacy organizations balance mission-driven messaging with donor accountability requirements. Pro bono and discounted rate structures are common, with agencies trading margin for portfolio diversity.
- Startups:Venture-backed technology firms in Manchester and London's Shoreditch cluster favor project-based digital activations. Rapid scaling timelines favor modular, outcome-attributed engagements over strategic dependency.
Corporates dominate contract value; startups are expanding most quickly.
Delivery Model:
Volume concentration varies by model, with captive in-house functions and external agencies occupying opposite ends of the headcount spectrum.
- Agency:External specialist firms retain dominant market share through scale economies and cross-client learning. London's corporate communications cluster and Manchester's digital hub concentrate differentiated capabilities.
- Hybrid:Blended captive strategy teams with external creative execution are gaining traction. Procurement teams demand clearer IP ownership boundaries and workflow integration protocols.
- In-House:Corporates with mature communications functions internalize strategic counsel while outsourcing execution. FTSE-listed companies in regulated sectors maintain the largest captive teams for regulatory disclosure control.
- Freelance:Independent practitioners serve project overflow and specialized niches. Gig-economy platforms and direct relationships sustain a fragmented supply layer below agency scale thresholds.
Agency delivery holds the largest share; Hybrid structures are climbing the fastest.
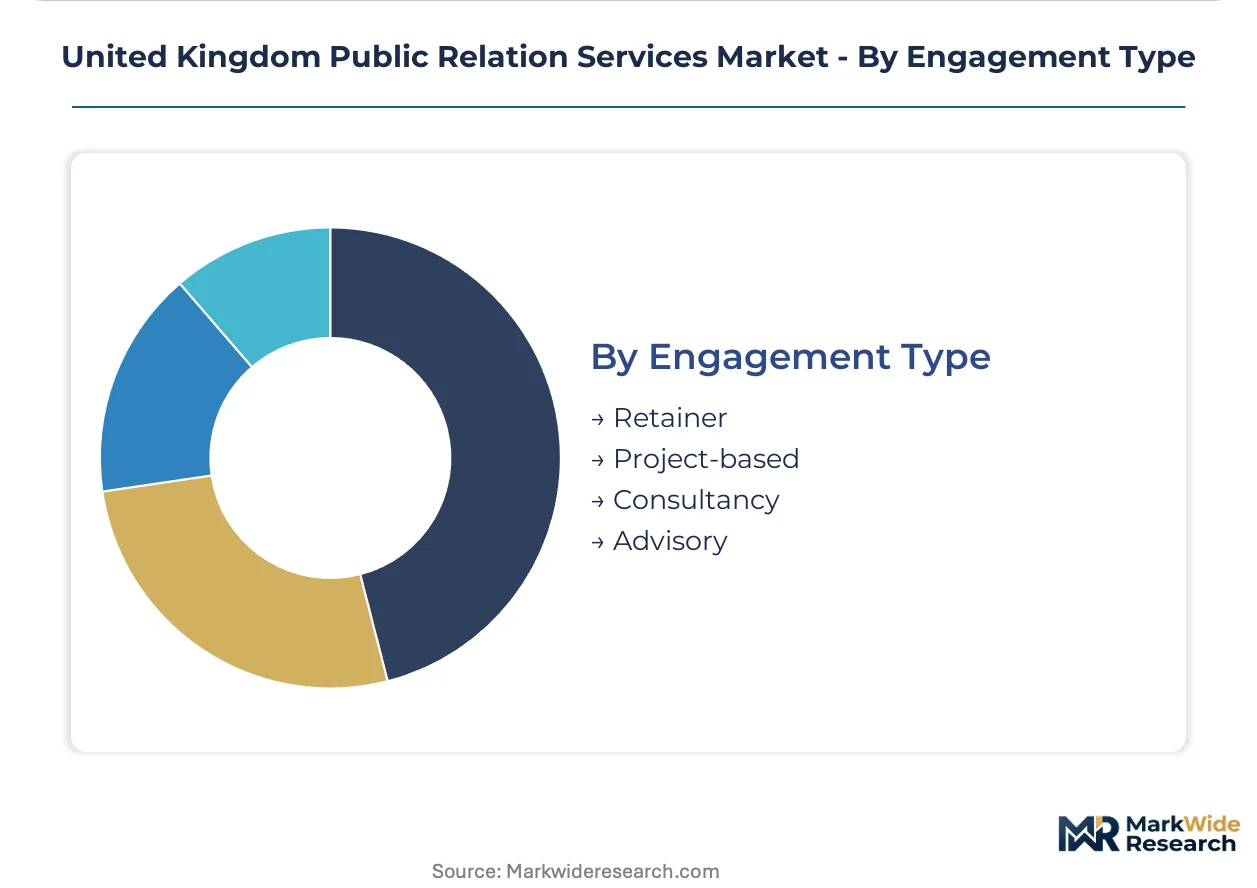
Engagement Type:
Margin profiles diverge by engagement structure, with advisory retainers sustaining premium pricing against commoditized project work.
- Retainer:Long-term advisory relationships with standby crisis capabilities and ongoing reputation monitoring anchor agency stability. Technology sector buyers are expanding retainer contracts with specialist agencies for regulatory navigation.
- Project-based:Discrete digital activations and campaign-specific execution suit procurement teams demanding outcome attribution. Pricing faces compression from competitive bidding and scope clarity requirements.
- Consultancy:Strategic diagnostics and organizational communication audits command day-rate premiums. Limited recurring revenue creates revenue volatility for boutique practitioners.
- Advisory:Board-level counsel and executive positioning services target C-suite access. Highest margin tier but constrained by relationship-intensive scaling limits.
Retainer structures hold the largest share; Project-based engagements are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London's corporate communications cluster consumes premium strategic counsel for FTSE-listed mandates, while Manchester's digital PR hub drives search-engine visibility adoption. Scotland and Northern England concentrate public sector procurement, with Wales developing specialist sustainability storytelling capacity.
London and the Southeast
Financial services and technology sector buyers anchor the deepest retainer relationships in Europe's largest corporate communications cluster. The UK Online Safety Bill and Advertising Standards Authority guidelines force agencies to embed compliance infrastructure directly into creative workflows. The City of London and Canary Wharf concentrate crisis management specialists serving regulated industries with compressed-response mandates.
Manchester and the North West
Technology sector startups and scale-ups favor project-based digital activations over strategic dependency. The region's growing digital PR hub attracts mid-sized agencies seeking distance from London saturation. Manchester's MediaCityUK cluster houses broadcast-integrated storytelling capabilities serving consumer brands and B2B technology firms.
Scotland
Public sector procurement frameworks and energy sector corporate affairs sustain steady advisory demand. The Scottish Government's net-zero policy communications create specialized sustainability storytelling requirements. Edinburgh's financial services cluster and Aberdeen's energy transition mandates concentrate regulatory disclosure expertise.
Wales
Public sector and third-sector communications dominate contract flow through Welsh Government procurement channels. Cardiff's developing agency ecosystem serves healthcare and education sector clients with bilingual campaign requirements. The Senedd's policy agenda drives demand for stakeholder engagement around regional infrastructure investment.
Northern England
Manufacturing and logistics sector corporate affairs sustain mid-market retainer relationships outside capital premium pricing. Leeds and Newcastle house regional agency networks serving FTSE 250 companies with distributed operational footprints. Northern Powerhouse policy communications create intermittent project-based demand for infrastructure narrative development.
United Kingdom Public Relation Services Market Competitive Landscape
Capability concentration sits with specialist boutiques holding crisis management and legal-communications coordination expertise; scale advantage sits with networked groups offering cross-border media buying synergies. The market structures around three archetypes: global networked agencies anchoring complex reputation mandates, mid-sized sector specialists capturing technology retainer expansion, and independent boutiques serving project overflow. Dominant competitive moves include unbundling retainer structures into modular strategy-execution components and deepening regulatory compliance infrastructure as client procurement demands clearer outcome attribution.
Within the global networked tier, Edelman and WPP occupy positions anchoring integrated corporate reputation mandates for multinational clients. BCW represents the scale-driven archetype leveraging cross-agency media relationships. Among mid-sized specialists, Berkeley Communications Group exemplifies sector-focused positioning capturing technology buyer retainer expansion. These named entities serve as anchors for industry-level dynamics rather than specific strategic action claims.
| Leading Market Players |
|---|
| Edelman |
| BCW |
| Weber Shandwick |
| Hill+Knowlton Strategies |
| WPP |
| Omnicom Group |
| Berkeley Communications Group |
| MHP Communications |
| PRLab |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in specialist crisis management talent across Manchester and Scotland is compressing project timelines and elevating retainer premiums, while simultaneously forcing procurement teams toward modular contract structures that fragment pricing power across the London-Manchester corridor.
Pricing Analysis
Long-term retainer contracts dominate enterprise-grade strategic counsel, while project-based digital activations serve venture-backed technology buyers seeking outcome-attributed engagements. Pricing stratifies across premium crisis standby, standard media relations, and economy project tiers, with differentiation anchored in regulatory disclosure expertise and ASA compliance infrastructure. Cost compression in mid-tier digital execution is intensifying because AI-assisted drafting tools are virtualizing narrative architecture functions. FTSE-listed corporates in London's financial district exhibit lowest price sensitivity; Manchester startups and scale-ups drive hardest procurement negotiations.
Supply Chain Analysis
Extended payment terms from public sector procurement frameworks are straining mid-sized agency cash flows, particularly in Wales and Scotland where government contracts concentrate. Talent supply draws from London's corporate communications cluster, Manchester's MediaCityUK broadcast-integrated capabilities, and Edinburgh's regulatory disclosure specialists. Single-source vulnerability sits with crisis management practitioners holding simultaneous legal-communications coordination expertise. Distribution runs through direct client-agency relationships, approved supplier frameworks, and hybrid captive-external execution models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK PR services market operates as a defensive-moat business where regulatory entrenchment creates sticky client relationships—ASA and Ofcom compliance requirements embed agencies deeply into creative workflows, generating switching costs that protect incumbent positions.
For Market Incumbents: Pre-empt modular unbundling by building dedicated compliance infrastructure that procurement teams cannot replicate internally. Deepen crisis management standby capabilities to capture technology sector retainer expansion. Vertical integration into sentiment analytics platforms addresses input cost volatility from third-party data licensing restrictions.
For New Entrants and Emerging Players: Establish a beachhead in Manchester's underpenetrated digital PR hub where technology sector presence is accelerating fastest. Target project-based SEO-integrated storytelling and influencer network activation for venture-backed scale-ups seeking distance from London agency saturation. Lead with AI-enabled narrative architecture tools to compress creative cycles and differentiate from established retainer-based competitors.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across digital execution sub-segments as generative language models reduce headcount-dependent delivery costs. Acquisition targets should exhibit sector-specialist positioning with regulatory compliance infrastructure—crisis management and legal-communications coordination capabilities command durable premium pricing. Watch for ASA enforcement action acceleration as an inflection signal for compliance advisory demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Infrastructure Buildout | ASA and Ofcom duty adherence embeds agencies into client workflows, creating defensive moats through mandatory co-creation. |
| AI-Enabled Narrative Architecture Integration | Generative language models compress creative cycles while elevating premium pricing for human-led strategic counsel on complex mandates. |
| Specialist Crisis Management Capacity Expansion | Compressed-response protocols and legal-communications coordination command retainer premiums from FTSE-listed and technology sector buyers. |
| Manchester Digital Hub Geographic Expansion | MediaCityUK cluster proximity attracts technology startups seeking project-based digital activations outside London saturation. |
| Hybrid Model IP Ownership Clarification | Clear workflow integration protocols reduce friction as corporates blend captive strategy teams with external creative execution. |
Research Methodology
Cross-validation between primary interviews with agency managing directors, technology sector procurement leads, and regulatory affairs specialists anchors the qualitative findings. Secondary validation draws from ASA enforcement action databases, Ofcom consultation submissions, and Companies House filing records. Bottom-up triangulation across service type, client sophistication tier, and engagement structure converges with top-down macroeconomic calibration.
Calibration against historical retainer contract growth patterns and technology sector buyer adoption curves shapes the analytical framework across the analysis window. Segmentation dimensions modeled include service specialization, delivery model configuration, client type stratification, and geographic cluster concentration. CAGRs derive from trend extrapolation moderated by regulatory enforcement intensity and AI diffusion rates. GDPR enforcement trajectory and Online Safety Bill implementation pace serve as industry-specific forecast inputs.
Stress conditions across regulatory acceleration, talent migration patterns, and platform API restriction severity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about technology sector buyer behavior and compliance cost pass-through elasticity. Macroeconomic contraction, regulatory enforcement deceleration, or generative AI capability breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Digital Ad Spending Market
Advertising and Marketing Media
Brand Licensing Market
Advertising and Marketing Media
Brazil OOH and DOOH Market
Advertising and Marketing Media
Social Network Advertising Market
Advertising and Marketing Media
North America Public Relation Services Market
Advertising and Marketing Media
South Korea OOH and DOOH Market
Advertising and Marketing Media
US Healthcare Advertising Market
Advertising and Marketing Media
Germany OOH and DOOH Market
Advertising and Marketing Media
In-App Advertising Market
Advertising and Marketing Media
Global Print Advertising Market
Advertising and Marketing Media
Outdoor Advertising Market
Advertising and Marketing Media
Indoor LCD Advertising Players Market
Advertising and Marketing Media
In-Game Advertising Market
Advertising and Marketing Media
Retail Media Creative Optimization Market
Advertising and Marketing Media
Middle East Marketing and Advertising Agency Market
Advertising and Marketing Media
Global Social Advertising and Social Media Market