
 Kids Musical Instrument Market | 2026-2036
Kids Musical Instrument Market Size, Share, and Industry Trends Forecast 2026-2036
Kids Musical Instrument Market Outlook
Market Dynamics
Chinese toy manufacturing clusters are rebalancing capacity toward educational musical products as labor costs shift. Yamaha Corporation leverages its acoustic engineering heritage to dominate premium wooden instrument tiers for school-age learners. Casio Computer Co., Ltd. sustains volume leadership in portable keyboards through plastic chassis standardization and battery-efficient designs. Melissa & Doug anchors the toddler segment with fabric and wood hybrid percussion sets sold through mass retail channels.
Product and Segment Structure
Kids musical instruments encompass scaled, simplified acoustic and electronic devices engineered with reduced string tension, padded mallets, or limited key spans to accommodate developing motor skills and hearing sensitivity in users typically aged six months to twelve years. Manufacturing emphasizes non-toxic finishes, rounded edges, and tunable components that withstand repetitive impact while maintaining pitch accuracy within child-appropriate frequency ranges. String instruments and keyboards command the largest revenue pools due to parental preference for instruments that transition into formal music education, while percussion instruments built from wood and fabric capture the fastest growth in infant and toddler age groups where durability and sensory texture drive purchase decisions.
Regulatory Environment and Outlook
The EU Toy Safety Directive and EN 71 standards mandate phthalate-free plastics and decibel limits for electronic instruments sold in Europe, while the US Consumer Product Safety Commission enforces similar material restrictions through the Consumer Product Safety Improvement Act. China's GB standards for toy safety, administered by the Standardization Administration, increasingly align with international norms as domestic brands target export markets. Stakeholders must monitor evolving acoustic exposure guidelines and chemical substance restrictions that will determine which material formulations and electronic designs retain market access across major economies.
Market Dynamics
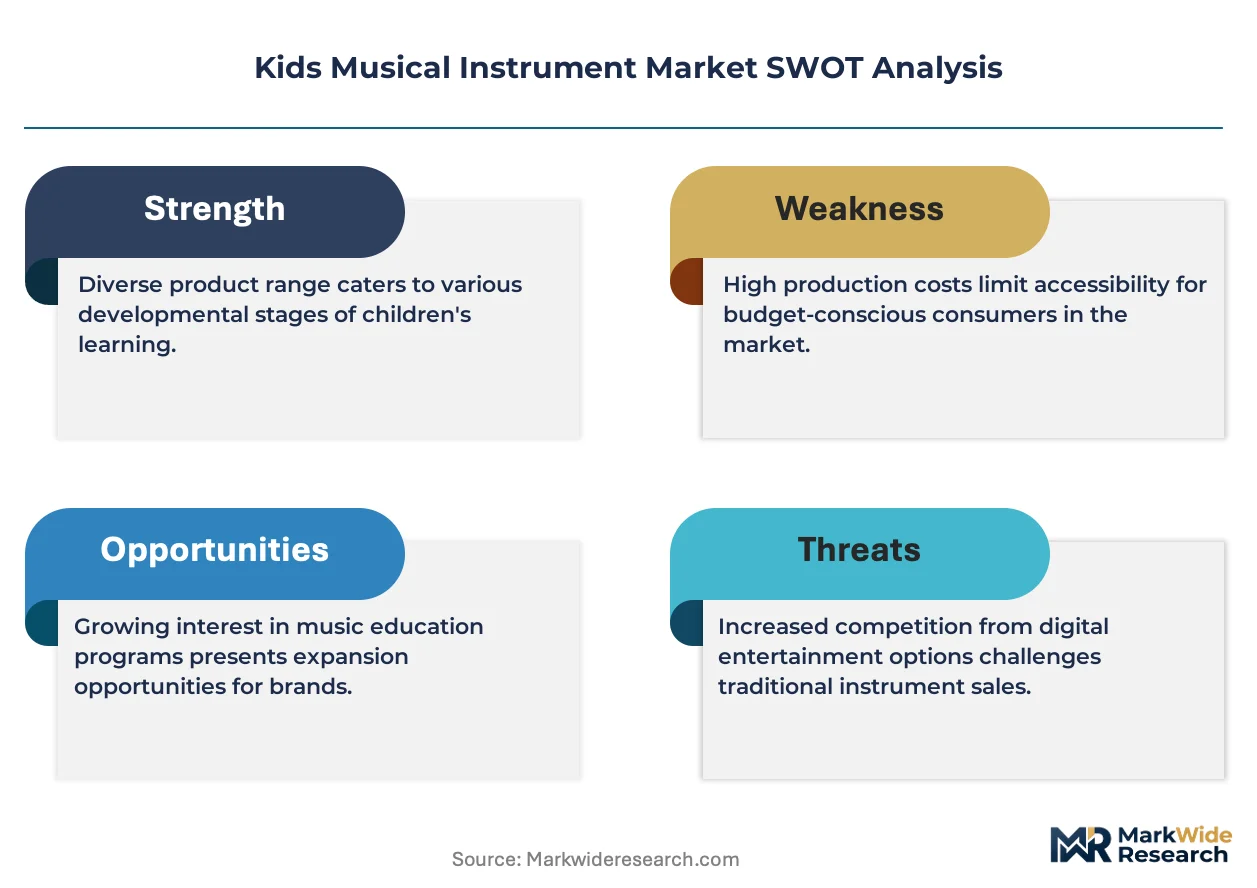
Regulatory tightening on acoustic exposure limits and material safety is forcing manufacturers to redesign electronic instruments and reformulate plastic composites, compressing margins while creating certification barriers that favor scaled producers with dedicated compliance infrastructure.
Growth Catalysts
- EU Toy Safety Directive EN 71-1:Harmonized mechanical and physical testing standards reduce fragmentation in export compliance, enabling Chinese manufacturers to consolidate certification costs across European markets.
- Preschool enrollment expansion:China's domestic early childhood education infrastructure buildout generates localized demand for percussion and keyboard instruments in tier-two and tier-three cities.
- Digital audio workstations:MIDI-compatible children's keyboards bridge home play and formal instruction, accelerating replacement cycles as parents seek instruments with educational software integration.
Market Restraints
- Phthalate-free polymer costs:Bio-based plastic alternatives for instrument casings carry 15-25% raw material premiums that smaller manufacturers cannot absorb without pricing out of mass retail.
- Guangdong manufacturing concentration:Over 60% of global wooden instrument production clusters in the Pearl River Delta, exposing supply chains to single-point labor disruptions and shipping congestion.
- Acoustic decibel ceilings:EN 71-1 and US CPSC hearing safety limits cap electronic instrument output, constraining product differentiation in the premium electronic segment.
Strategic Opportunities
- Subscription-based instrument access:Rental and trade-in programs for student-grade violins and cellos address parental hesitation over purchase commitment as children abandon formal lessons.
- India's toy manufacturing PLI scheme:Production-linked incentives for plastic and wooden toys create alternative sourcing bases outside China for EU and US brands seeking supply diversification.
- App-integrated acoustic instruments:Bluetooth-enabled tuning feedback and practice tracking in entry-level guitars and ukuleles captures digitally native parent segments in urban Japan and South Korea.
Industry Challenges
- Acoustic engineer scarcity:Tuning and voicing expertise for child-scaled string instruments remains concentrated in aging European and Japanese craft traditions, limiting quality-controlled volume expansion.
- Multi-jurisdiction certification lag:Simultaneous EN 71, ASTM F963, and GB 6675 testing extends product launch timelines by 8-14 months for new electronic instrument platforms.
Report Scope
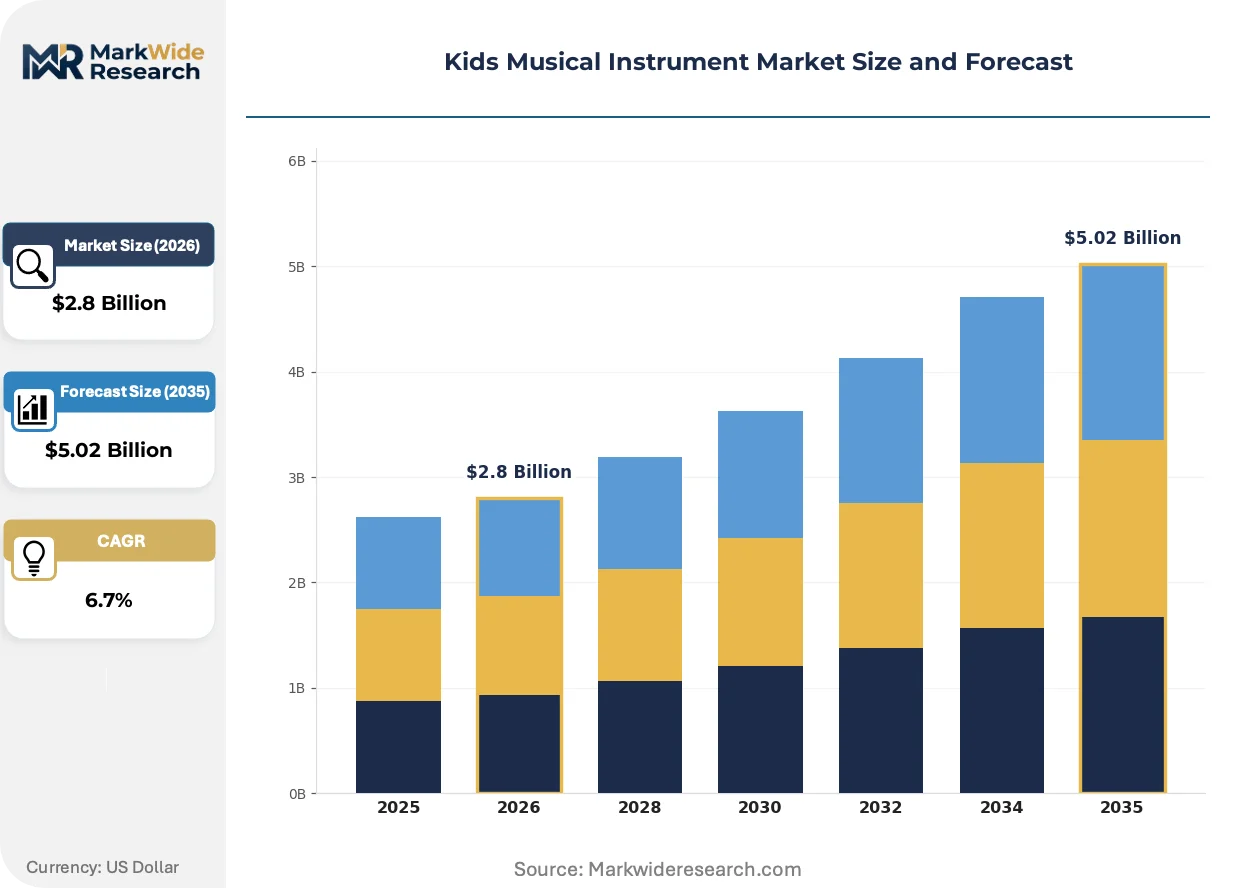
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kids Musical Instrument Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: String Instruments, Percussion Instruments, Wind Instruments, Keyboards Material: Wood, Plastic, Metal, Fabric Age Group: Infants, Toddlers, Preschoolers, School Age Skill Level: Beginner, Intermediate, Advanced, Recreational |
| Companies Covered | Loog Guitar, Casio Computer Co., Ltd., First Act, Roland Corporation, Yamaha Corporation, Melissa & Doug, Nino Percussion, John Packer Ltd., VTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kids Musical Instrument Market Strategic Shifts
Digital connectivity and material science advances are redefining how children's instruments deliver educational value, with hardware-software integration and sustainable material substitutions emerging as the primary vectors of competitive differentiation.
Silicone-based flexible keyboards with pressure-sensitive capacitive surfaces are modularizing how manufacturers configure product lines. Preschool music programs in US public school districts are adopting these instruments for shared classroom use due to sanitization durability. The technology is modularizing supply chains by allowing identical electronic cores to serve multiple instrument form factors through interchangeable silicone overlays.
REACH candidate list expansion for endocrine-disrupting chemicals is tightening compliance scope for plasticizer formulations in EU-bound instruments. Manufacturers must reformulate PVC components or switch to TPU alternatives to maintain market access. The percussion segment faces the steepest substitution costs due to high mallet and drum skin contact surfaces requiring frequent material verification.
Parental purchasing is fragmenting across direct-to-consumer channels and specialty music retailers as Amazon and vertical subscription services capture instrument discovery. Traditional toy superstores are losing keyboard and string instrument traffic to dedicated music education platforms offering bundled lesson content. This shift is most pronounced in German-speaking Europe where Thomann and specialized e-commerce have eroded mass retail instrument sales.
Kids Musical Instrument Market Segmentation
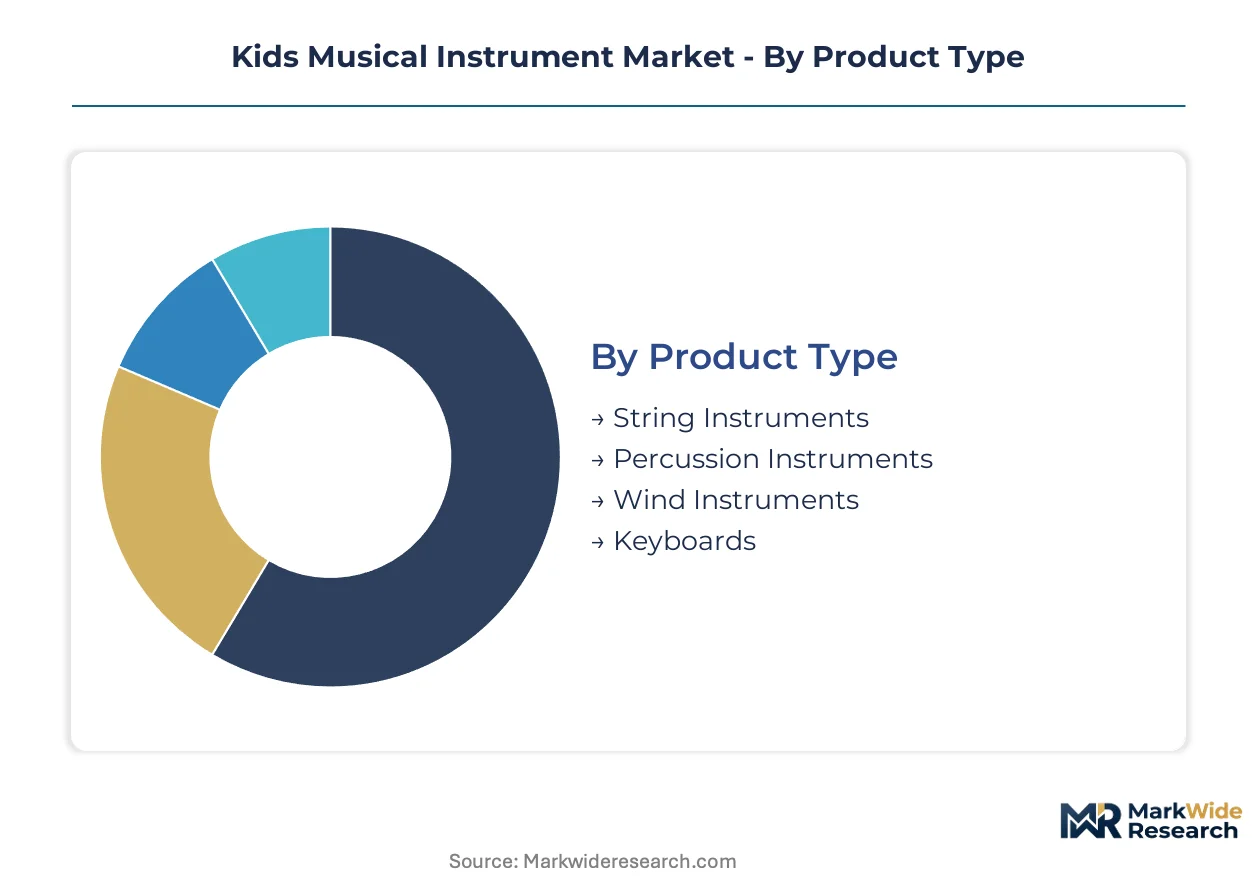
Segmentation in the Kids Musical Instrument Market reveals distinct procurement patterns across educational institutions and retail channels. Product specifications, material compliance requirements, and age-appropriate design standards create non-overlapping demand clusters that manufacturers must address through dedicated product lines.
Product Type:
Integration depth varies sharply: keyboards and string instruments embed into formal lesson curricula, while percussion and wind instruments serve standalone sensory play and school band programs respectively.
- String Instruments:Child-scaled violins, cellos, and guitars feature reduced string tension and fractional body sizes. School district procurement in the United States concentrates purchase orders for student-grade orchestral instruments, constrained by acoustic engineer scarcity that limits quality-controlled volume expansion.
- Keyboards:Portable electronic units with MIDI compatibility and limited key spans dominate home education transitions. Chinese manufacturing clusters in Guangdong province supply battery-efficient designs to mass retail channels, though EN 71-1 decibel ceilings constrain premium differentiation.
- Percussion Instruments:Xylophones, drums, and rhythm sets built from wood and fabric hybrids target toddler sensory development. REACH candidate list expansion for endocrine-disrupting chemicals drives reformulation costs for mallet and drum skin contact surfaces.
- Wind Instruments:Recorders, harmonicas, and simplified brass units emphasize breath control introduction. German music education platforms bundle these with digital lesson content, eroding traditional toy superstore traffic.
Volume placements concentrate in Keyboards; the faster expansion belongs to Percussion Instruments.
Material:
Cost tier stratification separates premium sustainable sourcing from mass-market synthetic alternatives, with compliance certification costs acting as a margin threshold.
- Wood:Maple, birch, and bamboo constructions dominate premium acoustic instruments. Yamaha Corporation leverages Japanese acoustic engineering heritage for school-age learner segments, sourcing tonewood through aging European craft traditions.
- Plastic:ABS and polypropylene chassis enable portable keyboard standardization and sanitization durability. Phthalate-free polymer alternatives carry raw material premiums that smaller manufacturers cannot absorb without pricing out of mass retail.
- Metal:Aluminum and steel components reinforce structural integrity in cymbals and tuned percussion. China's GB standards alignment with international norms enables domestic brands to target export markets with certified metal formulations.
- Fabric:Silicone and textile hybrids create collapsible, washable surfaces for infant percussion sets. US public school districts adopt these for shared classroom use due to sanitization protocols.
Plastic commands the highest shipment volumes; wood captures the steepest price premiums.
Age Group:
Application context shifts from sensory-motor development in early years to skill acquisition and formal instruction in later stages.
- Infants:Fabric and silicone percussion instruments emphasize texture exploration and safe mouthing. EN 71-1 mechanical testing standards govern rounded edges and non-toxic finishes for European market access.
- Toddlers:Wood and hybrid percussion sets build gross motor coordination. Melissa & Doug anchors this segment through mass retail distribution with durability-focused designs.
- Preschoolers:Simplified keyboards and string instruments introduce pitch recognition. China's domestic early childhood education infrastructure buildout generates localized demand in tier-two and tier-three cities.
- School Age:Full-function instruments bridge into formal music education. Parental hesitation over purchase commitment drives subscription-based rental program adoption for student-grade violins and cellos.
Preschoolers generate the largest absolute demand; infants are climbing the fastest.
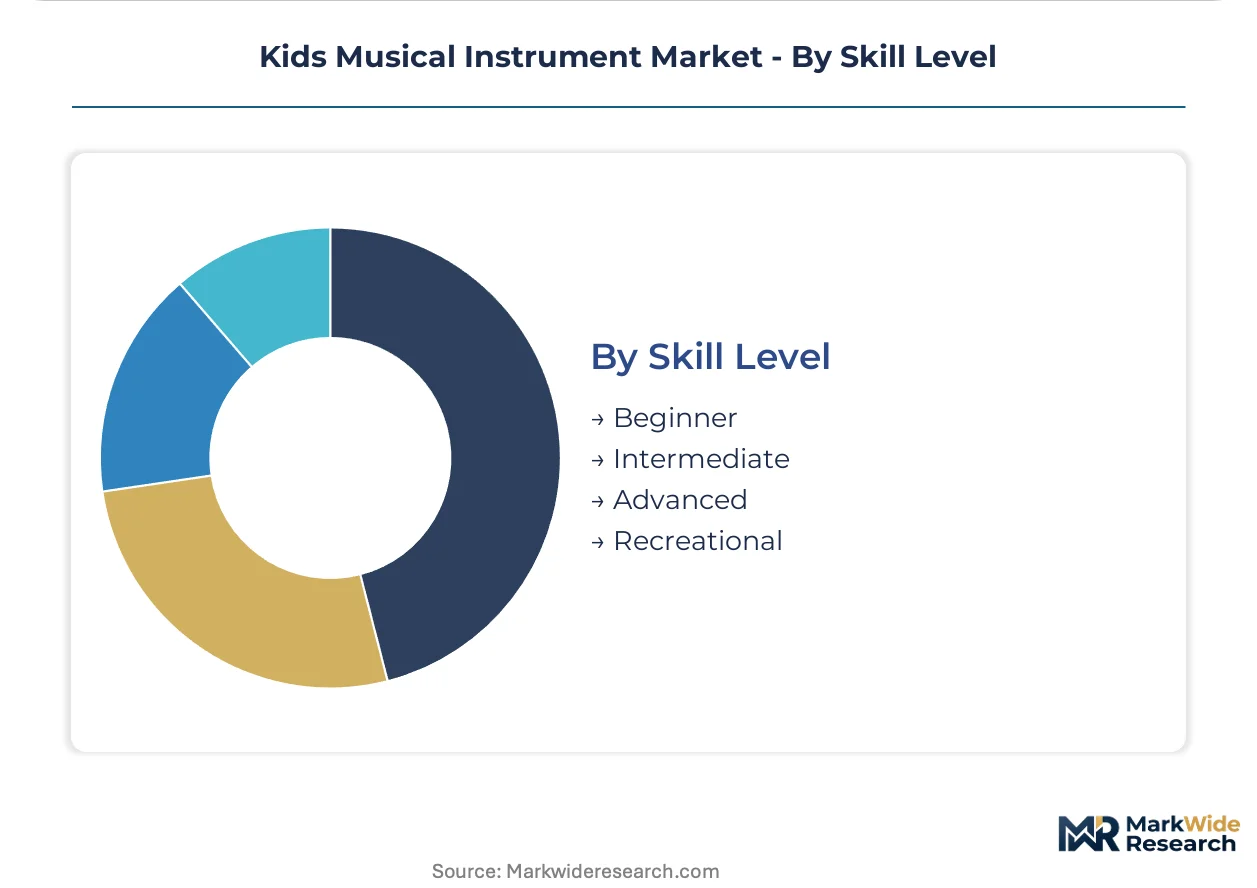
Skill Level:
Customer type segmentation separates institutional procurement from household purchase decisions, with commitment duration varying by progression stage.
- Beginner:Reduced string tension, padded mallets, and limited key spans accommodate developing motor skills. Casio Computer Co., Ltd. sustains volume leadership through plastic chassis standardization.
- Intermediate:Tunable components maintaining pitch accuracy support lesson advancement. Bluetooth-enabled tuning feedback in entry-level guitars captures digitally native parent segments in urban Japan and South Korea.
- Advanced:Child-scaled professional-grade instruments prepare for conservatory transition. Acoustic engineer scarcity limits quality-controlled volume expansion for this tier.
- Recreational:App-integrated acoustic instruments with practice tracking serve casual engagement. Amazon and vertical subscription services fragment parental purchasing away from traditional toy superstores.
Beginner instruments dominate shipment volumes; recreational products show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong province anchors wooden instrument production through Pearl River Delta clusters that supply scaled acoustic components to international brands. Labor cost migration and regulatory divergence across destination markets are redrawing procurement geography for finished goods.
United States
Public school district procurement drives institutional volume for student-grade orchestral strings and percussion. The US Consumer Product Safety Commission enforces material restrictions through the Consumer Product Safety Improvement Act, constraining phthalate content in plastic components. Tennessee and Texas distribution hubs consolidate inbound shipments from Asian manufacturing clusters for redistribution to Midwest and Southeast education markets.
China
Domestic preschool enrollment expansion in tier-two and tier-three cities generates localized demand for entry-level keyboards and percussion sets. The Standardization Administration administers GB standards for toy safety that increasingly align with international norms for export-bound production. Zhejiang and Jiangsu provinces are developing alternative wooden instrument manufacturing bases as Guangdong labor costs rise.
Germany
Specialized music education platforms and vertical e-commerce capture parental purchasing for wind instruments and lesson bundles. ECHA administers REACH candidate list expansion for endocrine-disrupting chemicals, tightening compliance scope for plasticizer formulations. Bavarian acoustic engineering traditions concentrate tuning expertise for child-scaled string instruments serving conservatory feeder programs.
Japan
Digitally native parent segments in urban centers drive adoption of Bluetooth-enabled acoustic instruments with practice tracking. METI oversees alignment with international safety standards for electronic instruments targeting export markets. Hamamatsu and surrounding Shizuoka prefecture clusters maintain acoustic R&D capabilities for premium wooden instrument tiers.
India
Production-linked incentive schemes for plastic and wooden toys attract contract manufacturing investment from EU and US brands seeking supply diversification. BIS certification requirements for toy safety create compliance infrastructure demands for new market entrants. Maharashtra and Gujarat industrial corridors are developing component supply ecosystems for percussion instrument assembly.
Kids Musical Instrument Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue app-integrated hardware and subscription access models. The vendor base stratifies across acoustic heritage specialists, electronics-scale manufacturers, and educational content integrators. Three archetypes dominate: vertically integrated instrument conglomerates with tuning expertise, mass-market electronics fabricators with plastic chassis standardization, and toy-industry crossovers with mass retail distribution. Competitive moves concentrate on M&A for acoustic engineering talent and strategic partnerships with digital lesson platforms.
Within the acoustic heritage tier, Yamaha Corporation and Roland Corporation exemplify engineering-led positioning built on decades of instrument voicing capability. Casio Computer Co., Ltd. represents the electronics-scale archetype through battery-efficient design standardization and portable keyboard volume leadership. Melissa & Doug occupies the toy-industry crossover position, anchoring toddler-segment distribution through mass retail channel relationships. These three patterns illustrate how competitive advantage sources diverge across price-performance tiers.
| Leading Market Players |
|---|
| Loog Guitar |
| Casio Computer Co., Ltd. |
| First Act |
| Roland Corporation |
| Yamaha Corporation |
| Melissa & Doug |
| Nino Percussion |
| John Packer Ltd. |
| VTech |
| Others |
Value Chain & Pricing Dynamics
Acoustic engineer concentration in Bavaria and Hamamatsu sustains premium-tier pricing power, while Pearl River Delta labor-cost migration widens spreads between artisan-grade wooden instruments and mass-market electronic alternatives.
Pricing Analysis
Warranty and service bundling separates premium acoustic tiers from unbundled mass-market electronics. Three-tier pricing structure across premium, standard, and economy levels rests on certification grade and after-sales service inclusion. Price erosion runs through the economy tier as phthalate-free polymer costs compress margins. School district procurement teams exhibit highest price sensitivity; conservatory feeder programs show lowest.
Supply Chain Analysis
Certification gating through EN 71, ASTM F963, and GB 6675 testing extends qualification timelines and favors scaled producers. Manufacturing concentrates in China, Vietnam, and Indonesia for wood and plastic components. Raw material inputs draw from Baltic birch tonewood, ABS polymer feedstock, and rare earth magnets for electronic pickups. Single-source vulnerability clusters in Guangdong wooden instrument clusters. Distribution runs through Tennessee and Texas hubs for US education markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained: acoustic engineer scarcity props pricing power in premium tiers while constraining quality-controlled volume expansion.
For Market Incumbents: To counter emerging app-integrated hardware entrants, Yamaha Corporation and Roland Corporation should deepen captive supply of Japanese tonewood and acquire Bluetooth-enabled tuning technology specialists. Certification investment in simultaneous EN 71 and GB 6675 pre-qualification defends channel access against faster-moving challengers. For New Entrants and Emerging Players: Enter via India's PLI scheme for plastic and wooden toy manufacturing, targeting EU and US brands seeking China diversification. The most penetrable white-space sits in subscription-based instrument access for student-grade strings. Go-to-market should pair with vertical lesson platforms like Thomann's education bundling. For Investors and Strategic Acquirers: The window for entry favors acoustic engineering specialists with aging European craft traditions and no succession planning. Long-term viability centers on 5-10 year holding periods for tuning expertise consolidation. The signal to watch is REACH candidate list expansion accelerating plasticizer reformulation costs and triggering distressed exits.| Strategic Initiative | Industry Significance |
|---|---|
| Acoustic Engineering Talent Acquisition | Yamaha Corporation's voicing expertise becomes unreplicable as Japanese craft traditions age without replacement pipelines. |
| Phthalate-Free Polymer Reformulation | REACH compliance investments by Casio Computer Co., Ltd. create certification barriers that smaller manufacturers cannot cross. |
| Bluetooth-Enabled Hardware Integration | Hamamatsu R&D clusters feed METI-aligned export standards for digitally native parent segments in urban Japan. |
| India PLI Scheme Manufacturing Footprint | BIS certification infrastructure in Maharashtra corridors enables EU and US brand supply diversification outside China. |
| Subscription Rental Program Launch | Melissa & Doug's mass retail relationships could extend into trade-in models addressing parental purchase-commitment hesitation. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with product development directors at instrument conglomerates, procurement officers at US public school districts, compliance managers at Guangdong manufacturing clusters, and category buyers at mass retail chains combined with secondary validation. Secondary sources included EN 71 testing documentation, US CPSC enforcement records, China customs export data, and EU REACH candidate list updates. Bottom-up shipment tallies by product type and material triangulated against top-down education spending forecasts.
Data-stream reconciliation across manufacturer shipment reports, institutional procurement databases, and retail audit channels informed the analytical framework. Segmentation dimensions modeled encompass product type, material composition, age group, and skill level across the projection horizon. CAGRs derived from curve-fitting historical volume trajectories against preschool enrollment expansion rates and regulatory compliance cost indices. Industry-specific inputs included Pearl River Delta labor-cost indices and REACH substance restriction timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH candidate list expansion or Guangdong labor disruption scenarios. Forecasts reflect assumptions around certification timeline stability and material substitution cost curves. A model refresh is warranted upon material change in EU acoustic exposure limit enforcement or India PLI scheme uptake rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Musical Instruments
Smart Musical Instrument Market
Musical Instruments
Bass Guitar Market
Musical Instruments
Digital Piano Market
Musical Instruments
Woodwind Instruments Market
Musical Instruments
Drum Sets Market
Musical Instruments
Global Piano Market
Musical Instruments
Electric Violin Market
Musical Instruments
Guitar Market
Musical Instruments
Violin Market
Musical Instruments
Electric Guitar Market
Musical Instruments
Digital Ensemble Pianos Market
Musical Instruments
Electronic Musical Instruments Market
Musical Instruments
Classical Guitar Market