
 Woodwind Instruments Market | 2026-2036
Woodwind Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Woodwind Instruments Market Insights
Aftermarket service revenue is tilting toward professional instrument overhaul and customization as manufacturers seek recurring income beyond initial sales. Yamaha leverages vertical integration across component fabrication and final assembly to control quality consistency. Henri Selmer Paris anchors premium professional saxophone and clarinet positioning through Parisian craftsmanship heritage. Buffet Crampon sustains dominance in French system clarinets through specialized bore design expertise.
Woodwind instruments comprise aerophones where air column vibration within a bore tube produces pitched tone, with key mechanisms altering effective tube length to change pitch; modern variants incorporate precision-milled tone holes, synthetic pad materials, and ergonomic key layouts to stabilize intonation across temperature and humidity extremes. The product type dimension shows saxophones capturing expanding jazz and contemporary ensemble participation while student flutes represent a mature, high-volume entry segment with compressed margins. Material selection increasingly concentrates in composite and advanced polymer formulations as manufacturers balance acoustic properties against CITES restrictions on tropical hardwoods.
The EPA governs volatile organic compound emissions from instrument finishing processes in the United States, while REACH restricts hazardous substances in lacquers and metal plating across European manufacturing. CITES appendix listings for grenadilla and rosewood directly constrain traditional oboe and clarinet body sourcing, pushing R&D toward certified sustainable alternatives. Stakeholders must monitor evolving trade instrument regulations and synthetic material acoustic validation to secure supply continuity and product certification access.
Market Dynamics
CITES appendix listings for grenadilla and rosewood are forcing manufacturers to abandon traditional oboe and clarinet body materials, triggering a supply-side scramble for certified sustainable alternatives that reshapes acoustic R&D priorities and sourcing relationships.
Growth Catalysts
- School music program procurement:North American educational institutions sustain volume demand for student-grade flutes and clarinets through district-level bulk purchasing agreements.
- REACH material compliance:European hazardous substance restrictions accelerate synthetic pad and polymer body adoption, opening certified supply channels for export-oriented manufacturers.
- Advanced polymer formulations:Composite material breakthroughs deliver stable intonation across humidity extremes, expanding instrument reliability in tropical climates.
Market Restraints
- Tropical hardwood scarcity:CITES permitting delays for African blackwood and rosewood extend lead times for professional-grade oboe and clarinet production.
- Student segment margin compression:High-volume entry-level flute and saxophone categories face pricing pressure from concentrated Chinese manufacturing output.
- Acoustic validation timelines:Synthetic material substitution requires extended performer acceptance testing before professional orchestra adoption.
Strategic Opportunities
- Aftermarket overhaul services:Professional instrument customization and restoration creates recurring revenue streams beyond initial hardware sales.
- Ergonomic key layout patents:Biomechanically optimized mechanisms attract aging amateur player segments seeking reduced hand strain.
- Digital-physical hybrid instruction:Sensor-embedded instruments paired with mobile applications open subscription-based learning revenue models.
Industry Challenges
- Master craftsperson succession:Parisian and Viennese hand-finishing expertise faces generational transfer gaps as retirement waves hit specialized bore-lapping technicians.
- Multi-jurisdiction certification burden:Manufacturers must simultaneously satisfy EPA volatile organic compound rules, REACH substance restrictions, and ISO acoustic measurement standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Woodwind Instruments Market |
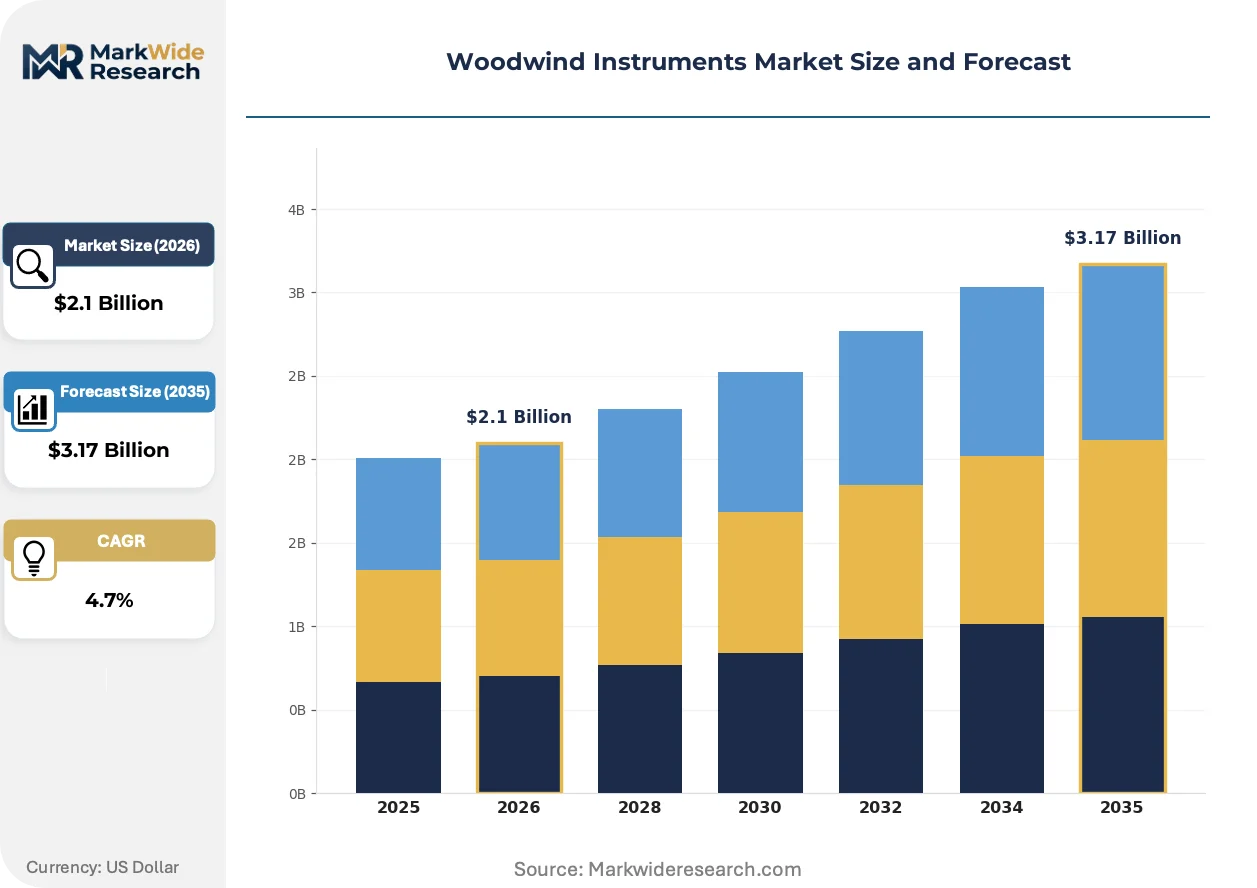
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.17 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flutes, Clarinets, Oboes, Saxophones Material: Wood, Plastic, Metal, Composite End User: Students, Professionals, Schools, Orchestras Application: Concerts, Education, Recording, Therapy |
| Companies Covered | Yamaha, Buffet Crampon, Henri Selmer Paris, Conn-Selmer, F.Lorée, Yanagisawa Wind Instruments, KHS Musical Instruments, Sahduoo Saxophone, Cannonball Saxophones, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Woodwind Instruments Market Trends and Innovations
Material science breakthroughs and regulatory pressure on traditional tonewoods are compressing the century-old craftsmanship model, while digital distribution channels and subscription learning platforms reconfigure how instruments reach players and generate lifetime value.
Additive manufacturing is collapsing the traditional tooling economics for complex key mechanism production. Student and intermediate saxophone manufacturers now prototype ergonomic layouts through selective laser sintering before committing to hard tooling. This compression of iteration cycles allows faster response to performer biomechanics feedback without capital-intensive die fabrication.
REACH substance restrictions on lacquers and metal plating are eliminating hexavalent chromium and certain solvent-based finishes from European supply chains. Manufacturers serving EU markets now specify water-based UV-cured coatings and trivalent chromium alternatives. Professional clarinet segments face the steepest reformulation burden as traditional French polish aesthetics compete against new durability requirements.
Direct-to-educator platforms are disintermediating traditional music store distribution for institutional procurement. School band directors in Texas and California now configure instrument packages through manufacturer portals with integrated financing and maintenance scheduling. This channel shift concentrates buyer power at the district level while compressing regional dealer margins.
Woodwind Instruments Market Segmentation
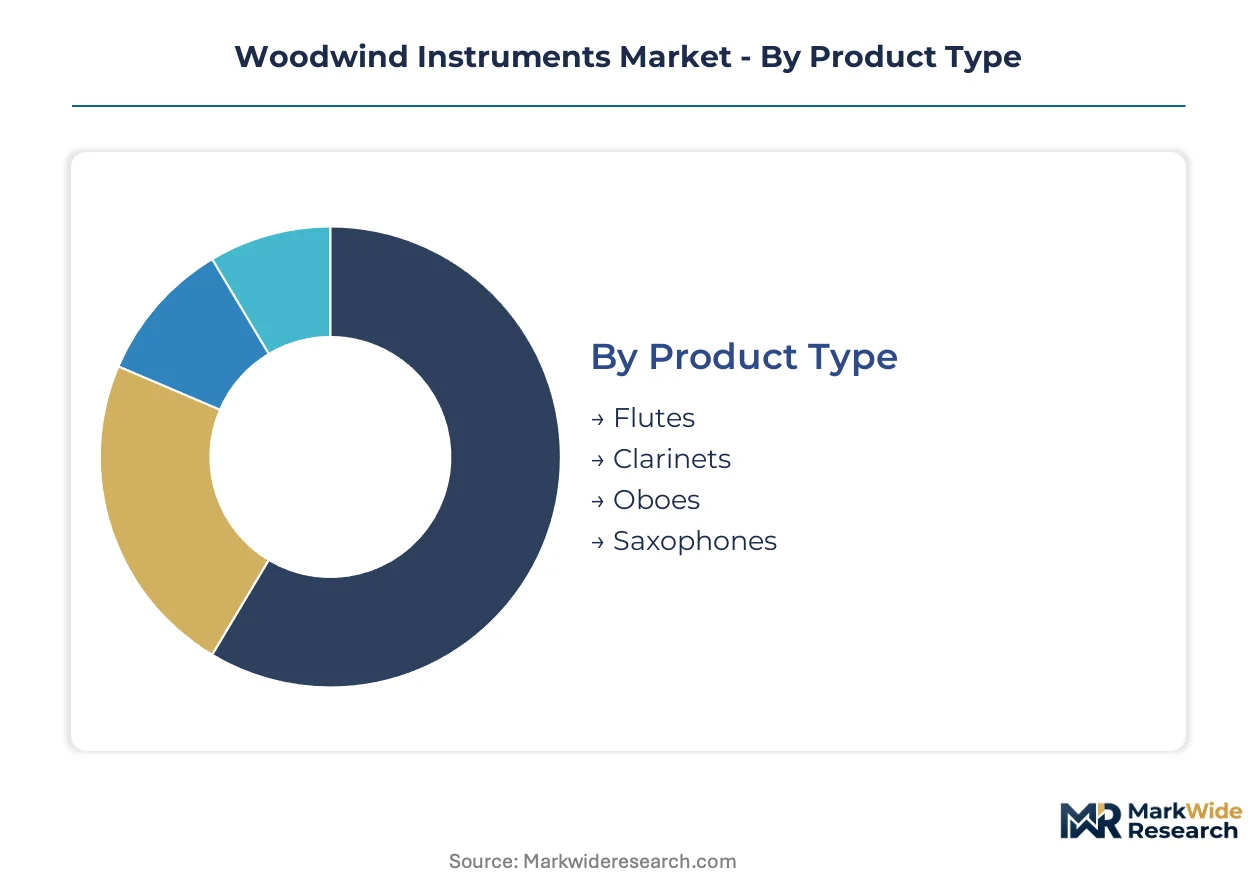
Woodwind instrument segmentation reveals divergent technical requirements across skill tiers and performance contexts. Material constraints from CITES regulations and ergonomic demands from aging amateur populations reshape how manufacturers prioritize R&D investment across product lines.
Product Type:
Players span absolute beginners in district band programs to conservatory-trained soloists demanding precision bore tolerances.
- Flutes:Cylindrical bore instruments with Boehm key systems dominate student procurement volume through bulk educational contracts. District-level purchasing in Texas and California sustains high-volume production of nickel-silver and silver-plated student models with plateau key configurations.
- Saxophones:Conical bore with single-reed mouthpiece anchors jazz ensemble participation and contemporary commercial performance. Yamaha and Selmer Paris compete for professional segment share through differentiated bore geometries and lacquer formulations that shape overtone projection.
- Clarinets:Cylindrical bore with single reed splits between French and German system fingerings, with Buffet Crampon's poly-cylindrical bore design commanding professional orchestra preference.
- Oboes:Conical bore with double reed demands hand-finished tone hole undercutting and specialized seasonal humidity adjustment, constraining production to Parisian and Viennese craft centers.
Established volume favors flutes; emerging adoption favors saxophones.
Material:
Acoustic properties collide with regulatory compliance timelines across sourcing strategies.
- Wood:African blackwood and grenadilla deliver superior damping characteristics for professional clarinet and oboe bodies. CITES appendix II listings now require chain-of-custody documentation, extending lead times and certifying sustainable plantation alternatives.
- Composite:Glass-fiber and carbon-fiber reinforced polymers stabilize pitch across temperature swings from 10°C to 40°C. Tropical military bands and outdoor ceremonial units drive demand for humidity-resistant saxophone and clarinet bodies.
- Plastic:ABS and polycarbonate formulations serve entry-level student flutes and recorders with injection-molded cost economics that undercut machined alternatives.
- Metal:Brass, nickel-silver, and silver alloys concentrate in flute construction and saxophone bodies, with wall thickness and alloy composition determining timbral brightness.
Regulatory pressure is concentrating R&D investment in composite formulations; traditional tonewood retains professional prestige despite supply constraints.
End User:
Purchasing authority and performance requirements stratify across institutional and individual buyers.
- Students:First-time players aged 10-14 require durable, low-maintenance instruments with plateau keys and synthetic pads. Price sensitivity peaks here, with Chinese manufacturing capturing volume through OEM supply to Western distributors.
- Professionals:Orchestra principals and recording session players demand hand-finished bore tolerances within 0.01mm and customized keywork. Henri Selmer Paris and Yamaha Custom series compete through artist endorsement relationships and modular upgrade paths.
- Schools:District music directors negotiate multi-year fleet replacement contracts with bundled maintenance and theft insurance. Direct-to-educator portals now disintermediate traditional music store distribution in North American markets.
- Orchestras:Section players and soloists require matched instrument sets with standardized intonation profiles, driving section-wide procurement from single manufacturers.
Institutional procurement concentrates volume in schools; individual expenditure peaks with professionals.
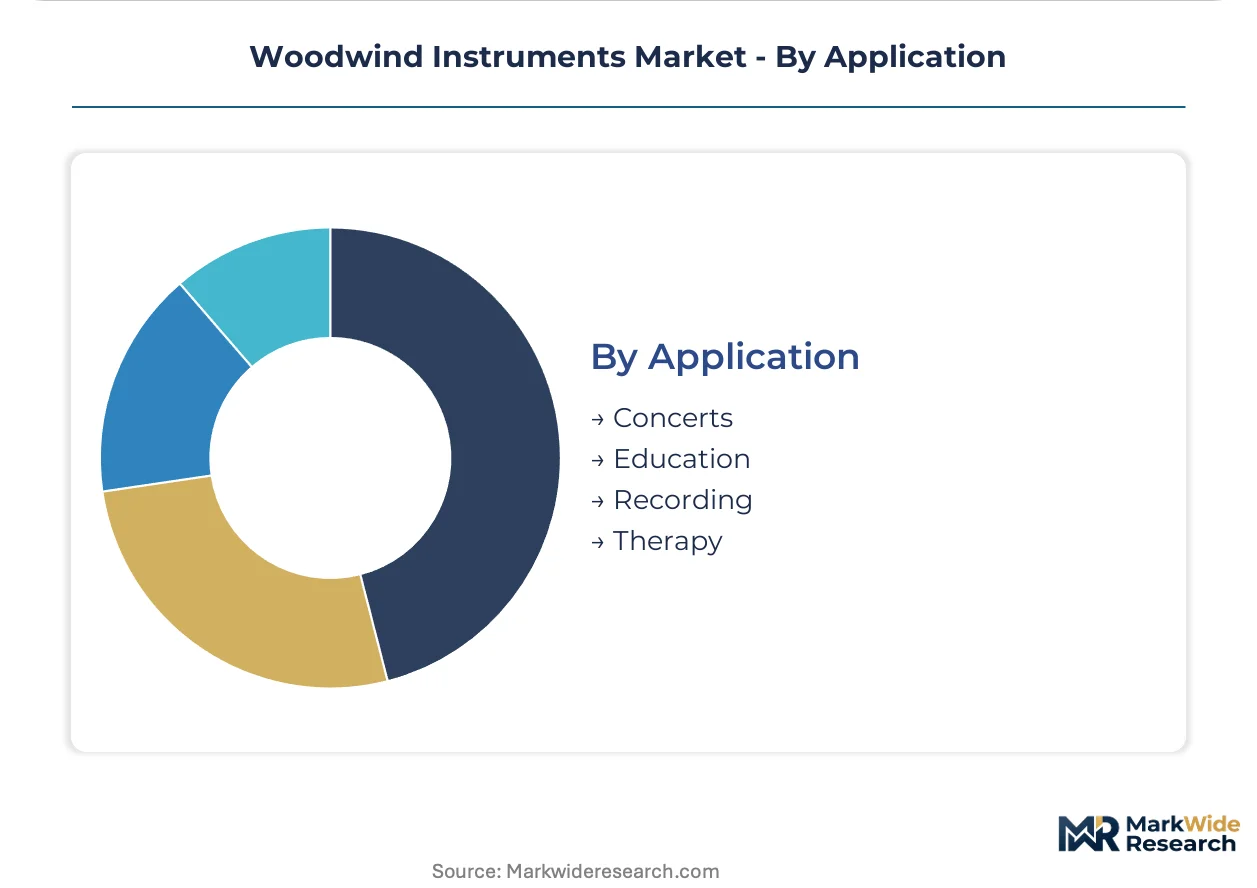
Application:
Performance context dictates durability, projection, and portability requirements.
- Education:Classroom and rehearsal hall use prioritizes dent resistance, pad longevity, and simplified maintenance protocols. REACH-compliant finishes and synthetic materials dominate this segment.
- Concerts:Live acoustic performance demands projection and blend capabilities across ensemble sections. Professional clarinetists favor French system bore designs for their overtone richness in large halls.
- Recording:Studio capture requires precise intonation stability and minimal mechanical noise from key action. Customized pad materials and silencer felts address microphone proximity.
- Therapy:Music therapy applications in clinical and geriatric settings employ simplified fingering systems and lightweight construction for motor rehabilitation protocols.
Education commands unit volume; recording applications sustain premium pricing for specialized configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with institutional procurement dominating North American volume while European professional segments prioritize certified sustainable materials and Asian markets concentrate student-grade manufacturing output.
United States
School district music programs in Texas and California drive bulk purchasing agreements for student flutes and clarinets. The EPA governs volatile organic compound emissions from instrument finishing processes, pushing manufacturers toward water-based UV-cured coatings. Elkhart, Indiana anchors domestic brass and woodwind fabrication with legacy craft infrastructure serving educational institutional contracts.
Germany
Conservatory-trained professional musicians sustain demand for precision-engineered oboes and clarinets with hand-finished bore tolerances. REACH restrictions on hazardous substances in lacquers and metal plating accelerate synthetic pad adoption across German manufacturing. Markneukirchen in Saxony concentrates historic string and wind instrument craft traditions with specialized bore-lapping technician apprenticeships.
Japan
Advanced amateur players and secondary school bands generate steady replacement demand for intermediate-grade saxophones and flutes. METI industrial standards shape quality certification protocols for export-oriented manufacturers. Hamamatsu in Shizuoka Prefecture hosts vertically integrated instrument production clusters combining component fabrication with final assembly operations.
China
Domestic music education expansion and Western distributor OEM contracts concentrate student-grade flute and saxophone output. The country's national environmental regulator enforces dual carbon goals that constrain energy-intensive metal plating operations. Tianjin and Shandong Province industrial zones specialize in injection-molded ABS body production and nickel-silver key mechanism machining at compressed cost economics.
France
Professional orchestra principals and jazz ensemble soloists sustain premium pricing for Parisian-crafted saxophones and clarinets. ECHA compliance documentation requirements extend lead times for exported instruments with traditional lacquer finishes. Mantes-la-Ville outside Paris anchors Henri Selmer Paris and Buffet Crampon operations where generational craft knowledge transfers through formal apprenticeship structures.
Woodwind Instruments Market Competitive Landscape
Capability concentration sits with heritage craft houses possessing generational bore-lapping expertise; scale advantage sits with vertically integrated Asian manufacturers controlling component fabrication through final assembly. The market structures around three tiers: Parisian and Viennese ateliers commanding professional premium positioning, Japanese integrators balancing quality consistency with volume flexibility, and Chinese OEM specialists serving compressed-margin educational procurement. Dominant competitive moves include backward integration into key mechanism production and geographic diversification of certified sustainable material sourcing.
Among heritage Parisian craft houses, Henri Selmer Paris and Buffet Crampon exemplify capability-driven positioning anchored in Mantes-la-Ville industrial concentration, while Yamaha represents the vertically integrated archetype with Hamamatsu-based control spanning precision-milled tone hole fabrication through ergonomic key layout final assembly.
| Leading Market Players |
|---|
| Yamaha |
| Buffet Crampon |
| Henri Selmer Paris |
| Conn-Selmer |
| F.Lorée |
| Yanagisawa Wind Instruments |
| KHS Musical Instruments |
| Sahduoo Saxophone |
| Cannonball Saxophones |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Parisian and Viennese bore-lapping craft centers drives premium pricing power for professional oboe and clarinet segments while pressuring manufacturers toward automated alternatives in student-grade production. This utilization gap between heritage hand-finishing capacity and mechanized volume output shapes divergent pricing strategies across skill tiers and geographic sourcing decisions.
Pricing Analysis
Long-term offtake contracts between North American school districts and major manufacturers anchor volume pricing for student flutes and clarinets, while spot-market transactions dominate professional instrument procurement. Three-tier pricing structure across premium, standard, and economy levels separates Parisian-crafted professional saxophones from Japanese intermediate models and Chinese OEM student output. Cost compression in entry-level categories is intensifying because concentrated manufacturing in Shandong Province feeds distributor price wars. School music directors exhibit highest price sensitivity through competitive bidding processes; orchestra principals demonstrate lowest sensitivity when commissioning customized keywork.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for Western distributors sourcing student-grade instrument components. Manufacturing concentrates in China, Japan, and France, with Tianjin industrial zones feeding ABS body injection molding, Hamamatsu clusters controlling precision key mechanism fabrication, and Mantes-la-Ville anchoring hand-finished professional assembly. Raw material dependencies encompass African blackwood subject to CITES permitting delays, nickel-silver alloys for keywork, and REACH-compliant water-based lacquers. Single-source vulnerability persists for grenadilla tonewood certified under chain-of-custody documentation. Distribution runs through direct-to-educator portals disintermediating traditional music store networks for institutional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs woodwind instrument value capture as sensor-embedded instruments and mobile learning applications reconfigure one-time hardware sales into recurring subscription revenue. Interoperability between physical instruments and digital instruction ecosystems represents the critical inflection reshaping competitive architecture.
For Market Incumbents: Harden defensive positioning by securing captive supply of certified sustainable tonewood alternatives before CITES restrictions tighten further, and accelerate backward integration into precision key mechanism production to insulate margins from Chinese component price volatility. Synthetic material acoustic validation timelines pose the primary threat to professional segment credibility; certification investment in ISO acoustic measurement standards offers the priority lever for maintaining orchestra adoption. For New Entrants and Emerging Players: Mid-market composite-body clarinets and saxophones for tropical military and ceremonial bands represent the most penetrable entry point, as humidity-resistant performance specifications remain underserved by traditional wood-centric manufacturers. Direct-to-consumer digital channels bypassing established distributor relationships offer the most viable go-to-market angle for building brand recognition without legacy retail margin burdens. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among aftermarket overhaul and customization service providers serving professional musician segments. Long-term viability over a multi-year horizon rests on acquiring craft houses with transferable bore-lapping expertise and established artist endorsement relationships. Watch for synthetic material acceptance inflection signals from principal orchestra player adoption as the critical indicator of professional segment disruption timing.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Sustainable Material Sourcing | CITES-compliant grenadilla alternatives secure professional clarinet and oboe production continuity. |
| Direct-to-Educator Platform Expansion | Texas and California school district portals concentrate buyer power while compressing dealer margins. |
| Ergonomic Key Mechanism Patenting | Biomechanically optimized layouts attract aging amateur segments seeking reduced hand strain. |
| Aftermarket Service Network Buildout | Professional overhaul and customization creates recurring revenue beyond initial hardware sales. |
| Digital-Physical Hybrid Product Launch | Sensor-embedded instruments with mobile applications enable subscription-based learning revenue models. |
Research Methodology
Operator-level perspectives from instrument manufacturing executives, school district music directors, professional orchestra principals, and aftermarket service technicians anchored the qualitative base. Primary interviews combined with secondary validation from SEC filings of publicly traded instrument manufacturers, customs and trade data on woodwind component flows, and music education procurement databases. Bottom-up district-level purchasing analysis and top-down manufacturer revenue triangulation established volume and value estimates.
Scenario-bracketing around CITES regulatory stringency and synthetic material adoption timelines bounded the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product type, material composition, end-user category, and application context, with regional regulatory clusters treated as distinct adoption environments. CAGRs derived from fitted growth curves applied to instrument replacement cycles and music education enrollment trends, incorporating REACH compliance cost pass-through and EPA finishing regulation impacts as industry-specific inputs.
Practitioners should monitor CITES appendix revision proceedings, synthetic material performer acceptance milestones, and school district budget allocation shifts for early signals warranting forecast reassessment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Musical Instruments
Digital Piano Market
Musical Instruments
Global Piano Market
Musical Instruments
Electric Guitar Market
Musical Instruments
Digital Ensemble Pianos Market
Musical Instruments
Violin Market
Musical Instruments
Kids Musical Instrument Market
Musical Instruments
Smart Musical Instrument Market
Musical Instruments
Classical Guitar Market
Musical Instruments
Guitar Market
Musical Instruments
Electric Violin Market
Musical Instruments
Bass Guitar Market
Musical Instruments
Drum Sets Market
Musical Instruments
Electronic Musical Instruments Market