
 Global Piano Market | 2026-2036
Global Piano Market Size, Share, and Industry Trends Forecast 2026-2036
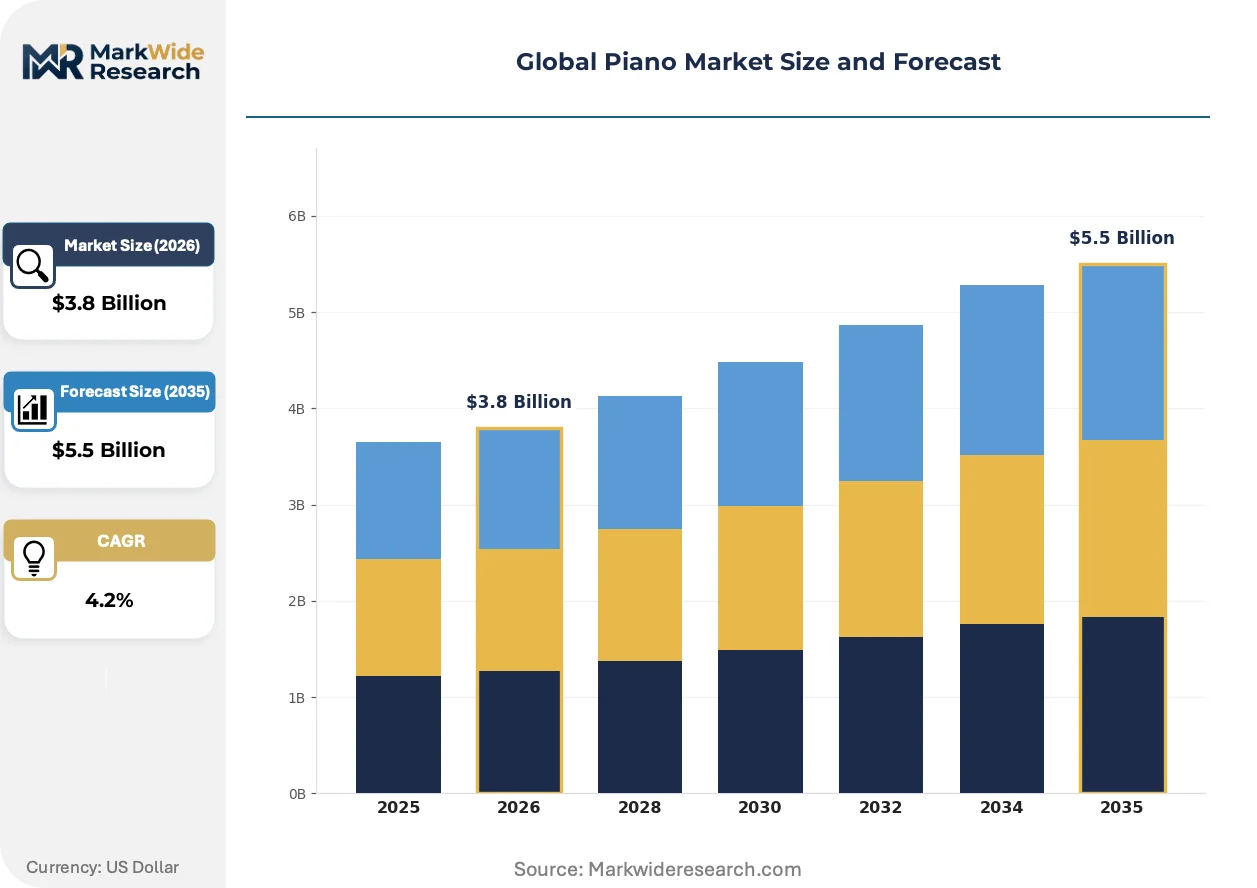
Global Piano Market Outlook
Buyer concentration among musical institutions is realigning procurement patterns across the value chain. Yamaha Corporation leverages its vertical integration into precision action manufacturing to sustain premium positioning. Guangzhou Pearl River Piano Group anchors volume supply through dominant domestic distribution networks. Steinway & Sons differentiates via handcrafted heritage positioning that commands pricing power in conservatory and orchestral channels.
A piano is a stringed percussion instrument employing felt-covered hammers striking steel wires tensioned over a cast-iron frame, with soundboards typically of spruce or maple that amplify vibrations through acoustic resonance. Grand and upright acoustic variants retain margin concentration in institutional and professional segments where tonal complexity and touch response justify sustained investment. Digital and hybrid pianos are capturing growth in home user and amateur player segments as key action simulation and sampling technologies narrow the performance gap with acoustic counterparts.
The EPA regulates volatile organic compound emissions from piano finishes and adhesives in the United States, while REACH compliance governs chemical substances in European manufacturing inputs. China's GB standards and MIIT directives shape domestic production specifications for both export and local consumption. Japan's METI oversees energy efficiency labeling that affects digital piano import requirements. Stakeholders must monitor evolving cross-border certification harmonization and raw material substitution timelines to calibrate sourcing and product development commitments.
Market Dynamics
The piano market is undergoing a fundamental realignment as digital hybrid action systems compress the performance gap with acoustic instruments, forcing legacy manufacturers to recalibrate R&D allocation between heritage craftsmanship and sensor-based haptic feedback engineering.
Growth Catalysts
- East Asian music education procurement:Government-funded conservatory expansion in China and South Korea is accelerating institutional instrument acquisition through dedicated cultural infrastructure budgets.
- REACH chemical compliance substitution:European finish and adhesive reformulation mandates are driving investment in low-VOC coating technologies that transfer across export markets.
- Hybrid action sampling advances:Optical key sensors and physical modeling algorithms are narrowing latency differentials that previously constrained digital piano adoption in pedagogy settings.
Market Restraints
- Spruce soundboard supply concentration:Premium resonant wood sourcing depends on Baltic and Alpine forestry regions with extended harvest cycles and climate vulnerability.
- Cast-iron frame logistics costs:Foundry capacity for piano-specific plate casting clusters in specific industrial zones, creating freight cost exposure for distant assembly operations.
- Acoustic piano space requirements:Urban dwelling downsizing in dense metropolitan markets constrains upright and grand instrument placement feasibility.
Strategic Opportunities
- Southeast Asia amateur player base:Vietnam, Indonesia, and Thailand exhibit rising disposable income intersecting with underdeveloped dealer network penetration.
- Rental-to-own channel development:Subscription-based instrument access models address upfront capital barriers for uncertain commitment household segments.
- ISO 17025 calibration services:Third-party touch-weight and pitch standardization certification creates recurring revenue attachment for institutional fleet maintenance.
Industry Challenges
- Action regulation technician scarcity:Master craftsmen capable of precision hammer voicing and damper adjustment are retiring faster than apprenticeship pipelines replenish.
- Cross-border certification harmonization:Divergent EPA, REACH, and GB standard testing protocols extend product launch timelines and duplicate validation expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Piano Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grand Piano, Upright Piano, Digital Piano, Hybrid Piano End User: Musical Institutions, Professional Musicians, Amateur Players, Home Users Price Tier: Luxury, Mid-Range, Entry-Level, Budget Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Auctions |
| Companies Covered | Roland Corporation, C. Bechstein, Yamaha Corporation, Blüthner, Guangzhou Pearl River Piano Group, Steinway & Sons, Bösendorfer, Samick Music Corporation, Kawai Musical Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Piano Market Strategic Shifts
Digital-acoustic convergence is dismantling traditional segment boundaries. Manufacturers now compete on haptic fidelity rather than sound source taxonomy, while regulatory chemical frameworks and procurement centralization reshape how instruments reach end users.
Optical hammer sensors paired with multi-velocity sampling engines is rewriting competitive benchmarks for touch response authenticity. Conservatory procurement committees in China and Germany are now evaluating hybrid platforms for secondary practice room deployment. The technology is compressing the addressable market for entry-level acoustic uprights while expanding total instrument penetration.
REACH Annex XVII restrictions on formaldehyde-emitting composite wood products are forcing European and export-oriented Asian manufacturers to requalify cabinet and soundboard material suppliers. Finish houses in Italy and Japan are accelerating water-based lacquer formulation transitions. Acoustic piano production lines with legacy solvent-based processes face capital-intensive retooling timelines.
Institutional buyers in China's tier-one cities are consolidating procurement through centralized cultural bureau tendering rather than individual conservatory purchasing authority. This centralization favors vendors with documented GB standard compliance and domestic service network density. Dealer margins compress as direct manufacturer relationships with municipal procurement offices displace traditional distribution hierarchies.
Global Piano Market Segmentation
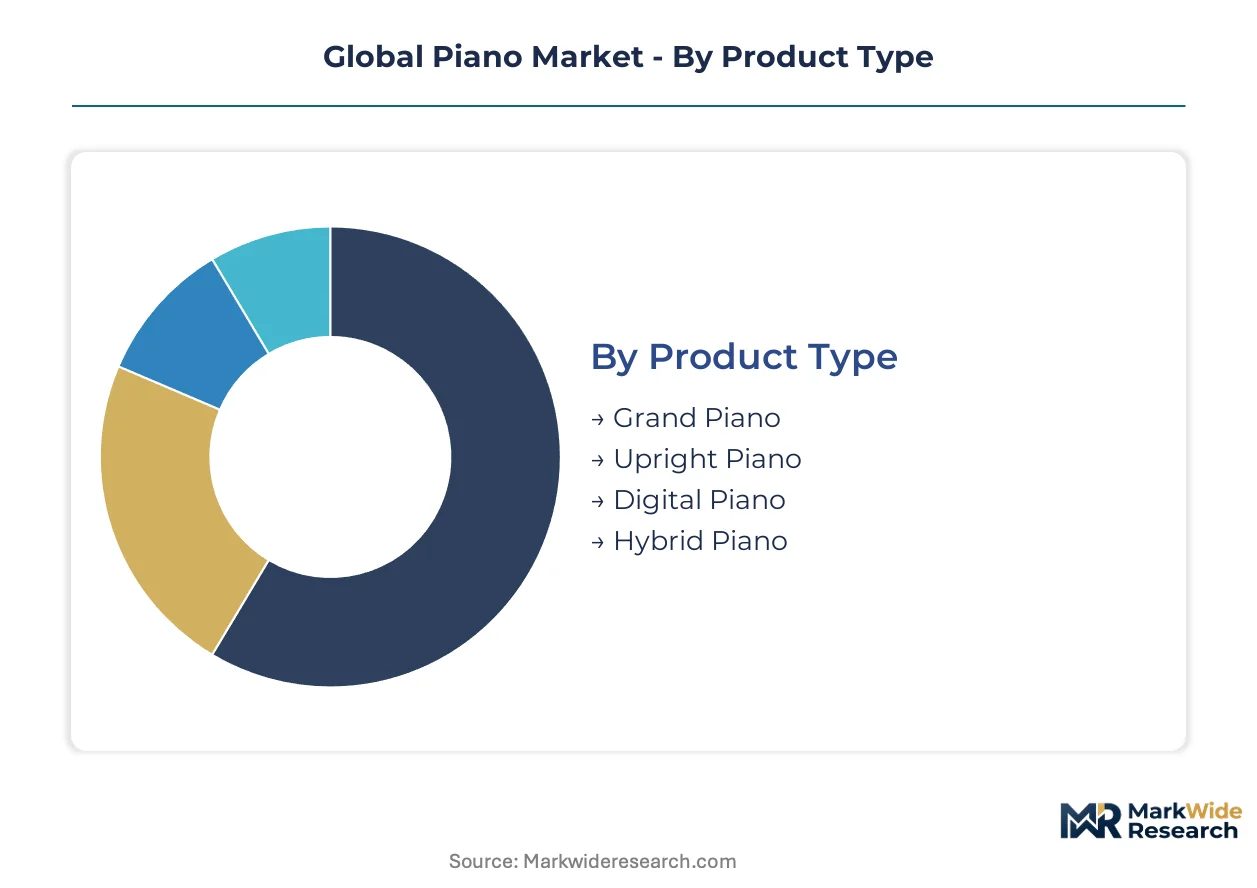
Piano market segmentation reflects fundamental tensions between acoustic heritage and digital innovation, with procurement patterns diverging sharply across institutional, professional, and household buyer archetypes. Manufacturers calibrate product portfolios across these axes to capture margin concentration in conservatory channels while penetrating volume opportunities in amateur and home segments.
Product Type:
Acoustic-digital hybridization is redrawing competitive boundaries as sensor fidelity and physical modeling narrow performance differentials that once separated sound generation methodologies.
- Grand Piano:Horizontal string frame with extended soundboard surface area delivers superior tonal projection and sustain characteristics demanded by concert venues and orchestral settings. Procurement concentrates in Germany's conservatory network and China's municipal cultural bureau tendering, where institutional budgets prioritize performance specifications over spatial constraints.
- Upright Piano:Vertical string orientation compresses footprint requirements while maintaining acoustic action mechanisms, occupying the institutional practice room and dedicated home studio segments. Demand clusters in East Asian urban districts where dwelling dimensions constrain grand instrument feasibility without sacrificing touch response authenticity for pedagogy applications.
- Digital Piano:Sample-based or modeled sound engines paired with weighted key actions serve price-sensitive household segments and portable performance contexts. Japan's METI energy efficiency labeling shapes import specifications for units entering that market.
- Hybrid Piano:Optical sensors capturing acoustic hammer mechanics combined with high-resolution sampling engines bridge categories for conservatory secondary room deployment. China's tier-one city procurement committees are evaluating these platforms for expanded fleet standardization.
Upright pianos lead on scale; hybrid pianos lead on momentum.
End User:
Buyer sophistication and procurement authority determine channel access, technical specification requirements, and service attachment expectations across the value chain.
- Musical Institutions:Conservatories, orchestral organizations, and educational facilities with centralized purchasing authority demand fleet standardization, documented calibration protocols, and domestic service network density. China's cultural infrastructure budgets are accelerating acquisition through municipal tendering consolidation.
- Professional Musicians:Recording studio operators, touring performers, and commissioned composers prioritize tonal complexity and touch response precision with tolerance for premium positioning. This segment drives specification adoption that subsequently diffuses into institutional procurement criteria.
- Amateur Players:Dedicated hobbyists with sustained practice commitment but unverified long-term persistence represent the rental-to-own channel opportunity. Southeast Asian markets exhibit rising disposable income intersection with underdeveloped dealer penetration.
- Home Users:Discretionary purchasers seeking furniture-grade aesthetics alongside recreational functionality populate entry-level digital and economy upright segments. Urban dwelling downsizing in dense metropolitan markets constrains acoustic instrument placement feasibility.
Musical institutions command procurement volume; amateur players offer expansion trajectory.
Price Tier:
Cost positioning aligns with craftsmanship intensity, material specification, and brand heritage authentication mechanisms rather than purely functional performance metrics.
- Luxury:Handcrafted heritage manufacturing with documented provenance, limited production volumes, and bespoke customization options serve conservatory and orchestral principal instrument requirements. Steinway's Hamburg and New York facilities anchor this tier through vertical control over precision action manufacturing.
- Mid-Range:Factory-produced instruments with standardized specifications and certified component sourcing balance performance accessibility with quality assurance for institutional fleet deployment. Yamaha's integrated production network dominates this tier through scale economies in precision manufacturing.
- Entry-Level:Simplified action designs, composite material substitutions, and streamlined finish protocols target household commitment uncertainty with accessible price points. Guangzhou Pearl River Piano Group anchors volume supply through dominant domestic distribution networks in China.
- Budget:Digital and entry-level acoustic instruments with minimized service attachment and compressed margin structures serve trial purchaser segments with high attrition probability. Online retail channels displace traditional dealer relationships in this tier.
Mid-range pricing captures institutional procurement volume; luxury tier maintains margin concentration.
Distribution Channel:
Channel selection determines service attachment capability, buyer education depth, and manufacturer margin retention across segment tiers.
- Online Retail:E-commerce platforms with logistics integration serve digital piano and entry-level acoustic segments where physical inspection and setup service requirements remain minimal. This channel is displacing traditional dealer hierarchies in budget tier penetration.
- Specialty Stores:Authorized dealer networks with technician staffing and showroom demonstration capacity dominate acoustic instrument distribution for institutional and professional segments. China's tier-one cities concentrate premium dealer presence alongside municipal procurement office relationships.
- Direct Sales:Manufacturer-managed relationships with conservatory procurement committees and municipal cultural bureaus compress traditional distribution margins while ensuring specification compliance documentation. Centralized tendering in China's cultural infrastructure expansion favors this channel.
- Auctions:Secondary market transactions for vintage and estate instruments serve collector segments and institutional fleet renewal programs with depreciation recovery mechanisms. Steinway heritage positioning commands pricing power in this channel.
Specialty stores retain institutional channel dominance; online retail climbs fastest in household segment penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Master craftsmen clusters in Hamburg, Hamamatsu, and Guangzhou anchor acoustic piano manufacturing heritage, while digital engineering talent concentrates in Tokyo and Seoul. These workforce geographies shape competitive positioning across instrument categories.
China
Municipal cultural bureau tendering in Beijing, Shanghai, and Guangzhou is consolidating institutional procurement authority. GB standards and MIIT directives govern both domestic production specifications and export certification requirements. The Pearl River Delta manufacturing corridor supplies volume production for entry-level and mid-range segments.
Germany
Conservatory network procurement in Berlin, Leipzig, and Munich sustains demand for handcrafted grand instruments. REACH compliance and ECHA chemical substance regulations mandate finish and adhesive reformulation across European production. The Hamburg-Braunschweig corridor hosts precision action manufacturing heritage.
Japan
METI energy efficiency labeling shapes digital piano import specifications and domestic product development priorities. Hamamatsu's integrated manufacturing ecosystem combines precision component fabrication with sensor-based haptic feedback engineering. Kawai and Yamaha anchor hybrid technology advancement from this cluster.
United States
EPA volatile organic compound regulations govern piano finish and adhesive emissions in domestic manufacturing and import compliance. New York and Queens maintain Steinway's handcrafted heritage positioning for conservatory and orchestral channels. Institutional procurement concentrates in East Coast and Midwest university networks.
South Korea
Government-funded conservatory expansion in Seoul and Busan accelerates institutional instrument acquisition through dedicated cultural infrastructure budgets. MFDS and national standards bodies shape product safety and import requirements. Digital piano adoption in pedagogy settings outpaces acoustic instrument placement in dense metropolitan districts.
Global Piano Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across acoustic and digital segments. The market structure tiers into heritage handcrafted manufacturers, integrated precision engineering groups, and volume-oriented domestic suppliers. Three archetypes dominate: vertically integrated action manufacturers, hybrid technology specialists, and scale-driven export platforms. Competitive moves concentrate on sensor fidelity licensing and municipal procurement relationship development.
Within the heritage handcrafted tier, Steinway & Sons and C. Bechstein exemplify premium positioning through documented provenance and limited production volumes. Yamaha Corporation and Roland Corporation anchor integrated engineering capabilities spanning acoustic action mechanics and digital haptic systems. Guangzhou Pearl River Piano Group represents scale-driven supply concentration through dominant domestic distribution networks in China.
| Leading Market Players |
|---|
| Roland Corporation |
| C. Bechstein |
| Yamaha Corporation |
| Blüthner |
| Guangzhou Pearl River Piano Group |
| Steinway & Sons |
| Bösendorfer |
| Samick Music Corporation |
| Kawai Musical Instruments |
| Others |
Value Chain & Pricing Dynamics
REACH Annex XVII chemical restrictions gate qualified supply for European and export-oriented manufacturers, compressing margins for solvent-dependent finish houses while elevating pricing power for water-based lacquer certified suppliers serving conservatory procurement channels.
Pricing Analysis
Bundled calibration and maintenance contracts separate institutional pricing from stripped-down household transactions. Three-tier pricing structure across premium handcrafted, mid-range factory-produced, and economy digital tiers reflects craftsmanship intensity and certification documentation depth. Price differentiation hinges on GB standard compliance documentation and domestic service network density for Chinese municipal tendering. Cost compression in entry-level acoustics intensifies as digital hybrid platforms capture pedagogy budgets. Amateur rental-to-own segments exhibit highest price sensitivity; luxury heritage manufacturers command lowest elasticity through provenance authentication.
Supply Chain Analysis
Single-source vulnerability sits with Baltic and Alpine spruce resonant wood harvest regions facing extended rotation cycles and climate stress. Foundry capacity for piano-specific cast-iron frame casting clusters in Germany, Japan, and China's Pearl River Delta. Action mechanism production draws from Hamamatsu, Hamburg, and Guangzhou precision manufacturing corridors. Tariff exposure on finished instrument imports into key procurement markets compounds logistics cost pressure from distant assembly operations. Distribution runs through municipal cultural bureau direct relationships for institutional volume, specialty dealer networks for acoustic demonstration requirements, and e-commerce platforms for digital household penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH chemical phase-outs and China's GB standard harmonization are accelerating fleet replacement demand across institutional procurement channels.
For Market Incumbents: Anchor hybrid technology licensing partnerships to defend against pure-digital entrants narrowing the performance gap in conservatory secondary rooms. Deepen backward integration into optical sensor component manufacturing to secure supply priority as Hamamatsu production corridors face capacity constraints. Invest in ISO 17025 calibration service infrastructure to capture recurring revenue attachment from China's centralized municipal tendering consolidation.
For New Entrants and Emerging Players: REACH-driven finish reformulation in Europe opens a window for water-based lacquer specialists to penetrate supply chains of heritage manufacturers facing capital-intensive retooling timelines. Target Vietnam, Indonesia, and Thailand amateur segments where rising disposable income intersects with underdeveloped dealer network penetration. Pursue rental-to-own channel development with subscription-based instrument access models that address upfront capital barriers for uncertain commitment households.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale acoustic manufacturers lacking hybrid technology pipelines or GB standard certification documentation for Chinese institutional access. Long-term viability favors vertically integrated groups controlling precision action manufacturing and domestic service network density. Watch for inflection signals in China's municipal cultural infrastructure budget allocations tier-one versus tier-two city distribution.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Technology Licensing | Optical sensor partnerships with Hamamatsu engineering clusters accelerate conservatory secondary room penetration. |
| Water-Based Finish Transition | REACH-compliant coating investments unlock European institutional procurement and export market access. |
| Municipal Procurement Relationship Development | Direct cultural bureau engagement in Beijing and Shanghai compresses traditional distribution margin extraction. |
| Calibration Service Infrastructure Buildout | ISO 17025 certification capabilities create recurring revenue attachment from institutional fleet maintenance contracts. |
| Southeast Asia Dealer Network Expansion | Vietnam and Indonesia distribution penetration captures rising amateur disposable income before incumbent saturation. |
Study Parameters
Bottom-up institutional and household demand modeling reconciled against top-down manufacturing capacity tracking forms the analytical core. Primary interviews with conservatory procurement directors, municipal cultural bureau officials, piano manufacturer R&D heads, specialty dealer network operators, and master action regulation technicians informed demand segmentation and technology adoption timelines. Secondary validation drew from MIIT production statistics, EPA import compliance filings, REACH substance restriction updates, and customs trade data for instrument and component flows. Triangulation across these sources calibrated volume and value estimates.
Input-output matrices mapped action mechanism production, soundboard material sourcing, and finish chemical supply against downstream segment demand across the projection horizon. Segmentation dimensions modeled include product type, end-user archetype, price tier positioning, and distribution channel structure. CAGRs derived from fitted growth curves applied to base-year observations, adjusted for regulatory milestone impacts and technology substitution elasticities. Forecast inputs incorporated municipal cultural infrastructure budget trajectories, hybrid platform adoption curves in pedagogy settings, and spruce harvest cycle constraints.
Revisions become necessary when REACH chemical substitution timelines accelerate, China's GB standard certification requirements shift, or hybrid platform performance benchmarks reset competitive thresholds. Forecasts reflect documented assumptions regarding institutional procurement centralization rates and digital-acoustic convergence velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Musical Instruments
Drum Sets Market
Musical Instruments
Violin Market
Musical Instruments
Smart Musical Instrument Market
Musical Instruments
Classical Guitar Market
Musical Instruments
Digital Ensemble Pianos Market
Musical Instruments
Electric Violin Market
Musical Instruments
Digital Piano Market
Musical Instruments
Kids Musical Instrument Market
Musical Instruments
Bass Guitar Market
Musical Instruments
Guitar Market
Musical Instruments
Electric Guitar Market
Musical Instruments
Electronic Musical Instruments Market
Musical Instruments
Woodwind Instruments Market