
 Violin Market | 2026-2036
Violin Market Size, Share, and Industry Trends Forecast 2026-2036
Violin Market Outlook
Aftermarket service revenue from restoration and authentication is narrowing as luthier labor pools shrink across Europe. Yamaha leverages its industrial manufacturing scale to produce consistent student-grade instruments at accessible price points. Florian Leonhard Fine Violins sustains premium positioning through London-based expertise in rare Italian instrument sourcing and valuation.
A violin is a four-stringed bowed instrument with a wooden body, typically constructed from maple and spruce, whose soundpost and bass-bar assembly transmits string vibrations to produce resonant tones across a three-and-a-half-octave range, serving concert performance, education, and recording applications. Acoustic violins dominate value pools among professional buyers, while electric violins capture growth from amplified genres and home recording setups. Carbon fiber materials extend instrument durability for touring musicians and outdoor performance contexts.
CITES documentation requirements for pernambuco and Brazilian rosewood shape cross-border trade compliance costs for dealers and collectors. REACH substance restrictions in the European Union limit certain varnish formulations and adhesive chemistries used in workshop finishing processes. Stakeholders must monitor evolving certification burdens and raw material substitution pathways.
Market Dynamics
CITES Appendix II listing of pernambuco wood since 2007 is tightening bow supply chains, forcing orchestras and dealers to absorb documentation costs and seek certified alternatives while vintage instrument authentication standards harden.
Growth Catalysts
- REACH substance restrictions:EU varnish chemistry rules are accelerating adoption of plant-based finishing oils among luthiers in Mittenwald and Markneukirchen workshops.
- Carbon fiber composite technology:Touring musicians are adopting reinforced fingerboards and tailpieces that withstand humidity swings across outdoor festival circuits.
- China conservatory feeder cities:Digital performance formats on Bilibili and Douyin are amplifying electric violin enrollment among students in Shenzhen and Chengdu.
Market Restraints
- Pernambuco supply concentration:Brazilian federal licensing for Pau-Brasil harvesting limits legally certified bow wood to a handful of authorized exporters.
- Luthier labor scarcity:European apprenticeship programs in Cremona and Mirecourt are graduating fewer trained craftspeople than retirement rates demand.
- Acoustic-electric substitution:Home recording setups using software-modeled string tones reduce entry-level acoustic purchases among amateur players.
Strategic Opportunities
- Blockchain provenance tracking:Italian instrument dealers are piloting distributed ledger systems to streamline Stradivari and Guarneri authentication for auction houses.
- India's emerging classical scene:Western violin pedagogy is expanding through Bangalore and Mumbai conservatories seeking European-trained faculty.
- EU Green Deal procurement incentives:German state orchestras now prioritize FSC-certified maple and spruce in competitive instrument tenders.
Industry Challenges
- Multi-jurisdictional CITES compliance:Cross-border shipments of pre-Convention instruments require species-specific permits that delay auction timelines by months.
- Legacy workshop digitization:Small Italian and French ateliers lack ERP systems to manage inventory and customer relationships at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Violin Market |
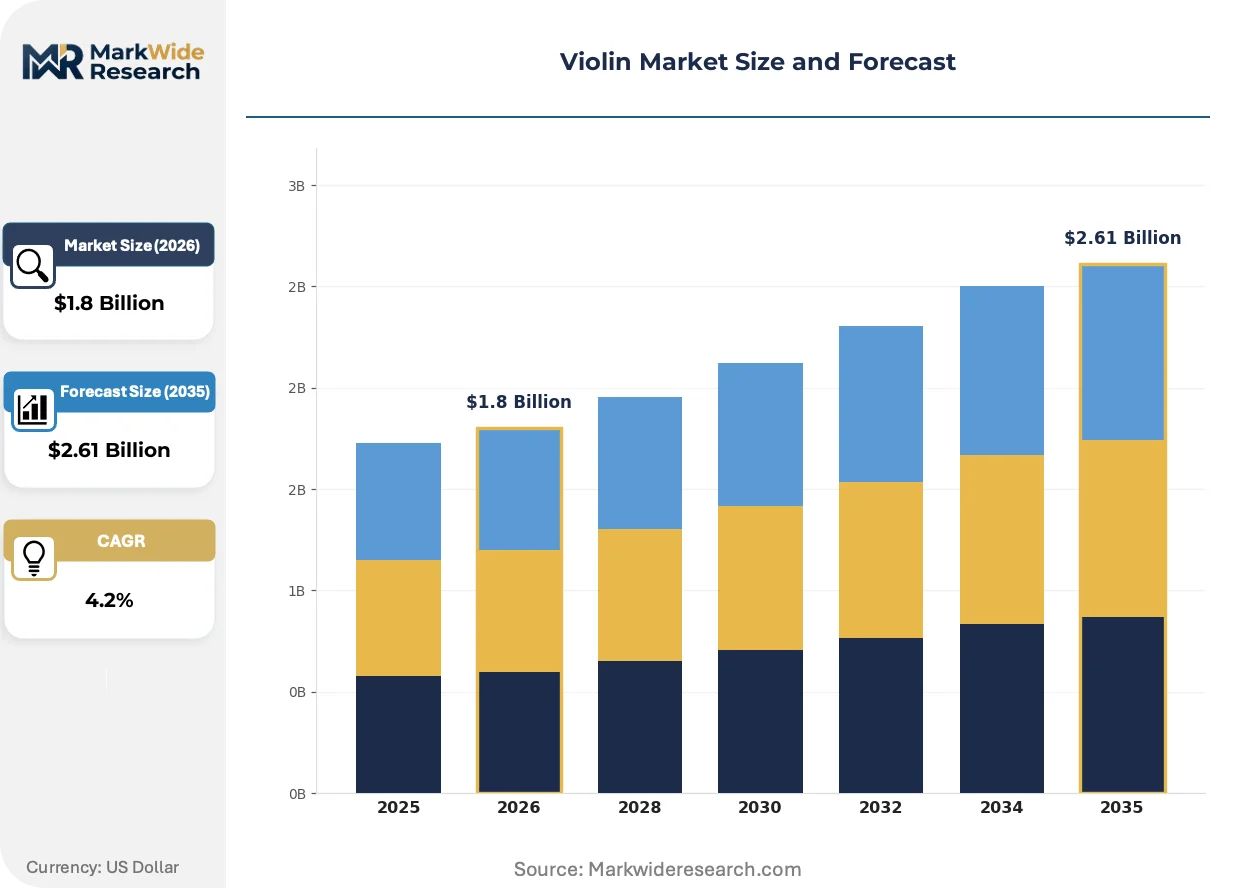
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acoustic Violin, Electric Violin, Silent Violin, Baroque Violin End User: Students, Hobbyists, Professional Musicians, Orchestras Distribution Channel: Online Retail, Specialty Stores, Concert Halls, Music Schools Material: Wood, Composite, Carbon Fiber, Plastic |
| Companies Covered | Stefan-Peter Greiner, Gregg Alf, Yamaha, Florian Leonhard Fine Violins, Elina Kaljunen, Stentor, Marc Paquin, Rudolf Pilsel, D'Addario, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Violin Market Strategic Shifts
Material science and digital distribution are compressing traditional craft cycles while regulatory documentation becomes a competitive differentiator among dealers serving institutional buyers.
Carbon fiber bow construction is migrating from niche touring applications toward student-grade price points. French bow makers in Paris and Lyon are licensing filament-winding techniques from aerospace suppliers. This shift is compressing the premium-synthetic price gap that has defined bow market segmentation for decades.
REACH substance restrictions on volatile organic compounds are forcing varnish reformulation across EU-based workshops. German luthiers in Bubenreuth are testing linseed oil and pine resin alternatives to traditional alcohol-based spirit varnishes. Acoustic finish specialists face the steepest adaptation costs as they balance tonal transparency against drying-time consistency.
Direct-to-consumer video commerce is displacing dealer showrooms for intermediate instrument purchases. Chinese manufacturers now livestream factory tours on Douyin to conservatory students bypassing traditional import distributors. This channel shift concentrates price discovery power with manufacturers while eroding regional dealer margins in North American and European markets.
Violin Market Segmentation
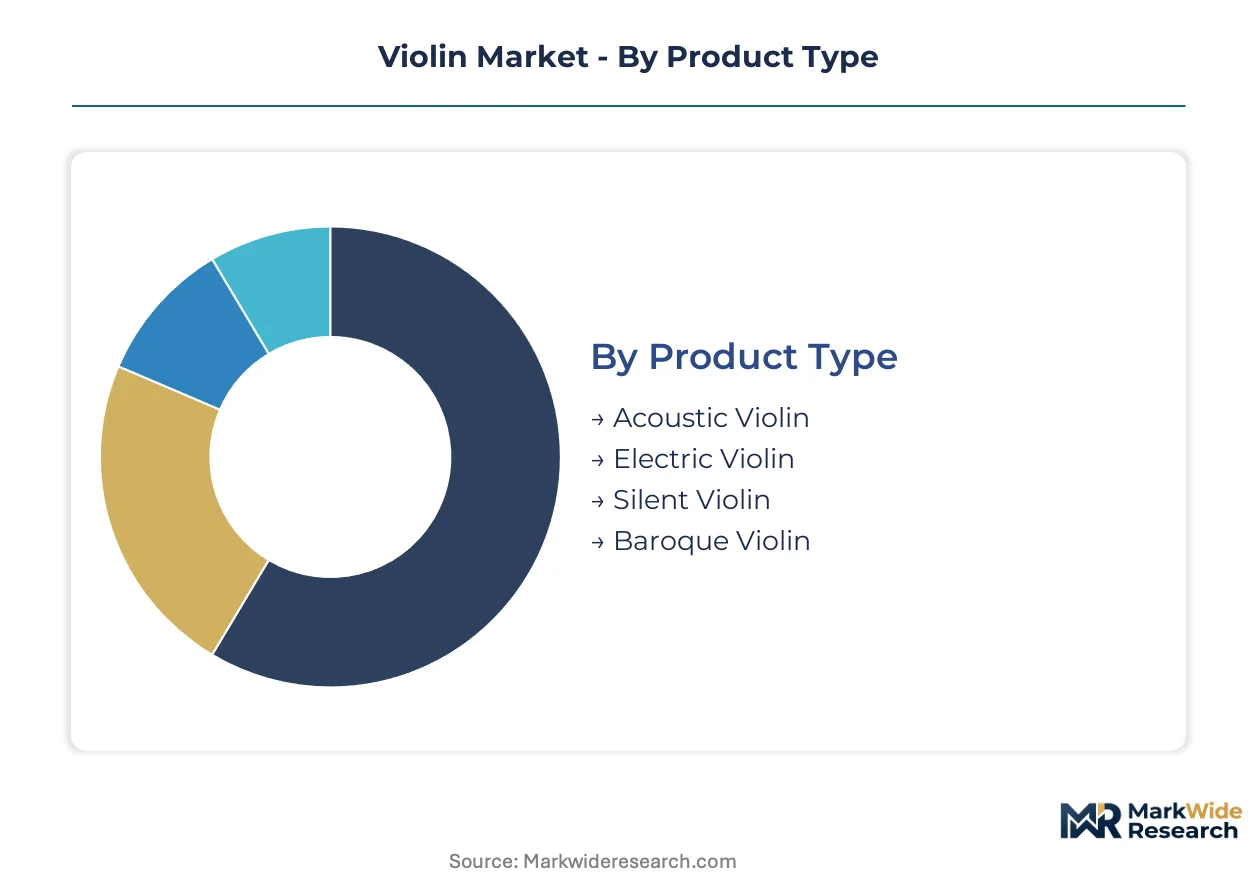
Violin market segmentation reveals divergent value capture across acoustic craftsmanship and electrified performance formats. Professional orchestras and conservatory students drive fundamentally different procurement patterns, while material science is fragmenting traditional wood-dominant supply chains.
Product Type:
The use-case spectrum spans unamplified concert halls to digitally processed home studios, with each format demanding distinct acoustic engineering and price positioning.
- Acoustic Violin:Traditional spruce-top and maple-back construction with hand-applied oil or spirit varnishes defines tonal character for orchestral and chamber repertoire. German state orchestras in Berlin and Munich anchor procurement volume, though CITES documentation burdens for pernambuco bow pairings extend procurement cycles.
- Electric Violin:Solid-body designs with piezoelectric or magnetic pickups enable amplified performance across jazz, rock, and electronic genres. Shenzhen and Chengdu conservatories are driving enrollment surges as Bilibili and Douyin content creators normalize digital performance formats.
- Silent Violin:Headphone-enabled practice instruments with resin bodies and built-in preamps serve apartment-dwelling students in dense Asian cities.
- Baroque Violin:Gut-string setups with shorter fingerboards and flatter bridges serve period-instrument ensembles in London and Amsterdam.
The dominant share belongs to Acoustic Violin, while Electric Violin is closing the gap fastest.
End User:
Customer maturity tiers separate price-sensitive volume purchasers from bespoke commission clients.
- Students:Entry-level fractional and full-size instruments from Chinese industrial manufacturers supply mass education markets. Yamaha's Bubenreuth facility ships consistent student-grade units to European and North American school districts.
- Professional Musicians:Soloists and chamber players commission Cremona and Mirecourt ateliers for hand-carved instruments with documented provenance. Italian workshops face multi-year backlogs as luthier retirement rates outpace apprenticeship completions.
- Hobbyists:Adult learners in Japan and South Korea purchase mid-range factory instruments through direct-to-consumer channels.
- Orchestras:Institutional buyers in Vienna and Leipzig negotiate bulk tenders specifying FSC-certified tonewoods under EU Green Deal procurement guidelines.
Students generate the highest unit volumes, yet Professional Musicians command the steepest price premiums per transaction.
Distribution Channel:
Channel economics are compressing as manufacturer livestreaming displaces traditional dealer intermediaries.
- Specialty Stores:London and Paris dealers maintain authentication expertise for vintage Italian instruments, though foot traffic is thinning.
- Online Retail:Chinese manufacturers now broadcast factory-floor violin construction on Douyin, enabling direct sales to conservatory students bypassing import distributors.
- Music Schools:Institutional procurement offices in Bangalore and Mumbai negotiate volume discounts for Western pedagogy programs.
- Concert Halls:Limited on-site retail serves touring musician emergency replacement needs.
Specialty Stores retain the premium authentication function, yet Online Retail is expanding its share most aggressively.
Material:
Raw material substitution is accelerating as regulatory restrictions and touring durability requirements reshape workshop practices.
- Wood:Alpine spruce from Bavarian and Bohemian forests and Balkan maple remain tonewood standards, though FSC certification is becoming mandatory for German public procurement.
- Carbon Fiber:Filament-wound composite construction delivers humidity-stable performance for outdoor festival circuits and airline cargo holds. French bow makers in Lyon are licensing aerospace manufacturing techniques to compress premium-synthetic price gaps.
- Composite:Glass-fiber and resin blends serve student-grade durability at intermediate price points.
- Plastic:Injection-molded ABS bodies target absolute entry-level price floors in emerging markets.
Wood maintains the prestige anchor, though Carbon Fiber is gaining functional adoption fastest among touring professionals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European orchestras prize acoustic craftsmanship and CITES-certified bow pairings, while Asian conservatories drive electric instrument demand through digital performance platforms. This consumption-mix differential separates procurement patterns across mature and emerging markets.
Germany
State orchestras in Berlin and Munich anchor acoustic violin procurement volume under EU Green Deal guidelines mandating FSC-certified tonewoods. REACH substance restrictions from ECHA accelerate plant-based varnish adoption in Mittenwald and Markneukirchen workshops. Bubenreuth industrial clusters host Yamaha's student-grade manufacturing for European school districts.
China
Shenzhen and Chengdu conservatories drive electric violin enrollment surges as Bilibili and Douyin content creators normalize amplified performance formats. The country's national forestry regulator tightens documentation for pernambuco bow imports under CITES enforcement protocols. Yangtze River Delta factories livestream construction processes to bypass traditional import distributors.
United States
University music programs and community orchestras sustain mid-range acoustic demand amid tightening EPA oversight of workshop solvent emissions. CITES documentation requirements from the Fish and Wildlife Service delay vintage instrument auction timelines by months. New York and Boston dealer networks maintain authentication expertise for Italian instrument provenance.
Italy
Cremona and Mirecourt-trained luthiers face multi-year backlogs as apprenticeship graduation rates lag retirement waves. EU Green Deal procurement incentives from Brussels shape public tender specifications for sustainable tonewood sourcing. Lombardy workshops pilot blockchain distributed ledger systems to streamline Stradivari authentication for auction houses.
India
Bangalore and Mumbai conservatories expand Western violin pedagogy programs seeking European-trained faculty for institutional appointments. The country's national standards body issues certification requirements for imported instrument quality verification. Maharashtra music schools negotiate volume discounts for student-grade fractional instruments through direct manufacturer relationships.
Violin Market Competitive Environment
Capability concentration sits with heritage ateliers commanding authentication premiums; scale advantage sits with industrial manufacturers producing consistent student-grade units. The market structures around three tiers: hand-craft workshops with documented provenance expertise, automated factories serving education markets, and hybrid specialists blending traditional finishing with modern materials. Dominant competitive moves include direct-to-consumer video commerce displacement of dealer intermediaries and carbon fiber composite licensing from aerospace suppliers.
Within the heritage atelier tier, Stefan-Peter Greiner and Florian Leonhard Fine Violins exemplify premium positioning through rare Italian instrument sourcing and London-based valuation expertise. Yamaha Corporation anchors the industrial manufacturing vector with consistent student-grade production at accessible price points. Elina Kaljunen represents the emerging specialist archetype bridging traditional craft training with contemporary performance format adaptation.
| Leading Market Players |
|---|
| Stefan-Peter Greiner |
| Gregg Alf |
| Yamaha |
| Florian Leonhard Fine Violins |
| Elina Kaljunen |
| Stentor |
| Marc Paquin |
| Rudolf Pilsel |
| D'Addario |
| Others |
Value Chain & Pricing Dynamics
CITES documentation chokepoints for pernambuco bow wood determine both the premium commanded by certified vintage instruments and the geographic routing of cross-border dealer networks. This regulatory friction compresses margins on mid-tier acoustic sales while amplifying price spreads between authenticated Italian ateliers and industrial student-grade manufacturers.
Pricing Analysis
Long-term offtake contracts between German state orchestras and Bavarian tonewood suppliers anchor premium acoustic pricing, while spot-market transactions dominate carbon fiber bow imports from French aerospace licensors. Price differentiation hinges on FSC certification tier and documented luthier provenance. Cost compression in student-grade segments intensifies as Chinese manufacturers livestream factory-floor sales directly to conservatory buyers. Hobbyists in Japan and South Korea exhibit the highest price sensitivity, whereas soloists commissioning Cremona workshops demonstrate minimal elasticity.
Supply Chain Analysis
Tariff exposure between Brazil and EU member states dominates raw material risk profiles for bow makers dependent on licensed Pau-Brasil harvesting. Alpine spruce from Bavarian forests, Balkan maple, and carbon fiber filament from Lyon aerospace suppliers constitute the core input base. Single-source vulnerability concentrates in Brazilian federal licensing for pernambuco export quotas. Distribution runs through London and Paris dealer networks for vintage authentication, while Shenzhen factories bypass intermediaries via Douyin livestream channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon fiber composite licensing from aerospace suppliers is disrupting traditional wood-dominant craft cycles, creating asymmetric growth windows for material-science specialists and heritage ateliers alike.
For Market Incumbents: Pre-empt luthier labor scarcity by underwriting Cremona and Mirecourt apprenticeship endowments before retirement waves erode workshop capacity. Secure backward integration into FSC-certified Bavarian tonewood stands to defend margin position against EU Green Deal procurement mandates. For New Entrants and Emerging Players: Build out direct-to-consumer video commerce infrastructure targeting Bangalore and Mumbai conservatory students before established dealers consolidate institutional relationships. India's emerging Western pedagogy programs represent the most penetrable geography, with European-trained faculty recruitment as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a materials-transition phase that favors hybrid specialists blending traditional craft training with carbon fiber manufacturing licenses. Long-term viability over the coming decade rests on capturing authentication expertise and scalable composite production under single ownership. Watch CITES enforcement stringency as the signal for vintage instrument liquidity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Fiber Licensing Agreement | French bow makers in Lyon gain humidity-stable construction techniques from aerospace filament-winding suppliers. |
| Blockchain Provenance Pilot | Lombardy workshops streamline Stradivari authentication for London and Paris auction houses. |
| Direct-to-Consumer Livestream Launch | Yangtze River Delta manufacturers bypass import distributors to reach Shenzhen conservatory students. |
| FSC-Certified Tonewood Backward Integration | German state orchestras secure compliant maple and spruce supply under EU Green Deal tender rules. |
| Apprenticeship Endowment Program | Cremona and Mirecourt ateliers counter luthier retirement waves with structured craft training pipelines. |
Study Parameters
A standing panel of Cremona luthiers, Paris bow makers, German orchestra procurement officers, and Chinese factory operations managers provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with these stakeholder roles against secondary validation from CITES trade databases, ECHA REACH substance filings, EU public procurement registries, and conservatory enrollment records. Bottom-up instrument shipment tallies and top-down orchestral budget allocations were triangulated to anchor volume estimates.
Scenario-bracketing around CITES enforcement intensity and carbon fiber adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user maturity tier, distribution channel format, and material composition. CAGRs were derived from elasticity-adjusted demand curves and replacement-cycle analysis. Forecast inputs incorporated pernambuco licensing quotas from Brazilian federal regulators and electric violin enrollment trajectories in Chengdu and Shenzhen feeder cities.
Stress conditions across CITES documentation delays, luthier graduation rates, and livestream commerce penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory stability and materials substitution pathways. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Musical Instruments
Classical Guitar Market
Musical Instruments
Drum Sets Market
Musical Instruments
Bass Guitar Market
Musical Instruments
Digital Ensemble Pianos Market
Musical Instruments
Kids Musical Instrument Market
Musical Instruments
Electronic Musical Instruments Market
Musical Instruments
Electric Guitar Market
Musical Instruments
Global Piano Market
Musical Instruments
Electric Violin Market
Musical Instruments
Smart Musical Instrument Market
Musical Instruments
Digital Piano Market
Musical Instruments
Guitar Market
Musical Instruments
Woodwind Instruments Market