
 Digital Ensemble Pianos Market | 2026-2036
Digital Ensemble Pianos Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Ensemble Pianos Market Insights
China is tilting toward domestic digital instrument manufacturing with new assembly corridors in Guangdong and Zhejiang. Yamaha Corporation leverages its vertical control over keybed fabrication and tone-generation chip design. Roland sustains competitive pressure through proprietary SuperNATURAL modeling architecture. Kawai anchors premium positioning with wooden-key actions and long-standing conservatory relationships.
A digital ensemble piano is an electronic keyboard instrument that replicates acoustic piano timbre and touch response through sampled recordings or physical modeling algorithms, typically featuring 88 weighted keys with graded hammer action and polyphony counts exceeding 128 simultaneous voices. Its primary commercial purpose spans live performance, pedagogical instruction, home recreation, and studio production where portability and volume control outweigh acoustic instrument requirements. Console pianos and digital grands capture the highest margin pools as furniture-grade cabinetry commands premium positioning. Stage pianos compete on weight reduction and direct line-out fidelity. Sampling technology dominates installed base while hybrid architectures that blend optical sensors with acoustic piano actions represent the fastest-growing configuration.
FCC electromagnetic emissions standards in the United States, CE marking requirements under EU RoHS and electromagnetic compatibility directives, and China's GB 8898 audio equipment safety standards collectively shape product certification costs and market access timelines. Japan's METI energy-efficiency guidelines and JIS acoustic measurement protocols further constrain design parameters for instruments targeting institutional procurement channels. Stakeholders must weigh hybrid technology R&D commitments against the consolidation risk as sampling patents expire and open-source modeling frameworks proliferate.
Market Dynamics
Hybrid optical-acoustic sensor architectures are compressing the performance gap between digital and acoustic instruments, forcing manufacturers to reallocate R&D budgets toward physical modeling algorithms while defending installed-base margins in sampling-dependent product lines.
Growth Catalysts
- GB 8898 Safety Certification:China's audio equipment standards have streamlined domestic assembly corridor approvals, accelerating factory-to-market timelines for instruments manufactured in Guangdong and Zhejiang provinces.
- Conservatory Procurement Mandates:East Asian educational institutions now specify 88-key weighted action instruments with minimum 128-note polyphony for accredited music programs, institutionalizing replacement cycles.
- SuperNATURAL Modeling:Proprietary physical modeling architectures reduce waveform storage requirements while expanding timbral variation, lowering bill-of-materials costs for mid-tier product lines.
Market Restraints
- Keybed Supply Concentration:Japanese and Indonesian fabrication facilities control 80% of graded hammer action mechanisms, exposing assemblers to single-source disruption risk.
- FCC Part 15 Compliance Costs:Electromagnetic emissions testing for digital tone-generation modules adds certification overhead disproportionately burdening sub-$800 retail price points.
- Acoustic Piano Substitution:Restored vertical and grand pianos from defunct institutional inventories compete on perceived authenticity in home recreation segments.
Strategic Opportunities
- India BIS Certification Gap:Domestic audio equipment standards remain underdeveloped for keyboard instruments, creating first-mover advantage for manufacturers establishing localized testing protocols.
- Studio Production Integration:MIDI 2.0 protocol adoption enables seamless DAW connectivity, opening professional audio engineering verticals previously served by dedicated controller hardware.
- EU Green Deal Ecodesign:Energy-efficiency labeling requirements favor instruments with switch-mode power supplies and auto-shutdown circuitry, rewarding redesign investment with preferential retail placement.
Industry Challenges
- Polyphony Architecture Talent Scarcity:Firmware engineers capable of optimizing voice-stealing algorithms for 256+ note simultaneous processing command premium compensation in Osaka and Shenzhen labor markets.
- CE Marking Timeline Compression:RoHS substance restriction documentation and electromagnetic compatibility retesting cycles delay product launches by four to six months for hybrid-configuration instruments.
- Sampling Patent Expiration Management:Open-source waveform libraries threaten proprietary soundbank differentiation, requiring accelerated physical modeling R&D to maintain sonic identity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Ensemble Pianos Market |
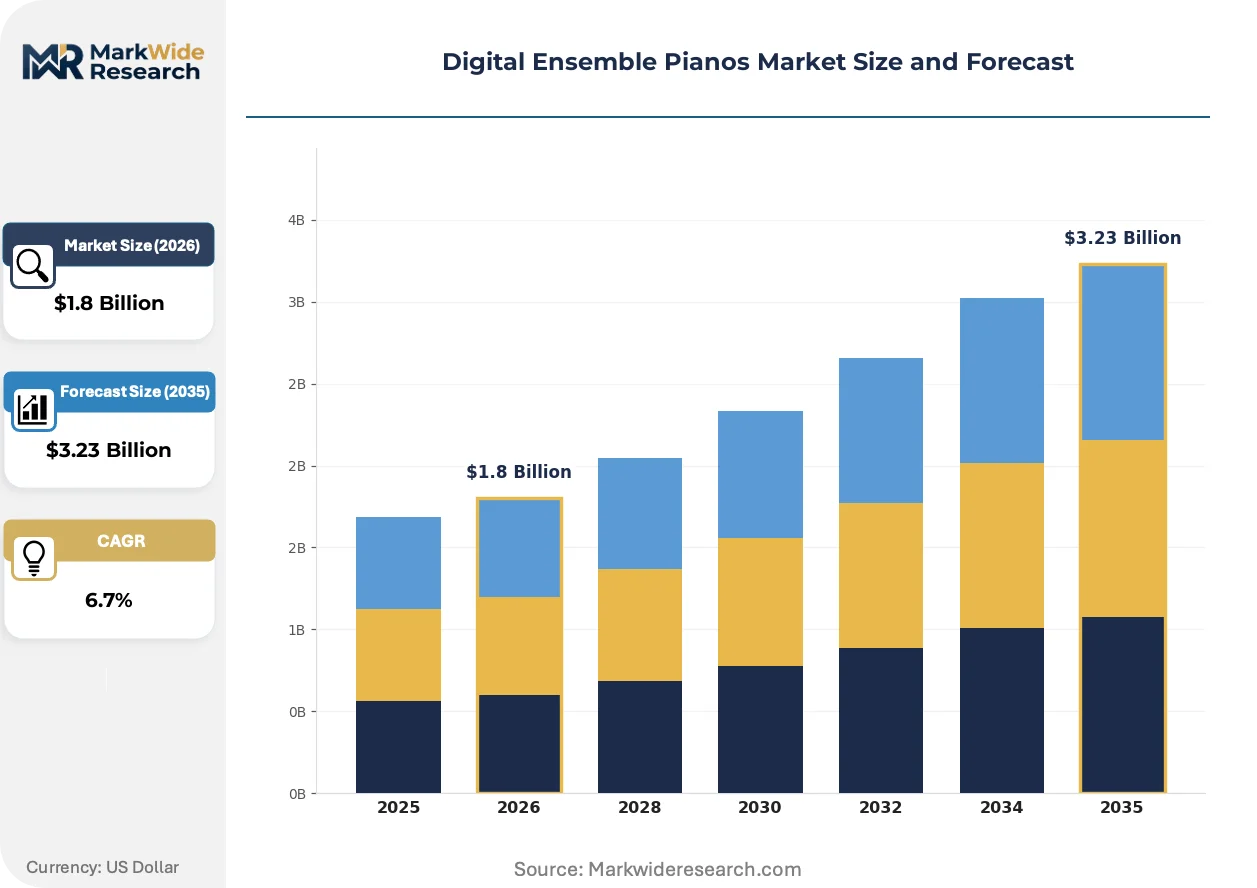
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stage Pianos, Portable Keyboards, Digital Grand Pianos, Console Pianos Technology: Sampling, Modeling, Hybrid, Synthesized End User: Musicians, Educational Institutions, Studios, Hobbyists Distribution Channel: Online Retail, Music Stores, Direct Sales, Distributors |
| Companies Covered | Yamaha Corporation, Roland, Kawai, Casio, Korg, Samick, FLYKEYS, Dexibell, Kurzweil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Ensemble Pianos Market Trends and Innovations
Optical sensor integration with wooden-key acoustic actions is redefining touch-response fidelity benchmarks, while regulatory pressure on energy consumption and electromagnetic emissions constrains hardware design freedom across all price tiers.
Hybrid architectures combining infrared key-position sensing with wooden-key actions are digitizing the expressive nuance previously exclusive to acoustic instruments. Conservatory programs in Seoul and Tokyo have adopted these configurations for advanced pedagogy, compressing the historical distinction between practice-room and performance-hall instruments. The technology is digitizing pedal-response curves and aftertouch dynamics with sufficient resolution to satisfy examination board technical requirements.
Japan's METI energy-efficiency guidelines now mandate standby power consumption below 0.5 watts for instruments procured through institutional channels. Manufacturers have responded with capacitor-backed memory retention systems that eliminate phantom load while preserving user presets. Console pianos targeting educational verticals face the steepest redesign burden, as furniture-grade cabinetry limits thermal dissipation options for switched-mode power supplies.
Direct-to-conservatory sales teams are displacing traditional music retail intermediaries in institutional procurement across East Asia. Yamaha Corporation and Kawai have established dedicated education division account managers who negotiate multi-year fleet replacement contracts. South Korean national universities have pioneered this model, bundling maintenance service agreements with initial hardware acquisition to minimize total cost-of-ownership disputes.
Digital Ensemble Pianos Market Segmentation
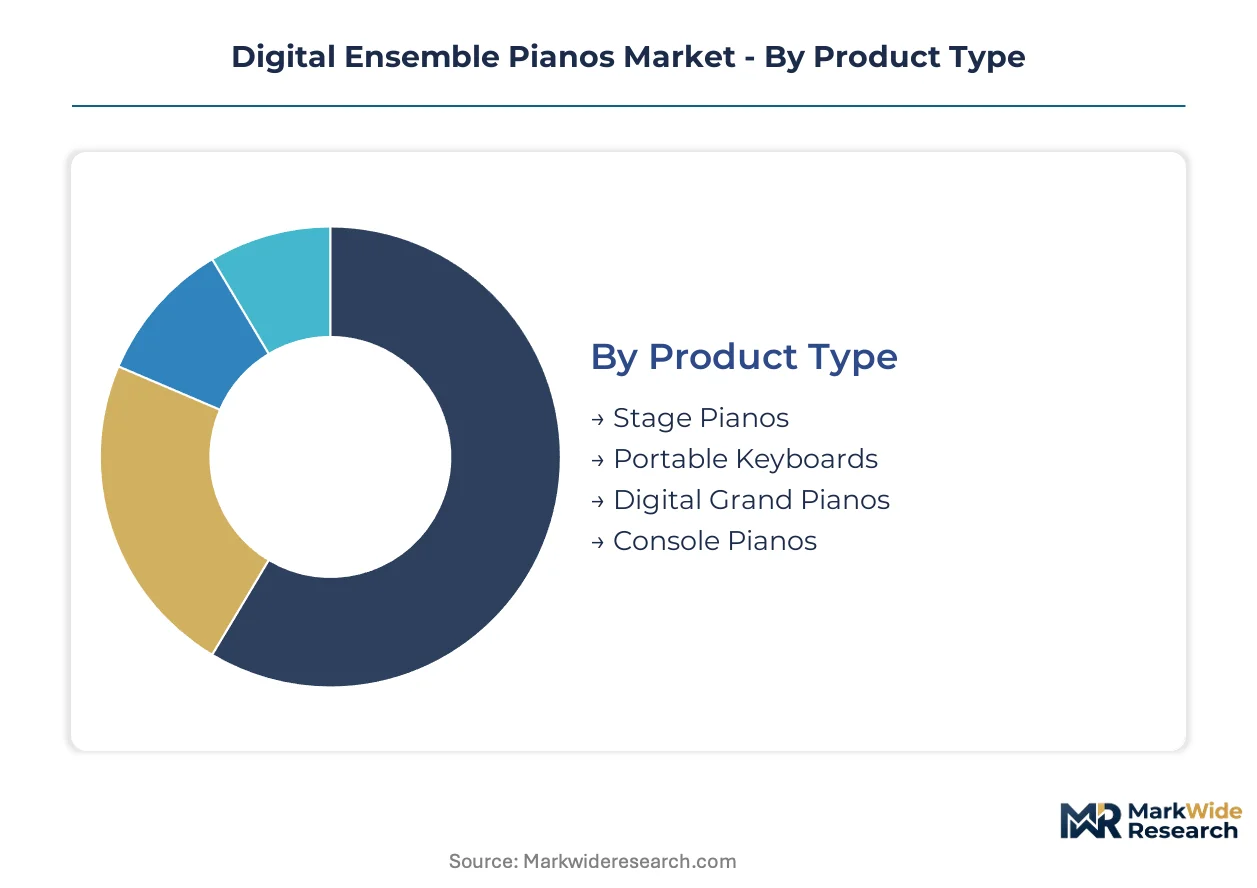
Segmentation in the digital ensemble pianos market reveals how technical specifications, procurement channels, and end-use requirements fragment demand across distinct hardware configurations. Manufacturers must align polyphony counts, keybed architectures, and distribution strategies to match the divergent priorities of conservatory fleet buyers, touring performers, and home recreation users.
Product Type:
Use-case spectrum spans portable performance rigs to furniture-grade installations anchoring institutional practice rooms.
- Console Pianos:Fixed-installation instruments with 88-key graded hammer actions housed in wooden cabinetry replicate acoustic piano aesthetics for home and educational environments. Demand concentrates in Japanese and South Korean conservatory practice rooms where METI energy-efficiency guidelines mandate standby power below 0.5 watts, forcing redesign of switched-mode power supplies within furniture-constrained enclosures.
- Stage Pianos:Lightweight chassis under 15 kilograms prioritize direct line-out fidelity and rapid patch switching for touring musicians. Seoul-based performance venues and Tokyo live houses drive adoption where load-in efficiency and venue amplification compatibility outweigh touch-response nuance.
- Portable Keyboards:Semi-weighted or unweighted actions with reduced key counts target entry-level instruction and casual recreation. Guangdong assembly corridors produce these units at volume for Chinese domestic educational procurement.
- Digital Grand Pianos:Extended cabinetry with proprietary speaker arrays and lid-prop simulation serve hotel lobbies and recital halls seeking visual presence without acoustic maintenance overhead.
Established volume favors console pianos in institutional replacement cycles; emerging adoption favors stage pianos in live performance infrastructure expansion.
Technology:
Cost tier stratification separates premium physical modeling from mass-market sampling architectures.
- Sampling:Waveform-based tone generation from multi-velocity acoustic piano recordings dominates installed base through lower firmware development costs and proven timbral familiarity. Patent expiration pressure is compressing differentiation margins for proprietary soundbank libraries.
- Hybrid:Infrared key-position sensing married to wooden-key acoustic actions digitizes aftertouch and pedal-response curves with resolution satisfying Tokyo and Seoul conservatory examination requirements. These configurations are climbing the fastest as advanced pedagogy programs adopt digitized touch-response fidelity benchmarks.
- Modeling:Proprietary physical modeling algorithms reduce storage requirements while expanding timbral variation, lowering bill-of-materials costs for mid-tier product lines targeting price-sensitive educational procurement.
- Synthesized:Subtractive and FM synthesis architectures persist in entry-tier instruments where polyphony constraints and timbral authenticity matter less than cost minimization.
Margin concentration sits with hybrid architectures; volume scale remains with sampling-dependent product lines defending legacy positions.
End User:
Customer type determines polyphony minimums, keybed specifications, and service agreement structures.
- Educational Institutions:Fleet procurement mandates 88-key weighted actions with minimum 128-note polyphony for accredited music programs across East Asian national universities. South Korean institutions pioneered multi-year replacement contracts bundling maintenance agreements to minimize total cost-of-ownership disputes.
- Musicians:Touring performers and session players prioritize weight reduction, direct USB audio output, and MIDI 2.0 protocol compatibility for DAW integration in professional audio engineering workflows.
- Studios:Recording facilities demand line-out fidelity and seamless controller integration for virtual instrument hosting, with MIDI 2.0 adoption opening verticals previously served by dedicated controller hardware.
- Hobbyists:Home recreation users balance furniture-grade aesthetics against volume control and headphone compatibility, competing with restored acoustic pianos from defunct institutional inventories on perceived authenticity.
Procurement standardization favors educational institutions; specification fragmentation characterizes musician and hobbyist segments.
Distribution Channel:
Supply concentration varies between direct institutional negotiation and fragmented retail intermediation.
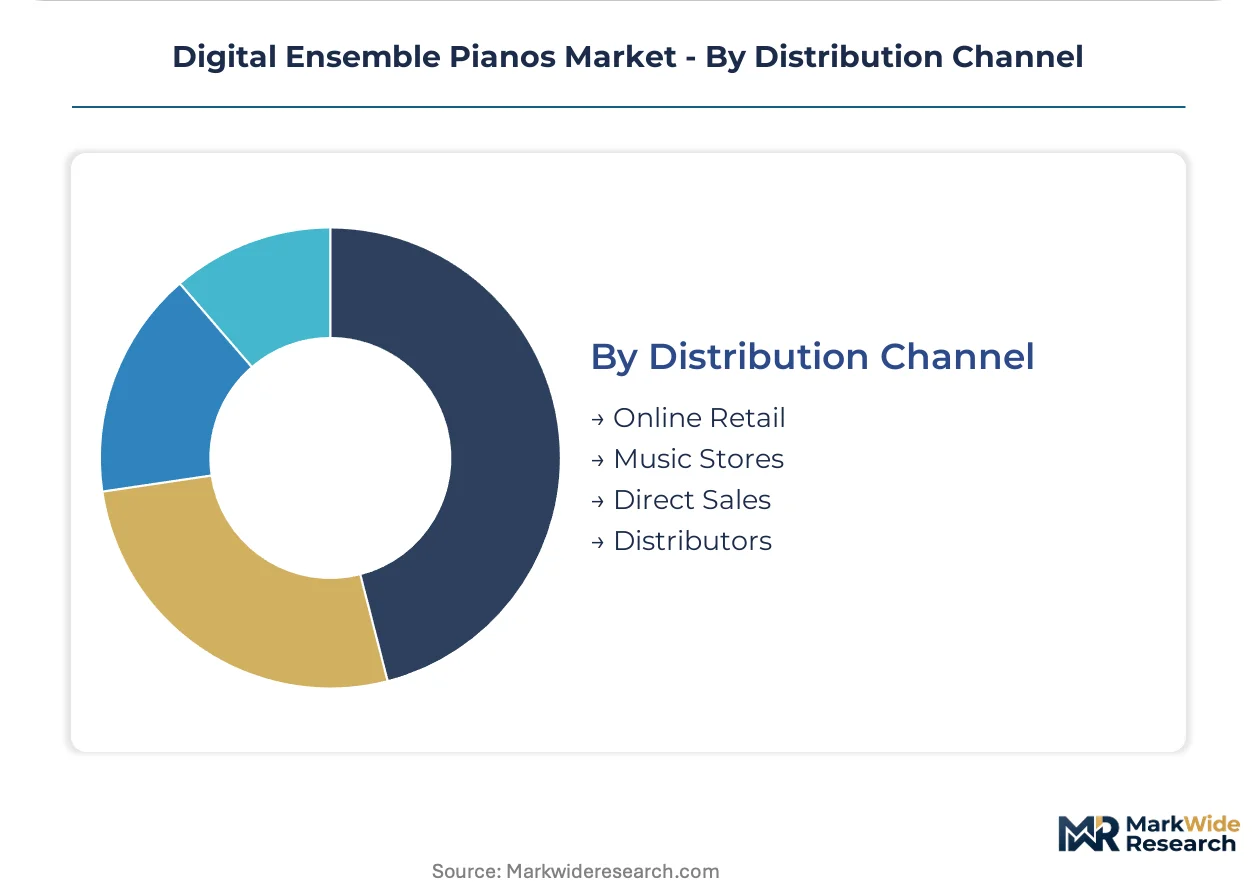
- Direct Sales:Dedicated education division account managers at major manufacturers negotiate fleet replacement contracts with East Asian conservatories, displacing traditional music retail intermediaries in institutional procurement.
- Music Stores:Brick-and-mortar retailers provide touch-and-feel evaluation for home recreation buyers and entry-level instruction markets where keybed assessment precedes purchase commitment.
- Online Retail:E-commerce platforms capture price-sensitive segments and replacement part sales, though furniture-grade console and grand pianos face logistics constraints on last-mile delivery.
- Distributors:Regional wholesalers manage inventory and certification compliance for cross-border shipments subject to FCC Part 15 electromagnetic emissions testing and CE marking RoHS documentation delays.
Channel power is concentrating in direct sales for institutional verticals; fragmentation persists in consumer-facing retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Yokohama's container throughput underwrites East Asia's dominance in electronic instrument assembly, while Guangzhou's Baiyun International Airport cargo terminals feed component corridors linking Shenzhen fabs to Zhejiang assembly plants.
Japan
Tokyo and Osaka metropolitan areas host the densest concentration of tone-generation chip design houses and keybed fabrication facilities. METI energy-efficiency guidelines mandating sub-0.5-watt standby consumption force redesign of switched-mode power supplies in furniture-constrained console enclosures. Hamamatsu's precision manufacturing cluster supplies graded hammer action mechanisms to domestic assemblers.
China
GB 8898 audio equipment safety certification has streamlined factory-to-market timelines for instruments assembled in Guangdong and Zhejiang provinces. The dual carbon goals under MIIT oversight accelerate adoption of capacitor-backed memory retention systems eliminating phantom load. Shenzhen's electronics corridor now feeds domestic sampling chipset production reducing import dependency.
South Korea
National university procurement mandates specifying 128-note minimum polyphony institutionalize replacement cycles across Seoul and Busan conservatories. The Korea Testing Laboratory's electromagnetic compatibility protocols align with CE marking requirements, smoothing export pathways to European educational markets. Daegu's manufacturing belt concentrates on mid-tier stage piano assembly for touring musician segments.
United States
FCC Part 15 electromagnetic emissions testing adds certification overhead disproportionately burdening entry-tier instruments below $800 retail. The Port of Long Beach handles inbound containerized keybed assemblies from Indonesian fabrication facilities. Nashville's music production infrastructure drives demand for MIDI 2.0 protocol-compatible stage pianos in professional audio engineering workflows.
Germany
EU Green Deal Ecodesign energy-efficiency labeling requirements favor instruments with auto-shutdown circuitry, rewarding redesign investment with preferential retail placement in Frankfurt and Munich music stores. CE marking RoHS documentation and electromagnetic compatibility retesting cycles delay hybrid-configuration product launches by four to six months. Hamburg's distribution hubs manage cross-border inventory for Central European conservatory procurement.
Digital Ensemble Pianos Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream controlling tone-generation chipsets and keybed fabrication. The vendor base concentrates around three Japanese conglomerates with captive supply chains, while Korean and Chinese assemblers compete on cost-optimized configurations. Strategic archetypes include vertical integrators with in-house semiconductor design, specialist fabricators focused on wooden-key actions, and scale-driven producers serving educational procurement channels. Competitive moves center on physical modeling R&D acceleration and direct-to-conservatory sales team deployment displacing traditional retail intermediaries.
Within the vertical integration tier, Yamaha Corporation and Roland exemplify platform control through upstream capture of keybed manufacturing and proprietary tone-generation architectures. Kawai occupies a position anchoring premium positioning through long-standing conservatory relationships. These three Japanese entities represent the dominant competitive anchors, with Casio and Korg sitting within the scale-driven mass-market segment competing on price-accessible educational procurement.
| Leading Market Players |
|---|
| Yamaha Corporation |
| Roland |
| Kawai |
| Casio |
| Korg |
| Samick |
| FLYKEYS |
| Dexibell |
| Kurzweil |
| Others |
Pricing and Supply Chain Analysis
Japanese and Indonesian keybed fabrication facilities control four-fifths of graded hammer action mechanisms, anchoring margin capture in console and stage piano tiers while exposing assemblers to single-source disruption premiums passed through to institutional buyers.
Pricing Analysis
FCC Part 15 electromagnetic emissions standards dictate the pricing tier structure across the United States market, forcing certification overhead that disproportionately burdens sub-$800 retail segments. Three-tier pricing structure across premium, standard, and economy levels separates hybrid optical-acoustic architectures from sampling-dependent mid-tier instruments and synthesized entry units. Cost compression in economy tiers is intensifying because open-source waveform libraries erode proprietary soundbank differentiation. Educational institutions exhibit least price sensitivity due to fleet procurement mandates bundling multi-year maintenance agreements, while home recreation hobbyists face restored acoustic piano competition on perceived authenticity.
Supply Chain Analysis
Tariff exposure between the United States and Indonesian fabrication facilities dominates supply chain risk assessment for keybed-dependent assemblers. Component sourcing draws from Japan for tone-generation chipsets, Indonesia for graded hammer mechanisms, and China for sampling chipset production in Guangdong and Zhejiang corridors. Single-source vulnerability concentrates in wooden-key action fabrication where Kawai's captive supply limits third-party access. Distribution runs through direct education division account managers for institutional verticals, while brick-and-mortar retailers and e-commerce platforms fragment consumer-facing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating in East Asian educational procurement as direct-to-conservatory sales teams displace traditional retail intermediaries, consolidating fleet replacement contract negotiation leverage among national university systems.
For Market Incumbents: Pre-empt open-source modeling proliferation by accelerating proprietary physical modeling R&D investment while defending sampling-dependent installed-base margins through firmware upgrade pathways. Threats from hybrid optical-acoustic sensor architectures compressing performance gaps demand backward integration into keybed fabrication to secure supply continuity against Indonesian single-source exposure. Channel control through dedicated education division account managers represents the priority defensive lever. For New Entrants and Emerging Players: Pursue India's BIS certification gap where domestic audio equipment standards remain underdeveloped for keyboard instruments, creating first-mover advantage through localized testing protocol establishment. The most penetrable segment sits in studio production integration where MIDI 2.0 protocol adoption enables DAW connectivity verticals previously served by dedicated controller hardware. Go-to-market execution should anchor on professional audio engineering workflow compatibility demonstrations. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed mid-tier assemblers in Guangdong and Zhejiang corridors lacking proprietary tone-generation architectures. Long-term viability across the projection horizon hinges on physical modeling capability acquisition or licensing rather than sampling-dependent hardware scale. The signal to watch is conservatory procurement mandate expansion beyond East Asia into Southeast Asian national university systems.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Architecture R&D Acceleration | Optical-acoustic sensor integration captures conservatory examination board specifications in Seoul and Tokyo. |
| Direct-to-Conservatory Sales Team Deployment | Dedicated education division account managers secure multi-year fleet replacement contracts bundling maintenance agreements. |
| Backward Integration into Keybed Fabrication | Captive supply of graded hammer mechanisms mitigates Indonesian single-source disruption risk. |
| Physical Modeling Patent Portfolio Buildout | Proprietary algorithms reduce waveform storage requirements while defending against open-source library erosion. |
| MIDI 2.0 Protocol Certification Investment | Seamless DAW connectivity opens professional audio engineering verticals in Nashville and Los Angeles studios. |
Research Methodology
Cross-validation between primary interviews with tone-generation chipset engineers, conservatory procurement directors, and keybed fabrication facility managers and secondary validation anchors the qualitative findings. Secondary sources include FCC Part 15 filing databases, METI energy-efficiency guideline documentation, GB 8898 certification records, and SEC 10-K disclosures from listed instrument manufacturers. Bottom-up triangulation from component-level bill-of-materials analysis and top-down reconciliation against educational procurement contract values ensures dimensional consistency.
Calibration against historical replacement cycle timing and institutional procurement budget trajectories shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology architecture, end-user category, and distribution channel structure. CAGRs derive from volume-weighted average growth rates across these segments. Industry-specific forecast inputs incorporate polyphony requirement evolution and hybrid configuration adoption curves from Seoul and Tokyo conservatory programs.
Sensitivities concentrate around sampling patent expiration timelines and open-source modeling framework proliferation that could accelerate price erosion in mid-tier product lines. Forecasts reflect assumptions regarding institutional procurement mandate geographic expansion and keybed supply concentration persistence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Musical Instruments
Digital Piano Market
Musical Instruments
Woodwind Instruments Market
Musical Instruments
Global Piano Market
Musical Instruments
Drum Sets Market
Musical Instruments
Kids Musical Instrument Market
Musical Instruments
Smart Musical Instrument Market
Musical Instruments
Bass Guitar Market
Musical Instruments
Classical Guitar Market
Musical Instruments
Electric Guitar Market
Musical Instruments
Electric Violin Market
Musical Instruments
Electronic Musical Instruments Market
Musical Instruments
Violin Market
Musical Instruments
Guitar Market