
 Digital Piano Market | 2026-2036
Digital Piano Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Piano Market Analysis
China is reconfiguring digital piano manufacturing capacity through vertically integrated facilities in Guangdong and Zhejiang provinces. Yamaha Corporation anchors premium console digital piano production through captive key-action foundries in Japan and Indonesia. Roland Corporation leverages proprietary SuperNATURAL modeling technology to differentiate its stage piano lineup against sampled-sound competitors. Guangzhou Pearl River Amason sustains cost leadership in entry-level portable digital pianos through Pearl River Piano Group's backward integration into hammer-action component production.
A digital piano is an electronic keyboard instrument that replicates acoustic piano sound and touch through sampled or modeled audio engines paired with weighted hammer-action keybeds typically spanning 88 keys with graded hammer standard specifications; its primary purpose serves musical education, live performance, and home practice where acoustic piano maintenance, space constraints, or volume control prove prohibitive. Console digital pianos occupy the largest revenue pool due to furniture-grade cabinetry and higher average selling prices in residential settings, while stage pianos represent the fastest-expanding category as gigging musicians prioritize portability and direct line-out connectivity. MIDI integration capabilities increasingly determine purchasing decisions across professional and educational segments as DAW compatibility becomes a baseline expectation rather than a premium feature.
FCC emissions compliance governs digital piano retail access in the United States, while CE marking and RoHS substance restrictions shape product design for European market entry. China's GB standards for electronic musical instruments and SAMR quality supervision create dual certification burdens for manufacturers sourcing from domestic factories. Stakeholders must monitor evolving battery-transport regulations for portable lithium-powered instruments and anticipate how EU Ecodesign requirements might extend to standby power consumption in connected digital pianos.
Market Dynamics
China's MIIT standards for electronic musical instruments and its dual carbon goals are forcing manufacturers to reconfigure production lines and supply chains, while East Asian production clusters concentrate hammer-action keybed manufacturing in Guangdong and Zhejiang provinces.
Growth Catalysts
- Music School Procurement:Institutional buyers in China and South Korea are replacing aging acoustic pianos with console digital pianos to reduce maintenance costs and enable headphone-based practice sessions.
- EU Ecodesign Requirements:Anticipated standby power consumption regulations for connected instruments are accelerating R&D investment in low-power DSP architectures before mandates take effect.
- SuperNATURAL Modeling:Physical modeling synthesis is displacing sample-based engines in professional stage pianos, reducing memory costs while enabling real-time sympathetic resonance simulation.
Market Restraints
- Hammer-Action Component Concentration:Three Japanese and Indonesian suppliers control premium graded-hammer mechanism production, creating bottleneck risk for tier-two manufacturers.
- Dual Certification Burden:China's SAMR quality supervision叠加GB standards create redundant testing requirements that extend product launch timelines by four to six months.
- Acoustic Piano Resale Markets:Depressed prices for used upright pianos in Japan and Germany present a low-cost substitute for budget-conscious residential buyers.
Strategic Opportunities
- Southeast Asia Education:Vietnam and Indonesia's expanding middle-class music education infrastructure remains underpenetrated by branded console digital piano distribution.
- Lithium-Powered Portables:Battery-transport regulation harmonization opens door to gigging musician segments previously blocked by air-freight restrictions on lithium cells.
- DAW-Native Integration:USB-C Audio Class 2.0 and MIDI 2.0 property exchange convergence enables seamless DAW connectivity as a baseline rather than premium feature tier.
Industry Challenges
- Keybed Calibration Talent:Factory technicians capable of grading hammer-weight variance to acoustic piano tolerances remain scarce in newly established Chinese facilities.
- RoHS Substance Substitution:Lead-free solder alternatives in high-vibration pedal assemblies exhibit fatigue failure rates that complicate warranty reserve calculations.
- Legacy MIDI Ecosystem Integration:Backward compatibility with five-pin DIN implementations requires maintaining parallel hardware architectures that fragment firmware development resources.
Report Scope
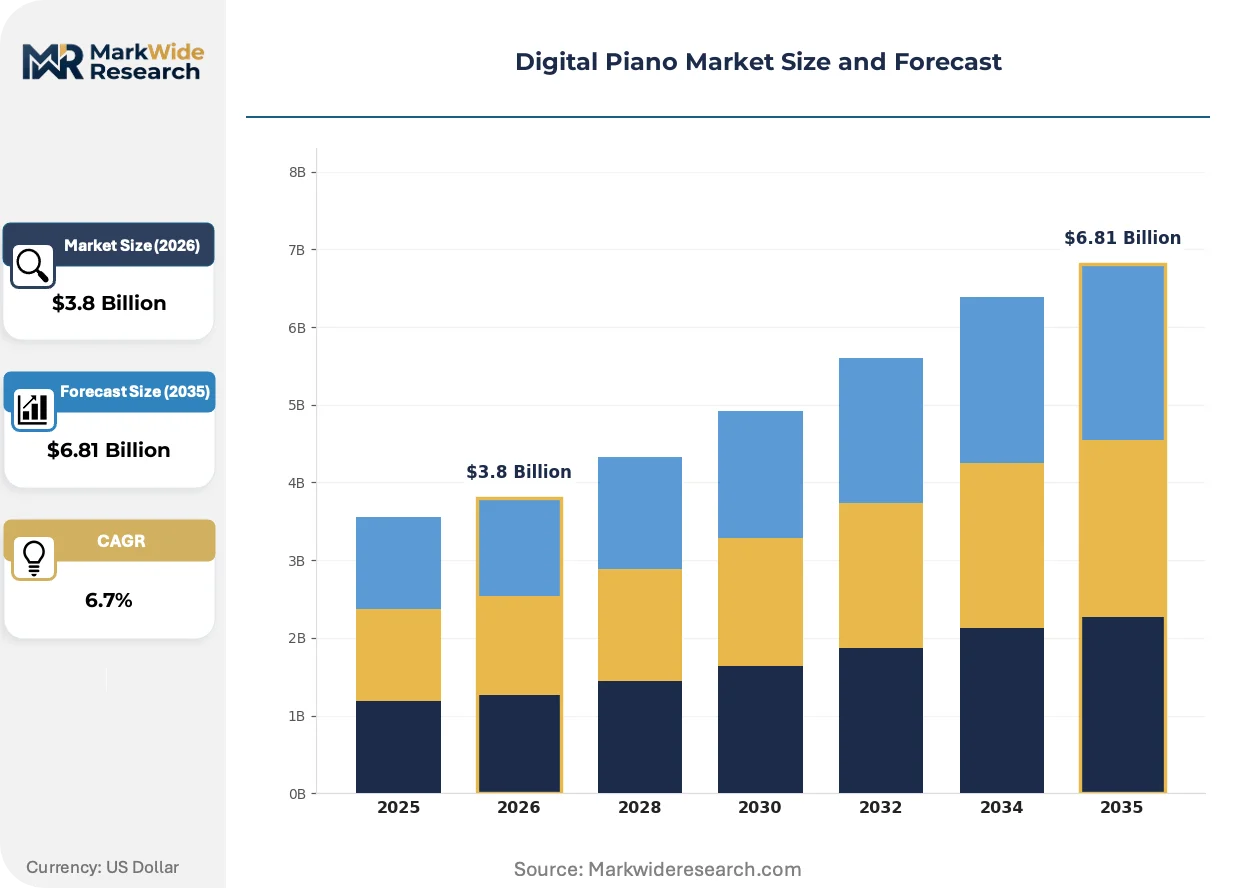
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Piano Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stage Pianos, Console Digital Pianos, Portable Digital Pianos, Hybrid Pianos Technology: Weighted Keys, Non-Weighted Keys, Touch Sensitive, MIDI Integration End User: Music Schools, Professional Musicians, Home Users, Recreational Players Price Tier: Entry-Level, Mid-Range, High-End, Luxury |
| Companies Covered | Casio Computer Co., Ltd., Guangzhou Pearl River Amason (FLYKEYS), Yamaha Corporation, Kurzweil, Dexibell, Roland Corporation, Korg Inc., Clavia (Nord), Kawai Musical Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Piano Market Emerging Trajectories
Physical modeling synthesis is digitizing acoustic piano replication, while regulatory pressure on standby power and battery transport reshapes hardware architectures. Distribution channels fragment as direct-to-educator sales bypass traditional music retail.
SuperNATURAL and comparable physical modeling engines are digitizing the acoustic piano sound generation stack by replacing multi-gigabyte sample libraries with real-time mathematical resonance models. Professional stage pianists and touring keyboardists are adopting these instruments for reduced load-in weight and instant patch recall. The technology is digitizing cost structures by compressing bill-of-materials for memory and storage subsystems.
China's MIIT standards for electronic musical instruments are tightening electromagnetic compatibility thresholds for products manufactured in domestic facilities. Exporters face retesting requirements that diverge from FCC and CE marking protocols, forcing parallel certification tracks. Console digital piano manufacturers with vertically integrated Guangdong facilities are absorbing compliance costs through captive laboratory investment.
Music schools and institutional buyers are consolidating procurement through centralized purchasing cooperatives that bypass traditional dealer networks. Bulk tender specifications now mandate minimum five-year service agreements and spare parts availability guarantees. This concentration is most visible in China's provincial education bureaus and South Korea's after-school academy chains.
Digital Piano Market Segmentation
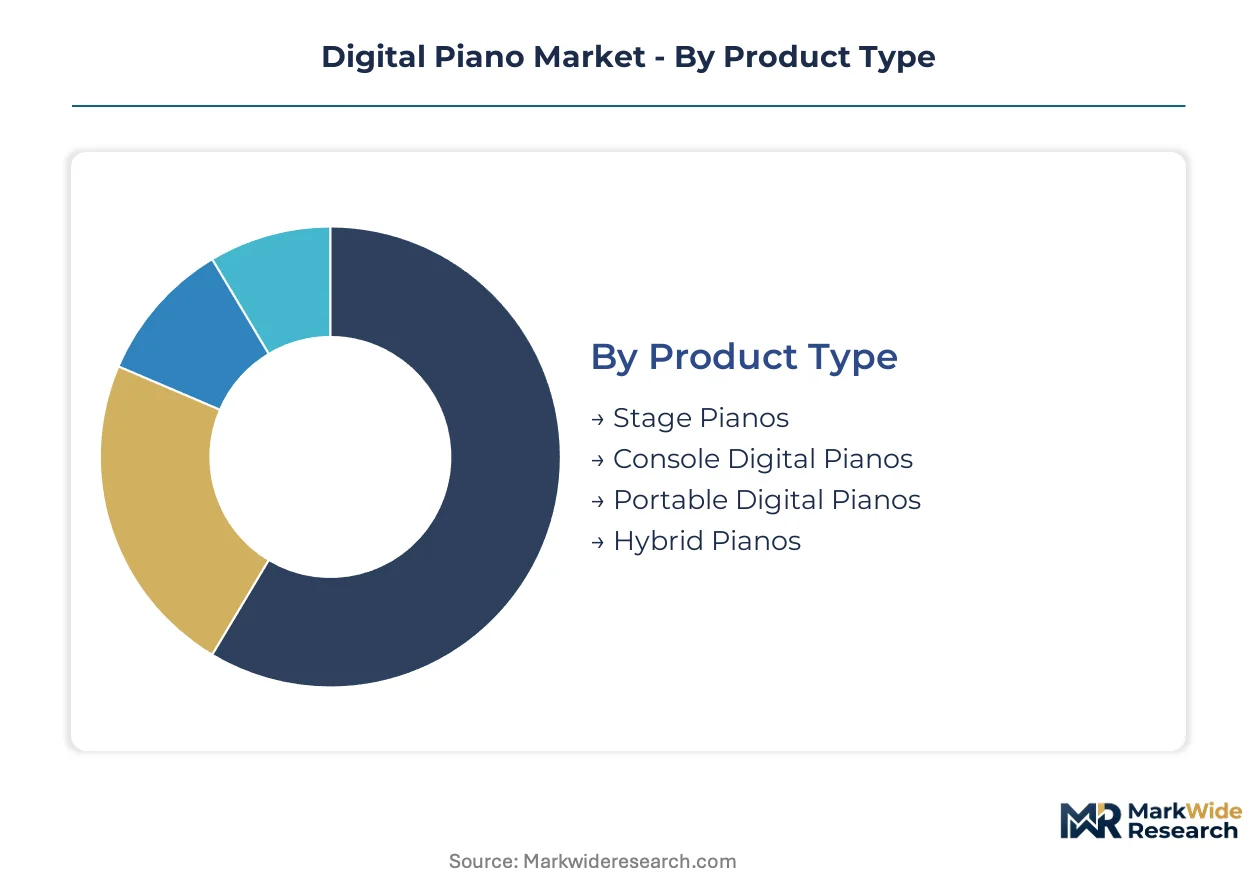
Digital piano manufacturers configure product architectures around distinct usage environments and buyer sophistication levels. Segmentation determines factory tooling investments, certification pathways, and channel compensation structures.
Product Type:
The use-case spectrum spans stationary furniture-grade installations through touring-grade portability requirements.
- Console Digital Pianos:Furniture-grade cabinetry encloses 88-key graded hammer-action keybeds with built-in speaker systems. Residential buyers in Japan and Germany drive demand for acoustic piano alternatives where space constraints and maintenance avoidance matter. Institutional procurement from China's provincial education bureaus is accelerating as music schools consolidate tender awards.
- Stage Pianos:Professional touring keyboardists prioritize direct line-out connectivity, reduced load-in weight, and instant patch recall over onboard amplification. SuperNATURAL modeling engines are displacing sample-based architectures in this segment, compressing memory costs while enabling real-time sympathetic resonance simulation.
- Portable Digital Pianos:Battery-powered configurations target gigging musicians and mobile educators. Lithium cell transport regulation harmonization is unlocking air-freight distribution channels previously blocked by carrier restrictions.
- Hybrid Pianos:Acoustic piano actions trigger optical sensors for digital sound generation, bridging purist touch requirements with silent practice capabilities. Niche positioning limits volume to dedicated showrooms and conservatories.
The dominant share belongs to Console Digital Pianos, while Stage Pianos is closing the gap fastest.
Technology:
Cost tier stratification separates professional-grade mechanisms from entry-level alternatives.
- Weighted Keys:Graded hammer standard specifications replicate acoustic piano resistance curves across 88-key spans. Three Japanese and Indonesian suppliers control premium mechanism production, creating supply concentration for tier-two manufacturers.
- MIDI Integration:USB-C Audio Class 2.0 and MIDI 2.0 property exchange convergence is redefining baseline connectivity expectations. DAW-native compatibility now determines purchasing decisions across professional and educational segments.
- Touch Sensitive:Velocity-responsive keybeds without hammer mechanisms serve budget-conscious recreational players. Manufacturing concentration in Guangdong province sustains cost leadership through scale.
- Non-Weighted Keys:Spring-action designs dominate entry-level portable configurations where price sensitivity outweighs authentic touch requirements.
Weighted Keys commands the installed base, though MIDI Integration is gaining specification frequency fastest in institutional tenders.
End User:
Application context determines service agreement structures and product lifecycle expectations.
- Music Schools:Centralized purchasing cooperatives in China and South Korea mandate five-year service agreements and spare parts guarantees. Console digital pianos are displacing aging acoustic inventories to reduce maintenance expenditure and enable headphone-based practice.
- Professional Musicians:Touring keyboardists and studio session players prioritize stage piano portability and direct DAW connectivity. Physical modeling synthesis adoption is compressing load-in logistics.
- Home Users:Residential buyers in Japan and Germany evaluate console digital pianos against depressed used upright prices. Furniture-grade aesthetics influence selection alongside touch authenticity.
- Recreational Players:Casual learners drive portable digital piano volume through online retailer channels. Price elasticity sustains entry-level configuration dominance.
Music Schools anchor institutional revenue concentration, while Professional Musicians is expanding most quickly through touring market recovery.
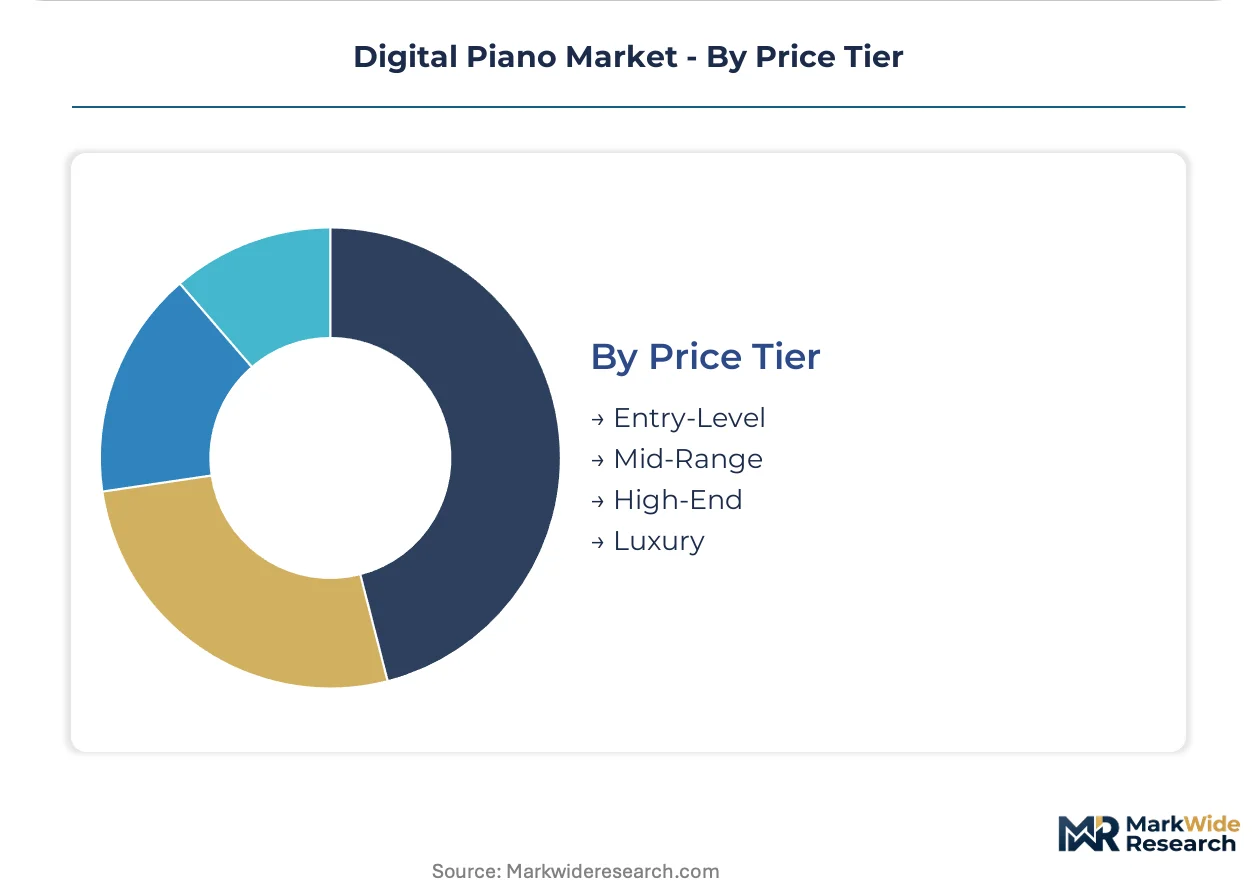
Price Tier:
Margin architecture separates premium certification-grade instruments from mass-market alternatives.
- High-End:Proprietary key-action foundries and physical modeling engines differentiate offerings for conservatory and professional segments. Yamaha Corporation's captive Japanese and Indonesian production sustains premium positioning.
- Entry-Level:Pearl River Piano Group's backward integration into hammer-action component production enables Guangzhou Pearl River Amason's cost leadership in portable configurations.
- Mid-Range:Balanced specifications target serious home learners and semi-professional gigging musicians. Feature parity with high-end alternatives is narrowing through DSP architecture commoditization.
- Luxury:Limited artisan cabinetry and bespoke action regulation serve collector and institutional donor markets. Volume constraints limit manufacturing scale.
Entry-Level captures shipment volume leadership, while High-End is climbing the fastest on average selling price expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai anchors East Asian digital piano distribution, handling containerized instrument exports from Guangdong and Zhejiang manufacturing clusters to North American and European retail channels.
China
Provincial education bureaus in Guangdong and Jiangsu are consolidating music school procurement through centralized tender systems. MIIT electromagnetic compatibility standards and SAMR quality supervision create dual certification requirements for domestic manufacturers. Guangzhou and Shenzhen production clusters concentrate hammer-action keybed fabrication and console cabinetry assembly.
Japan
Conservatory and professional musician demand sustains premium console and stage piano shipments. METI energy efficiency guidelines influence standby power specifications for connected instruments. Hamamatsu and Kakegawa industrial zones host captive key-action foundries serving domestic and Indonesian assembly operations.
United States
FCC emissions compliance governs retail market access for console and portable configurations. Music education infrastructure in Texas and California drives institutional procurement of headphone-enabled practice instruments. Los Angeles and Nashville distribution hubs stage inventory for dealer networks and direct-to-educator sales channels.
Germany
RoHS substance restrictions and CE marking protocols shape product design for European market entry. Depressed used upright piano prices in Berlin and Munich present substitution pressure for residential console digital piano buyers. Hamburg and Frankfurt logistics corridors handle regional distribution and spare parts warehousing.
South Korea
After-school academy chains are accelerating console digital piano deployment to replace aging acoustic inventories. MFDS electrical safety standards align with international certification frameworks, streamlining import processes. Seoul Capital Area concentration of music education infrastructure drives bulk tender specifications with five-year service mandates.
Digital Piano Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in hammer-action mechanisms and DSP architectures. The vendor base organizes around three strategic archetypes: captive foundry operators with backward integration into keybed production, licensing-dependent assemblers sourcing mechanisms from Japanese suppliers, and software-centric modeling engine developers. Competitive moves concentrate on geographic expansion through Southeast Asian education markets and technology licensing for physical modeling synthesis.
Among Japanese platform integrators, Yamaha Corporation and Roland Corporation exemplify the captive foundry archetype through in-house key-action production. Guangzhou Pearl River Amason occupies a position within the cost-optimized assembly tier, leveraging Pearl River Piano Group's component supply. Casio Computer Co., Ltd. represents the electronics-first entrant, applying consumer device manufacturing scale to portable digital piano configurations.
| Leading Market Players |
|---|
| Casio Computer Co., Ltd. |
| Guangzhou Pearl River Amason (FLYKEYS) |
| Yamaha Corporation |
| Kurzweil |
| Dexibell |
| Roland Corporation |
| Korg Inc. |
| Clavia (Nord) |
| Kawai Musical Instruments |
| Others |
Supply Flow & Price Mechanics
The Port of Shanghai's container freight cost dynamics compress margin structures for Guangdong-based manufacturers while amplifying price differentiation between console and portable configurations. Hammer-action mechanism scarcity in Japanese and Indonesian supplier networks feeds upstream into premium tier pricing power, whereas Pearl River Piano Group's backward integration into component production sustains entry-level cost leadership.
Pricing Analysis
Volume-discount tiering structures separate institutional procurement cooperatives from individual retail transactions, with five-year service agreement bundling commanding premium positioning. Price differentiation rests on certification grade—FCC and CE marking tiers versus domestic GB standard compliance—and brand equity anchored in captive key-action foundry ownership. Pricing pressure stems from depressed used acoustic piano resale values in Japan and Germany, which constrain console digital piano ceiling prices. Recreational players exhibit highest price sensitivity, while conservatory procurement committees prioritize touch authenticity over unit cost.
Supply Chain Analysis
Extended payment terms from Japanese key-action suppliers to tier-two assemblers in Guangdong and Zhejiang provinces lubricate working capital cycles amid component scarcity. Manufacturing concentration centers on China, Japan, and Indonesia, with hammer-action mechanisms, DSP chipsets, and lithium battery cells constituting critical input dependencies. Single-source vulnerability in graded-hammer mechanism supply creates bottleneck exposure for non-captive manufacturers. Distribution runs through dealer networks in developed markets while direct-to-educator channels bypass traditional retail in China's provincial education systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics tied to music education infrastructure refresh cycles, with institutional replacement demand for aging acoustic inventories providing the cyclical driver.
For Market Incumbents: Insulate premium positioning through captive key-action foundry capacity expansion in Hamamatsu and Kakegawa industrial zones, while accelerating low-power DSP architecture R&D ahead of anticipated EU Ecodesign standby power mandates. Physical modeling synthesis adoption by touring professionals threatens sample-based engine incumbency, requiring defensive patent licensing or acquisition of modeling technology specialists. For New Entrants and Emerging Players: Vietnam and Indonesia's underpenetrated after-school academy chains offer white-space expansion opportunity, with bulk tender participation enabled by establishing regional spare parts warehousing in Ho Chi Minh City or Jakarta. Entry through battery-powered portable configurations bypasses hammer-action supply concentration, while USB-C Audio Class 2.0 native integration addresses DAW connectivity expectations without premium tier positioning. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-centric modeling engine developers with defensible IP in physical synthesis algorithms, as hardware commoditization compresses margins in keybed manufacturing. Long-term viability across the analysis window hinges on DAW-native integration capabilities and education sector channel control. The signal to watch is institutional tender specification migration toward MIDI 2.0 property exchange requirements as an inflection indicator for technology obsolescence risk in legacy five-pin DIN architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Key-Action Foundry Investment | Yamaha Corporation's Indonesian and Japanese facilities sustain premium tier supply security against mechanism bottlenecks. |
| Physical Modeling Engine Licensing | Roland Corporation's SuperNATURAL technology differentiation compresses competitor memory cost structures through algorithmic synthesis. |
| Direct-to-Educator Channel Development | China's provincial education bureau tender consolidation rewards bypassing traditional dealer network margin extraction. |
| Battery-Transport Compliance Harmonization | Lithium cell air-freight regulatory alignment unlocks portable configuration distribution to gigging musician segments. |
| Low-Power DSP Architecture R&D | EU Ecodesign standby power anticipation drives pre-mandate compliance investment in connected instrument designs. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with product development directors at Japanese platform integrators, procurement leads at China's provincial education bureaus, and channel sales heads at European distribution networks, combined with secondary validation through MIIT electromagnetic compatibility filings, FCC equipment authorization databases, and customs trade records for hammer-action mechanism imports. Bottom-up shipment modeling and top-down education infrastructure spend analysis were triangulated against manufacturer production capacity disclosures.
Forecast inputs encompassed product type segmentation across console, stage, portable, and hybrid configurations; technology tier stratification by key-action mechanism grade and MIDI integration protocol; end-user demand patterns spanning institutional, professional, residential, and recreational segments; and geographic adoption curves tied to music education policy implementation. CAGRs were derived from installed base replacement cycles and tender award velocity across the projection horizon, with specific weighting applied to physical modeling synthesis adoption rates and battery-powered portable configuration regulatory clearance timelines.
Practitioners should monitor lithium cell transport regulation harmonization progress and EU Ecodesign mandate finalization timing for early signals of distribution channel and R&D budget reallocation. Forecasts reflect assumptions regarding institutional procurement consolidation continuity and hammer-action supplier capacity expansion. Macroeconomic deterioration in East Asian education spending, regulatory divergence in electromagnetic compatibility standards, or breakthrough advances in optical sensing keybed technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Musical Instruments
Violin Market
Musical Instruments
Woodwind Instruments Market
Musical Instruments
Electronic Musical Instruments Market
Musical Instruments
Electric Guitar Market
Musical Instruments
Drum Sets Market
Musical Instruments
Electric Violin Market
Musical Instruments
Classical Guitar Market
Musical Instruments
Digital Ensemble Pianos Market
Musical Instruments
Smart Musical Instrument Market
Musical Instruments
Guitar Market
Musical Instruments
Kids Musical Instrument Market
Musical Instruments
Bass Guitar Market
Musical Instruments
Global Piano Market