
 Electric Violin Market | 2026-2036
Electric Violin Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Violin Market Foresight
A shift from single-source Asian OEM contracts toward multi-source regional manufacturing is rebalancing component procurement across the electric violin supply chain. Yamaha leverages captive production facilities in Japan to sustain quality consistency for professional-grade instruments. NS Design competes through specialized ergonomic architectures that dominate niche segments among touring performers. Wood Violins anchors its position by controlling hand-carved body sourcing from select European tonewood suppliers.
An electric violin is a string instrument equipped with electromagnetic or piezoelectric pickups that convert string vibration into electrical signals, typically requiring active preamplification and outputting through standard quarter-inch jacks or wireless transmitters for amplification and effects processing. Solid body configurations generate minimal acoustic feedback, suicing high-volume stage environments where semi-hollow designs retain partial acoustic character for hybrid performance contexts. Professional musicians represent the margin-intensive segment where MIDI-enabled instruments command premium positioning, while student-grade analog models occupy volume-driven channels through music school procurement programs. Wireless technology adoption concentrates among gigging performers seeking stage mobility, whereas digital signal processing integration expands compositional workflows in studio settings.
The Federal Communications Commission governs wireless transmitter frequency allocations affecting instrument operability across United States venues, while CE marking requirements under EU Radio Equipment Directive shape European market access for Bluetooth-enabled models. Japan's Ministry of Economy, Trade and Industry oversees electrical appliance safety certifications that constrain power supply and battery configurations for instruments distributed domestically. Stakeholders must evaluate regulatory divergence across these jurisdictions when configuring product portfolios and certification roadmaps.
Market Dynamics
The electric violin market faces structural pressure from wireless transmitter frequency reallocation mandates, which force manufacturers to redesign RF modules and recertify existing product lines across multiple jurisdictions simultaneously.
Growth Catalysts
- USB-C Power Standardization:The EU Radio Equipment Directive's harmonized charging requirements eliminate proprietary adapter fragmentation, reducing BOM complexity for manufacturers targeting European distribution.
- Conservatory Modernization:North American music education institutions are replacing acoustic inventory with amplified instruments to accommodate contemporary performance curricula and ensemble flexibility.
- Piezoelectric Pickup Advancement:Polymer film transducer technology now captures harmonic overtones previously lost to electromagnetic designs, expanding tonal palette for studio recording applications.
Market Restraints
- Tonewood Supply Concentration:Carved-body electric violin production depends on Balkan maple and spruce reserves where export permitting delays have extended raw material lead times.
- RF Spectrum Licensing Costs:FCC Part 15 compliance testing for 2.4 GHz wireless transmitters adds fixed certification overhead that disproportionately burdens entry-price instrument manufacturers.
- Acoustic Violin Resale Liquidity:The secondary market for traditional instruments retains stronger depreciation resistance, complicating electric violin value propositions for risk-averse student buyers.
Strategic Opportunities
- German Orchestral Digitization:Publicly funded ensembles in Berlin and Munich are piloting amplified string sections, creating institutional procurement channels absent in neighboring markets.
- MIDI-DAW Convergence:Integration with Ableton Live and Logic Pro workflows positions electric violins as composition input devices for electronic music producers.
- Japan's Silver Music Education:METI-supported lifelong learning programs target retirees with beginner instrument packages, expanding addressable demographics beyond traditional school-age segments.
Industry Challenges
- Luthier Skill Migration:Traditional violin craftsmanship training pipelines lack electronics fabrication competencies, constraining workforce supply for hybrid instrument production.
- Multi-Jurisdiction Certification Lag:Sequential FCC, CE, and METI approval timelines delay product launches by 8-14 months, compressing effective sales windows for seasonal purchasing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Violin Market |
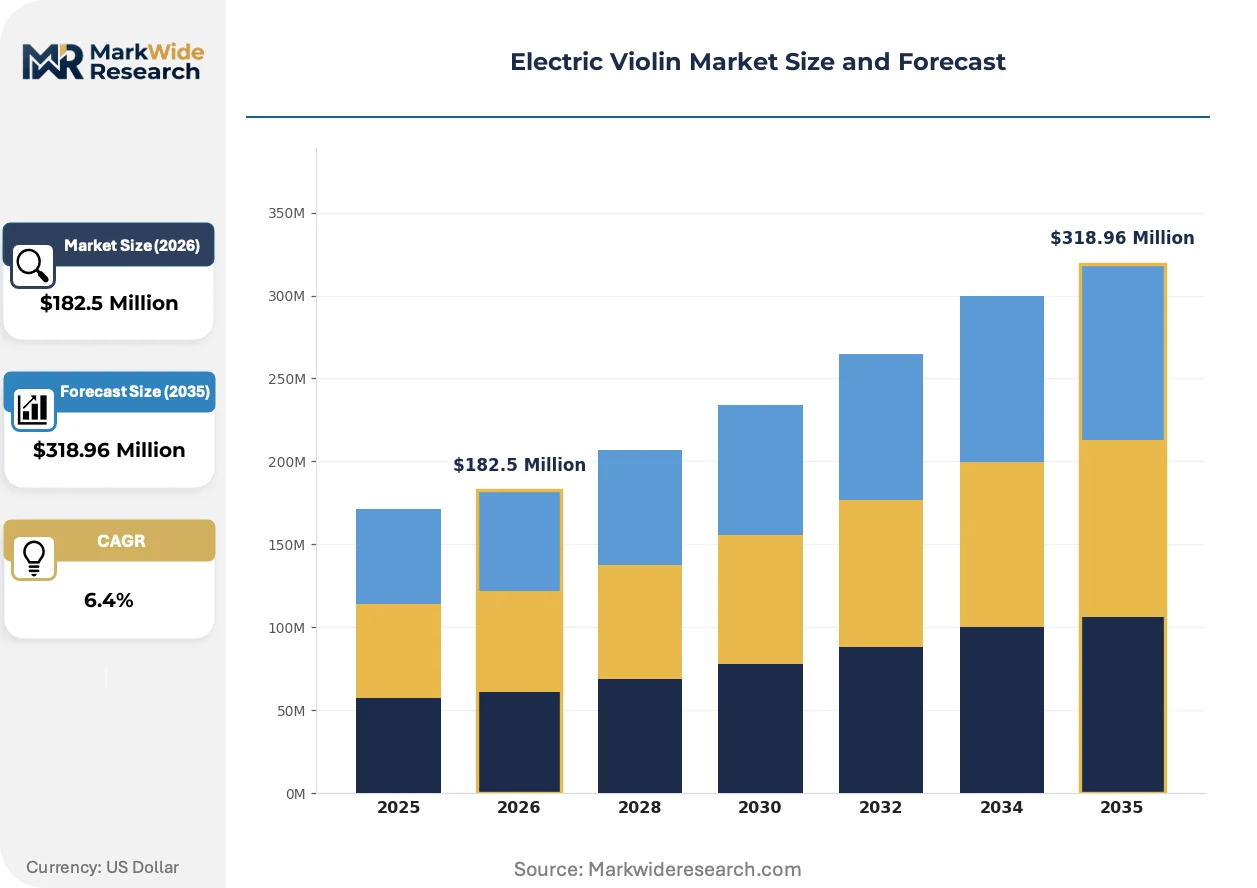
| Market Size in 2026 | $182.5 Million |
| Market Size in 2035 | $318.96 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Body, Semi-Hollow, Traditional, Performance Model End User: Professional Musicians, Students, Music Schools, Hobbyists Distribution Channel: Online Retail, Music Stores, Direct Sales, Concerts Technology: Analog, Digital, Wireless, MIDI |
| Companies Covered | Wood Violins, NS Design, Yamaha, Hofner, Silver Creek, Bridge, Zeta, Aurora, Barcus Berry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Violin Market Shifts & Advancements
Wireless audio transmission and embedded signal processing are collapsing the distinction between acoustic performance and electronic production workflows. These capabilities are redefining instrument value propositions across professional and educational segments.
Polymer composite fingerboard materials are electrifying player expectations for maintenance-free performance. Touring musicians operating in variable humidity environments have adopted these surfaces to eliminate seasonal neck adjustments. This material transition is compressing demand for traditional ebony components and rewiring supplier relationships in the accessory tier.
FCC transmitter power restrictions under Part 15.247 are constraining effective range specifications for wireless violin systems. Manufacturers must now engineer antenna diversity solutions to maintain dropout-free performance in congested venue RF environments. Professional gigging segments in the United States are responding by specifying frequency-agile systems with automated interference detection.
Direct-to-educator sales platforms are bypassing traditional brick-and-mortar music retailers. Conservatory procurement officers now negotiate volume pricing through manufacturer portals, disintermediating distributors who previously captured institutional margins. This channel compression is most advanced in United States public school districts with centralized purchasing authority.
Electric Violin Market Segmentation
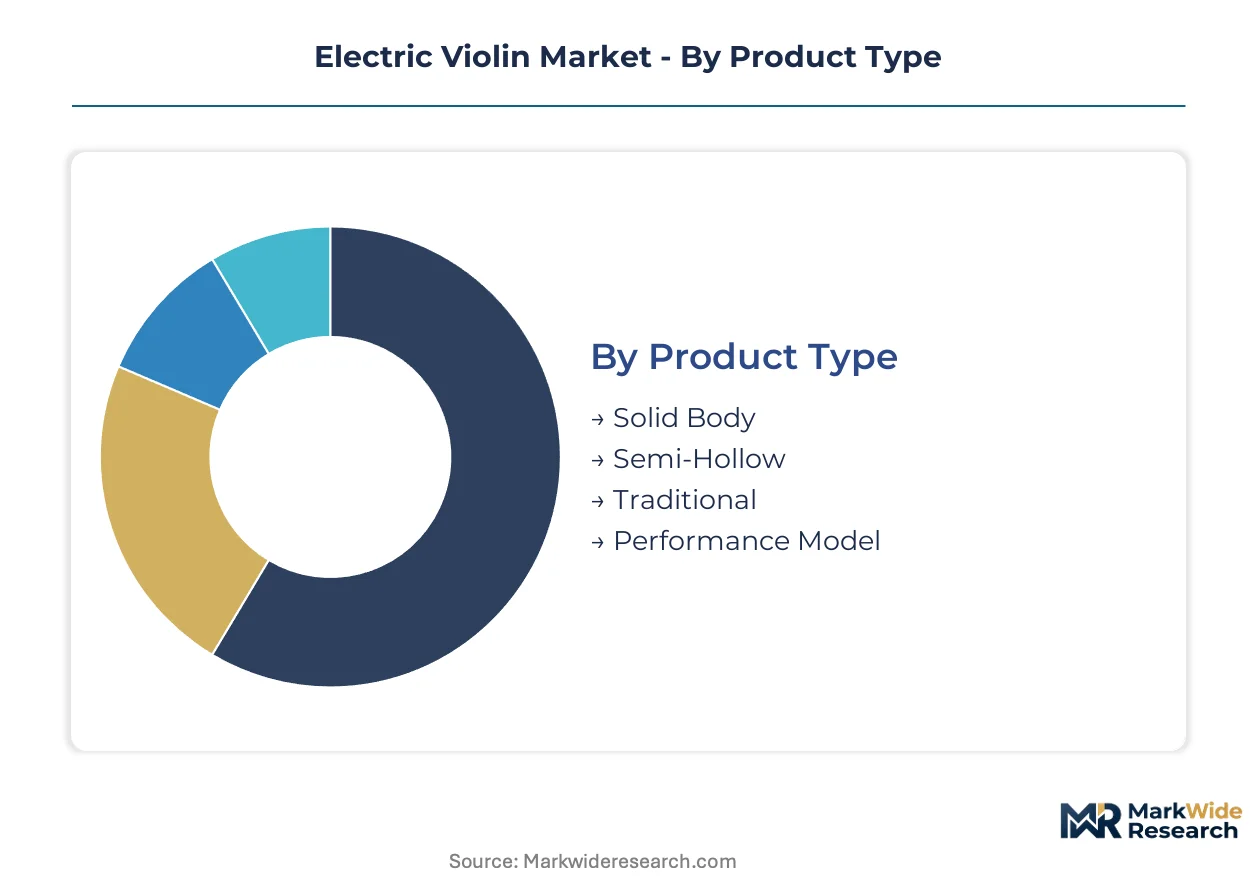
Electric violin segmentation separates instruments by acoustic behavior, player sophistication, procurement pathway, and signal architecture. Each dimension carries distinct margin profiles and certification burdens that reshape manufacturer portfolio priorities.
Product Type:
Capital intensity peaks with carved-body designs requiring tonewood curing facilities and CNC machining centers, while molded composite production demands lower fixed asset deployment.
- Solid Body:Dense polymer or laminated wood construction eliminates feedback loops at stage volume. Touring rock and metal violinists in the United States specify these configurations for arena amplification reliability.
- Semi-Hollow:Chambered cores retain partial acoustic resonance for jazz and crossover classical repertoire. German chamber orchestras piloting amplified sections favor these models for tonal warmth retention.
- Traditional:Acoustic violin profiles modified with aftermarket pickup installations. Student buyers in Japan's lifelong learning programs prioritize familiar handling characteristics.
- Performance Model:Integrated wireless transmitters and proprietary preamplification circuits. Professional soloists commission these through direct manufacturer relationships.
Most installed capacity flows through Solid Body. Expansion is steepest in Performance Model.
End User:
Volume concentration sits with institutional procurement programs, while margin concentration clusters around individual professionals specifying custom configurations.
- Professional Musicians:Touring performers and studio session players requiring road-ready durability and signal chain flexibility. MIDI-enabled instruments command premium positioning in this tier.
- Students:Secondary school and undergraduate learners entering through rental-to-own programs. Price sensitivity here drives Asian OEM volume contracts.
- Music Schools:Conservatory and public district fleet purchases replacing acoustic inventory. North American institutions consolidate buying through centralized procurement portals.
- Hobbyists:Adult learners and amateur ensemble participants purchasing through online retail channels. This segment shows highest return rates due to playability mismatches.
Music Schools absorb the highest unit volumes. Professional Musicians deliver the steepest margin expansion trajectory.
Distribution Channel:
Channel selection determines working capital requirements, with direct sales compressing inventory float but demanding dedicated sales engineering staff.
- Online Retail:Amazon and specialized music e-commerce platforms serving price-comparison shoppers. Hobbyist and student segments concentrate here.
- Music Stores:Brick-and-mortar retailers providing instrument setup and trial facilities. Professional trial purchases and school district showroom selections flow through this channel.
- Direct Sales:Manufacturer portals and field sales teams negotiating institutional contracts. Conservatory procurement officers in the United States increasingly prefer this pathway.
- Concerts:Merchandise tables and artist endorsement arrangements at live events. Limited volume but high conversion for signature model purchases.
Direct Sales channels capture the fastest institutional volume growth. Online Retail maintains the broadest geographic penetration.
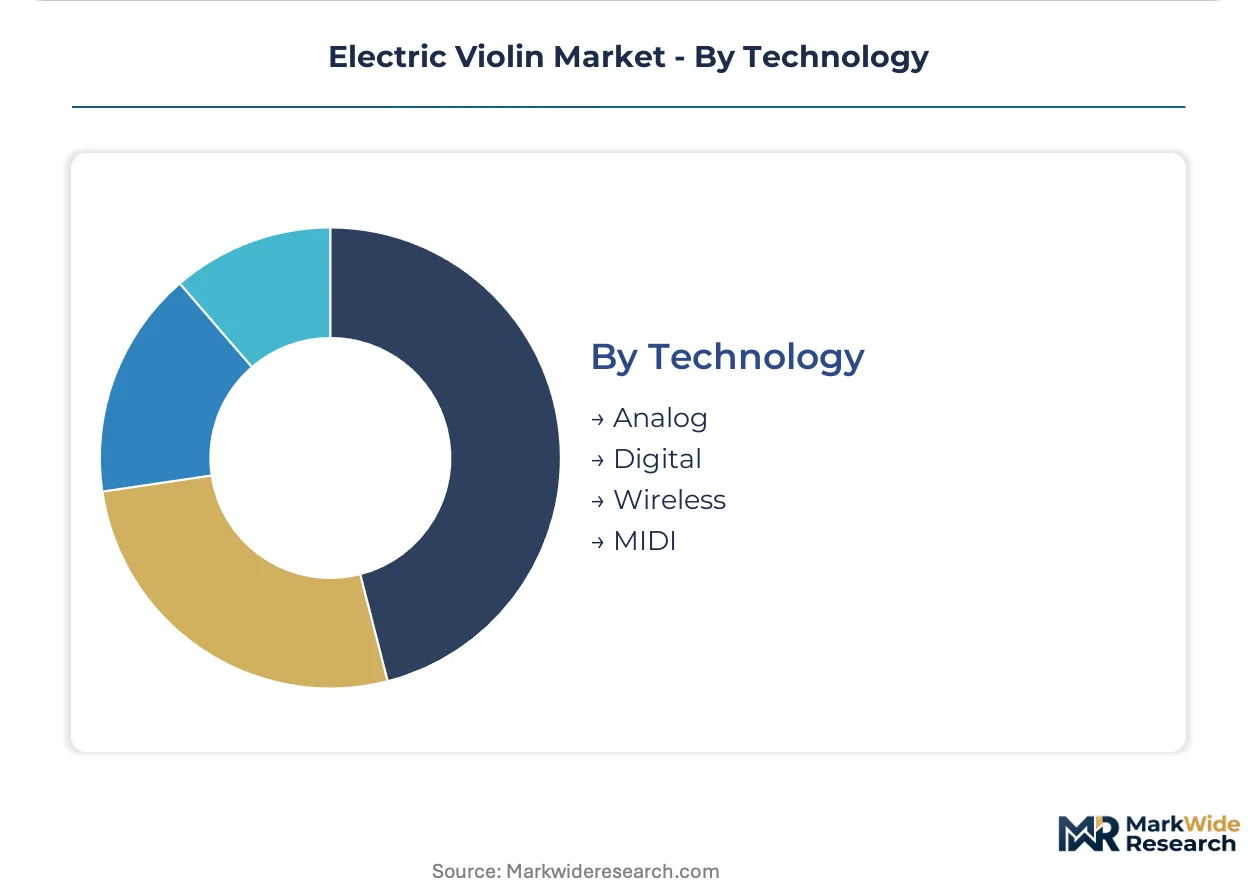
Technology:
Digital signal processing integration requires firmware development competencies absent from traditional luthier training pipelines, creating capability scarcity for hybrid instrument production.
- Analog:Passive piezoelectric or electromagnetic pickups without onboard processing. Entry-price student instruments and vintage-style professional models employ this architecture.
- Digital:Onboard analog-to-digital conversion with effects modeling and tone storage. Studio producers in Germany and Japan specify these for direct-to-DAW recording workflows.
- Wireless:Integrated RF transmitters operating in 2.4 GHz or UHF bands. FCC Part 15 compliance testing adds fixed overhead that burdens entry-price manufacturers.
- MIDI:Pitch-to-MIDI conversion enabling synthesizer and sampler control. Electronic music producers using Ableton Live and Logic Pro drive demand concentration here.
Analog technology retains the largest installed base. MIDI integration is gaining share fastest among professional purchasers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States orchestral digitization initiatives and Germany's publicly funded ensemble modernization programs concentrate procurement demand in North American and European industrial clusters. Japanese lifelong learning subsidies and United Kingdom conservatory curriculum reforms expand addressable demographics beyond traditional student segments. Regulatory divergence across FCC, CE marking, and METI jurisdictions shapes manufacturer certification roadmaps and product configuration priorities.
United States
Conservatory procurement officers in Boston and New York negotiate volume pricing through direct manufacturer portals, bypassing traditional brick-and-mortar distributors. FCC Part 15 governs wireless transmitter frequency allocations affecting instrument operability across domestic venues. Nashville's touring musician cluster specifies frequency-agile systems with automated interference detection for arena amplification reliability.
Germany
Berlin and Munich orchestras pilot amplified string sections through publicly funded digitization programs, creating institutional procurement channels absent in neighboring markets. CE marking requirements under EU Radio Equipment Directive shape market access for Bluetooth-enabled models. Bavaria's chamber music infrastructure favors semi-hollow configurations for tonal warmth retention in crossover classical repertoire.
Japan
METI-supported silver music education programs target retirees with beginner instrument packages, expanding demographics beyond school-age segments. Japan's Ministry of Economy, Trade and Industry oversees electrical appliance safety certifications constraining power supply and battery configurations. Tokyo's electronic music production studios drive MIDI-enabled instrument specifications for direct-to-DAW recording workflows.
United Kingdom
Conservatory curriculum reforms in London and Manchester replace acoustic inventory with amplified instruments for contemporary performance flexibility. REACH compliance obligations affect polymer composite fingerboard material approvals for touring musician maintenance-free specifications. Scotland's traditional music festivals generate demand for hybrid acoustic-electric configurations in folk crossover applications.
Electric Violin Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue wireless integration and embedded signal processing specializations. Market structure consolidates around three capability tiers: captive manufacturing facilities sustaining quality consistency, specialized ergonomic architectures dominating niche performer segments, and hand-carved body sourcing controlling premium tonewood supply chains. Strategic archetypes include vertically integrated instrument conglomerates, design-focused ergonomic specialists, and artisanal luthier houses with European tonewood relationships. Dominant competitive moves encompass direct-to-educator platform deployment and multi-jurisdiction certification pre-positioning.
Among United States-based specialists, Wood Violins and NS Design exemplify contrasting archetypes within the premium carved-body and ergonomic architecture segments respectively. Yamaha anchors the vertically integrated tier through Japanese captive production facilities. These three entities represent distinct competitive positioning vectors: artisanal tonewood control, specialized performer ergonomics, and scale-driven quality standardization.
| Leading Market Players |
|---|
| Wood Violins |
| NS Design |
| Yamaha |
| Hofner |
| Silver Creek |
| Bridge |
| Zeta |
| Aurora |
| Barcus Berry |
| Others |
Supply & Pricing Matrix
Captive production facilities in Japan anchor both supply security and pricing power for professional-grade instruments. Yamaha's in-house manufacturing controls quality consistency while insulating margin structures from Balkan tonewood volatility and Asian OEM price swings.
Pricing Analysis
Input-cost pass-through from Balkan maple and spruce reserves shapes margin structures across carved-body tiers. Three-tier pricing structure across premium, standard, and economy levels separates hand-carved European tonewood instruments from CNC-machined laminates and molded composite student models. Cost compression in entry-price segments intensifies because FCC Part 15 certification overhead disproportionately burdens smaller manufacturers. Students exhibit highest price sensitivity through rental-to-own programs, while professional soloists commissioning performance models demonstrate lowest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from conservatory procurement officers now mandate multi-supplier qualification for RF modules and pickup assemblies. Component manufacturing concentrates in China, Japan, and Germany, with polymer film transducers drawing from South Korean electronics suppliers. Raw material dependencies center on Balkan maple, spruce tonewood, and rare-earth magnets for electromagnetic pickups. Single-source vulnerability persists in hand-carved body supply from select European luthier houses. Distribution runs through direct manufacturer portals for institutional volume, bypassing traditional brick-and-mortar intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Radio Equipment Directive harmonization around USB-C charging standards is accelerating institutional replacement cycles across European conservatories.
For Market Incumbents: Hedge against luthier skill migration by embedding electronics fabrication training into traditional craftsmanship pipelines. Secure captive supply of Balkan tonewood through long-term European supplier contracts before export permitting delays worsen. Counter wireless transmitter frequency reallocation mandates by pre-positioning multi-jurisdiction certification roadmaps ahead of product launches. For New Entrants and Emerging Players: Enter via Japan's silver music education segment where METI-supported lifelong learning programs expand addressable demographics beyond traditional school-age buyers. Target Germany's publicly funded orchestral digitization pilots in Berlin and Munich where institutional procurement channels remain underdeveloped. Pursue direct-to-educator platform deployment to bypass entrenched distributor relationships in North American conservatory markets. For Investors and Strategic Acquirers: Roll-up economics work for ergonomic architecture specialists because touring performer demand concentrates around niche design capabilities that resist commoditization. Acquire design-focused firms with proprietary preamplification circuits and wireless integration competencies over the coming decade. Watch FCC transmitter power restriction enforcement as the inflection indicator for frequency-agile system adoption rates among professional gigging segments.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Certification Pre-Positioning | Simultaneous FCC, CE, and METI approvals compress 8-14 month launch timelines for seasonal purchasing cycles. |
| Direct-to-Educator Platform Deployment | Bypasses brick-and-mortar distributors who previously captured institutional margins in United States public school districts. |
| Ergonomic Architecture Specialization | NS Design's performer-centric designs demonstrate pricing power resistant to Asian OEM cost competition. |
| European Tonewood Supply Control | Wood Violins' hand-carved body sourcing relationships create defensible positioning in premium carved-body segments. |
| MIDI-DAW Integration Development | Ableton Live and Logic Pro workflow compatibility positions instruments as composition input devices for electronic music producers. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region informing cross-validation. Interviews with conservatory procurement officers, touring musician equipment managers, luthier guild representatives, and electronics manufacturing executives combined with secondary analysis of FCC equipment authorization databases, EU CE marking registries, METI safety certification filings, and trade customs data. Bottom-up instrument shipment tallies triangulate against top-down market value estimates derived from manufacturer revenue disclosures.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include body construction type, end-user sophistication tier, distribution channel pathway, and signal processing architecture. CAGRs derive from logistic diffusion curves fitted to technology adoption patterns and replacement cycle dynamics. Industry-specific forecast inputs incorporate wireless transmitter frequency allocation timelines and conservatory modernization budget cycles.
Inputs from regulatory filing databases and institutional procurement portals were available through the study window; gaps in luthier guild membership records and direct manufacturer shipment disclosures introduce uncertainty bands around artisanal production volume estimates. Deviation in FCC Part 15 enforcement intensity or EU Radio Equipment Directive amendment timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Musical Instruments
Global Piano Market
Musical Instruments
Drum Sets Market
Musical Instruments
Electronic Musical Instruments Market
Musical Instruments
Guitar Market
Musical Instruments
Digital Ensemble Pianos Market
Musical Instruments
Bass Guitar Market
Musical Instruments
Classical Guitar Market
Musical Instruments
Woodwind Instruments Market
Musical Instruments
Violin Market
Musical Instruments
Kids Musical Instrument Market
Musical Instruments
Electric Guitar Market
Musical Instruments
Smart Musical Instrument Market
Musical Instruments
Digital Piano Market