
 Drum Sets Market | 2026-2036
Drum Sets Market Size, Share, and Industry Trends Forecast 2026-2036
Drum Sets Market Analysis
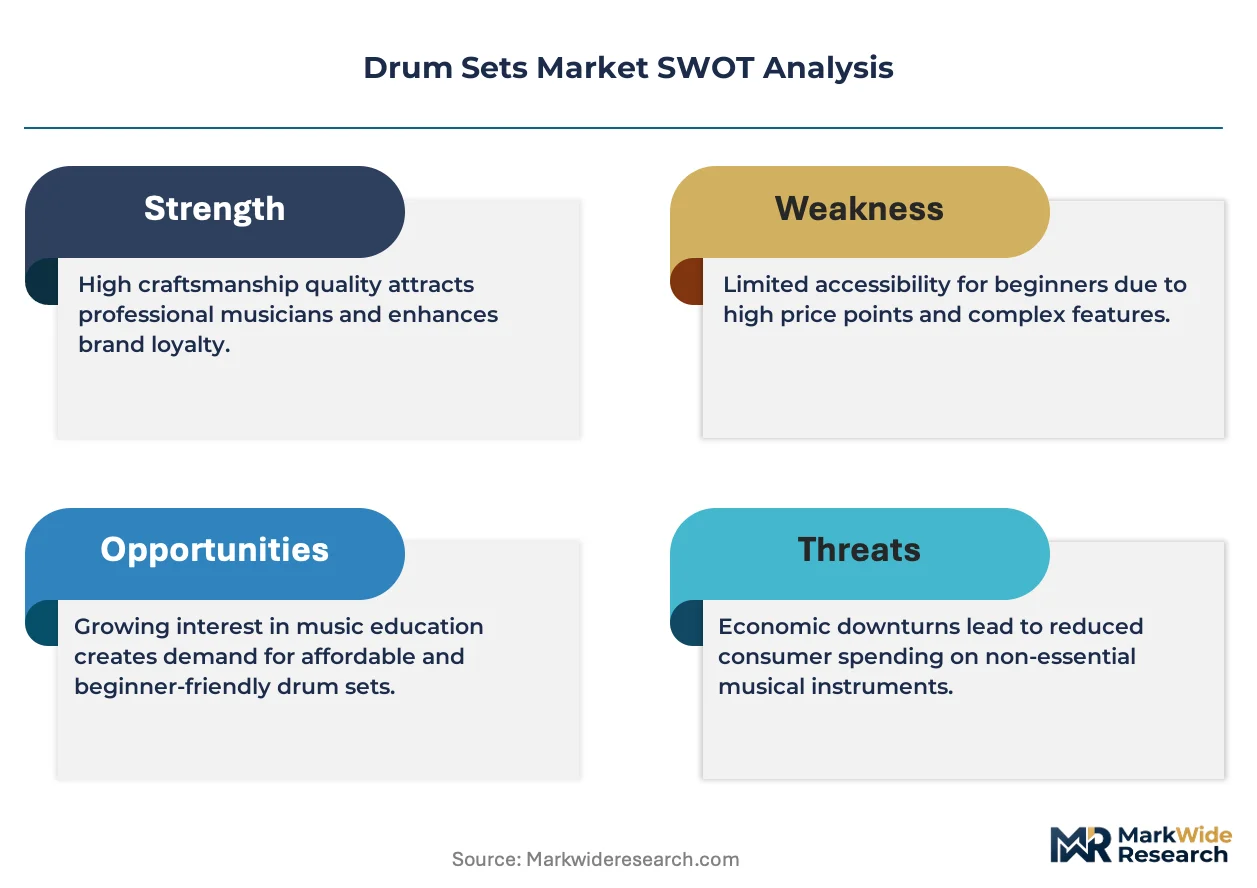
The capability gap between mass-market assemblers and vertically integrated shell manufacturers is unwinding competitive stability in the drum sets industry. Yamaha leverages captive maple and birch sourcing from Japanese forests to sustain margin control across professional tiers. Pearl anchors its position through proprietary SST shell-forming technology that dominates high-end acoustic segments. DW Drums competes via artisan-grade custom-shop operations in California, where in-house hardware forging extends brand premium.
A drum set comprises multiple percussion vessels—typically snare, toms, bass drum, and cymbals—mounted on stands or racks, constructed from laminated wood plies, cast metal, or synthetic composites, and tuned to specific pitch ranges for rhythmic accompaniment across musical genres. Acoustic drum kits retain the largest revenue pool despite electronic drum kits capturing faster growth in apartment-dwelling amateur segments where volume constraints apply. Educational institutions represent a mature but stable demand channel, while professional artists concentrate margin in hand-finished wood-shell configurations with combination material hardware.
Japan's Ministry of Economy, Trade and Industry (METI) oversees industrial standards for musical instrument manufacturing, while ISO 226 acoustic measurement protocols shape product certification for international distribution. The EU F-Gas Regulation constrains synthetic foam damping materials used in electronic pad construction, redirecting R&D toward plant-based alternatives. Stakeholders must monitor how biodegradable composite adoption alters shell resonance properties and whether captive timber certification becomes a mandatory market-access condition.
Market Dynamics
The drum sets market is being reshaped by tightening acoustic certification requirements in Europe, which are compressing refresh cycles for professional touring kits and forcing manufacturers to revalidate shell resonance profiles against ISO 226 protocols.
Growth Catalysts
- ISO 226 acoustic protocols:European enforcement of updated measurement standards is accelerating replacement demand among touring ensembles seeking certification-compliant configurations.
- Educational institutional procurement:School music programs in Japan and the United States are stabilizing baseline volume through structured acquisition budgets for acoustic kit inventories.
- Captive maple sourcing:Japanese manufacturers with direct forest lease arrangements control premium shell material flows, insulating margin from spot lumber volatility.
Market Restraints
- European F-Gas Regulation:Restrictions on synthetic foam damping materials constrain electronic pad construction, elevating R&D costs for plant-based alternatives.
- Japanese wood-shell supply concentration:Premium laminated ply production clusters with domestic manufacturers, creating bottleneck risk for international brands lacking captive timber access.
- Apartment volume constraints:Urban density in metropolitan housing markets limits acoustic kit penetration, redirecting amateur demand toward electronic substitutes with inferior margin profiles.
Strategic Opportunities
- Biodegradable composite shells:Plant-based resin alternatives to petroleum-derived binders offer positioning advantage as METI evaluates sustainable manufacturing incentives.
- Direct-to-artist custom channels:California-based artisan operations demonstrate viability of bypassing retail markup through studio-direct relationships with session musicians.
- Combination hardware configurations:Hybrid cast aluminum and titanium mounting systems command premium pricing in professional segments seeking weight reduction without resonance compromise.
Industry Challenges
- Shell-forming technician scarcity:Proprietary SST and heat-compression molding expertise concentrates with aging workforces in Osaka and Nagoya manufacturing clusters.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of CE marking, METI registration, and FCC electromagnetic compliance for electronic components extends product launch windows.
- Legacy inventory integration:Professional artists demand backward compatibility between new rack systems and vintage hardware, complicating generational product transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drum Sets Market |
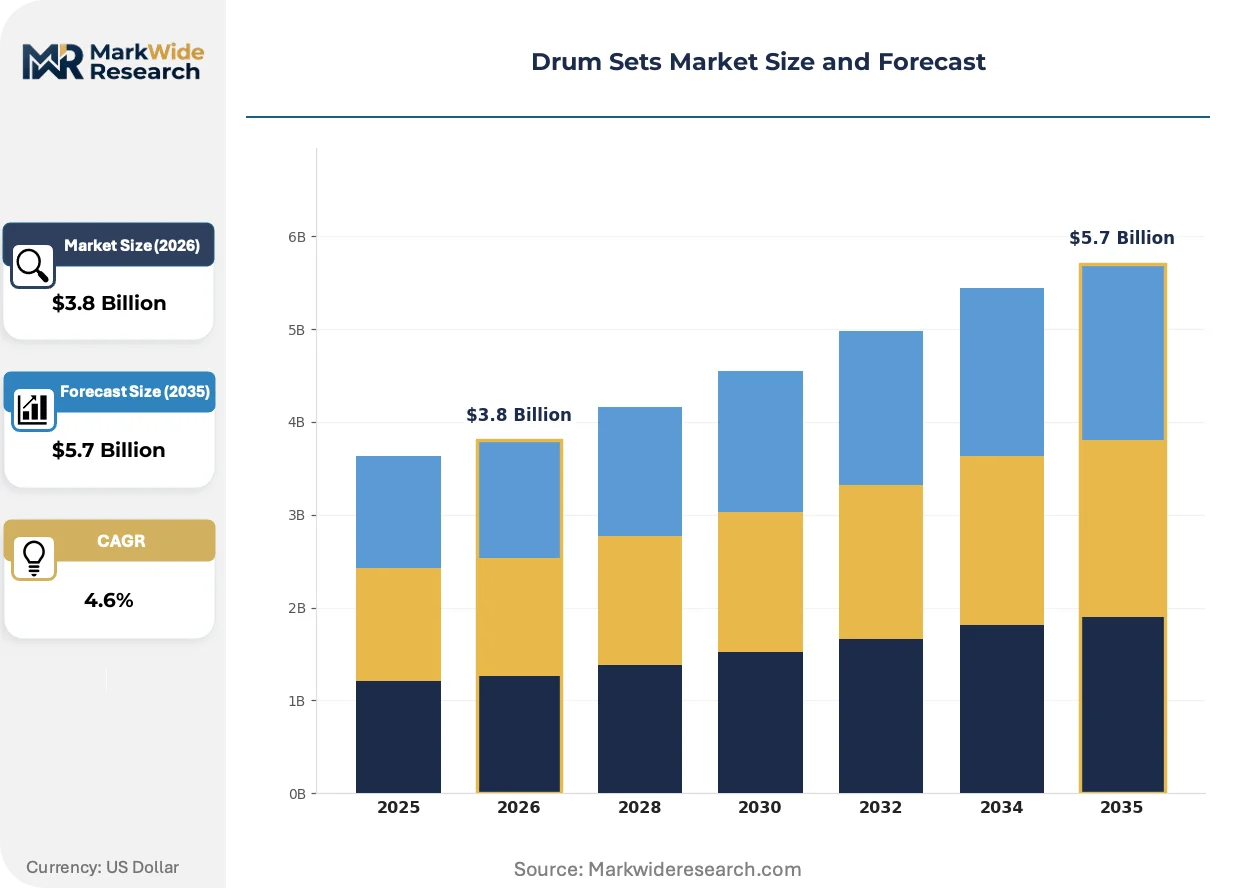
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
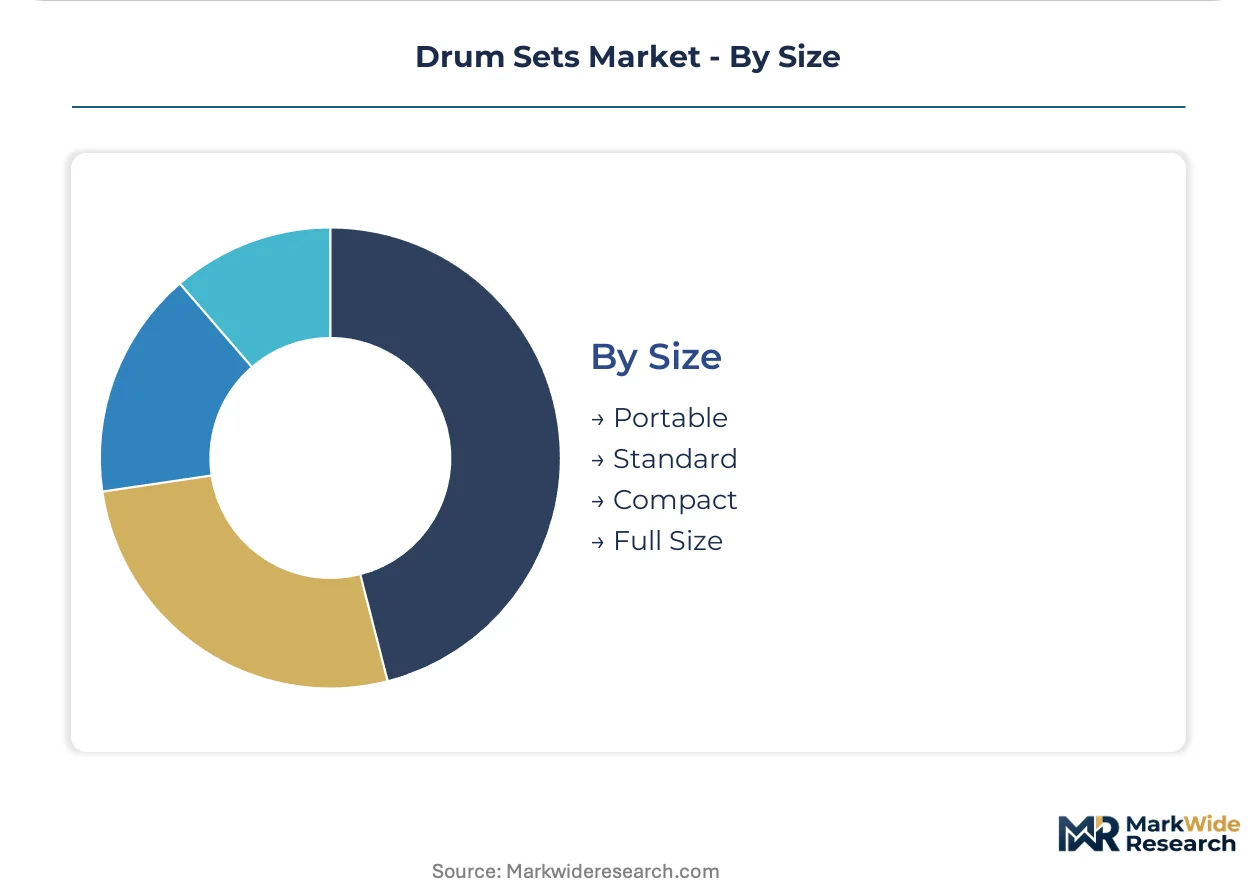
| Segmentation | Product Type: Acoustic Drum Kits, Electronic Drum Kits, Hybrid Drum Sets, Accessory Sets End User: Beginner Musicians, Professional Artists, Educational Institutions, Studios Material: Wood, Metal, Synthetic, Combination Size: Portable, Standard, Compact, Full Size |
| Companies Covered | Yamaha, Pearl, Tama, Gretsch Drums, Ludwig, DW Drums, Mapex, Sonor, Premier, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drum Sets Market Emerging Trajectories
Material science advances and regulatory pressure on synthetic components are fragmenting traditional manufacturing approaches, with acoustic and electronic segments diverging toward incompatible supply chain configurations.
Plant-based resin binders are bifurcating shell construction methodologies. Manufacturers in Japan and Germany are adopting soy-derived adhesives to preempt F-Gas Regulation expansion, while mass-market assemblers in Southeast Asia retain petroleum-based systems for cost containment. This split is enabling premium-tier brands to enforce supply chain segregation and capture certification-driven price premiums unavailable to standardized producers.
EU F-Gas Regulation amendments are constraining damping foam formulations in electronic pad construction. Manufacturers must reformulate core components or source alternative materials, compressing margin for mid-tier electronic kit producers. German and French distributors are prioritizing inventory with verified plant-based content, shifting procurement weight toward suppliers with documented biodegradable composite programs.
Session musicians are consolidating kit procurement through studio-direct relationships rather than retail channels. Los Angeles and Nashville recording complexes are negotiating bulk configurations with custom-shop operations, disintermediating traditional music retailers. This concentration is visible most acutely in the United States, where project-studio proliferation has created a networked buyer class with collective negotiating leverage against standardized product lines.
Drum Sets Market Segmentation
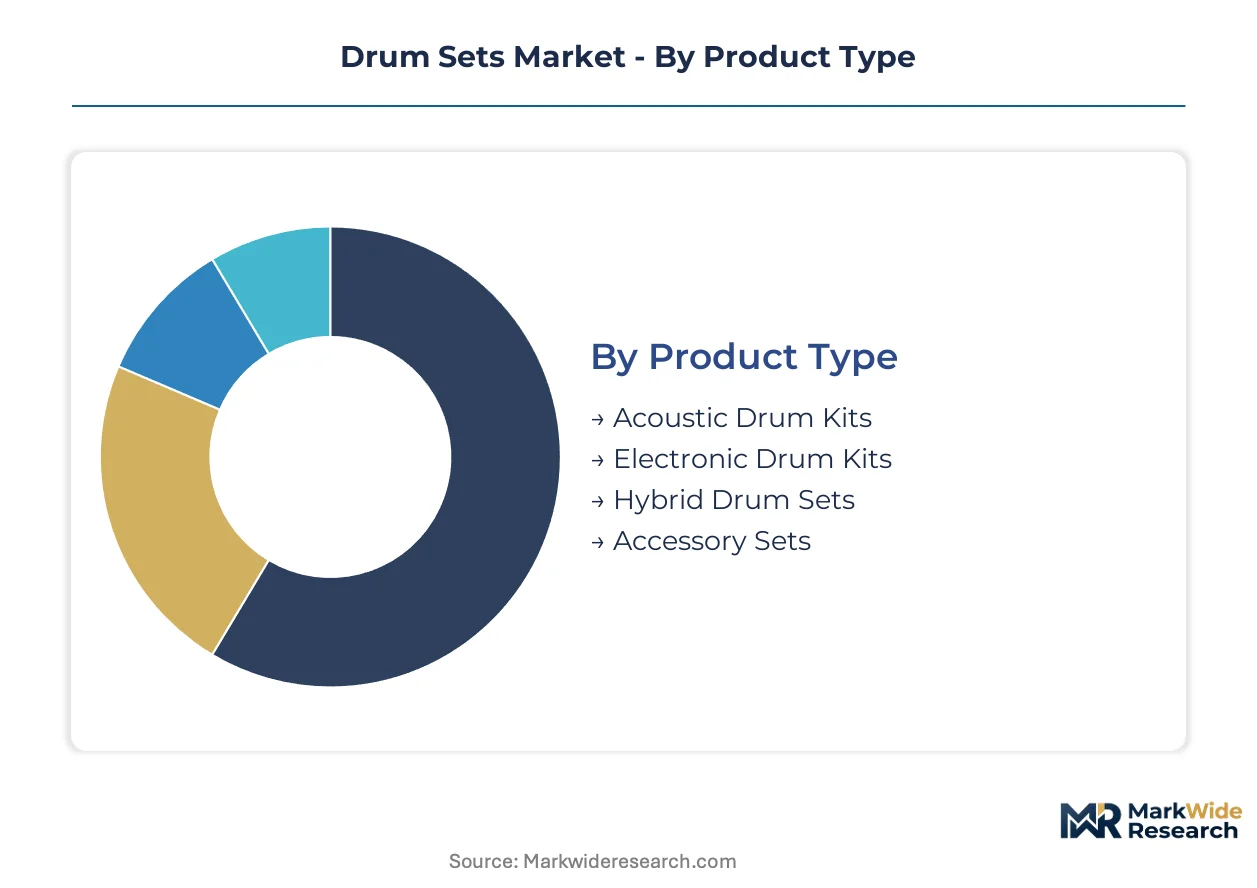
Segmentation in drum sets reveals how regulatory pressure and acoustic certification reshape procurement patterns across professional and amateur tiers. Material sourcing constraints and ISO protocol compliance create divergent margin profiles that manufacturers must navigate through targeted product architectures.
Product Type:
ISO 226 acoustic measurement protocols and EU F-Gas Regulation enforcement split certification requirements across electronic and acoustic construction methodologies.
- Acoustic Drum Kits:Laminated wood-ply shells tuned to specific pitch ranges retain the largest revenue pool. Professional touring ensembles in Japan and Germany concentrate replacement demand as European certification deadlines compress refresh cycles.
- Electronic Drum Kits:Synthetic pad construction with triggered sound modules captures apartment-dwelling amateur segments where metropolitan volume constraints apply. F-Gas Regulation restrictions on foam damping materials elevate R&D costs for plant-based alternatives.
- Hybrid Drum Sets:Combination acoustic shells with electronic trigger integration.
- Accessory Sets:Hardware, cymbals, and replacement components sold separately from core kits.
Established volume favors acoustic configurations; emerging adoption favors electronic substitutes.
End User:
Customer procurement authority varies from institutional budgeting cycles to individual artist studio-direct relationships.
- Professional Artists:Session musicians and touring drummers command hand-finished wood-shell configurations with combination material hardware. Los Angeles and Nashville recording complexes negotiate bulk custom configurations, disintermediating traditional retailers.
- Educational Institutions:School music programs in Japan and the United States stabilize baseline volume through structured acquisition budgets for acoustic kit inventories.
- Beginner Musicians:First-time purchasers with price-sensitive entry thresholds.
- Studios:Commercial recording facilities maintaining multiple kit configurations for client sessions.
Margin concentration sits with professional artists; volume stability sits with educational procurement.
Material:
Supply chain control over premium inputs determines competitive positioning in shell construction.
- Wood:Maple and birch laminated plies dominate premium acoustic segments. Japanese manufacturers with direct forest lease arrangements control material flows, insulating margin from spot lumber volatility.
- Combination:Hybrid cast aluminum and titanium mounting systems with wood shells command premium pricing in professional segments seeking weight reduction without resonance compromise.
- Metal:Cast shells and hardware components for specific tonal properties.
- Synthetic:Petroleum-derived or plant-based resin alternatives for electronic pad construction.
Captive sourcing favors wood-dominant configurations; regulatory pressure favors synthetic reformulation.
Size:
Physical footprint constraints align with residential density patterns in metropolitan housing markets.
- Standard:Full-configuration kits with multiple tom and cymbal placements serve professional stage and studio requirements.
- Compact:Reduced shell depths and truncated hardware spans accommodate smaller rehearsal spaces while retaining acoustic properties.
- Portable:Collapsible hardware and nesting shell designs for mobile musicians.
- Full Size:Maximum shell diameter configurations for orchestral and large-ensemble settings.
Urban density constraints favor compact formats; professional stage requirements favor standard configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan consumes drum sets through premium wood-shell configurations for professional touring, while the United States channels demand through studio-direct custom procurement and apartment-dwelling amateurs favor electronic substitutes.
Japan
Professional touring ensembles drive kit refresh cycles as ISO 226 acoustic standards tighten compliance requirements. METI oversees industrial standards for musical instrument manufacturing while evaluating sustainable manufacturing incentives. Manufacturing clusters in Osaka and Nagoya concentrate proprietary SST shell-forming expertise with aging workforces.
United States
Session musicians consolidate procurement through studio-direct relationships with California-based custom-shop operations. FCC electromagnetic compliance requirements extend product launch windows for electronic components. Los Angeles and Nashville recording complexes negotiate bulk configurations, disintermediating traditional music retailers.
Germany
EU F-Gas Regulation enforcement redirects R&D toward plant-based alternatives for damping materials. CE marking requirements compress refresh cycles for professional touring kits seeking certification-compliant configurations. German distributors prioritize inventory with verified plant-based content, shifting procurement weight toward documented biodegradable composite programs.
United Kingdom
Educational institutional procurement stabilizes baseline volume through structured acquisition budgets for acoustic kit inventories. REACH compliance shapes material certification for international distribution. London and Birmingham music education hubs maintain steady replacement demand for school band programs.
France
Apartment volume constraints in metropolitan housing markets limit acoustic kit penetration, redirecting amateur demand toward electronic substitutes. ECHA oversight of chemical substances affects synthetic foam formulations in pad construction. Paris recording studios negotiate hybrid configurations combining acoustic shells with electronic trigger integration.
Drum Sets Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the drum sets market. Yamaha and Pearl control premium wood-shell supply chains through captive sourcing arrangements, while DW Drums anchors artisan-grade custom operations. Three archetypes define competitive positioning: vertically integrated Japanese manufacturers with forest lease arrangements, California-based custom-shop specialists with in-house hardware forging, and mass-market assemblers dependent on spot lumber markets. Dominant competitive moves include backward integration into timber sourcing and direct-to-artist channel development bypassing retail markup.
Within the integrated manufacturer tier, Yamaha exemplifies captive supply control through direct forest lease arrangements, while Pearl occupies a position defined by proprietary shell-forming technology concentration. DW Drums represents the artisan-grade custom-shop archetype with California-based operations. These three companies anchor the competitive structure through divergent supply chain configurations—Japanese forest leases, proprietary manufacturing processes, and studio-direct relationships respectively.
| Leading Market Players |
|---|
| Yamaha |
| Pearl |
| Tama |
| Gretsch Drums |
| Ludwig |
| DW Drums |
| Mapex |
| Sonor |
| Premier |
| Others |
Supply Flow & Price Mechanics
ISO 226 acoustic measurement protocols gate both supply qualification and price differentiation simultaneously, forcing manufacturers to revalidate shell resonance profiles before accessing premium European touring segments. Compliance investment separates certified Japanese producers from mass-market assemblers, concentrating margin in METI-registered configurations while non-compliant inventory faces price compression.
Pricing Analysis
Long-term offtake contracts between Japanese manufacturers and domestic forest leaseholders anchor premium wood-shell pricing, insulating margin from spot lumber volatility. Pricing stratifies across certification tiers: ISO 226-compliant professional kits command substantial premiums over uncertified inventory, while electronic substitutes face cost compression from F-Gas Regulation compliance burdens. Apartment-dwelling amateurs exhibit highest price sensitivity, redirecting demand toward lower-margin electronic substitutes. Touring ensembles demonstrate lowest sensitivity, prioritizing certification-compliant configurations regardless of cost elevation.
Supply Chain Analysis
Inventory lead times extend substantially for hand-finished custom configurations, compressing availability for studio-direct channels. Manufacturing gravity centers on Japan, Germany, and the United States, with Japanese clusters dominating proprietary SST shell-forming expertise. Supply chains draw from maple and birch timber, cast aluminum hardware, and synthetic or plant-based resin binders. Single-source vulnerability concentrates with aging technician workforces in Osaka and Nagoya. Distribution runs through direct-to-artist custom channels and educational procurement frameworks, bypassing traditional retail markup in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The drum sets market sits in early-cycle expansion as ISO 226 protocol enforcement accelerates replacement demand among professional touring ensembles seeking certification-compliant configurations.
For Market Incumbents: Secure captive timber access through direct forest lease arrangements or long-term supply agreements to defend margin against spot lumber volatility. Accelerate proprietary shell-forming technician training programs to mitigate aging workforce concentration risk in Japanese manufacturing clusters. Invest in METI-registered biodegradable composite R&D to preempt sustainable manufacturing incentive shifts. For New Entrants and Emerging Players: CE marking fast-track programs offer entry pathway into European professional touring segments where certification compliance gates market access. Target hybrid drum set configurations combining acoustic shells with electronic trigger integration, a white-space segment with limited incumbent specialization. Pursue studio-direct relationships with Los Angeles and Nashville recording complexes to bypass established retail channel control. For Investors and Strategic Acquirers: F-Gas Regulation expansion reshapes the acquisition landscape toward plant-based resin technology holders and documented biodegradable composite programs. Long-term viability favors vertically integrated manufacturers with captive sourcing and proprietary forming expertise over mass-market assemblers. Monitor METI sustainable manufacturing incentive announcements as inflection indicator for premium-tier repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timber Sourcing | Direct forest lease arrangements insulate Japanese manufacturers from spot lumber price volatility. |
| ISO 226 Certification Investment | Compliance validation opens European professional touring segments to premium pricing capture. |
| Plant-Based Resin R&D Program | F-Gas Regulation redirection elevates German and French distributor priority for verified sustainable inventory. |
| Studio-Direct Channel Development | Bypassing retail markup through Los Angeles and Nashville recording complex relationships sustains artisan-grade margin. |
| Technician Workforce Expansion | Proprietary SST and heat-compression molding expertise concentration in aging Osaka and Nagoya clusters creates succession risk. |
Methodological Framework
Cross-validation between primary fieldwork with drum set manufacturers and secondary trade data anchors the qualitative findings. Interviews with shell-forming technicians, product development directors at integrated manufacturers, educational procurement officers, and session musicians informed supply chain and demand dynamics. Secondary sources included METI industrial standards filings, EU F-Gas Regulation amendments, ISO 226 protocol documentation, and customs records for musical instrument trade flows. Bottom-up segmentation modeling triangulated against top-down market sizing.
Sensitivity analysis tested forecast outputs against variable adoption rates for electronic substitutes and certification compliance timelines. The analytical framework segmented volume across product type, end user, material composition, and physical size dimensions throughout the projection horizon. CAGRs derived from historical replacement cycle analysis and regulatory-driven refresh acceleration. Industry-specific inputs incorporated ISO 226 enforcement schedules and METI sustainable manufacturing incentive evaluation timelines.
Decision-makers should treat outputs as directional under assumptions of steady regulatory enforcement and stable educational procurement budgets; material deviation would warrant model refresh. Specific risks include accelerated F-Gas Regulation expansion, sudden timber supply disruption, or faster-than-expected electronic kit penetration in metropolitan housing markets. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Musical Instruments
Violin Market
Musical Instruments
Digital Ensemble Pianos Market
Musical Instruments
Smart Musical Instrument Market
Musical Instruments
Global Piano Market
Musical Instruments
Guitar Market
Musical Instruments
Kids Musical Instrument Market
Musical Instruments
Electronic Musical Instruments Market
Musical Instruments
Bass Guitar Market
Musical Instruments
Electric Guitar Market
Musical Instruments
Woodwind Instruments Market
Musical Instruments
Classical Guitar Market
Musical Instruments
Digital Piano Market
Musical Instruments
Electric Violin Market