
 Marine Algae Polysaccharides Market | 2026-2036
Marine Algae Polysaccharides Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Algae Polysaccharides Market Analytics
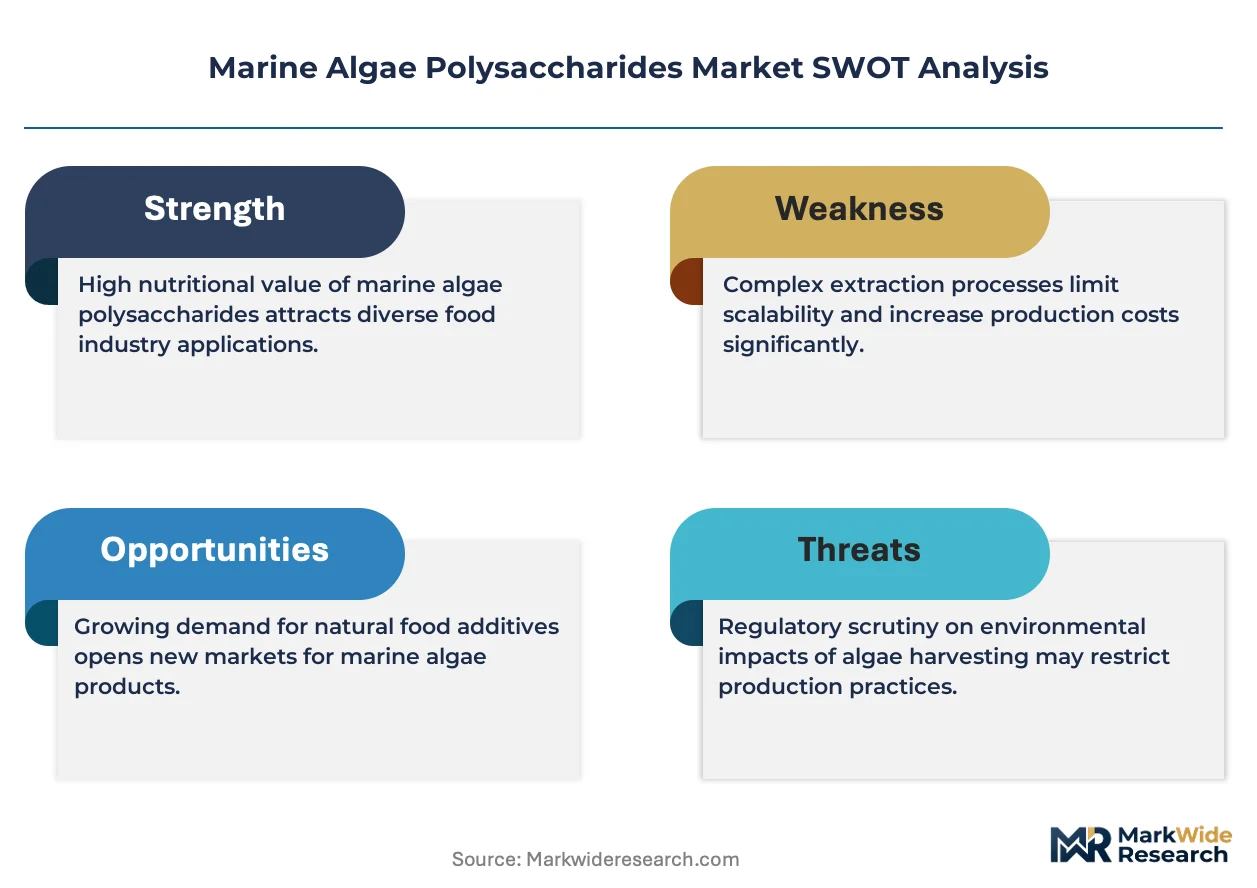
REACH compliance is rebalancing capital allocation toward solvent-recovery extraction infrastructure. CP Kelco anchors North Atlantic supply chains through captive brown algae sourcing. Gelymar specializes in Chilean carrageenan grades for clean-label dairy applications. BASF SE leverages its industrial biotechnology footprint to integrate fermentation-derived alternatives alongside wild-harvested feedstock.
Marine algae polysaccharides comprise high-molecular-weight carbohydrate polymers extracted from seaweed cell walls, with alginates containing β-D-mannuronic acid and α-L-guluronic acid blocks that gel in calcium presence, carrageenans forming thermoreversible gels via sulfate-esterified galactans, and agar providing irreversible gelation at sub-40°C temperatures; these functional properties drive their use as stabilizers, encapsulants, and viscosity modifiers across formulated goods. Carrageenan dominates food and beverage applications where dairy texturization commands premium pricing, while fucoidans from brown algae represent the fastest-growing product type as oncology researchers validate sulfated polysaccharide bioactivity. Nutraceutical applications concentrate margin pools due to clinical-grade purity requirements and batch certification costs that standard food-grade supply cannot absorb.
The European Commission's F-Gas Regulation and ECHA bioaccumulation assessments constrain solvent-based extraction methods, while FDA GRAS notifications for novel algal ingredients determine U.S. market access timelines for new entrants. China's SAMR and GB standards for food additive purity create parallel compliance tracks that fragment cross-border formulation strategies. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and redundant certification spend.
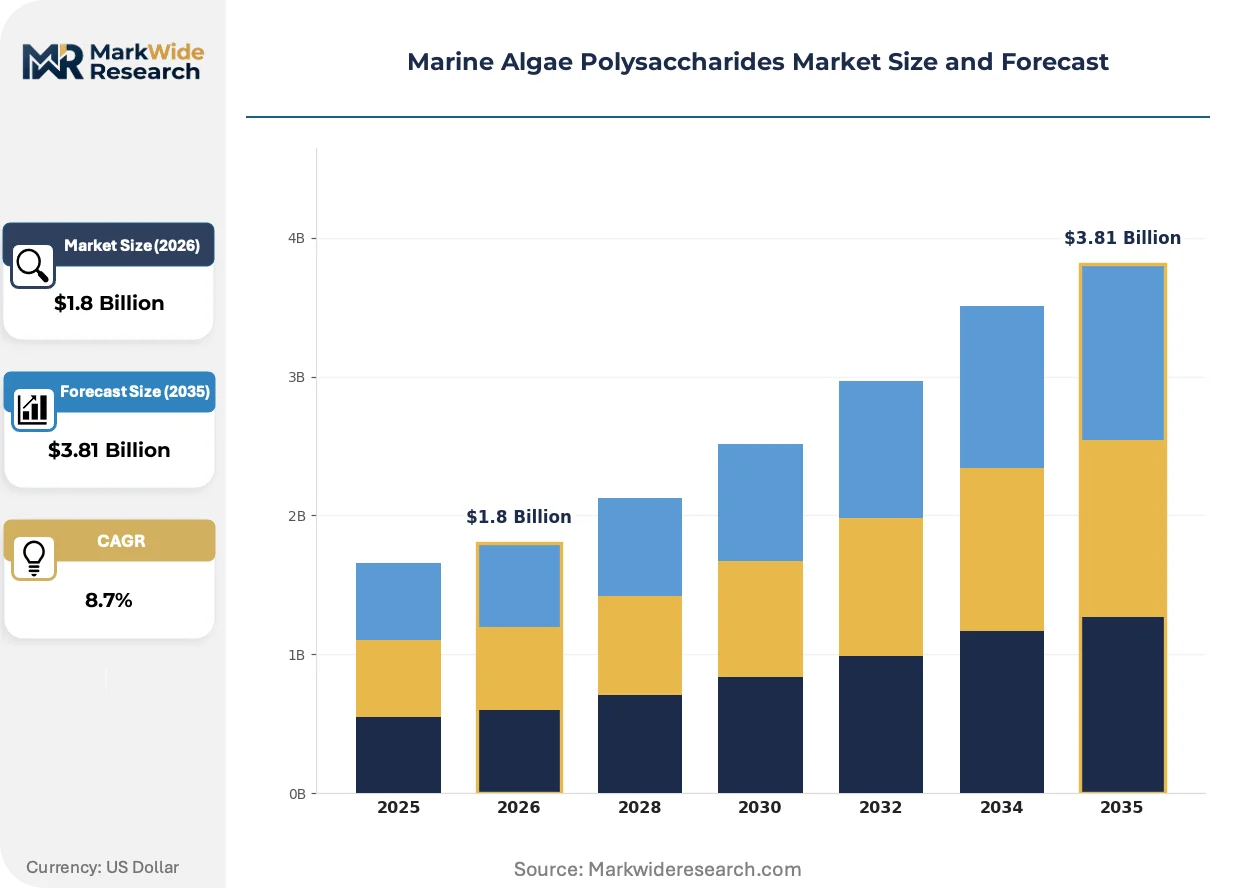
Market Dynamics
Pharmaceutical procurement of controlled-release excipients is restructuring supply priorities, while EU Green Deal traceability mandates force harvesters to document biomass provenance from coastal zones to processing facilities.
Growth Catalysts
- Controlled-Release Drug Formulations:Pharmaceutical manufacturers are expanding polysaccharide procurement for tablet matrix systems and targeted delivery mechanisms. Alginates and carrageenans provide tunable dissolution profiles that synthetic polymers cannot replicate.
- REACH Solvent-Recovery Mandates:European chemical regulations are redirecting capital toward closed-loop extraction infrastructure. Processors investing in ethanol recovery systems gain operational continuity as ECHA bioaccumulation assessments tighten.
- Coastal Aquaculture Zone Expansion:China's Fujian and Shandong provinces are scaling kelp and red algae cultivation to feed domestic hydrocolloid processors. Biomass volume concentration lowers raw material logistics costs for regional refiners.
Market Restraints
- Wild-Harvest Feedstock Volatility:Brown algae availability fluctuates with North Atlantic sea temperature patterns. Harvesters in Norway and Iceland face seasonal biomass gaps that disrupt alginate production schedules.
- F-Gas Extraction Constraints:The European Commission's fluorinated gas regulations limit solvent-based processing methods. Facilities relying on conventional extraction chemistry must retrofit or face production halts.
- Fermentation-Derived Substitution:BASF SE and industrial biotechnology competitors are commercializing microbial polysaccharide alternatives. These fermentation products bypass harvest variability and offer batch-to-batch consistency that wild-sourced materials cannot guarantee.
Strategic Opportunities
- Oncology Fucoidan Applications:Sulfated polysaccharide bioactivity research is opening clinical-grade revenue streams. Nutraceutical manufacturers pursuing FDA GRAS notifications can capture margin pools unavailable to food-grade suppliers.
- Clean-Label Dairy Texturization:Chilean carrageenan grades are penetrating premium yogurt and plant-based milk formulations. Gelymar's specialty refining capabilities demonstrate how regional sourcing commands pricing power in ingredient-conscious markets.
- Dual Carbon Goals in Processing:China's MIIT energy efficiency mandates are accelerating solar-integrated drying facilities. Algae processors adopting renewable thermal systems qualify for provincial green manufacturing incentives.
Industry Challenges
- Clinical-Grade Purity Certification:Batch certification costs for nutraceutical applications exceed food-grade validation by an order of magnitude. Manufacturers must maintain parallel quality systems without cross-contamination.
- Cross-Border Regulatory Divergence:China's SAMR GB standards, FDA GRAS pathways, and EFSA novel food assessments create fragmented compliance tracks. Formulators face stranded inventory risk when specifications misalign across destination markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Algae Polysaccharides Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Agar, Carrageenan, Alginates, Fucoidans Application: Food & Beverages, Pharmaceuticals, Cosmetics, Nutraceuticals End User: Food Manufacturers, Cosmetic Companies, Research Institutions, Pharmaceutical Firms Source: Red Algae, Brown Algae, Green Algae, Others |
| Companies Covered | BASF SE, Cargill, CP Kelco, Croda International, Evonik Industries, DuPont Nutrition & Biosciences, FMC Corporation, Algaia, Gelymar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Algae Polysaccharides Market Evolving Landscape
Extraction technology maturation is compressing the cost gap between wild-harvested and fermentation-derived polysaccharides, while regulatory chemistry restrictions are forcing process reinvention across coastal processing zones.
Enzymatic extraction protocols are converging with traditional solvent-based methods to reduce thermal degradation of bioactive sulfated polysaccharides. Nutraceutical manufacturers in Japan and South Korea are adopting hybrid processes that preserve fucoidan molecular weight distributions. This technology convergence is enabling clinical-grade certification at scales previously restricted to food-grade output.
REACH authorization requirements for solvent-based extraction are eliminating open-loop processing configurations across EU member states. ECHA's systematic bioaccumulation assessments now cover residual extraction chemicals in algae-derived food additives. Brown algae processors in France and Ireland are retrofitting facilities with membrane filtration and ethanol recovery systems to maintain market access.
CP Kelco's captive sourcing model is reshaping procurement expectations among North American formulators. Ingredient buyers are demanding documented traceability from harvest coordinates through refining stages, replacing spot-market purchasing with multi-year supply agreements. This contractual shift is most visible in hydrocolloid procurement by dairy and meat alternative manufacturers operating in California and Wisconsin.
Marine Algae Polysaccharides Market Segmentation
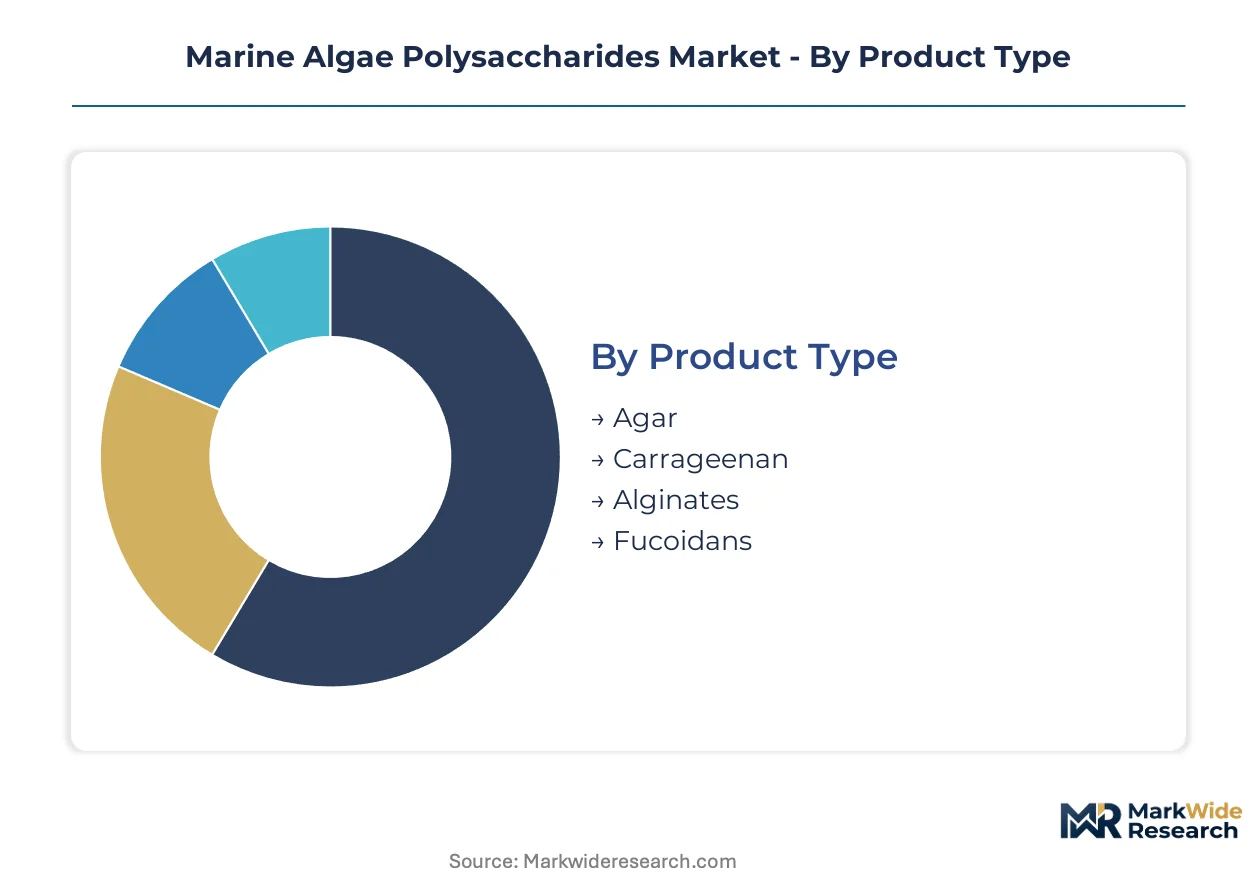
Segmentation in marine algae polysaccharides reveals how functional properties align with divergent purity requirements and regulatory pathways. Carrageenan and alginates serve mass-market hydrocolloid applications, while fucoidans and clinical-grade extracts command premium positioning through bioactivity validation.
Product Type:
Supply concentration around high-volume hydrocolloids has created tiered manufacturing infrastructure, with commodity processors in China and specialty refiners in Europe operating on different certification economics.
- Carrageenan:Sulfated galactan polymers extracted primarily from Kappaphycus and Eucheuma species form thermoreversible gels essential to dairy texturization. Demand concentrates in clean-label yogurt and plant-based milk formulations, where Chilean and Philippine biomass supply chains serve North American and European formulators seeking documented provenance.
- Alginates:Block copolymers of β-D-mannuronic and α-L-guluronic acids gel irreversibly with calcium ions, enabling controlled-release pharmaceutical matrices. Norwegian and Icelandic harvesters face seasonal biomass gaps that pharmaceutical procurement contracts must price in through advance purchase agreements.
- Agar:Agarose and agaropectin fractions provide sub-40°C gelation for microbiological media and confectionery applications.
- Fucoidans:Sulfated polysaccharides from Laminaria and Undaria species are gaining nutraceutical traction through oncology bioactivity research.
Carrageenan absorbs the bulk of installed capacity; fucoidans are expanding most quickly through clinical-grade certification pipelines.
Application:
Cost tier stratification separates commodity food additives from pharmaceutical excipients, with certification overhead creating margin pools that standard-grade supply cannot access.
- Food & Beverages:Hydrocolloid stabilizers and gelling agents dominate volume consumption across processed dairy, meat alternatives, and confectionery. Chinese coastal aquaculture zones supply raw biomass to domestic processors serving Asia-Pacific formulation demand, while European dairy manufacturers source specialty grades through multi-year procurement contracts.
- Pharmaceuticals:Controlled-release tablet matrices and encapsulation systems require tunable dissolution profiles that alginates and carrageenans uniquely provide. FDA GRAS notifications and EMA excipient master files determine market access timelines, with batch certification costs exceeding food-grade validation by substantial margins.
- Cosmetics:Film-forming and moisture-retention properties drive incorporation into topical formulations and personal care products.
- Nutraceuticals:Bioactive sulfated polysaccharides target immune modulation and metabolic health positioning.
Food and beverage applications command the greatest volume throughput; pharmaceuticals claim the steepest expansion trajectory through targeted delivery mechanism adoption.
End User:
Customer type determines procurement sophistication, with pharmaceutical and research buyers imposing traceability requirements that commodity food manufacturers rarely demand.
- Food Manufacturers:Dairy, plant-based protein, and processed meat formulators constitute the largest procurement base for standard-grade hydrocolloids. These buyers prioritize supply security and price stability over clinical documentation, sourcing through distributors rather than direct harvester relationships.
- Pharmaceutical Firms:Controlled-release formulation developers require excipient master files, drug master files, and batch-specific CoA documentation that constrains supplier qualification to a narrow tier of certified processors.
- Cosmetic Companies:Personal care formulators seek film-forming and rheology modification properties for topical delivery systems.
- Research Institutions:Academic and government laboratories consume analytical-grade materials for bioactivity characterization and mechanism-of-action studies.
Food manufacturers absorb the bulk of installed capacity; pharmaceutical firms are expanding most quickly through excipient outsourcing trends.
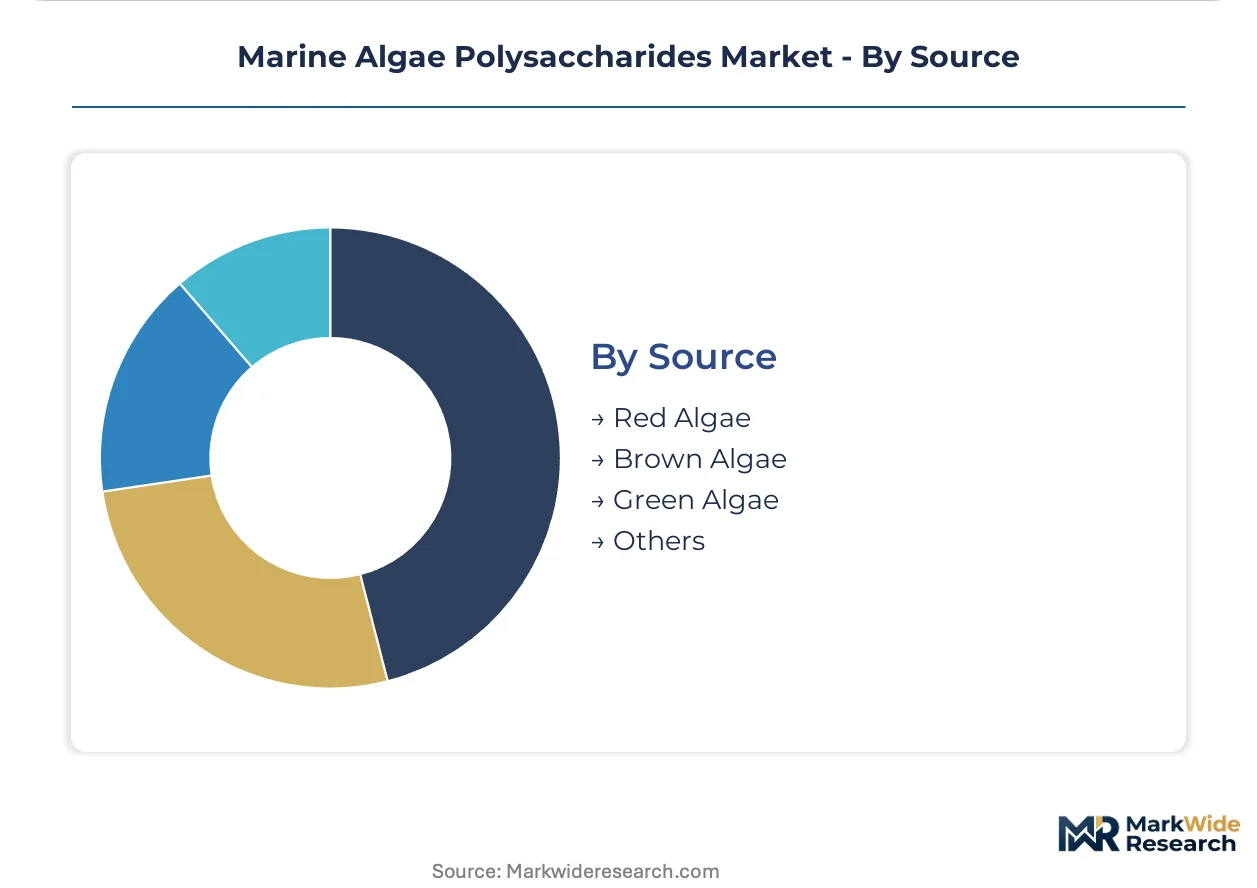
Source:
Biomass provenance dictates extract composition and regulatory classification, with red and brown algae species commanding distinct processing infrastructure and end-market access.
- Red Algae:Rhodophyte species including Chondrus, Gelidium, and Gracilaria yield carrageenan and agar with gel strength characteristics valued in food and microbiological applications. Philippine and Indonesian cultivation zones supply the majority of global Kappaphycus biomass for carrageenan extraction.
- Brown Algae:Phaeophyte kelps and rockweeds provide alginates and fucoidans through solvent or enzymatic extraction. North Atlantic wild harvest faces climate-driven availability fluctuations that Norwegian and French processors mitigate through inventory carry and alternative sourcing.
- Green Algae:Chlorophyte species contain ulvan and other sulfated polysaccharides with emerging nutraceutical interest.
- Others:Cyanobacterial and microalgal sources represent experimental feedstocks for fermentation-integrated production systems.
Red algae absorb the bulk of installed capacity; brown algae are expanding most quickly through fucoidan bioactivity commercialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fujian and Shandong coastal economic zones concentrate Chinese kelp cultivation, while EU Green Deal traceability mandates reshape North Atlantic harvest documentation. Norwegian fjord zones and Chilean Biobío Region anchor brown and red algae supply chains respectively.
China
Shandong and Fujian coastal aquaculture zones supply raw kelp biomass to domestic hydrocolloid processors. MIIT dual carbon goals accelerate solar-integrated drying facility adoption across provincial green manufacturing parks. Qingdao processors are scaling enzymatic extraction capacity to serve pharmaceutical-grade alginate demand.
Norway
North Atlantic kelp harvesters face seasonal biomass gaps that disrupt alginate production schedules for pharmaceutical procurement contracts. ECHA bioaccumulation assessments under REACH constrain residual extraction chemicals in food additives. Bergen-area processors retrofit membrane filtration systems to maintain EU market access.
Chile
Biobío Region carrageenan grades penetrate premium yogurt and plant-based milk formulations in North American clean-label markets. Chilean export documentation standards align with FDA GRAS notification requirements for novel algal ingredients. Concepción refiners specialize in Kappaphycus-derived sulfate-esterified galactans for dairy texturization.
United States
California and Wisconsin dairy manufacturers source specialty hydrocolloid grades through multi-year procurement contracts replacing spot-market purchasing. FDA excipient master file documentation determines pharmaceutical market access timelines for alginate tablet matrix suppliers. San Diego biotech clusters validate sulfated polysaccharide bioactivity for oncology applications.
France
Brittany brown algae processors navigate F-Gas Regulation constraints on solvent-based extraction methods. EFSA novel food assessments create compliance tracks distinct from FDA GRAS pathways for fucoidan nutraceutical entrants. Saint-Malo facilities invest in closed-loop ethanol recovery infrastructure to defend operational continuity.
Marine Algae Polysaccharides Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across extraction technology tiers. The vendor base stratifies between captive sourcing operators and merchant market suppliers. Three archetypes dominate: chemical conglomerates with fermentation capabilities, coastal harvester-processors with vertical biomass control, and specialty refiners with clinical-grade certification infrastructure. Competitive moves concentrate on multi-year supply agreement negotiation and solvent-recovery retrofit investment.
Among diversified chemical conglomerates, BASF SE occupies a position exemplifying industrial biotechnology integration alongside wild-harvested feedstock exposure. CP Kelco represents the captive sourcing archetype through documented North Atlantic supply chain control. Gelymar anchors the specialty refiner tier with Chilean coastal concentration. These three entities illustrate how geographic biomass access, regulatory compliance infrastructure, and end-market certification capabilities separate competitive positions.
| Leading Market Players |
|---|
| BASF SE |
| Cargill |
| CP Kelco |
| Croda International |
| Evonik Industries |
| DuPont Nutrition & Biosciences |
| FMC Corporation |
| Algaia |
| Gelymar |
| Others |
Value Network & Pricing Analysis
Captive sourcing models anchor both supply security and pricing power for North Atlantic alginate processors, with CP Kelco's vertical biomass control enabling premium contract terms that spot-market buyers cannot replicate. China's coastal aquaculture zones generate economy-grade carrageenan through volume concentration, while European REACH solvent-recovery mandates add cost layers that widen the premium-economy spread.
Pricing Analysis
Short lead-time premiums dominate pharmaceutical procurement, with alginate tablet matrix contracts commanding substantial markups over spot food-grade purchases. Three-tier pricing structure across clinical-grade, food-grade, and feedstock tiers separates nutraceutical manufacturers from dairy formulators. Cost compression in standard hydrocolloids intensifies as Chinese processors scale enzymatic extraction capacity. Food manufacturers exhibit highest price sensitivity; pharmaceutical buyers prioritize batch certification over unit economics.
Supply Chain Analysis
EU Green Deal domestic-content traceability mandates are reshaping sourcing documentation for North Atlantic harvesters. Supply concentrates in China, Chile, and Norway, with biomass drawn from Fujian kelp farms, Biobío Region Kappaphycus cultivation, and Norwegian fjord zones. Raw material dependencies rest on seasonal Laminaria availability, sulfate-esterified galactan grades, and calcium-gelation alginate blocks. Single-source vulnerability runs through North Atlantic wild-harvest gaps. Distribution runs through multi-year procurement contracts replacing spot-market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic extraction protocols are displacing solvent-based methods as the dominant processing technology, compressing the cost gap between clinical-grade and food-grade outputs while enabling bioactive preservation that legacy thermal methods cannot achieve.
For Market Incumbents: Cement supply security through captive biomass arrangements in Norwegian fjord zones and Chilean coastal concessions. Deepen upstream control over kelp cultivation to buffer against North Atlantic seasonal gaps. Invest in closed-loop ethanol recovery infrastructure ahead of ECHA bioaccumulation enforcement. Defend margin position by qualifying clinical-grade fucoidan batches before fermentation-derived substitutes scale. For New Entrants and Emerging Players: Capture white-space in oncology-focused nutraceutical applications where FDA GRAS notification pathways remain underpenetrated. Target pharmaceutical excipient outsourcing trends among controlled-release formulation developers. Enter through enzymatic extraction specialization that preserves sulfated polysaccharide molecular weight distributions. Build go-to-market credibility via EMA excipient master file partnerships with established refiners. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty refiner acquisitions with clinical-grade certification infrastructure and documented coastal biomass access. Long-term viability favors processors with dual food-pharma quality systems that can absorb batch certification overhead without cross-contamination. Watch EFSA novel food assessment timelines as inflection indicators for fucoidan nutraceutical commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | CP Kelco's multi-year contracts with California dairy manufacturers replace volatile spot-market purchasing. |
| Green Manufacturing Transition | Qingdao processors adopting solar-integrated drying qualify for MIIT dual carbon incentives. |
| Backward Integration | Gelymar's Chilean coastal concentration secures Kappaphycus provenance for clean-label dairy grades. |
| Regulatory Approval Pathway | FDA GRAS notifications for novel fucoidan ingredients determine U.S. nutraceutical market access timelines. |
| Capacity Expansion | Bergen-area alginate facilities retrofit membrane filtration to maintain REACH operational continuity. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hydrocolloid procurement managers, pharmaceutical formulation scientists, coastal aquaculture operators, and EMA regulatory affairs specialists. ECHA bioaccumulation assessments, FDA GRAS notification databases, China's SAMR GB standards, and EU Green Deal traceability documentation provided cross-jurisdictional validation. Bottom-up biomass volume estimates from Fujian and Shandong cultivation zones combined with top-down pharmaceutical excipient demand projections.
Granularity-level modeling segmented the market by product type, application, end user, and source across national production hubs. CAGRs derived from polynomial trend fitting to historical extraction capacity expansion and pharmaceutical procurement contract growth. Forecast inputs incorporated MIIT dual carbon policy implementation schedules, REACH solvent-recovery mandate compliance timelines, and enzymatic extraction technology adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to North Atlantic kelp biomass fluctuations, fermentation-derived substitution rates, and cross-border regulatory divergence between FDA GRAS and EFSA novel food pathways. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Asia-Pacific Mineral Turpentine Market
Extracts
Thymoquinone Market
Extracts
Histidine Market
Extracts
Global Magnolia Bark Extract Market
Extracts
Botanicals Market
Extracts
Irish Moss Extract Market
Extracts
Belladonna Market
Extracts
White Willow Bark Extract Market
Extracts
Patchouli Oil Market
Extracts
Pectin Powder Market
Extracts
Lemongrass Oil Market
Extracts
Rosa Roxburghii Powder Market
Extracts
Global Rose Oils Market
Extracts
Helichrysum Oil Market
Extracts
Pennyroyal Oil Market
Extracts
Bee Venom Extract Market