
 GCC Outbound Tourism Market | 2026-2036
GCC Outbound Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Outbound Tourism Market Foresight
Market Context
The premium outbound segment is consolidating around ultra-luxury experiential packages while commodity leisure travel fragments across digital channels. Kanoo Travel leverages its century-old heritage and corporate relationships to sustain dominance in business travel corridors. Al Futtaim Travel anchors its position through vertical control of hospitality assets and destination management services. Al Mosafer competes aggressively on price-transparent digital booking platforms targeting younger demographics.
Technical Definition and Structural Segments
GCC outbound tourism encompasses all resident departures from Gulf Cooperation Council states for temporary stays exceeding twenty-four hours, measured by trip volume, expenditure flows, and destination country receipts. The primary commercial purpose centers on foreign exchange outflows, aviation capacity allocation, and cross-border hospitality revenue capture. Leisure travel commands the largest expenditure pool among purpose categories, while medical tourism generates the highest per-trip margins due to extended stays and companion travel. Online Travel Agencies capture growing share among the 26-35 age bracket, though corporate travel desks retain pricing power in the business segment.
Regulatory Framework
Saudi Arabia's General Authority of Civil Aviation and the UAE's General Civil Aviation Authority coordinate bilateral air service agreements that determine route capacity and carrier access across Gulf departure points. MOHAP in the UAE and Saudi Arabia's national health regulator certify medical facilities abroad, directly shaping medical tourism destination preferences through approved-provider networks. Stakeholders must monitor evolving visa reciprocity negotiations between GCC states and Asian destination markets.
Market Dynamics
Saudi Arabia's Vision 2030 visa liberalization is redistributing departure volumes across Gulf corridors, compressing the UAE's historical dominance while creating new origin-destination pairings through expanded air service agreements and destination marketing co-investments.
Growth Catalysts
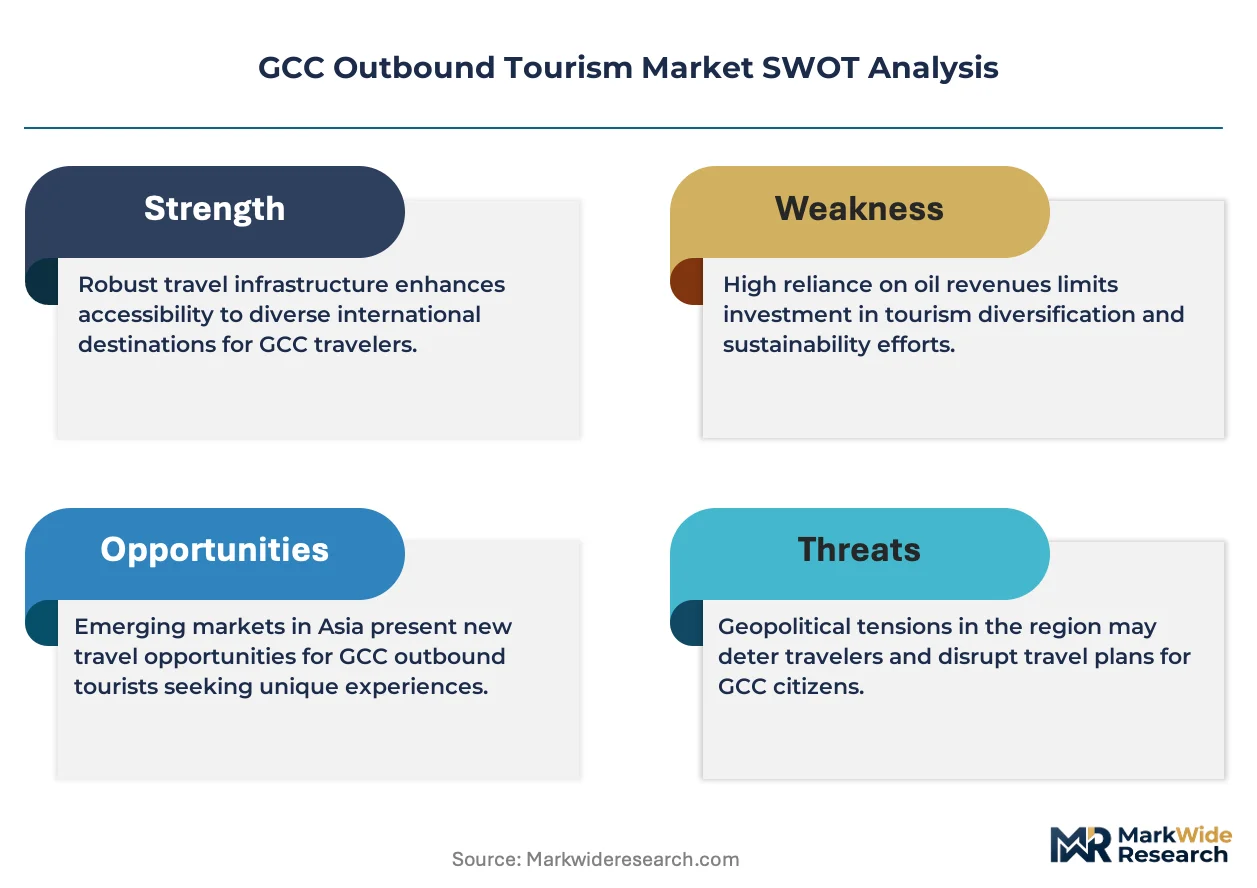
- Visa Policy Liberalization:Saudi Arabia's e-visa platform and 96-hour transit schemes issued under Vision 2030 are unlocking first-time outbound mobility for households previously excluded by documentation friction.
- Air Service Expansion:Bilateral capacity agreements negotiated by the General Authority of Civil Aviation are adding seat supply to Southeast Asian leisure destinations, reducing fare premiums on high-demand routes.
- Medical Accreditation Networks:MOHAP-certified provider directories in the UAE are streamlining patient routing to Thai and German healthcare facilities, extending average trip duration and companion expenditure.
Market Restraints
- Aviation Capacity Concentration:Route scheduling dominance by Emirates, Saudia, and Qatar Airways limits competitive pricing on trunk routes to European and South Asian destinations.
- Currency Peg Volatility:Dollar-indexed GCC currencies amplify destination cost inflation when the euro, sterling, or Asian currencies appreciate, compressing real purchasing power for leisure travelers.
- Biometric Exit Controls:Saudi Arabia's Absher platform integration with departure processing creates documentation bottlenecks during peak seasonal windows.
Strategic Opportunities
- Kuwait and Bahrain Underpenetration:These markets maintain lower outbound penetration rates per capita than the UAE or Saudi Arabia, presenting whitespace for digital-first booking platforms targeting price-sensitive segments.
- Halal Tourism Infrastructure:Destination management investments in prayer facilities, halal dining certification, and gender-segregated wellness amenities are unlocking Muslim-majority European and East Asian markets.
- Corporate Travel Tech Convergence:Integration of expense management APIs with mobile booking platforms is displacing legacy travel desk intermediaries in mid-market business segments.
Industry Challenges
- Arabic-Language Digital Talent Scarcity:Shortages in UX localization and regional payment gateway integration are delaying platform rollouts for Saudi and Kuwaiti market entry.
- Legacy GDS Migration Friction:Corporate travel desks face integration complexity when transitioning from Sabre and Amadeus terminals to NDC-enabled direct airline connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Outbound Tourism Market |
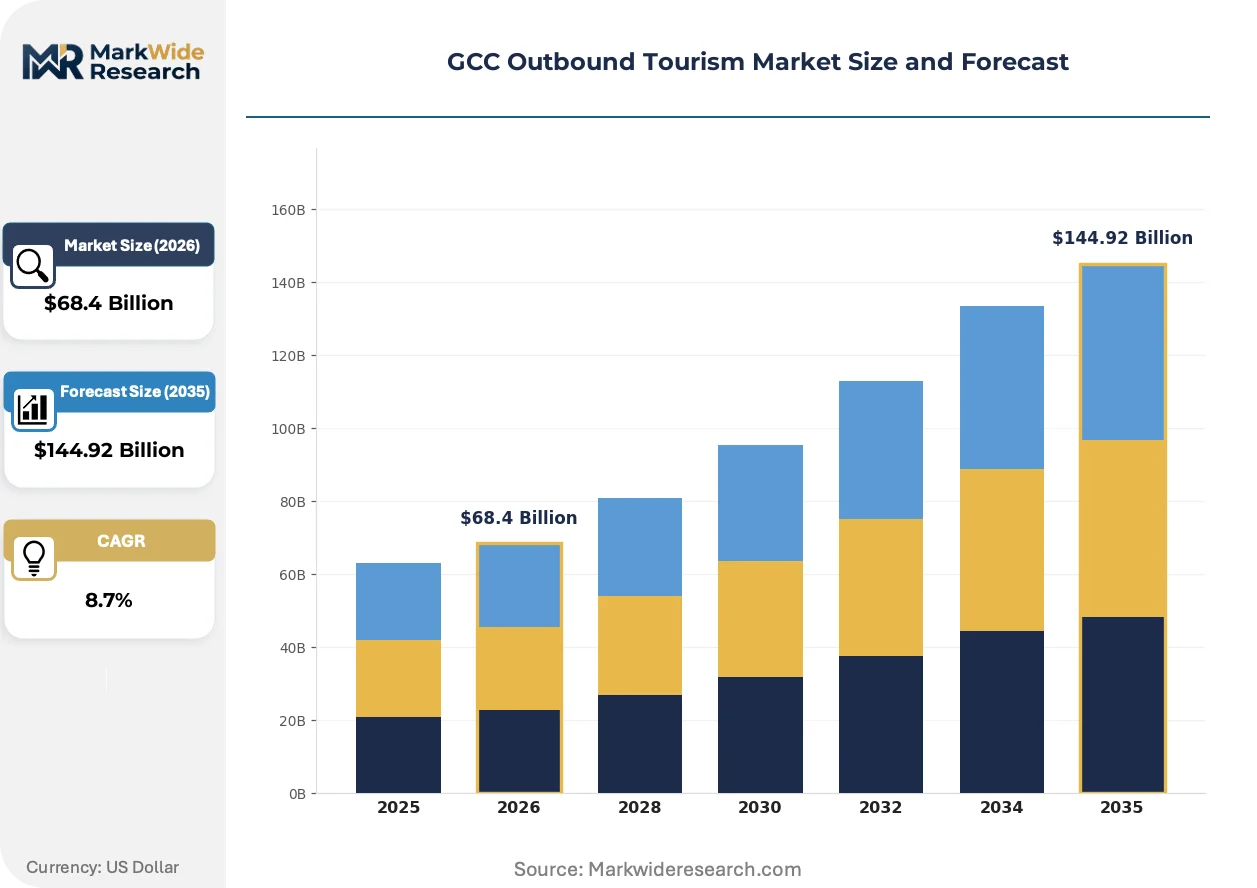
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Purpose of Travel: Leisure, Business, Education, Medical Tourism, Cultural Exploration, Pilgrimage Traveler Age Group: 18-25, 26-35, 36-50, 51-65, Above 65 Booking Channel: Online Travel Agencies, Direct Airline Websites, Travel Agents, Mobile Apps, Tour Operators, Corporate Travel Desks Accommodation Type: Luxury Hotels, Boutique Hotels, Serviced Apartments, Hostels, Vacation Rentals, Eco-Lodges |
| Companies Covered | Kanoo Travel, Al-Hokair Group, Al Futtaim Travel, Al Naboodah Travel, Belhasa Tourism & Travel, Al Ghanim Travel, Al Mosafer, ITL World, Al Rostamani Travel and Holidays, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Outbound Tourism Market Shifts & Advancements
Artificial intelligence and biometric identity systems are compressing booking-to-departure timelines while regulatory coordination across Gulf aviation authorities is reshaping competitive access to destination markets.
Dynamic packaging algorithms are integrating real-time flight, hospitality, and experience inventory into single-transaction mobile bookings. Younger travelers in the 26-35 bracket are adopting these tools fastest, collapsing the traditional multi-day research window into minutes. This compression is integrating last-minute inventory clearance into primary revenue management strategies.
Saudi Arabia's General Authority of Civil Aviation is negotiating open-skies provisions with ASEAN regulators, expanding fifth-freedom rights for Gulf carriers into secondary Indonesian and Malaysian destinations. Low-cost subsidiaries of full-service airlines are capturing this incremental capacity. Medical tourism coordinators are responding by diversifying approved-provider networks beyond traditional Bangkok and Kuala Lumpur clusters.
Subscription-based travel clubs are displacing commission-driven agency relationships among high-frequency leisure households in Dubai and Riyadh. These memberships bundle annual trip credits with concierge services and price-protection guarantees. Kuwaiti and Qatari expatriate segments show the fastest uptake, prioritizing transparent total-cost-of-ownership over per-transaction price comparison.
GCC Outbound Tourism Market Segmentation
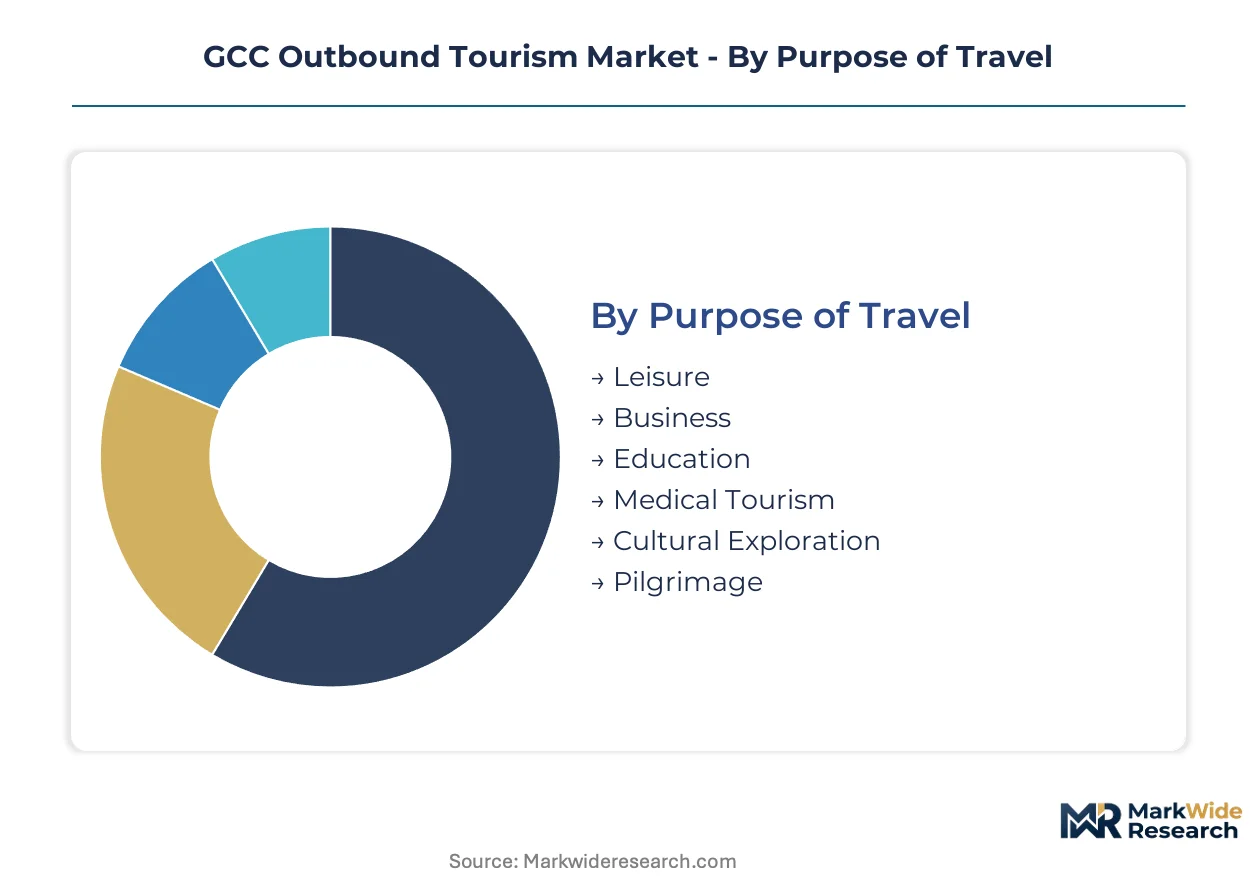
GCC outbound tourism segmentation reveals divergent spending patterns across trip purpose, generational cohorts, and booking behaviors. Understanding these fault lines enables targeted capacity allocation and revenue management strategies for aviation and hospitality stakeholders.
Purpose of Travel:
Expenditure intensity and trip duration vary sharply by travel motivation, with medical and pilgrimage journeys commanding premium pricing while leisure volumes dominate absolute departures.
- Leisure:Beach resorts, shopping corridors, and entertainment destinations absorb the largest share of outbound flight capacity from Dubai and Riyadh. Demand concentrates in European summer windows and Southeast Asian winter escapes, with Saudi Arabia's e-visa platform unlocking first-time leisure mobility for previously documentation-constrained households.
- Medical Tourism:Extended-stay healthcare journeys to Thai and German facilities generate the highest per-trip expenditure through companion travel and post-procedure recovery periods. MOHAP-certified provider directories in the UAE streamline patient routing and elongate average trip duration.
- Business:Corporate travel desks retain pricing power through negotiated volume contracts, though mobile expense management APIs are displacing legacy intermediaries in mid-market segments.
- Education:Long-duration student mobility to UK, US, and Australian universities creates predictable seasonal demand with lower per-trip margins but high loyalty value.
- Cultural Exploration:Heritage tourism to European and East Asian destinations is expanding as Saudi Vision 2030 promotional co-investments raise destination awareness.
- Pilgrimage:Umrah and ziyarat travel maintains steady volumes with constrained price elasticity due to religious obligation, though secondary pilgrimage destinations beyond Mecca and Medina are gaining traction.
Leisure leads volumes today; medical tourism is gaining share fastest through accredited provider network expansion.
Traveler Age Group:
Digital adoption thresholds and disposable income curves create distinct service requirements across generational bands, with platform preferences shifting abruptly at the 35-year boundary.
- 26-35:Dynamic packaging algorithms and single-transaction mobile bookings collapse research-to-purchase timelines to minutes. This cohort drives adoption of subscription-based travel clubs in Dubai and Riyadh, prioritizing transparent total-cost-of-ownership over per-transaction comparison.
- 36-50:Family-centric travel with multi-generational companion requirements commands premium accommodation and experience bundling. Demand concentrates in school holiday windows with inflexible departure dates.
- 18-25:Price-sensitive exploration travel favors hostels, low-cost carriers, and peer-reviewed digital booking platforms with minimal service layer.
- 51-65:Comfort-prioritized leisure with extended trip duration and destination familiarity preferences; slower digital adoption sustains travel agent relationships.
- Above 65:Medical tourism and pilgrimage concentration with high companion-to-traveler ratios and accessibility requirements shaping accommodation selection.
The 26-35 bracket commands platform innovation investment; the 51-65 segment delivers the highest margin per departure.
Booking Channel:
Channel selection correlates with trip complexity, corporate policy constraints, and traveler digital fluency, creating fragmented intermediary economics.
- Online Travel Agencies:Aggregated inventory comparison with price transparency dominates younger demographic acquisition, though commission compression pressures platform profitability.
- Corporate Travel Desks:Policy-enforced booking with negotiated rate access and duty-of-care compliance sustains relevance in regulated industries despite mobile platform encroachment.
- Direct Airline Websites:NDC-enabled connectivity and loyalty program integration are reclaiming share from intermediaries on trunk routes where Gulf carriers dominate capacity.
- Mobile Apps:Last-minute inventory clearance and experience bundling target spontaneous departure decisions with geolocation-triggered offers.
- Travel Agents:Complex multi-destination itineraries and visa documentation services sustain traditional intermediary roles for pilgrimage and medical tourism segments.
- Tour Operators:Packaged experiences with ground handling and destination management integration capture risk-averse first-time outbound travelers.
Online Travel Agencies lead transaction volumes today; corporate travel tech convergence is climbing the fastest through API-based expense integration.
Accommodation Type:
Property selection reflects trip purpose alignment, with medical and business travel demanding service reliability while leisure tolerates experience trade-offs for cost reduction.
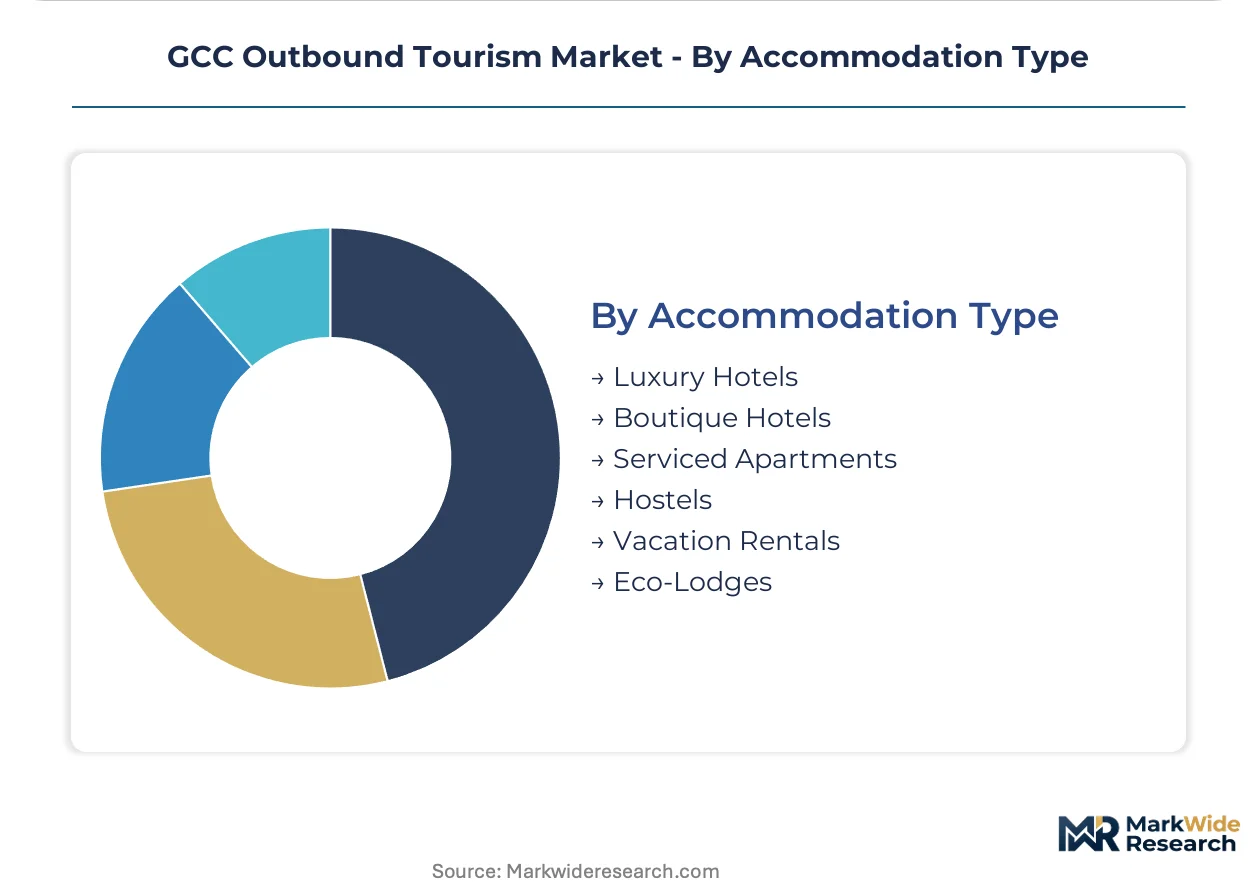
- Luxury Hotels:Full-service properties with concierge, spa, and dining integration capture high-net-worth leisure and business segments in London, Paris, and Bangkok corridors. Kanoo Travel's corporate relationships and Al Futtaim's vertical hospitality control sustain premium channel access.
- Serviced Apartments:Extended-stay configurations with kitchen facilities and reduced service frequency match medical tourism recovery periods and education-sector long-duration stays.
- Boutique Hotels:Design-focused properties with localized experience curation attract cultural exploration segments seeking Instagram-differentiated stays.
- Vacation Rentals:Platform-mediated private accommodation with multi-bedroom configurations serves family leisure with cost efficiency and space requirements.
- Eco-Lodges:Sustainability-certified properties with nature immersion programming capture emerging demand from environmentally conscious younger travelers.
- Hostels:Minimal-service shared accommodation with social programming targets 18-25 price-sensitive exploration travel.
Luxury hotels lead revenue per available room today; serviced apartments are expanding most quickly through medical tourism companion stay elongation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-net-worth household concentrations in Dubai and Riyadh anchor outbound departure volumes, while emerging mobility corridors in secondary Gulf cities reshape origin-destination pairings under expanded air service agreements.
United Arab Emirates
Dubai International Airport and Abu Dhabi Zayed International Airport process the highest outbound passenger volumes from the Gulf, with Emirates and Etihad dominating trunk route capacity to European and Southeast Asian leisure destinations. MOHAP-certified medical tourism networks streamline patient routing to Thai healthcare facilities, elongating average trip duration. The Dubai corridor concentrates luxury hospitality demand through Kanoo Travel's corporate relationships and Al Futtaim's vertical control of destination management services.
Saudi Arabia
Riyadh and Jeddah departure volumes are compressing the UAE's historical dominance as the General Authority of Civil Aviation negotiates expanded bilateral capacity agreements with ASEAN regulators. The e-visa platform and 96-hour transit schemes under Vision 2030 unlock first-time outbound mobility for previously documentation-constrained households. King Abdulaziz International Airport in Jeddah anchors pilgrimage-related outbound flows, while Absher platform integration creates biometric exit processing bottlenecks during peak seasonal windows.
Qatar
Hamad International Airport serves as a premium-tier departure hub with Qatar Airways commanding pricing power on European and South Asian trunk routes. Expatriate segments in Doha show fastest uptake of subscription-based travel clubs, prioritizing transparent total-cost-of-ownership over per-transaction comparison. The national carrier's fifth-freedom rights negotiations are expanding access to secondary Indonesian and Malaysian destinations.
Kuwait
Kuwait International Airport maintains lower outbound penetration per capita than Dubai or Riyadh, presenting whitespace for digital-first booking platforms targeting price-sensitive segments. The 26-35 demographic drives adoption of dynamic packaging algorithms and mobile-first inventory clearance tools. Legacy travel agent relationships persist for complex multi-destination itineraries and visa documentation services.
Bahrain
Bahrain International Airport serves as a compact departure point with concentrated business travel demand through corporate travel desk relationships. The island's expatriate-heavy population sustains steady leisure volumes to South Asian destinations with shorter average trip duration. Regulatory coordination with Saudi Arabia's General Authority of Civil Aviation shapes cross-border air service access for Bahraini residents.
GCC Outbound Tourism Market Competitive Landscape
Top-tier vendors anchor corporate and luxury leisure segments, while mid-tier digital platforms compete on price transparency and mobile booking velocity. The vendor base stratifies across heritage travel agencies with century-old relationships, vertically integrated hospitality-holding groups, and technology-native booking platforms. Three archetypes dominate: legacy corporate travel desks, asset-heavy destination management operators, and algorithm-driven aggregators. Competitive moves concentrate on API-based expense management integration and direct airline NDC connectivity to bypass legacy GDS intermediaries.
Within the heritage agency tier, Kanoo Travel represents established corporate relationship dominance, while Al Futtaim Travel exemplifies vertical integration through hospitality asset control. Al Mosafer occupies a position within the digital-native price-competitive segment targeting younger demographics through transparent booking platforms. These three anchors illustrate the competitive tension between relationship-driven intermediation and technology-enabled disintermediation reshaping Gulf outbound travel distribution.
| Leading Market Players |
|---|
| Kanoo Travel |
| Al-Hokair Group |
| Al Futtaim Travel |
| Al Naboodah Travel |
| Belhasa Tourism & Travel |
| Al Ghanim Travel |
| Al Mosafer |
| ITL World |
| Al Rostamani Travel and Holidays |
| Others |
Supply & Pricing Matrix
Saudi Vision 2030 sustainability mandates for aviation emissions disclosure are gating both qualified carrier supply and premium-tier pricing access, as Gulf carriers invest in fleet modernization to maintain route eligibility while budget subsidiaries capture price-sensitive segments through unbundled service models.
Pricing Analysis
Bundled concierge services versus unbundled seat-only inventory defines the pricing split across GCC outbound channels. Subscription-based travel clubs command annual commitments with price-protection guarantees, while dynamic packaging platforms compete on per-transaction transparency. Three-tier pricing structure across premium, standard, and economy levels reflects cabin class, loyalty tier, and advance purchase windows. Cost compression in economy leisure bookings intensifies as low-cost carriers expand bilateral capacity agreements. Corporate travel desks show lowest price sensitivity due to policy-enforced duty-of-care requirements.
Supply Chain Analysis
Single-source vulnerability sits with Emirates, Saudia, and Qatar Airways dominating trunk route seat allocation across Dubai, Riyadh, and Doha departure hubs. Aviation fuel procurement draws from Singapore, Rotterdam, and Fujairah refining clusters, while in-flight catering and ground handling services rest on Jeddah, Bangkok, and Kuala Lumpur operational bases. Tariff exposure through bilateral air service renegotiations threatens route profitability. Distribution runs through GDS terminals, NDC-enabled direct connectivity, and mobile app inventory clearance in parallel channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC outbound tourism market functions as a stable compounder anchored by irreversible visa liberalization and rising household mobility across Saudi Arabia and secondary Gulf cities.
For Market Incumbents: Deepen corporate travel desk relationships through API-based expense management integration to counter displacement by mobile booking platforms. Expand MOHAP-certified medical tourism provider networks to capture companion stay elongation and post-procedure recovery margins. Anchor position in Riyadh and Jeddah corridors as Saudi departure volumes compress UAE historical dominance.
For New Entrants and Emerging Players: Saudi Arabia's General Authority of Civil Aviation bilateral capacity expansion with ASEAN regulators opens a window for digital-first platforms targeting Kuwait and Bahrain underpenetrated segments. Capture 26-35 demographic adoption of subscription-based travel clubs through transparent total-cost-of-ownership positioning. Prioritize Arabic-language UX localization and regional payment gateway integration as the critical go-to-market enabler.
For Investors and Strategic Acquirers: Roll-up economics work for mid-tier digital booking platforms because fragmented intermediary economics across corporate desks, OTAs, and mobile apps create consolidation arbitrage. Target acquisition candidates with established NDC-enabled airline connectivity and halal tourism destination management capabilities. Monitor Saudi Absher platform biometric processing bottlenecks during peak seasonal windows as the operational inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| NDC-Enabled Direct Airline Connectivity | Bypasses legacy GDS intermediaries to reclaim margin on Emirates and Saudia trunk routes. |
| Halal Tourism Infrastructure Investment | Unlocks Muslim-majority European and East Asian markets through prayer facility certification. |
| Medical Tourism Provider Network Expansion | MOHAP-certified directories streamline patient routing to Thai healthcare facilities. |
| Subscription-Based Travel Club Launch | Kuwaiti and Qatari expatriate segments prioritize transparent annual commitment models. |
| Dynamic Packaging Algorithm Deployment | Collapses research-to-purchase timelines for 26-35 demographic mobile adoption. |
Research Methodology
Bottom-up traveler cohort modeling reconciled against top-down aviation capacity tracking forms the analytical core of this study. Primary interviews with airline network planners, corporate travel procurement managers, hotel revenue directors, and medical tourism coordinators combined with secondary validation from IATA passenger traffic data, General Authority of Civil Aviation bilateral agreement filings, and MOHAP-certified provider registries. Triangulation across departure volume statistics, hospitality occupancy reports, and OTA transaction disclosures ensures cross-source consistency.
Historical trendline analysis of trip purpose segmentation, generational booking behavior shifts, and accommodation type preferences established baseline growth patterns across the projection horizon. Modeled dimensions include travel purpose category, age bracket digital adoption thresholds, booking channel fragmentation, and property service tier. CAGRs derived from elasticity-adjusted expenditure projections and seat capacity expansion schedules, with medical tourism companion ratios and e-visa platform penetration rates as key forecast inputs.
Revisions become necessary when biometric exit processing disruptions, currency peg volatility against Asian destination markets, or air service agreement renegotiations materialize beyond baseline assumptions. Forecasts reflect documented parameters around visa policy implementation timelines and fleet delivery schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Middle East and Africa Travel Retail Market
Travel and Tourism
Hong Kong Outbound Tourism Market
Travel and Tourism
Global Duty-Free and Travel Retail Market
Travel and Tourism
Indonesia Sustainable Tourism Market
Travel and Tourism
North America Driving Vacation Market
Travel and Tourism
India Wellness Tourism Market
Travel and Tourism
Global Enotourism Market
Travel and Tourism
France Luxury Travel Market
Travel and Tourism
Inflight Shopping Market
Travel and Tourism
Leisure Travel Market
Travel and Tourism
South Korea Tourism Market
Travel and Tourism
South Korea Sports Tourism Market
Travel and Tourism
Europe Tourism Vehicle Rental Market
Travel and Tourism
Surfing Tourism Market
Travel and Tourism
Maldives Hospitality Market
Travel and Tourism
Airline Retailing Market