
 India Big Data Analytics Market | 2026-2036
India Big Data Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
India Big Data Analytics Market Insights
Platform licensing revenue is tilting from perpetual on-premise contracts toward recurring cloud-native subscriptions. Fractal Analytics leverages its AI research labs in Mumbai and Bengaluru to sustain premium positioning in predictive modeling for consumer packaged goods. TCS anchors its dominance through captive delivery centers that integrate data engineering with enterprise ERP modernization. Mu Sigma competes on apprenticeship-driven talent density, training over a thousand decision scientists annually at its Bengaluru headquarters.
Big data analytics encompasses the systematic computational examination of large, heterogeneous datasets—structured transaction logs, unstructured social media streams, and semi-structured sensor outputs—to uncover patterns, correlations, and predictive signals. Hadoop distributed processing frameworks handle petabyte-scale batch workloads across commodity server clusters, while in-memory computing accelerates real-time analytical queries for sub-second decision cycles. Cloud-based deployment is capturing the fastest expansion as enterprises migrate data lakes from capital-intensive server farms to elastic infrastructure, though on-premise configurations retain share in BFSI segments governed by data localization mandates. Predictive analytics commands the deepest margin pools where proprietary algorithms translate into outcome-based client contracts.
India's Digital Personal Data Protection Act imposes strict purpose-limitation and cross-border transfer rules on analytics vendors processing citizen information, compelling architecture redesigns for consent management and encryption. BIS cloud security standards and RBI guidelines on outsourced IT services further constrain how financial institutions engage third-party data processors. SEBI's mandate for algorithmic trading audit trails generates specialized compliance demand from capital market participants. Stakeholders must weigh the cost of multi-jurisdictional data residency against the latency advantages of centralized cloud regions.
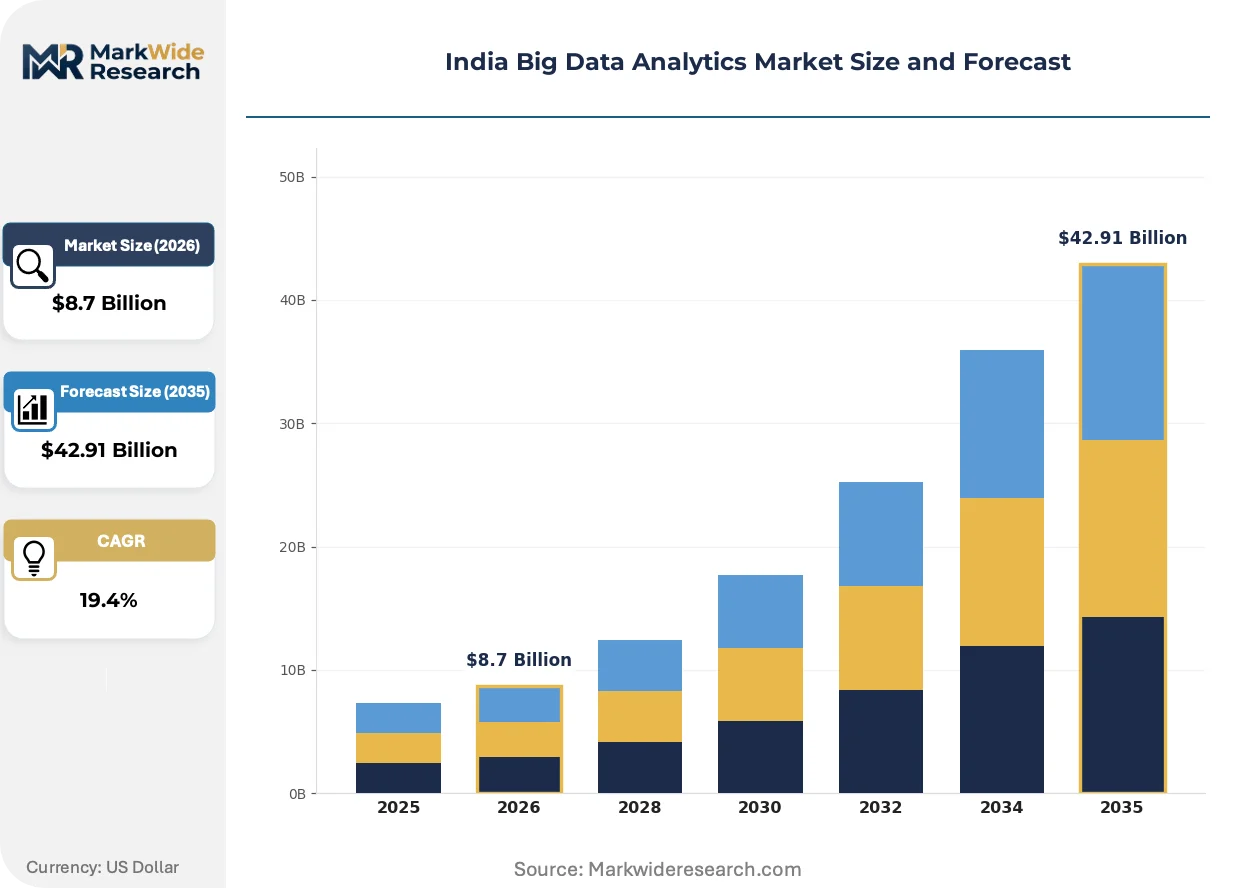
Market Dynamics
India's Digital Personal Data Protection Act is forcing analytics vendors to rebuild data architectures around consent management and localization requirements, compressing margins for cross-border processing models while creating competitive advantage for domestic cloud infrastructure providers.
Growth Catalysts
- Real-time fraud detection mandates:RBI guidelines on digital payments security and SEBI's algorithmic trading audit requirements are compelling BFSI institutions to upgrade batch-processing systems to streaming analytics platforms.
- Cloud infrastructure clustering:Karnataka's Bengaluru-Mysuru corridor combines hyperscale data center investments with specialized university pipelines feeding decision science talent directly into vendor R&D centers.
- PLI scheme incentives:The government's production-linked incentive scheme for IT hardware manufacturing is reducing server and storage equipment costs for domestic analytics deployments.
Market Restraints
- Data localization compliance costs:RBI's strict guidelines on outsourced IT services for financial institutions mandate dedicated in-country infrastructure, raising operational expenditure for multinational vendors.
- Talent concentration risk:Over 60 percent of specialized data engineering skills pool in Bengaluru and Hyderabad, creating wage inflation and retention vulnerability for firms outside these clusters.
- GPU supply bottlenecks:AI/ML model training depends on NVIDIA and AMD accelerator imports subject to US export controls and DGFT licensing delays.
Strategic Opportunities
- Tier-2 city expansion:Pune, Chennai, and Kochi offer untapped talent pools at 30-40 percent lower cost structures for delivery center establishment.
- Edge analytics integration:Convergence of 5G rollout with industrial IoT sensor networks creates demand for distributed processing architectures at manufacturing plant floors.
- Outcome-based contracting:BIS cloud security certification enables domestic vendors to offer performance-guaranteed pricing models previously restricted to global system integrators.
Industry Challenges
- Decision science talent scarcity:Mu Sigma's apprenticeship model trains roughly one thousand analysts annually, yet industry demand outstrips supply by a factor of three for candidates with both statistical modeling and domain expertise.
- Legacy ERP integration complexity:TCS and comparable system integrators dedicate 40-50 percent of project timelines to data pipeline engineering across incompatible SAP, Oracle, and custom-built transaction systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Big Data Analytics Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Data Mining, Predictive Analytics, Data Visualization, Descriptive Analytics Technology: Hadoop, NoSQL, In-Memory Computing, Cloud Computing End User: Retail, Healthcare, BFSI, Telecommunications Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Fractal Analytics, Mu Sigma, Tiger Analytics, SG Analytics, Wipro, TCS, Accenture, LatentView Analytics, EXL Service, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Big Data Analytics Market Trends and Innovations
Streaming analytics architectures are collapsing the latency gap between data generation and actionable insight, reshaping competitive requirements across India's regulated industries.
In-memory computing is collapsing the performance penalty that previously separated real-time from batch analytical workloads. Large private-sector banks now process transaction streams through Apache Flink and Spark Streaming clusters to flag anomalous patterns within sub-second windows. This compression eliminates the competitive differentiation that legacy overnight batch systems once provided, forcing mid-tier vendors to upgrade infrastructure or exit high-frequency use cases entirely.
India's Digital Personal Data Protection Act imposes purpose-limitation and cross-border transfer restrictions that segment vendor capabilities by compliance maturity. Financial institutions governed by RBI outsourcing guidelines must maintain audit trails demonstrating data residency and encryption standards. SEBI-registered brokers are deploying specialized compliance modules to capture algorithmic decision logs, creating a secondary software layer that domestic vendors are capturing ahead of multinational competitors.
Enterprise buyers are consolidating vendor relationships from point-solution portfolios to integrated platform subscriptions. Chief data officers at manufacturing and retail conglomerates now prioritize single-contract accountability for data engineering, model deployment, and governance tooling. This preference rotation favors captive delivery centers and full-stack domestic providers over specialized boutique analytics shops, with the shift most visible in Mumbai and Delhi-NCR headquarters of diversified industrial groups.
India Big Data Analytics Market Segmentation
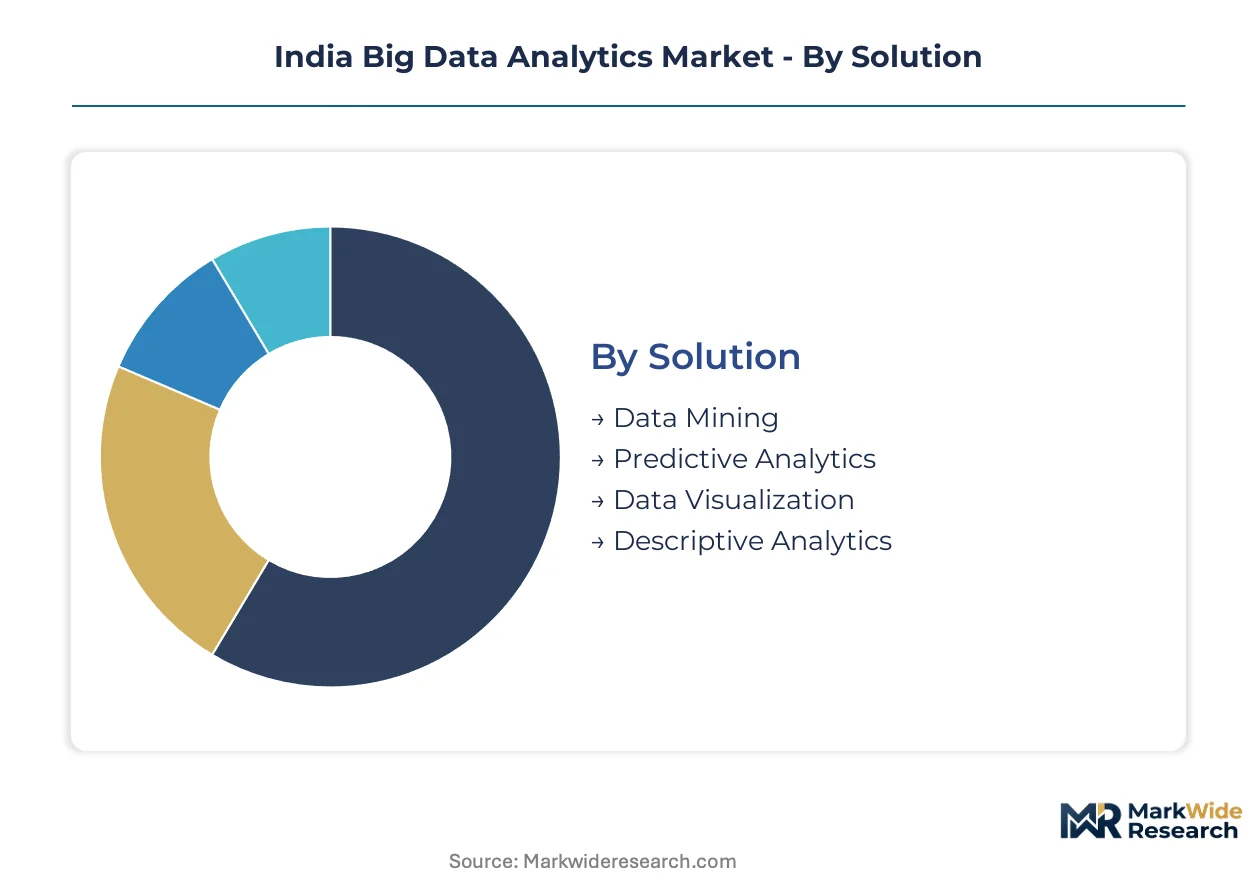
Segmentation in India's big data analytics market reveals distinct procurement rhythms across solution types and deployment modes. Buyers cycle through visualization tools rapidly while predictive platforms lock in multi-year enterprise commitments.
Solution:
Cycle times vary sharply across solution categories, with visualization tools refreshing every 18-24 months versus predictive analytics contracts extending 5-7 years.
- Predictive Analytics:Proprietary algorithmic engines process historical patterns to forecast demand, risk, and operational outcomes. BFSI institutions in Mumbai and Bengaluru anchor procurement volume, driven by RBI mandates for real-time fraud detection and stress-testing automation.
- Data Visualization:Interactive dashboard layers translate complex datasets into executive-facing graphical interfaces. Retail conglomerates headquartered in Delhi-NCR refresh these tools most frequently, pressured by merchandising teams demanding mobile-first consumption formats.
- Data Mining:Pattern recognition systems extract actionable signals from unstructured text, image, and sensor streams.
- Descriptive Analytics:Historical reporting modules aggregate past performance into standardized KPI frameworks.
Predictive Analytics anchors the volume base while Data Visualization gains share at the steepest rate.
Technology:
Cost tiers separate capital-intensive on-premise infrastructure from elastic cloud consumption models with diverging margin profiles.
- Cloud Computing:Elastic infrastructure pools allocate compute resources on demand through hyperscale provider networks. Karnataka's Bengaluru-Mysuru corridor concentrates deployment activity, where dedicated data center investments overlap with PLI scheme subsidies for domestic server manufacturing.
- In-Memory Computing:RAM-resident processing architectures eliminate disk I/O latency for sub-second analytical queries. Capital market participants regulated by SEBI drive specialized demand, requiring algorithmic trading audit trails with millisecond timestamp granularity.
- Hadoop:Distributed batch processing frameworks partition petabyte-scale workloads across commodity server clusters.
- NoSQL:Schema-flexible databases accommodate unstructured social media, IoT sensor, and log file ingestion.
Hadoop retains the largest installed base though Cloud Computing expands most quickly as data localization requirements reshape vendor selection criteria.
End User:
Application intensity varies by sector data maturity, with financial services leading algorithmic sophistication and healthcare trailing due to CDSCO diagnostic data restrictions.
- BFSI:Banking, insurance, and capital markets operations deploy streaming analytics for transaction monitoring, credit scoring, and regulatory reporting. Mumbai's financial district generates concentrated demand, compelled by SEBI algorithmic audit mandates and RBI outsourcing guidelines requiring in-country data residency.
- Telecommunications:Network optimization and subscriber churn prediction consume massive subscriber usage datasets. Hyderabad's telecom R&D clusters anchor procurement, fueled by TRAI quality-of-service benchmarking requirements and 5G rollout infrastructure investments.
- Retail:Merchandising analytics and supply chain optimization leverage point-of-sale and e-commerce transaction streams.
- Healthcare:Clinical decision support and epidemiological surveillance face constrained data sharing under Digital Personal Data Protection Act purpose-limitation rules.
BFSI contributes the deepest revenue pool while Telecommunications climbs fastest on 5G-enabled edge analytics deployment.
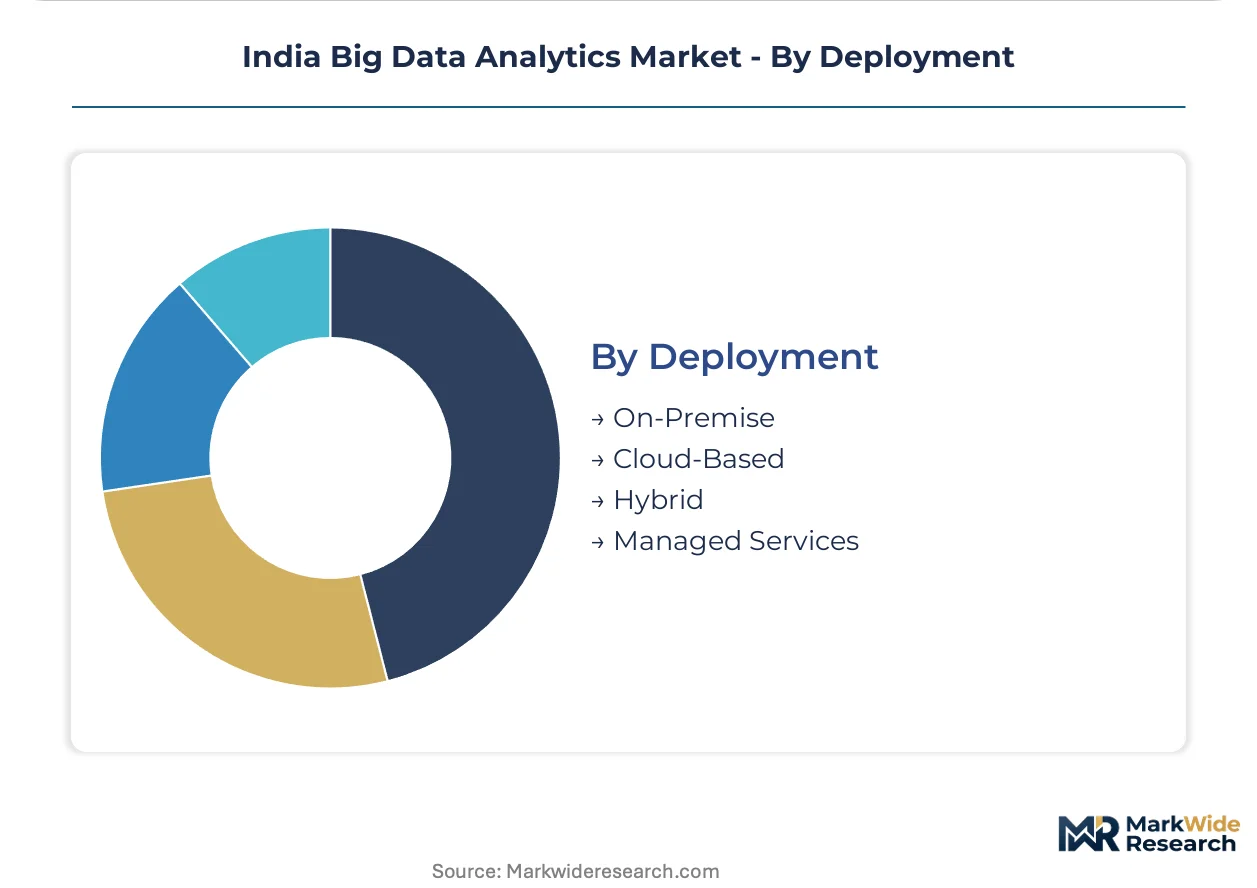
Deployment:
Customer type stratification separates regulated entities requiring captive infrastructure from growth-stage firms prioritizing operational flexibility.
- Cloud-Based:Third-party hosted environments deliver elastic scalability without capital expenditure commitment. Bengaluru-headquartered SaaS analytics vendors capture disproportionate share, enabled by BIS cloud security certification qualifying them for public sector and regulated industry contracts previously reserved to global integrators.
- Hybrid:Split architectures maintain sensitive data on-premise while bursting analytical workloads to external infrastructure. Manufacturing conglomerates in Pune and Chennai favor this model, balancing IP protection for proprietary process data against compute elasticity for demand forecasting.
- On-Premise:Dedicated server installations satisfy data localization mandates and legacy system integration requirements.
- Managed Services:Outsourced operational accountability bundles infrastructure, platform, and analytical talent.
On-Premise retains dominant share among RBI-regulated entities while Hybrid deployment accelerates most sharply as manufacturing firms reconcile legacy ERP constraints with cloud agility imperatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Karnataka's technology corridor demonstrate the least price sensitivity, absorbing premium cloud-native subscriptions, while procurement teams in tier-2 manufacturing hubs negotiate hardest on perpetual license costs.
Karnataka
Bengaluru-Mysuru anchors the deepest talent concentration, with hyperscale data centers overlapping specialized university pipelines feeding decision science roles. RBI outsourcing guidelines and BIS cloud security standards shape vendor qualification requirements. Fractal Analytics and Mu Sigma operate AI research labs and apprenticeship centers here, capturing premium positioning in predictive modeling contracts.
Maharashtra
Mumbai's financial district generates concentrated BFSI demand for real-time fraud detection and algorithmic trading audit trails. SEBI mandates for millisecond-timestamp granularity and RBI data localization rules compel dedicated in-country infrastructure investments. Captive delivery centers from system integrators dominate procurement, integrating data engineering with legacy ERP modernization programs.
Telangana
Hyderabad's telecom R&D clusters drive network optimization and subscriber churn prediction workloads. TRAI quality-of-service benchmarking requirements and 5G rollout investments accelerate edge analytics procurement. GPU supply bottlenecks from DGFT licensing delays constrain AI/ML model training capacity for vendors operating here.
Tamil Nadu
Chennai's manufacturing base favors hybrid deployment architectures, balancing IP protection for proprietary process data against cloud elasticity for demand forecasting. PLI scheme subsidies for IT hardware manufacturing reduce server costs for domestic analytics deployments. Wage inflation remains 30-40 percent below Bengaluru levels for comparable data engineering skills.
Delhi-NCR
Retail conglomerates headquartered here refresh data visualization tools most frequently, pressured by merchandising teams demanding mobile-first consumption formats. Digital Personal Data Protection Act purpose-limitation rules segment vendor capabilities by compliance maturity. Enterprise buyers consolidate vendor relationships from point-solution portfolios toward integrated platform subscriptions.
India Big Data Analytics Market Competitive Landscape
Full-stack system integrators and specialized analytics boutiques split the market into distinct capability tiers. Consolidation pressure favors vendors with captive delivery centers and BIS cloud security certification qualifying for public sector contracts. Three archetypes dominate: apprenticeship-driven talent factories, hyperscale captive delivery networks, and cloud-native platform specialists. Competitive moves center on geographic expansion into tier-2 cities and outcome-based contracting models that shift risk to vendors.
Within the full-stack integrator tier, TCS anchors through captive delivery centers that bundle data engineering with enterprise ERP modernization, while Wipro occupies a position spanning infrastructure services through analytical application deployment. Among specialized analytics pure-plays, Fractal Analytics exemplifies premium positioning sustained through AI research investment, and Mu Sigma represents the apprenticeship-driven archetype training decision scientists at scale. LatentView Analytics sits within the mid-tier segment serving manufacturing and retail conglomerates with hybrid deployment expertise.
| Leading Market Players |
|---|
| Fractal Analytics |
| Mu Sigma |
| Tiger Analytics |
| SG Analytics |
| Wipro |
| TCS |
| Accenture |
| LatentView Analytics |
| EXL Service |
| Others |
Pricing and Supply Chain Analysis
The Mumbai-JNPT freight corridor's container handling cost dynamics amplify supply concentration effects across India's analytics vendor base, compressing margins for hardware-dependent deployments while enabling cloud-native providers to sustain premium subscription tiers through localized data center proximity.
Pricing Analysis
Managed services and extended support contracts generate lifetime value exceeding initial platform licensing by a factor of three for established vendors. Three-tier pricing structure across premium, standard, and economy levels segments buyers by compliance maturity and deployment complexity, with BFSI institutions absorbing premium tiers for RBI-mandated data residency while mid-market manufacturers negotiate standard offerings. Pricing pressure stems from GPU supply bottlenecks and DGFT licensing delays that inflate infrastructure costs for on-premise deployments. Retail conglomerates in Delhi-NCR demonstrate highest price sensitivity, cycling through visualization tools every 18-24 months to capture feature improvements without long-term commitment.
Supply Chain Analysis
Domestic server assembly capacity concentrates with Dixon Technologies and Lava International under PLI scheme incentives, supplemented by hyperscale cloud infrastructure from AWS, Microsoft Azure, and Google Cloud's Mumbai and Hyderabad regions. NVIDIA and AMD GPU imports from Taiwan and USA face DGFT licensing delays and US export control scrutiny, while domestic memory and storage component sourcing from Samsung India and Micron Technology's Gujarat facility reduces lead times for tier-1 deployments. Single-source vulnerability in AI accelerator supply chains threatens model training capacity for vendors outside Bengaluru's infrastructure cluster. Distribution runs through direct enterprise sales teams for large BFSI contracts, with channel partners penetrating mid-market manufacturing and retail segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's big data analytics market sits in early-cycle expansion, with Digital Personal Data Protection Act compliance mandates forcing architecture rebuilds that expand addressable spend per enterprise by 40-60 percent for consent management and localization tooling.
For Market Incumbents: Harden data residency capabilities through captive cloud infrastructure investments in Karnataka and Maharashtra to defend against domestic challengers with BIS cloud security certification. Deepen vertical integration into GPU provisioning through direct NVIDIA allocation agreements, bypassing distributor bottlenecks that constrain AI/ML delivery timelines. Lock in multi-year outcome-based contracts with manufacturing conglomerates before hybrid deployment expertise commoditizes. For New Entrants and Emerging Players: Establish a beachhead in tier-2 city delivery centers across Pune, Chennai, and Kochi, where wage arbitrage of 30-40 percent against Bengaluru enables competitive bidding for mid-market manufacturing analytics. Target the SEBI-mandated algorithmic trading audit trail segment, where compliance complexity deters generalist competitors and specialized modules command premium pricing. Lead with BIS cloud security certification as a qualification wedge for public sector contracts previously reserved to global integrators. For Investors and Strategic Acquirers: Apprenticeship-driven analytics boutiques with scalable decision science training pipelines represent the most defensible acquisition archetype in this talent-constrained market. Long-term viability hinges on structural supply-demand imbalance in decision science skills that persists through the projection horizon. Monitor DGFT GPU import license approval velocity as the critical inflection signal for AI/ML vendor capacity expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Analytics Platform Launch | Captures 5G-enabled industrial IoT demand from manufacturing plant floors in Tamil Nadu and Gujarat. |
| Consent Management Module Integration | Addresses Digital Personal Data Protection Act purpose-limitation requirements for BFSI clients in Mumbai. |
| Tier-2 City Delivery Center Expansion | Unlocks 30-40 percent cost arbitrage against Bengaluru for data engineering talent in Pune and Kochi. |
| BIS Cloud Security Certification Investment | Qualifies domestic vendors for public sector contracts previously restricted to global system integrators. |
| GPU Supply Agreement with Direct Allocation | Bypasses distributor bottlenecks and DGFT licensing delays constraining AI/ML model training capacity. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with chief data officers at BFSI institutions, platform engineering leads at hyperscale cloud providers, decision science directors at analytics boutiques, and procurement heads at manufacturing conglomerates. Secondary validation drew from RBI circulars on outsourced IT services, SEBI algorithmic trading audit guidelines, BIS cloud security standards, TRAI quality-of-service benchmarking reports, and PLI scheme disbursement disclosures. Bottom-up sizing of vendor revenue pipelines triangulated against top-down IT services spending allocation models.
Calibration across historical growth trajectories, regulatory implementation timelines, and infrastructure investment cycles shaped the analytical framework over the projection horizon. Segmentation dimensions modeled encompassed solution type, deployment architecture, end-user industry vertical, and geographic adoption cluster. CAGRs were derived from slope-consistent trajectory fitting anchored to disclosed vendor expansion plans and hyperscale data center commissioning schedules. Forecast inputs incorporated GPU import license approval rates, PLI scheme subsidy utilization, and university pipeline graduation volumes for decision science specializations.
Stress conditions across DGFT licensing delays, GPU supply disruptions, and talent wage inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and cloud infrastructure buildout cadence. Quarterly review of hyperscale data center commissioning announcements, PLI scheme beneficiary lists, and RBI circular issuance patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Legal Analytics Market
Analytics
Italy Geospatial Analytics Market
Analytics
North America Operational Intelligence Market
Analytics
Global Big Data Market
Analytics
Marketing Analytics Software Market
Analytics
Global Business Intelligence (BI) Software Market
Analytics
Asia-Pacific HR Analytics Market
Analytics
Speech and Voice Analytics Market
Analytics
Global Data Prep Market
Analytics
Global Digital Intelligence Platform Market
Analytics
CSP Network Analytics Market
Analytics
India Big Data Technology and Service Market
Analytics
Audio and Video Analytics Software Market
Analytics
Embedded Analytics Market
Analytics
Cloud Analytics Market
Analytics
Research and Development (Randd) Analytics Market