
 Encapsulated Flavors and Fragrances Market | 2026-2036
Encapsulated Flavors and Fragrances Market Size, Share, and Industry Trends Forecast 2026-2036
Encapsulated Flavors and Fragrances Market Analysis
The specialty ingredient distribution channel is narrowing as large flavor houses consolidate procurement relationships with multinational food and beverage clients. Kerry Group plc leverages its integrated taste and nutrition platform to sustain captive demand from global bakery and snack manufacturers. Givaudan SA anchors its position through deep R&D partnerships with European cosmetics brands seeking compliant fragrance encapsulation. International Flavors & Fragrances Inc. competes by extending its spray-drying capacity across North American and Asian production nodes.
Encapsulated flavors and fragrances are core-shell or matrix-embedded volatile compounds protected by edible polymers, typically 10–200 microns in diameter, designed for controlled release under thermal, mechanical, or pH triggers. Their primary commercial purpose is to extend shelf life, mask off-notes, and enable precise dosing in processed consumer goods. Microencapsulated flavors lead volume due to baked goods and confectionery demand, while aroma compounds command premium positioning in luxury personal care applications. Spray drying dominates manufacturing scale, though fluidized bed coating is displacing legacy methods where thermal sensitivity demands gentler processing.
FDA food additive regulations and EPA volatile organic compound standards shape permissible carrier chemistries and release profiles in the United States, while REACH registration requirements in Europe constrain synthetic aroma chemical portfolios and accelerate bio-based alternatives. The EU Green Deal's chemical sustainability targets are forcing reformulation timelines across fragrance oil suppliers serving cosmetics brands. Stakeholders must monitor evolving EPA hazard classifications and ECHA substance restrictions to anticipate which encapsulation technologies will retain market access.
Market Dynamics
Food manufacturers' procurement consolidation is compressing the specialty ingredient distribution channel, forcing encapsulation suppliers to embed directly into multinational supply chains or risk disintermediation.
Growth Catalysts
- EU Green Deal chemical sustainability targets:The framework mandates bio-based carrier reformulation, opening procurement windows for European fragrance oil suppliers serving cosmetics brands.
- Spray-drying capacity expansion:Fluidized bed coating is displacing legacy thermal methods where heat-sensitive aroma compounds require gentler processing parameters.
- Germany's fragrance house clustering:Hamburg-based coacervation expertise concentrates advanced R&D capabilities, drawing formulation partnerships from global personal care brands.
Market Restraints
- REACH registration complexity:ECHA substance restrictions constrain synthetic aroma chemical portfolios, forcing costly reformulation timelines for legacy encapsulation systems.
- Edible polymer input volatility:Gum arabic and modified starch supply concentrates in Sudan and Thailand, exposing processors to climate-driven price swings.
- Microcapsule size distribution limits:Standard 10–200 micron diameters fail to meet nano-scale delivery requirements for intracellular fragrance targeting in advanced cosmetics.
Strategic Opportunities
- India's processed food sector:FSSAI-compliant encapsulation systems for spice and flavor stability remain underpenetrated in domestic bakery and snack manufacturing.
- pH-triggered release convergence:Combining chitosan-wall microencapsulation with active packaging sensors enables intelligent shelf-life signaling for refrigerated goods.
- Direct-to-manufacturer platform distribution:Specialty chemical marketplaces are bypassing traditional flavor house intermediaries, reducing minimum order quantities for mid-tier food processors.
Industry Challenges
- Coacervation chemistry expertise scarcity:Formulation scientists capable of complex-phase separation for high-load fragrance encapsulation command premium compensation, constraining scale-up capacity.
- Multi-jurisdiction certification timelines:Simultaneous FDA food additive petitions and EFSA novel food evaluations extend product launch cycles by 18–36 months for global suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Encapsulated Flavors and Fragrances Market |
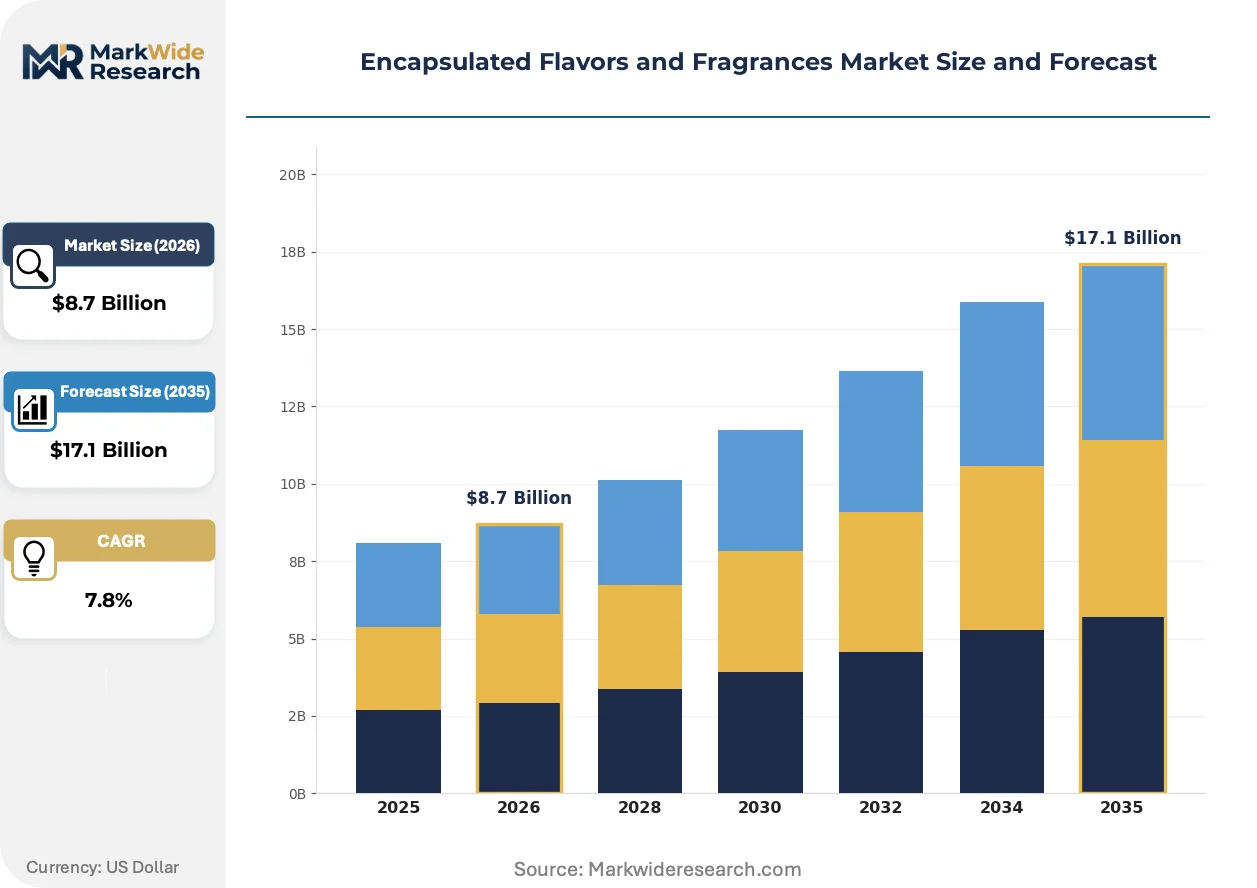
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Microencapsulated Flavors, Aroma Compounds, Fragrance Oils Application: Cosmetics, Food & Beverage, Household Products, Personal Care Technology: Spray Drying, Fluidized Bed Coating, Coacervation, Melt-Extrusion End User: Food Manufacturers, Beverage Companies, Cosmetics Brands, Household Care Producers |
| Companies Covered | Symrise AG, Kerry Group plc, Givaudan SA, Takasago International Corporation, Mane SA, International Flavors & Fragrances Inc., Sensient Technologies Corporation, Robertet SA, DSM-Firmenich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Encapsulated Flavors and Fragrances Market Emerging Trajectories
Digital formulation platforms are collapsing the traditional trial-and-error development cycle, enabling encapsulation houses to simulate release kinetics before physical prototyping.
Computational fluid dynamics modeling of spray-drying atomization is virtualizing the optimization of particle size distribution and wall-thickness uniformity. Mid-sized fragrance houses in Germany and the Netherlands are adopting these simulation suites to reduce pilot-scale batches. The technology is virtualizing capital deployment patterns, allowing regional players to compete with multinational R&D budgets without equivalent physical infrastructure.
REACH authorization requirements for synthetic aroma chemicals are accelerating bio-based carrier substitution across European fragrance oil portfolios. ECHA's expanding candidate list of substances of very high concern is forcing encapsulation houses to pre-register alternatives before sunset dates. Cosmetics brands serving Germany and France are now requiring bio-based content certification from suppliers to de-risk future compliance exposure.
Buyer concentration among multinational food processors is compressing supplier negotiation leverage and extending payment terms. Specialty encapsulation houses are responding by forming cooperative procurement consortia to secure polymer raw materials at scale. This consolidation dynamic is most visible in North American baked goods and confectionery supply chains, where three processors account for the majority of microencapsulated flavor volumes.
Encapsulated Flavors and Fragrances Market Segmentation
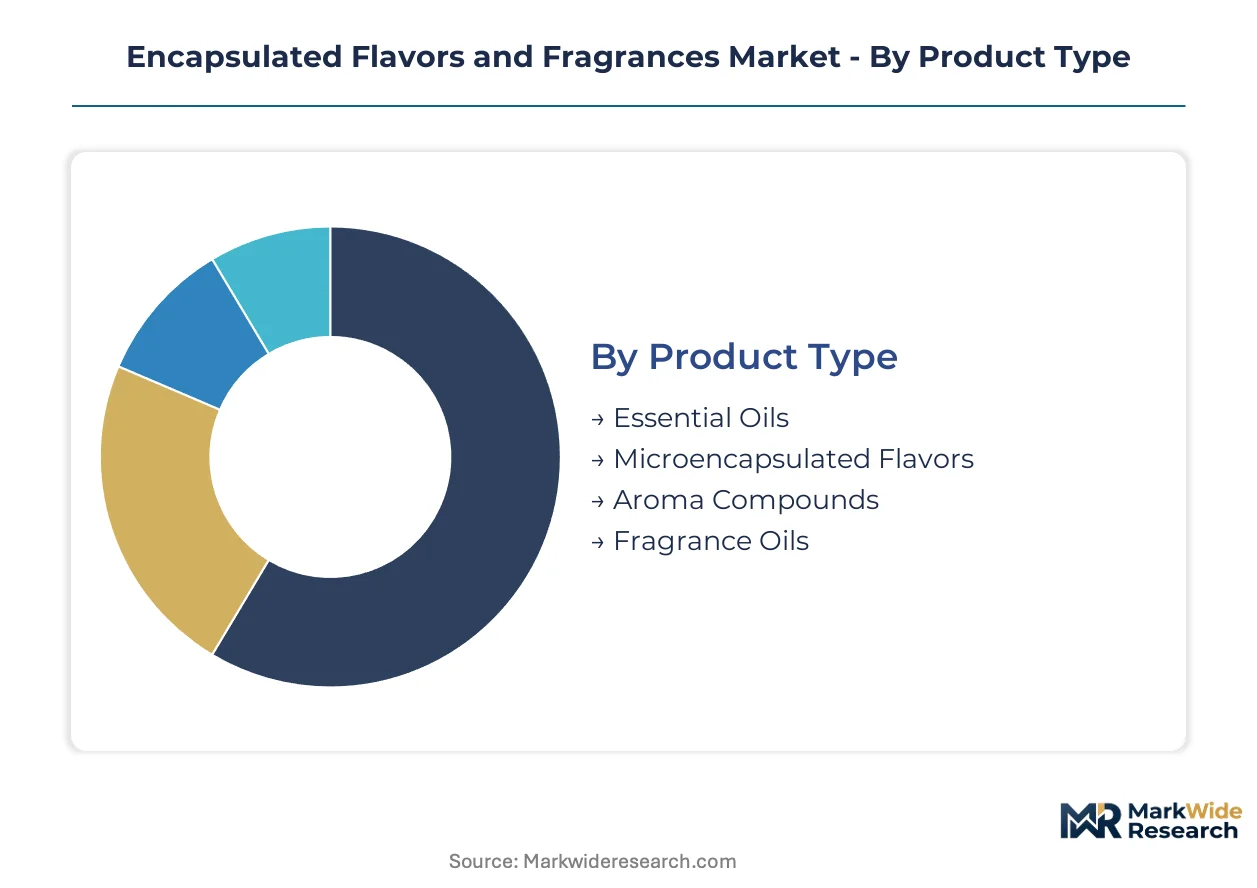
Encapsulated flavors and fragrances require precise technical matching between carrier chemistry and release trigger conditions. Segmentation reveals where formulation complexity commands premium positioning versus commodity scale.
Product Type:
Mature encapsulation formats dominate volume, while emerging high-load systems capture margin expansion in precision applications.
- Microencapsulated Flavors:Matrix-embedded volatile compounds in 10–200 micron diameters using modified starch or gum arabic walls. Bakery and confectionery processors in Germany and the United States absorb the majority of output, driven by shelf-stability requirements in extended distribution networks.
- Aroma Compounds:Synthetic and nature-identical molecules requiring thermal protection through core-shell architectures. Demand concentrates in French and Italian cosmetics brands seeking REACH-compliant fragrance delivery without synthetic aroma chemical restrictions.
- Essential Oils:Plant-derived terpenes and phenolics encapsulated for oxidation resistance.
- Fragrance Oils:Blended aromatic compounds for household and personal care matrices.
Microencapsulated flavors handles the majority of throughput; aroma compounds is the fastest mover on share.
Application:
Cost tier stratification separates mass-market food systems from premium personal care formulations requiring bio-based certification.
- Food & Beverage:Encapsulation systems for flavor masking, off-note suppression, and controlled release during thermal processing. North American baked goods manufacturers and Indian snack processors under FSSAI compliance drive procurement consolidation toward direct supplier relationships.
- Cosmetics:Fragrance encapsulation for skin-contact applications demanding chitosan or lipid-based carriers. German and French brands lead bio-based content certification requirements under EU Green Deal chemical sustainability targets.
- Personal Care:Shampoo, deodorant, and skincare applications requiring pH-triggered release.
- Household Products:Detergent and air freshener matrices tolerating cost-optimized spray-dried systems.
Food and beverage commands the largest volume position; cosmetics delivers the steepest expansion trajectory.
Technology:
Volume concentration favors thermal methods, while margin capture shifts toward gentle processing for heat-sensitive payloads.
- Spray Drying:Atomization of emulsified flavors into hot air streams, producing 20–100 micron particles with 20–50% flavor load. Scale economies concentrate in North American and Asian production nodes serving multinational food processors.
- Fluidized Bed Coating:Layer-by-layer deposition of molten or dissolved wall materials onto fluidized core particles. Hamburg-based fragrance houses deploy this method for thermal-sensitive aroma compounds requiring sub-60°C processing parameters.
- Coacervation:Complex-phase separation of hydrocolloids around oil cores for high-load fragrance encapsulation.
- Melt-Extrusion:Thermoplastic carbohydrate matrices extruded and milled for controlled dissolution release.
Spray drying handles the majority of throughput; fluidized bed coating is climbing the fastest on share.
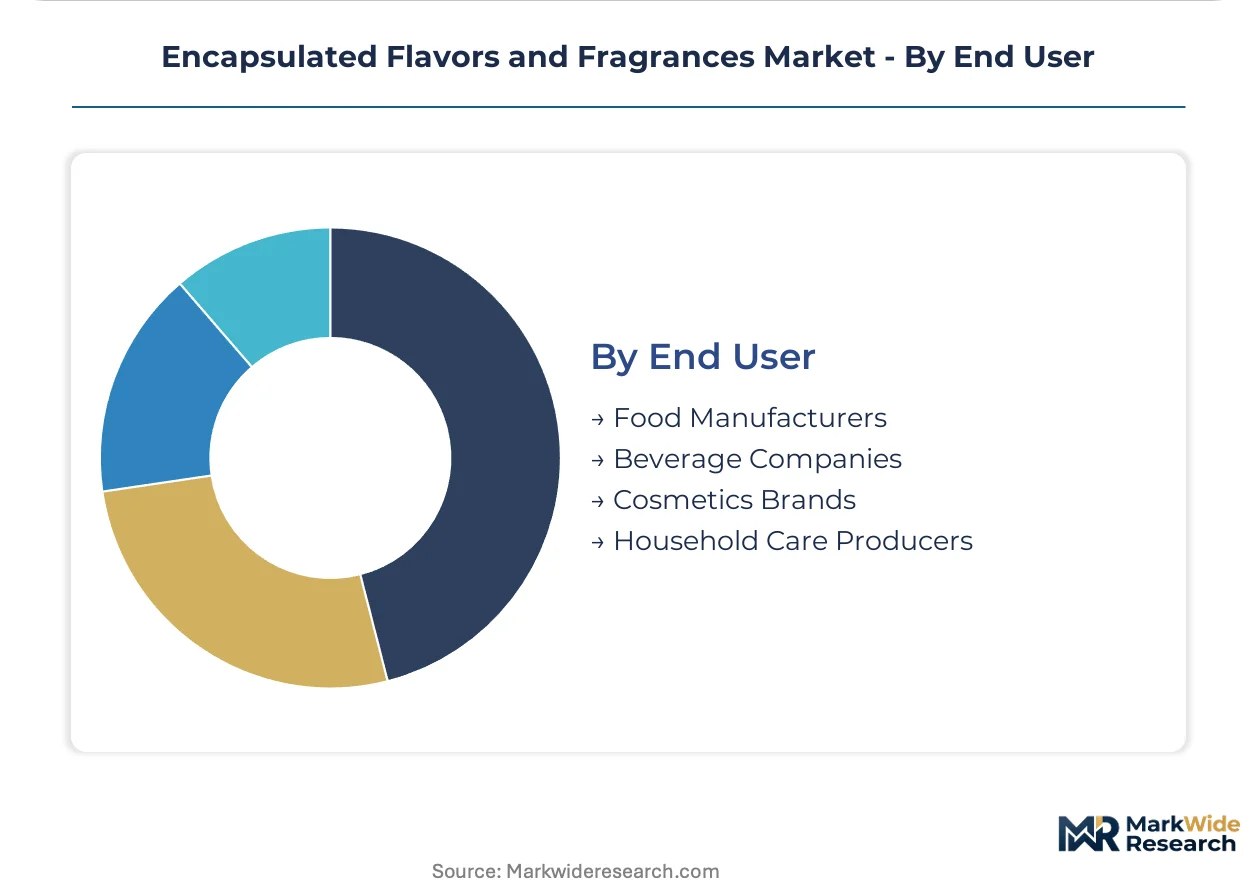
End User:
Customer type fragmentation creates divergent procurement patterns between consolidated multinationals and specialty mid-tier processors.
- Food Manufacturers:Bakery, snack, and confectionery processors requiring shelf-stable flavor systems for extended distribution. Three North American processors account for the majority of microencapsulated flavor volumes, compressing supplier negotiation leverage.
- Cosmetics Brands:European personal care houses demanding REACH-compliant, bio-based encapsulation with certified content documentation. Hamburg and Paris formulation clusters concentrate advanced coacervation partnerships.
- Beverage Companies:Powdered drink and ready-to-drink processors requiring instant-release flavor systems.
- Household Care Producers:Detergent and air care manufacturers prioritizing cost-optimized encapsulation at scale.
Food manufacturers handle the majority of throughput; cosmetics brands is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German fragrance clusters while North American food processors extract volume discounts through procurement consolidation. This asymmetry reshapes regional investment patterns across the forecast window.
Germany
Hamburg anchors European coacervation expertise with fragrance houses leveraging complex-phase separation for high-load encapsulation. REACH authorization requirements from ECHA accelerate bio-based carrier substitution across supplier portfolios. The Hamburg-Paris corridor concentrates advanced R&D partnerships serving cosmetics brands demanding certified sustainable content.
United States
Three baked goods and confectionery processors dominate microencapsulated flavor procurement, compressing supplier margins through direct relationship mandates. FDA food additive regulations and EPA volatile organic compound standards constrain permissible carrier chemistries for domestic manufacturers. Spray-drying capacity clusters in Midwest production nodes serving multinational food distribution networks.
France
Paris-based cosmetics brands drive premium positioning for aroma compounds requiring REACH-compliant fragrance delivery systems. EU Green Deal chemical sustainability targets force reformulation timelines across fragrance oil suppliers serving luxury personal care markets. The Île-de-France formulation cluster specializes in chitosan-wall microencapsulation for skin-contact applications.
India
FSSAI-compliant encapsulation systems for spice and flavor stability remain underpenetrated in domestic bakery and snack manufacturing. The country's national food regulator maintains strict additive approval timelines that extend product launch cycles for international suppliers. Maharashtra and Gujarat concentrate processed food production capacity with growing demand for shelf-stable flavor systems.
Netherlands
Rotterdam and Amsterdam host specialty chemical marketplaces bypassing traditional flavor house intermediaries for mid-tier food processors. EFSA novel food evaluation requirements run parallel to REACH compliance, creating dual regulatory navigation for encapsulation suppliers. The Randstad region concentrates digital formulation platform adoption among mid-sized fragrance houses seeking simulation-based development cycles.
Encapsulated Flavors and Fragrances Market Vendor Landscape
Integrated taste-and-nutrition platforms and standalone fragrance specialists split the market along captive-versus-merchant supply structures. Consolidation pressures intensify as multinational food processors narrow approved supplier lists to three-to-five encapsulation partners per category. Three strategic archetypes dominate: vertically integrated flavor houses with in-house polymer capabilities, regional coacervation specialists serving cosmetics brands, and contract manufacturers scaling spray-dried commodity formats. Dominant competitive moves include backward integration into gum arabic and modified starch sourcing to hedge Sudan and Thailand supply volatility, plus technology licensing partnerships to access fluidized bed coating expertise without capital deployment.
Within the integrated-platform tier, Kerry Group plc and Givaudan SA exemplify divergent strategic positioning. Kerry Group plc anchors captive demand through its combined taste and nutrition infrastructure serving global bakery and snack manufacturers. Givaudan SA occupies a position emphasizing deep R&D partnerships with European cosmetics brands navigating REACH compliance complexity. International Flavors & Fragrances Inc. sits within the scale-driven archetype, extending production node coverage across multiple geographies to serve multinational procurement consolidation patterns.
| Leading Market Players |
|---|
| Symrise AG |
| Kerry Group plc |
| Givaudan SA |
| Takasago International Corporation |
| Mane SA |
| International Flavors & Fragrances Inc. |
| Sensient Technologies Corporation |
| Robertet SA |
| DSM-Firmenich |
| Others |
Supply Flow & Price Mechanics
Rotterdam-Antwerp freight corridors shape cost dynamics for gum arabic shipments originating from Sudan, concentrating supply risk in a single logistics artery while downstream buyers in Germany and France extract tiered price concessions based on bio-based certification tiers.
Pricing Analysis
The customization-premium spread separates REACH-compliant aroma compound formulations from commodity spray-dried flavor systems. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiators. Cost compression in standard-grade microencapsulated flavors is intensifying because three North American baked goods processors dominate procurement volumes. Mid-tier food manufacturers exhibit highest price sensitivity, while French and German cosmetics brands accept premium positioning for chitosan-wall encapsulation with documented sustainable content.
Supply Chain Analysis
Tariff exposure between Sudan and European processing hubs dominates raw material risk for gum arabic supply, the primary edible polymer for matrix-embedded flavor systems. Production concentrates in Thailand for modified starch alternatives and Germany for advanced coacervation expertise. The supply chain draws from climate-vulnerable agricultural zones and specialized chemical processing clusters simultaneously. Single-source vulnerability in Sudanese gum arabic extraction creates concentration risk for matrix-encapsulation formats. Distribution runs through Rotterdam specialty chemical marketplaces and direct manufacturer relationships for multinational food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The encapsulated flavors and fragrances market sits at a high-growth inflection as EU Green Deal chemical sustainability mandates force bio-based carrier substitution across European supplier portfolios.
For Market Incumbents: Harden backward integration into gum arabic sourcing from Sudan and modified starch supply from Thailand to hedge climate-driven input volatility. Lock in fluidized bed coating capacity partnerships in Hamburg to defend against regional coacervation specialists capturing premium cosmetics formulation work. Priority investment targets certification infrastructure for bio-based content documentation demanded by Paris and Berlin cosmetics clusters. For New Entrants and Emerging Players: Pursue FSSAI-compliant encapsulation system deployment in Maharashtra and Gujarat processed food corridors, where domestic bakery and snack manufacturing remains underserved by international suppliers. Target pH-triggered release convergence with active packaging sensor integration as the most penetrable white-space application. Go-to-market execution should route through Rotterdam specialty chemical marketplaces to bypass traditional flavor house intermediaries and reduce minimum order barriers for mid-tier processors. For Investors and Strategic Acquirers: Regional coacervation specialists with Hamburg-based R&D partnerships and established ECHA pre-registration track records represent the optimal acquisition archetype for exposure to premium fragrance encapsulation growth. Long-term viability hinges on positioning ahead of REACH sunset dates for synthetic aroma chemicals. Monitor ECHA candidate list expansion velocity as the critical inflection signal for bio-based carrier substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Edible Polymer Sourcing | Captive supply of gum arabic from Sudan hedges climate-driven price volatility for matrix-encapsulation formats. |
| Fluidized Bed Coating Capacity Expansion | Gentle processing below 60°C protects thermal-sensitive aroma compounds for Hamburg fragrance house partnerships. |
| Bio-Based Certification Investment | Documented sustainable content credentials unlock procurement windows with Paris cosmetics brands under EU Green Deal targets. |
| Direct-to-Manufacturer Platform Distribution | Rotterdam marketplace access reduces minimum order quantities and bypasses traditional flavor house intermediaries. |
| pH-Triggered Release R&D Partnership | Chitosan-wall microencapsulation convergence with active packaging sensors enables intelligent shelf-life signaling. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across formulation scientists at Hamburg fragrance houses, procurement leads at North American baked goods processors, FSSAI regulatory affairs specialists in Mumbai, and technical R&D directors at European encapsulation equipment manufacturers. Secondary validation drew from ECHA substance restriction databases, FDA food additive petition filings, EU Green Deal implementation tracking, and customs trade data for gum arabic and modified starch flows. Bottom-up volume modeling triangulated against top-down market sizing from identified production node capacities.
Calibration anchored segment-level growth rates to historical capacity utilization patterns and documented procurement consolidation trends across multinational food manufacturers. Segmentation dimensions spanned product type, application, technology, and end-user archetype across the analysis window, with additional modeling for bio-based certification tier adoption. CAGRs derived from weighted average of capacity expansion announcements, regulatory timeline impacts, and buyer concentration effects. Industry-specific inputs included ECHA pre-registration volumes for synthetic aroma chemical alternatives and fluidized bed coating equipment installation tracking.
Sensitivities concentrate around REACH authorization timeline shifts, Sudanese gum arabic harvest disruptions, and FSSAI additive approval velocity for international suppliers. Forecasts reflect documented assumptions on regulatory implementation schedules and buyer procurement consolidation trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
India Essential Oils Market
Flavor and Fragrance Chemicals
Global Solid Perfume Market
Flavor and Fragrance Chemicals
Guaiacwood Oil Market
Flavor and Fragrance Chemicals
Sulphite Ammonia Caramel Market
Flavor and Fragrance Chemicals
Natural Vanillin Market
Flavor and Fragrance Chemicals
Sensory Modifiers Market
Flavor and Fragrance Chemicals
Limonene Market
Flavor and Fragrance Chemicals
Europe Deodorants Market
Flavor and Fragrance Chemicals
United States Aroma Chemicals Market
Flavor and Fragrance Chemicals
Global Natural Cinnamic Aldehyde Market
Flavor and Fragrance Chemicals
Aromatic Compounds Market
Flavor and Fragrance Chemicals
Natural Fragrance Chemicals Market
Flavor and Fragrance Chemicals
Natural Aroma Chemicals Market
Flavor and Fragrance Chemicals
Fragrance Fixatives Market
Flavor and Fragrance Chemicals
Smoke Ingredients Market
Flavor and Fragrance Chemicals
Perillaldehyde Market