
 Treadmill Desks Market | 2026-2036
Treadmill Desks Market Size, Share, and Industry Trends Forecast 2026-2036
Treadmill Desks Market Insights
EU Green Deal building efficiency directives is pivoting commercial real estate toward active furniture portfolios that reduce sedentary liability. LifeSpan Fitness leverages in-house biomechanics R&D to sustain premium positioning across North American corporate accounts. WalkingPad dominates compact folding designs for residential remote workers. Technogym anchors high-end commercial installations through direct channel control in European fitness clubs.
A treadmill desk integrates an under-desk walking belt, typically 40 to 60 inches in belt length, with an adjustable-height work surface operating at 0.5 to 4.0 mph speeds, designed to enable low-intensity locomotion during computer-based tasks. Electric models with programmable incline and Bluetooth connectivity capture the majority of value pools as employers prioritize data-integrated wellness tracking. The corporate end-user segment leads volume due to bulk procurement by Fortune 500 human resources departments, while residential demand accelerates fastest among hybrid professionals outfitting dedicated home offices. Heavy-duty capacity variants command margin premiums in call center and control room deployments where continuous daily use exceeds eight hours.
FCC electromagnetic emissions standards govern Bluetooth-enabled treadmill desk connectivity modules sold in the United States, while CE marking requirements under EU machinery directives enforce emergency stop protocols and pinch-point guarding for European commercial installations. OSHA general duty clause interpretations on musculoskeletal disorder prevention increasingly prompt employers to document active workstation alternatives in ergonomic assessments. Stakeholders must monitor evolving building code integrations that classify treadmill desks as permanent electrical fixtures versus portable equipment, as this distinction determines installation liability and insurance underwriting frameworks.
Market Dynamics
Corporate wellness mandates from Fortune 500 human resources departments are compressing procurement cycles for active workstations, forcing manufacturers to reconcile ISO 9241 certification requirements with Bluetooth-enabled data integration demands.
Growth Catalysts
- OSHA workplace ergonomics guidelines:The general duty clause on musculoskeletal disorder prevention compels employers to document active workstation alternatives in formal ergonomic assessments, expanding addressable corporate accounts.
- Hybrid work permanence:Sustained remote work arrangements among knowledge workers in the United States drive dedicated home office equipment investment, particularly compact folding configurations.
- EU Green Deal building efficiency directives:Commercial real estate portfolios across European Union member states are pivoting toward active furniture to reduce sedentary liability exposure.
Market Restraints
- Steel and aluminum input volatility:Treadmill frame and belt deck materials face commodity price swings that compress margin stability for mid-tier manufacturers.
- Motor supplier concentration:Continuous-duty DC motor production for walking belts clusters among East Asian component specialists, creating single-source vulnerability.
- FCC electromagnetic emissions compliance:Bluetooth connectivity modules require costly pre-certification testing that extends product development timelines for smaller entrants.
Strategic Opportunities
- Call center vertical expansion:Heavy-duty capacity variants for eight-hour continuous daily use command premium pricing in customer service operations and control room deployments.
- Building code reclassification:Jurisdictions treating treadmill desks as permanent electrical fixtures versus portable equipment create installation liability frameworks favoring established vendors with underwriting relationships.
- Insurance wellness incentive integration:Health insurers in the United States are piloting premium discounts for employers deploying active workstations, opening channel partnerships.
Industry Challenges
- Biomechanics engineering talent scarcity:In-house R&D teams capable of optimizing belt cushioning algorithms for typing stability remain concentrated among premium manufacturers.
- Multi-standard certification timelines:Simultaneous pursuit of CE marking under EU machinery directives, FCC compliance, and ISO 9241 conformance strains quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Treadmill Desks Market |
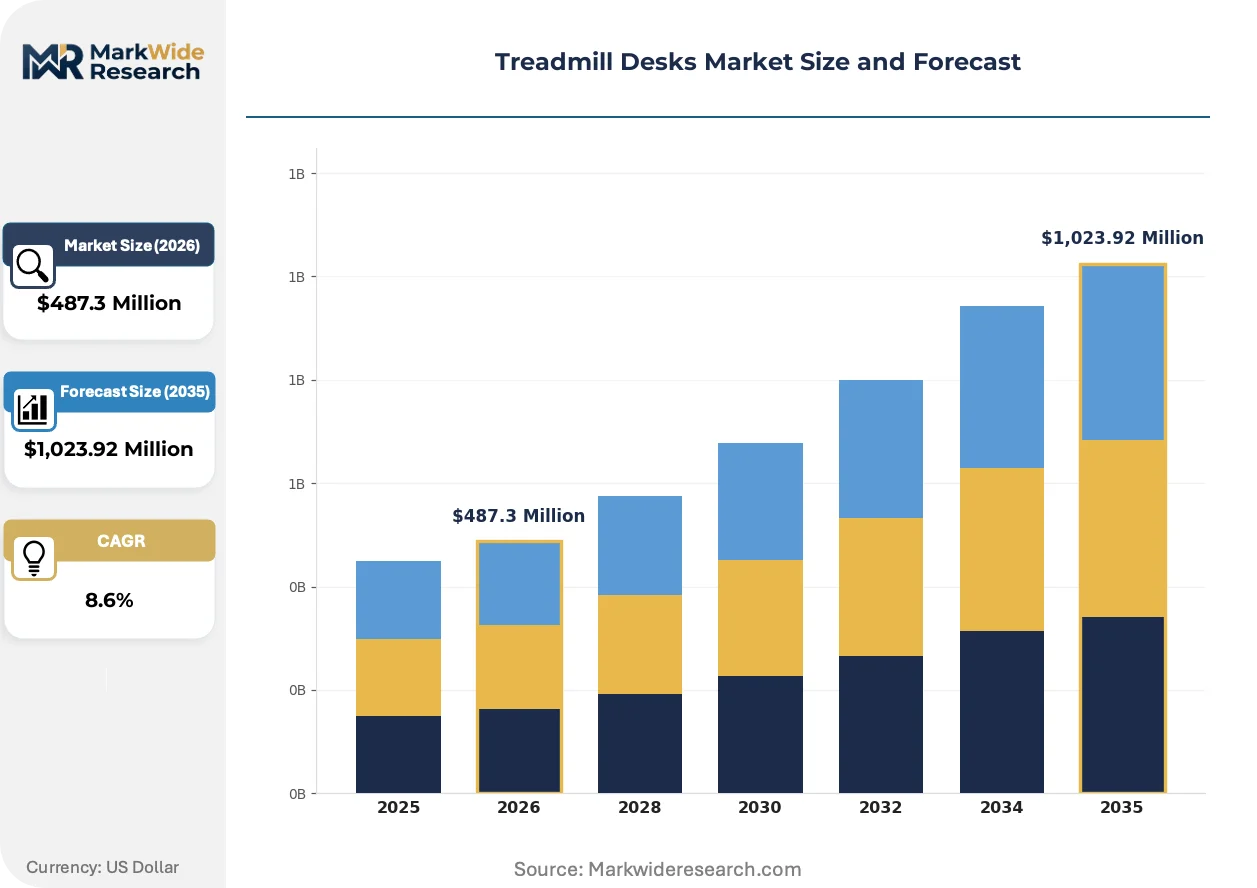
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Electric, Folding, Non-Folding End User: Residential, Commercial, Educational, Corporate Capacity: Light Duty, Medium Duty, Heavy Duty, Ultra Heavy Duty Features: Bluetooth Connectivity, Adjustable Height, Safety Features, Built-in Speakers |
| Companies Covered | GoYouth, DeerRun, WalkingPad, GoPlus, Urevo, LifeSpan Fitness, iMovR, Fitbit, Technogym, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Treadmill Desks Market Trends and Innovations
Active workstation technology is converging around sensor-integrated platforms that capture locomotion metrics while synchronizing with enterprise wellness dashboards, compressing the gap between fitness equipment and office furniture categories.
Brushless DC motor systems with programmable incline are absorbing the premium tier of corporate procurement. These drive units enable whisper-quiet operation below 50 decibels, a threshold Fortune 500 facilities managers now specify for open-plan deployments. The technology is absorbing margin from conventional fixed-speed alternatives as employers prioritize acoustic comfort alongside movement enablement.
OSHA general duty clause interpretations on ergonomic hazard abatement are tightening documentation requirements for sedentary workstation alternatives. Employers must now catalog active workstation availability in formal assessments, creating procurement pull-through for certified products. United States commercial installations face the steepest compliance velocity, with human resources departments mandating ISO 9241-conforming equipment in RFP specifications.
Enterprise buying committees are consolidating vendor relationships around full-service active furniture portfolios rather than point solutions. Facilities managers in the United States are displacing single-product tenders with multi-year contracts covering installation, maintenance, and data platform access. This pattern concentrates volume among suppliers capable of underwriting performance guarantees and integrated wellness reporting.
Treadmill Desks Market Segmentation
Treadmill desk procurement decisions hinge on certification requirements that vary sharply across product configurations. ISO 9241 conformance, FCC electromagnetic approvals, and EU machinery directive compliance create tiered barriers that reshape competitive positioning within each segment cluster.
Product Type:
Electric and Bluetooth-enabled variants carry the heaviest certification burden, requiring FCC pre-certification for U.S. connectivity modules and CE marking under EU machinery directives for emergency stop protocols.
- Electric:Brushless DC motor systems with programmable incline operate below 50 decibels for open-plan corporate deployments. Fortune 500 facilities managers in the United States specify these for acoustic comfort alongside locomotion enablement, absorbing margin from fixed-speed alternatives.
- Folding:Compact hinge mechanisms with reinforced deck supports target residential remote workers outfitting dedicated home offices. WalkingPad dominates this configuration through East Asian manufacturing clusters optimized for space-constrained urban apartments.
- Manual:Belt-driven units without motorized components bypass FCC electromagnetic testing entirely. These serve price-sensitive educational institutions with limited facilities budgets.
- Non-Folding:Rigid frame construction delivers maximum stability for control room deployments. Call center operators favor these for eight-hour continuous daily use.
Electric sits at the top of the volume ranking, with Folding climbing the fastest.
End User:
Procurement authority and volume scale diverge dramatically across buyer types, with corporate human resources departments consolidating around multi-year vendor contracts while residential purchasers prioritize single-transaction convenience.
- Corporate:Fortune 500 human resources departments mandate ISO 9241-conforming equipment in RFP specifications. Bulk procurement compresses vendor selection cycles toward full-service active furniture portfolios covering installation, maintenance, and wellness data platforms.
- Residential:Hybrid professionals in the United States drive fastest expansion through dedicated home office investment. Compact folding configurations with Bluetooth synchronization to personal fitness apps capture this demand.
- Commercial:Fitness clubs and coworking spaces anchor high-end installations through direct channel relationships. European facilities prioritize CE-marked emergency stop protocols.
- Educational:Universities and K-12 districts deploy manual variants in library study zones. Budget constraints limit penetration to pilot programs.
Corporate commands absolute volume leadership, with Residential gaining share most rapidly.
Capacity:
Frame reinforcement and motor specification tiers determine warranty underwriting and insurance classification, with heavy-duty variants treated as permanent electrical fixtures in certain U.S. jurisdictions.
- Heavy Duty:Reinforced steel frames and continuous-duty DC motors support eight-hour daily cycles. Call center and control room deployments command premium pricing through performance guarantees.
- Medium Duty:Balanced specifications target standard corporate office rotations among multiple users. ISO 9241 certification suffices for most procurement committees.
- Light Duty:Aluminum frame construction reduces shipping costs for residential e-commerce channels. Belt cushioning algorithms receive less R&D investment.
- Ultra Heavy Duty:Industrial-grade components exceed standard office furniture classifications. Building code reclassification as permanent fixtures triggers specialized installation liability frameworks.
Heavy Duty leads corporate procurement volume, with Ultra Heavy Duty expanding most quickly in specialized verticals.
Features:
Data integration capabilities and safety engineering investments separate premium tiers from commodity alternatives, with Bluetooth connectivity requiring the most extensive pre-market testing.
- Bluetooth Connectivity:Modules synchronizing with enterprise wellness dashboards demand FCC electromagnetic emissions certification. Development timelines extend product launches for smaller entrants lacking pre-certified component suppliers.
- Adjustable Height:Electric lift columns with programmable memory positions align with OSHA workplace ergonomics guidelines. Corporate buyers document these in formal musculoskeletal disorder prevention assessments.
- Safety Features:Emergency stop protocols and pinch-point guarding satisfy CE marking requirements under EU machinery directives. European commercial installations mandate these specifications.
- Built-in Speakers:Audio integration adds minimal certification burden beyond standard electrical safety. Residential purchasers occasionally specify these for entertainment multitasking.
Bluetooth Connectivity dominates value pools, with Adjustable Height showing steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The treadmill desk industry traces its commercial origins to 2007 when Dr. James Levine at the Mayo Clinic in Rochester, Minnesota pioneered active workstation research. This institutional foundation established the United States as the primary demand center before diffusion into European corporate wellness programs and East Asian manufacturing clusters.
United States
Fortune 500 human resources departments in New York and Chicago metro areas mandate ISO 9241-conforming equipment in procurement specifications. OSHA general duty clause interpretations on musculoskeletal disorder prevention compel employers to document active workstation alternatives. Minneapolis-St. Paul anchors corporate pilot programs where Mayo Clinic research partnerships validate wellness ROI metrics.
Germany
Ruhr Valley industrial employers deploy heavy-duty variants in control room environments where eight-hour continuous cycles exceed standard office use. CE marking requirements under EU machinery directives enforce emergency stop protocols and pinch-point guarding for commercial installations. Munich engineering consultancies specialize in ergonomic workspace certification for DAX-listed corporations.
China
Zhengzhou manufacturing clusters produce compact folding mechanisms optimized for space-constrained urban apartments. GB standards for electrical safety govern domestic sales while export-oriented factories pursue FCC pre-certification for Bluetooth connectivity modules. Shenzhen component suppliers concentrate continuous-duty DC motor production for walking belt assemblies.
United Kingdom
London financial services firms pilot active workstations in trading floor environments where sedentary exposure liability concerns mount. HSE workplace health guidelines encourage ergonomic alternatives without mandating specific equipment categories. Cambridge research parks host biomechanics startups optimizing belt cushioning algorithms for typing stability.
Japan
Tokyo metropolitan government offices integrate treadmill desks in civil servant wellness initiatives addressing metabolic syndrome prevalence. METI industrial standards for office equipment safety shape product certification requirements for domestic manufacturers. Osaka precision engineering firms supply brushless DC motor systems achieving sub-50 decibel operation thresholds.
Treadmill Desks Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification intensity and data integration capability. The vendor base stratifies into three tiers: full-service providers underwriting installation and maintenance contracts, component-integrated assemblers leveraging East Asian manufacturing scale, and manual-variant specialists serving price-sensitive educational channels. Dominant competitive moves include multi-year enterprise contract consolidation and in-house biomechanics R&D team assembly.
Within the premium-tier vector, LifeSpan Fitness and Technogym occupy positions emphasizing direct channel control and high-end commercial installations. WalkingPad exemplifies the compact folding archetype targeting residential remote workers through East Asian manufacturing optimization. DeerRun and Urevo represent mid-tier assemblers competing on e-commerce accessibility and Bluetooth-enabled feature integration.
| Leading Market Players |
|---|
| GoYouth |
| DeerRun |
| WalkingPad |
| GoPlus |
| Urevo |
| LifeSpan Fitness |
| iMovR |
| Fitbit |
| Technogym |
| Others |
Pricing and Supply Chain Analysis
Captive in-house biomechanics R&D anchors premium pricing power for established manufacturers while outsourcing motor production to East Asian specialists compresses margins for mid-tier assemblers competing on Bluetooth-enabled feature parity. Steel frame fabrication and continuous-duty DC motor sourcing concentrate cost structures, with certification intensity determining which suppliers capture value versus ceding it to component vendors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO 9241-certified electric models with programmable incline from FCC-compliant Bluetooth variants and manual belt-driven units. Certification grade and volume scale drive price differentiation, with Fortune 500 bulk procurement commanding negotiated discounts unavailable to residential purchasers. Cost compression in mid-tier electric configurations is intensifying because East Asian motor suppliers extract margin through single-source positioning. Educational institutions exhibit highest price sensitivity, while call center operators deploying heavy-duty variants for eight-hour cycles demonstrate lowest sensitivity due to performance guarantee requirements.
Supply Chain Analysis
Ocean freight cost volatility from East Asian manufacturing clusters to North American distribution centers amplifies working capital pressure for e-commerce-dependent assemblers. Production concentrates in China for compact folding mechanisms, Japan for brushless DC motor systems, and the United States for premium biomechanics R&D. Steel and aluminum frame materials draw from commodity spot markets, while continuous-duty DC motor production rests on Shenzhen component specialists. Single-source vulnerability in motor supply creates structural risk. Distribution runs through direct enterprise contracts for corporate accounts and Amazon-dominated e-commerce for residential purchasers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between EU Green Deal building efficiency mandates and OSHA workplace ergonomics enforcement creates divergent certification investment requirements, with European compliance costs running higher due to CE marking machinery directive protocols.
For Market Incumbents: Hedge against Bluetooth module cost inflation by cultivating secondary FCC pre-certified component suppliers outside Shenzhen clusters. Anchor enterprise contract renewals through in-house biomechanics R&D teams capable of optimizing belt cushioning algorithms for typing stability, displacing mid-tier assemblers lacking comparable capabilities.
For New Entrants and Emerging Players: Launch via educational institution pilot programs deploying manual variants that bypass FCC electromagnetic testing entirely. Target price-sensitive K-12 districts and university library systems with belt-driven units, then migrate certified purchasers toward electric upgrades through demonstrated ROI documentation.
For Investors and Strategic Acquirers: Roll-up economics work for component-integrated assemblers because multi-standard certification timelines strain quality assurance bandwidth at sub-scale manufacturers. Long-term viability favors targets with established CE marking and FCC compliance infrastructure. Watch insurance wellness incentive pilot programs as inflection signal for employer procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Standard Certification Investment | Simultaneous ISO 9241, FCC, and CE marking pursuit opens Fortune 500 and EU commercial channels. |
| In-House Biomechanics R&D Assembly | Proprietary belt cushioning algorithms defend premium positioning against East Asian manufacturing scale. |
| Enterprise Contract Consolidation | Multi-year installation and maintenance agreements displace single-product tenders in facilities procurement. |
| Insurance Channel Partnership Development | Premium discount pilot programs with U.S. health insurers create procurement pull-through mechanism. |
| Heavy-Duty Vertical Expansion | Eight-hour continuous use variants command pricing premiums in call center and control room deployments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Fortune 500 facilities managers, corporate wellness directors, treadmill desk product engineers, and East Asian motor component suppliers with secondary validation against OSHA guidance documents, FCC electromagnetic emissions databases, EU machinery directive technical files, and ISO 9241 conformance registries. Bottom-up shipment estimates triangulated against top-down corporate wellness program spend allocations.
Segment-weighting approaches applied differential growth assumptions across product type, end user, capacity tier, and feature configuration dimensions throughout the forecast period. CAGRs derived from logistic diffusion curves modeling corporate wellness program adoption saturation and residential hybrid work permanence. Industry-specific inputs included brushless DC motor cost trajectories and building code reclassification timelines for permanent electrical fixture treatment.
Several conditions sit outside the modeled scope, including potential tariff restructuring on East Asian motor imports and unforeseen OSHA general duty clause reinterpretation. Forecasts reflect documented assumptions about certification timeline stability and commodity input price normalization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Leg Exercise Equipment Market
Fitness Equipment
North America Fitness Rings Market
Fitness Equipment
Europe Home Fitness Equipment Market
Fitness Equipment
Weight Training Market
Fitness Equipment
Gymnastics Equipment Market
Fitness Equipment
Gym Ball Market
Fitness Equipment
Functional Fitness Equipment Market
Fitness Equipment
Yoga Accessories Market
Fitness Equipment
Pilates Equipment and Gears Market
Fitness Equipment
Yoga Mat Market
Fitness Equipment
Exercise Resistance Bands Market
Fitness Equipment
Europe Fitness Rings Market
Fitness Equipment
PVC Stretch Yoga Mats Market
Fitness Equipment
Elliptical Market
Fitness Equipment
Gymnastic Springboard Market
Fitness Equipment
Push-Up Board Market