
 Home Theatre Market | 2026-2036
Home Theatre Market Size, Share, and Industry Trends Forecast 2026-2036
Home Theatre Market Analysis
A shift from single-source display procurement to multi-source component ecosystems is restructuring how manufacturers secure panel and driver supply. Samsung Electronics leverages captive semiconductor and display fabrication to control cost trajectories across its soundbar and projector lines. Sony Corporation anchors its premium positioning through proprietary image processing silicon and acoustic calibration technologies. LG Electronics competes aggressively in OLED home theatre panels while extending its webOS platform into integrated streaming environments.
Home theatre denotes a dedicated audio-visual reproduction environment comprising source components, amplification, loudspeakers, and display surfaces engineered for cinematic fidelity in residential or commercial spaces. Systems typically achieve reference-grade performance through calibrated luminance above 1,000 nits, multi-channel audio beyond 5.1 configurations, and acoustically treated room geometry. The product type landscape tilts toward speakers and soundbars as margin pools concentrate in acoustic hardware, while projector demand accelerates among homeowners seeking screen diagonals exceeding 120 inches. Technology segmentation reveals 4K UHD as the installed baseline with OLED commanding premium price tiers due to per-pixel emissive architecture and infinite contrast ratios.
FCC equipment authorization governs RF emissions from wireless subwoofers and streaming sticks in the United States, while CE marking under the EU Radio Equipment Directive shapes market access for Bluetooth and Wi-Fi-enabled components sold across Europe. REACH restrictions on hazardous substances in cabling and cabinetry materials compel manufacturers to reformulate PVC jackets and flame-retardant composites. Energy efficiency labeling programs in multiple jurisdictions further constrain standby power draw and operational consumption thresholds. Stakeholders must monitor evolving codec licensing structures and HDMI specification transitions to anticipate compatibility-driven replacement demand.
Market Dynamics
Immersive audio codec proliferation is restructuring upgrade cycles as homeowners replace 5.1 systems with object-based surround configurations, compressing replacement timelines from seven years to four.
Growth Catalysts
- Dolby Atmos penetration:Object-based audio is redefining minimum performance benchmarks across residential installations in the United States, Germany, and China.
- Smart home integration mandates:FCC equipment authorization for RF-enabled subwoofers and streaming sticks accelerates wireless ecosystem adoption.
- CE marking harmonization:The EU Radio Equipment Directive streamlines Bluetooth and Wi-Fi component market access across 27 member states.
Market Restraints
- Display panel supply concentration:OLED fabrication capacity clusters in South Korea and China, creating allocation bottlenecks for premium screen diagonals exceeding 77 inches.
- HDMI specification fragmentation:Compatibility gaps between 2.1a and earlier versions force premature receiver obsolescence.
- REACH compliance costs:Restrictions on halogenated flame retardants in cabling compel PVC jacket reformulation, raising material expenses.
Strategic Opportunities
- India residential construction:Underpenetrated dedicated entertainment room installations present white space for calibrated acoustic treatment services.
- Energy efficiency labeling:Standby power mandates in multiple jurisdictions create differentiation for sub-watt standby amplifier designs.
- Streaming codec convergence:Integration of immersive audio with gaming engines opens adjacent revenue in PC-based home theatre configurations.
Industry Challenges
- Acoustic calibration expertise scarcity:Qualified room-tuning technicians remain concentrated in metropolitan installation markets.
- Codec licensing complexity:Multi-format royalty stacks for DTS:X, Auro-3D, and Dolby Atmos inflate BOM costs for mid-tier receivers.
- Legacy amplifier inventory:Analog RCA-dominant installed bases resist HDMI-ARC integration without costly converter hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Theatre Market |
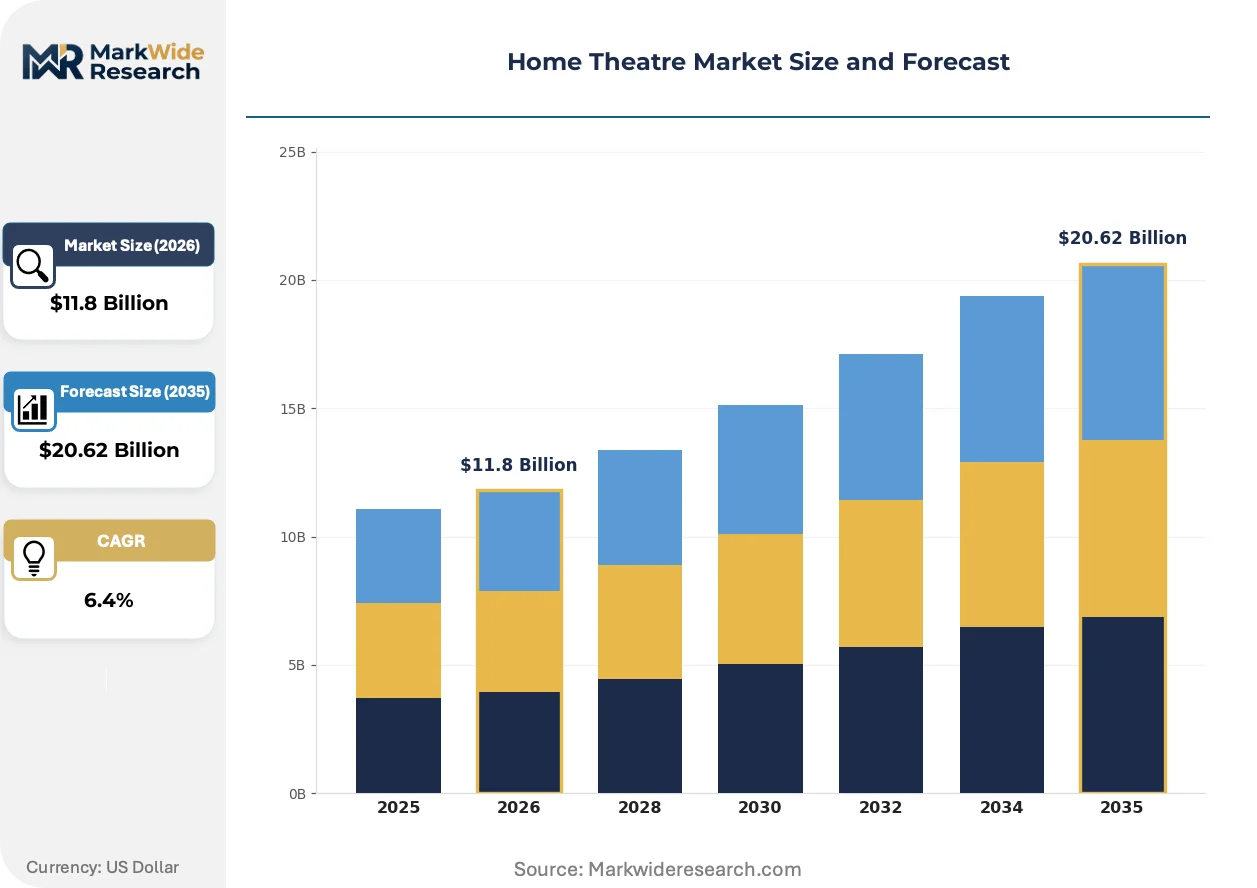
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AV Receivers, Speakers, Projectors, Screens Technology: 4K UHD, OLED, LED, Soundbar Application: Residential, Commercial, Cinematic, Streaming End User: Homeowners, Renters, Businesses, Event Venues |
| Companies Covered | Samsung Electronics, Sony Corporation, LG Electronics, Panasonic Corporation, Bose Corporation, Yamaha Corporation, Koninklijke Philips N.V., Sonos, Harman International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Theatre Market Emerging Trajectories
Wireless spatial audio transmission is collapsing the physical infrastructure once required for immersive surround, while regulatory pressure on standby consumption forces semiconductor redesign across power amplification stages.
Laser phosphor illumination is electrifying projector brightness economics, enabling 3,000+ lumen output from compact chassis previously limited to lamp-based architectures. Custom integrators in California and Texas specify these engines for ambient-light residential environments. The technology is electrifying the 120-inch-plus screen segment by eliminating lamp replacement cycles and reducing thermal management costs.
REACH restrictions on hazardous substances are compelling manufacturers to reformulate PVC jackets and halogenated flame retardants in speaker cabling and cabinetry composites. European importers now demand full material disclosure documentation upstream to Chinese and Vietnamese cabinet fabricators. Acoustic hardware vendors with EU exposure are accelerating bio-based composite qualification to maintain market access.
Streaming-first content consumption is compressing physical media attachment rates among homeowners under 45, shifting procurement toward integrated soundbar-projector bundles over discrete component builds. Big-box retailers in the United States and Germany report declining SKU counts for standalone Blu-ray players. This behavioral pivot concentrates margin capture in subscription-enabled display ecosystems rather than source component sales.
Home Theatre Market Segmentation
Home theatre procurement patterns diverge sharply across product configurations, display technologies, and user contexts. Upgrade cycles compress where immersive audio codecs and wireless ecosystems reduce installation friction.
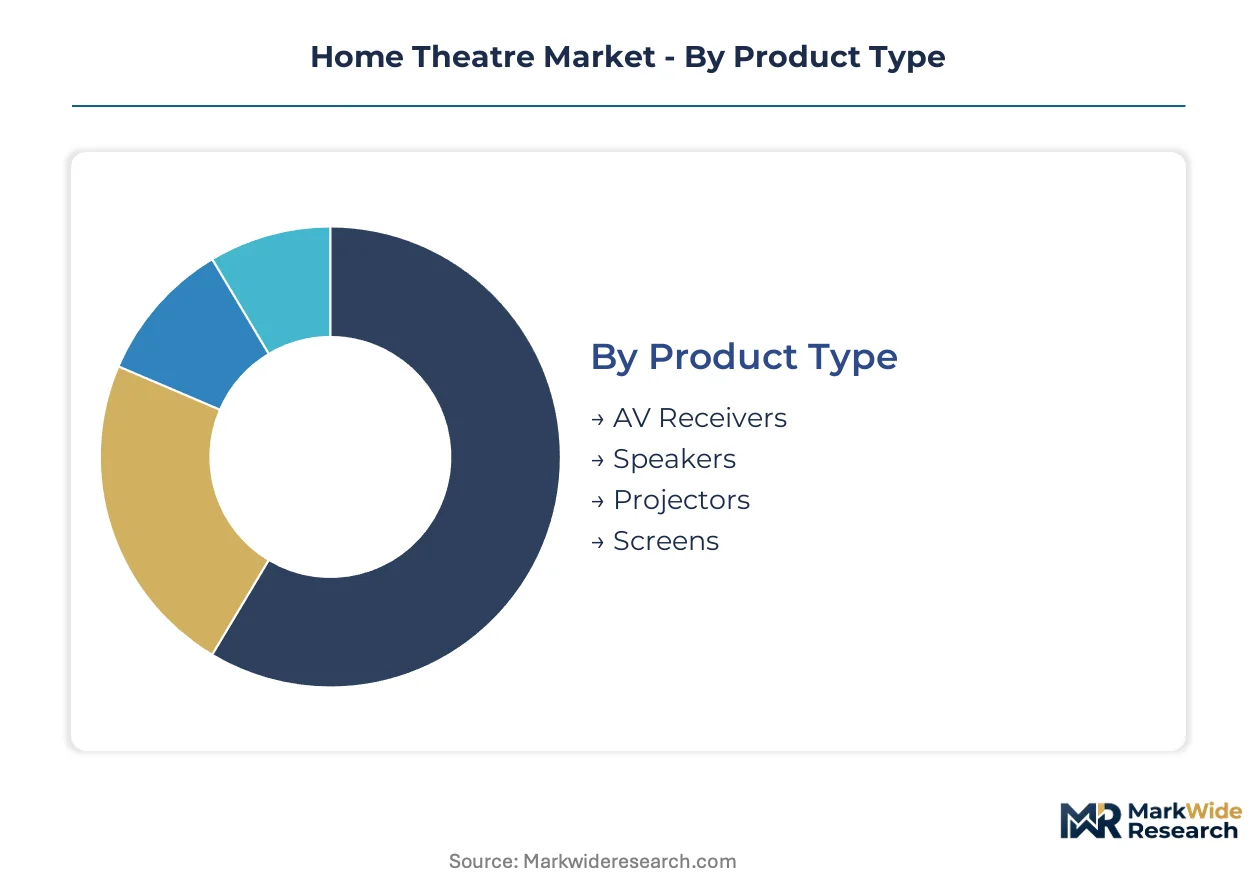
Product Type:
Replacement timelines now hinge on codec compatibility rather than hardware failure, accelerating turnover in amplification and acoustic components.
- AV Receivers:Multi-channel amplification units with HDMI 2.1a switching and object-based audio decoding. Demand clusters in dedicated entertainment rooms across the United States and Germany where Dolby Atmos mandates drive seven-to-four-year cycle compression.
- Speakers:Floor-standing, bookshelf, and architectural loudspeakers delivering calibrated frequency response. Acoustic hardware captures concentrated margin pools as homeowners prioritize room-tuned performance over display upgrades.
- Projectors:Lamp-based and solid-state illumination engines for screen diagonals exceeding 120 inches. Laser phosphor variants gain traction in ambient-light residential environments.
- Screens:Fixed-frame and motorized projection surfaces with gain-optimized coatings. ALR (ambient light rejecting) materials command premium positioning in open-plan installations.
Volume placements concentrate in Speakers; the faster expansion belongs to Projectors.
Technology:
Cost tier stratification separates reference-grade installations from mass-market bundles, with emissive architectures commanding substantial price premiums.
- 4K UHD:3840x2160 resolution baseline now standard across mid-tier displays and source components. Regulatory energy efficiency labeling in multiple jurisdictions constrains standby power draw for UHD-enabled receivers.
- OLED:Per-pixel emissive architecture delivering infinite contrast ratios and sub-millisecond response times. Fabrication capacity bottlenecks in South Korea and China limit availability for diagonals exceeding 77 inches.
- LED:Transmissive LCD backlighting with quantum dot enhancement layers. Volume manufacturing in Chinese panel fabs sustains aggressive price positioning.
- Soundbar:Integrated amplification and driver arrays with wireless subwoofer pairing. Streaming-first consumption patterns favor bundled soundbar-projector configurations over discrete component builds.
LED captures unit volume leadership; OLED posts the steepest expansion trajectory in value terms.
Application:
Customer type determines installation complexity and service attachment rates, with residential dedicated rooms supporting premium calibration revenue.
- Residential:Dedicated entertainment rooms and open-plan living spaces with acoustically treated geometry. Custom integrators in California and Texas specify laser phosphor projectors for ambient-light environments.
- Commercial:Corporate briefing centers and hospitality venues requiring extended operational durability. Service contracts and preventive maintenance generate recurring revenue streams.
- Cinematic:Private screening rooms replicating theatrical reference standards. THX and ISF certification requirements elevate component specifications and installation labor.
- Streaming:Content-first configurations prioritizing subscription service integration over physical media. Big-box retailers report declining standalone Blu-ray player SKU counts.
Residential dominates current placements; Streaming applications are climbing the fastest as behavioral preferences shift.
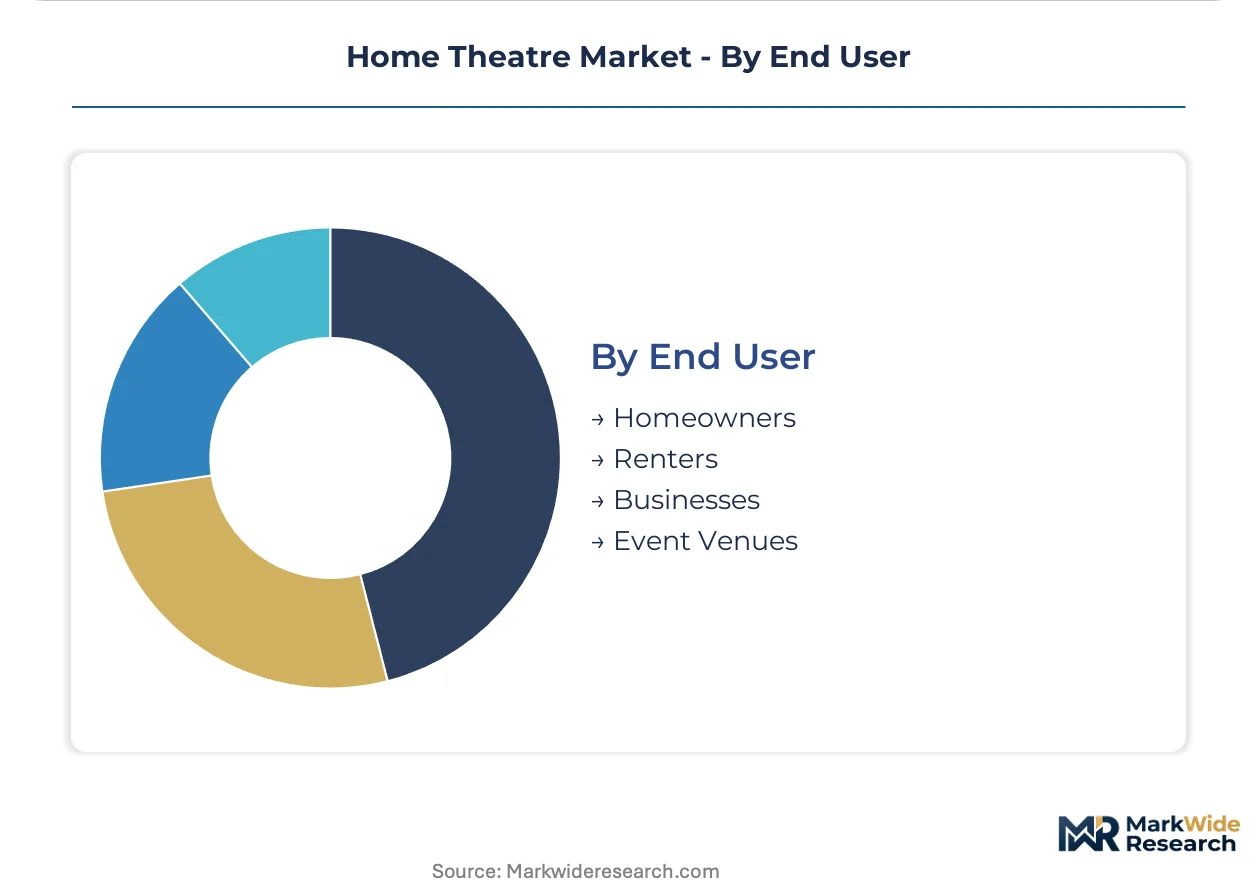
End User:
Geography and tenure status shape procurement authority, with homeowners investing in permanent installations and renters favoring portable or minimally invasive solutions.
- Homeowners:Property owners with structural modification permissions for acoustic treatment and fixed mounting. Upgrade authorization rests with single decision-makers rather than landlord approvals.
- Renters:Lease-constrained occupants prioritizing wireless soundbars and portable projectors over architectural speaker installations. Damage deposit risks limit wall penetration and cable routing.
- Businesses:Corporate procurement departments with standardized AV specifications and volume purchasing agreements. FCC equipment authorization compliance is mandatory for RF-enabled conference room deployments.
- Event Venues:Temporary installation operators requiring rapid deployment and strike capabilities. Rental inventory management prioritizes ruggedized chassis and universal mounting compatibility.
Homeowners anchor volume demand; Businesses are gaining share fastest as hybrid work models sustain meeting room investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Display panel fabrication clusters in South Korea and China anchor the upstream supply architecture for premium home theatre installations worldwide.
United States
Residential dedicated entertainment room construction drives AV receiver and speaker system procurement across California and Texas metro corridors. FCC equipment authorization governs RF emissions from wireless subwoofers and streaming sticks. Custom integrators in Los Angeles and Austin specify laser phosphor projectors for ambient-light residential environments.
China
OLED fabrication capacity concentration in Chinese panel fabs sustains aggressive price positioning for large-format displays. MIIT standards and GB certification requirements shape domestic market access for Bluetooth and Wi-Fi-enabled components. Yangtze River Delta manufacturing clusters supply acoustic hardware and cabinetry materials to European and North American importers.
Germany
Premium installation services and smart home integration accelerate replacement cycles in dedicated entertainment rooms across Bavaria and North Rhine-Westphalia. CE marking under the EU Radio Equipment Directive streamlines Bluetooth component market access. REACH restrictions on halogenated flame retardants compel PVC jacket reformulation in speaker cabling sourced from Chinese fabricators.
South Korea
Captive semiconductor and display fabrication enables cost control across soundbar and projector lines for domestic manufacturers. Energy efficiency labeling programs constrain standby power draw for UHD-enabled receivers. Seoul Capital Area technology clusters drive proprietary image processing silicon development for premium positioning.
India
Underpenetrated dedicated entertainment room installations present white space for calibrated acoustic treatment services in Maharashtra and Karnataka. BIS certification mandates govern safety standards for electrical components in residential AV systems. Mumbai and Bengaluru residential construction booms accelerate demand for wireless soundbar-projector bundles among first-time homeowners.
Home Theatre Market Vendor Landscape
Capacity expansion dominates the current landscape as manufacturers secure captive panel and driver supply. The vendor base structures around three tiers: diversified electronics conglomerates with captive fabrication, specialized acoustic hardware vendors, and streaming-integrated platform players. Two strategic archetypes predominate: vertically integrated display manufacturers leveraging semiconductor control, and audio specialists commanding margin pools in room-tuned performance hardware. M&A activity and technology licensing agreements represent the dominant competitive moves reshaping component ecosystem relationships.
Within the diversified electronics tier, Samsung Electronics Co., Ltd. and Sony Corporation exemplify contrasting approaches to premium positioning through upstream control. LG Electronics anchors the OLED display vector with fabrication depth in large-format panels. These three conglomerates occupy positions that reflect the broader industry tension between captive supply economics and specialized acoustic engineering.
| Leading Market Players |
|---|
| Samsung Electronics |
| Sony Corporation |
| LG Electronics |
| Panasonic Corporation |
| Bose Corporation |
| Yamaha Corporation |
| Koninklijke Philips N.V. |
| Sonos |
| Harman International |
| Others |
Supply Flow & Price Mechanics
Immersive audio codec mandates from Dolby Laboratories are compressing replacement cycles and forcing manufacturers to absorb royalty stacks while maintaining price accessibility across mid-tier receiver segments.
Pricing Analysis
Extended warranty bundling and calibration service attachments separate premium AV receiver tiers from unbundled economy alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with THX and ISF certification commanding substantial markups. Pricing pressure stems from HDMI 2.1a specification transitions forcing premature obsolescence of legacy inventory. Renters exhibit highest price sensitivity, prioritizing wireless soundbar-projector bundles over discrete component investments.
Supply Chain Analysis
Ocean freight rate volatility from Yangtze River Delta ports to Long Beach and Rotterdam is compressing margins on bulky speaker cabinetry and projection screens. Manufacturing concentrates in China, South Korea, and Vietnam for display panels, acoustic drivers, and cabinet fabrication. Supply chains draw from rare earth magnet suppliers for driver motors, laser phosphor diodes for projectors, and flame-retardant composite feedstock constrained by REACH restrictions. Single-source vulnerability sits with OLED fabrication capacity clustered in South Korean and Chinese panel fabs. Distribution runs through big-box retailers, custom integration channels, and direct-to-consumer streaming-integrated platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Object-based audio codecs are displacing channel-based surround configurations, creating a technology-transition phase where calibration expertise and wireless ecosystem integration determine competitive survival.
For Market Incumbents: Deepen captive semiconductor fabrication for image processing silicon to defend margin pools against specialized acoustic hardware vendors. Secure allocation agreements with South Korean and Chinese OLED panel suppliers before capacity bottlenecks intensify for diagonals exceeding 77 inches. Invest in technician certification programs to address acoustic calibration expertise scarcity in secondary metro markets.
For New Entrants and Emerging Players: First-time homeowners in Indian metropolitan construction corridors represent an underserved buyer archetype with minimal dedicated entertainment room penetration. Target wireless soundbar-projector bundles with integrated streaming platforms to bypass legacy amplifier inventory resistance. Pursue partnerships with residential developers for pre-installation specification in Maharashtra and Karnataka housing projects.
For Investors and Strategic Acquirers: The window for entry favors specialized acoustic hardware vendors with room-tuning IP and established custom integrator relationships. Long-term viability hinges on recurring calibration service revenue rather than transactional hardware margins. Monitor laser phosphor projector adoption rates in ambient-light residential environments as inflection indicator for solid-state illumination displacement of lamp-based architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Laser Phosphor Projector Launch | Samsung Electronics and Sony Corporation are accelerating solid-state illumination adoption for ambient-light residential installations. |
| Acoustic Calibration Service Expansion | Bose Corporation and Sonos are building recurring revenue streams through room-tuning technician networks. |
| HDMI 2.1a Receiver Platform Upgrade | Yamaha Corporation and Harman International are forcing replacement cycles through compatibility-driven obsolescence. |
| OLED Panel Supply Agreement | LG Electronics is securing captive fabrication capacity for premium home theatre screen diagonals exceeding 77 inches. |
| Streaming Codec Integration Partnership | Panasonic Corporation and Koninklijke Philips N.V. are embedding subscription platforms into display ecosystems. |
Methodological Framework
Independent corroboration across custom integrators, acoustic hardware procurement managers, and streaming platform engineering leads underwrites the qualitative findings in this study. Primary interviews with dedicated entertainment room designers, AV receiver product managers, laser phosphor projector engineers, and big-box retail category buyers were cross-referenced against secondary validation from FCC equipment authorization filings, MIIT certification databases, CE marking directives, and REACH compliance documentation. Bottom-up unit shipment estimates and top-down value aggregation were reconciled through iterative triangulation.
Rate-of-change decomposition across product type, display technology, application context, and end-user tenure status structured the analytical framework over the projection horizon. Segmentation dimensions modeled include speaker configuration, illumination engine architecture, room treatment requirements, and geographic regulatory cluster. CAGRs were derived from historical replacement cycle compression and forward-looking codec penetration assumptions. Industry-specific forecast inputs incorporated laser phosphor brightness economics and wireless spatial audio transmission adoption curves.
Revisions become necessary when HDMI specification transitions accelerate, REACH restrictions expand to additional substance categories, or OLED fabrication capacity shifts geographically. Forecasts reflect documented assumptions about immersive audio codec licensing structures and streaming-first consumption behavioral persistence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
US Personal Care Products Market
Consumer Goods
Window Air Conditioners Market
Consumer Goods
China Smoking Pipe Market
Consumer Goods
Drinkware Accessories Market
Consumer Goods
Japan Do-It-Yourself (DIY) Home Improvement Retailing Market
Consumer Goods
Europe Small Home Appliances Market
Consumer Goods
Household Care Wipes Market
Consumer Goods
Asia-Pacific Lingerie Market
Consumer Goods
Global Office Peripherals and Products Market
Consumer Goods
Erasable Ink Pen Market
Consumer Goods
Middle East and Africa Refurbished and Used Mobile Phones Market
Consumer Goods
Cosmetic Mirror Market
Consumer Goods
Europe Air Fryers Market
Consumer Goods
Electronic Cigarette Atomizer Market
Consumer Goods
Leather Goods Market
Consumer Goods
Cutlery Steel Market