
 Leather Goods Market | 2026-2036
Leather Goods Market Size, Share, and Industry Trends Forecast 2026-2036
Leather Goods Market Analysis
Artisanal tanning expertise is unwinding across traditional manufacturing clusters, creating bottlenecks in vegetable-tanned output while unlocking premium pricing power for heritage producers. LVMH leverages captive tanneries in France and Italy to secure full-grain supply chains. Hermès International sustains decades-long leatherworker apprenticeship programs that limit production velocity but anchor exclusivity. Kering competes through controlled chrome-tanning partnerships that balance scale with environmental compliance.
Leather goods encompass finished products crafted from animal hides or skins through chemical or vegetable preservation, with full-grain retaining the outermost corium layer for durability and patina development; these items serve functional, status-signaling, and longevity-driven consumer needs across personal accessories and apparel. Bags and wallets occupy the largest value pool due to repeat purchase frequency and gift-market elasticity, while footwear commands the highest unit engineering complexity. Vegetable-tanned leather is gaining fastest among sustainability-oriented buyers, though chrome-tanned materials still dominate mass production for cost efficiency.
REACH restricts chromium VI discharge thresholds across European tanneries, pushing producers toward vegetable-tanned alternatives or closed-loop water systems. EPA guidelines in the United States govern hazardous air pollutants from leather finishing operations, affecting import eligibility for untreated hides. BIS certification requirements in India standardize leather quality grades for export competitiveness. Stakeholders must monitor how evolving chemical disclosure mandates reshape supplier qualification criteria and capital allocation across tanning capacity.
Market Dynamics
Artisanal tanning capacity is contracting across Italian and French heritage clusters while REACH chemical disclosure mandates force capital redeployment toward closed-loop water recovery systems.
Growth Catalysts
- EU Green Deal compliance:Tanneries investing in vegetable-tanned alternatives capture premium positioning among sustainability-oriented buyers in Northern Europe.
- China domestic brand elevation:Local craftsmanship standards and provincial sourcing requirements concentrate demand for full-grain hides among Shanghai and Guangzhou fashion houses.
- Chrome-tanning efficiency gains:Automated drum processing and chemical recovery systems reduce water intensity per hide processed at scale facilities.
Market Restraints
- Hide supply volatility:Cattle herd fluctuations in Brazil and Argentina create input cost instability for mass-market producers dependent on South American raw material.
- REACH chromium VI thresholds:European tanneries face discharge limit compliance costs that disadvantage smaller operators against consolidated French and Italian competitors with captive treatment infrastructure.
- Synthetic leather substitution:Polyurethane and plant-based alternatives from automotive and footwear sectors erode addressable volume in price-sensitive accessory segments.
Strategic Opportunities
- India export certification:BIS grade standardization opens compliant tanneries to duty-advantaged supply contracts with European luxury houses seeking non-China sourcing.
- Direct-to-consumer channels:Heritage producers bypass wholesale margins through owned digital platforms and flagship experiential retail in Tokyo, Paris, and New York.
- Biobased tanning chemistry:Convergence of enzymatic processing and bio-synthetic tanning agents enables water-neutral production claims for certified sustainable product lines.
Industry Challenges
- Leatherworker apprenticeship gaps:Hermès-style multi-year training programs face enrollment shortages as younger workers migrate to technical manufacturing roles.
- Dual certification timelines:Simultaneous pursuit of LWG environmental and ISO quality credentials extends supplier qualification cycles for new tanning partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leather Goods Market |
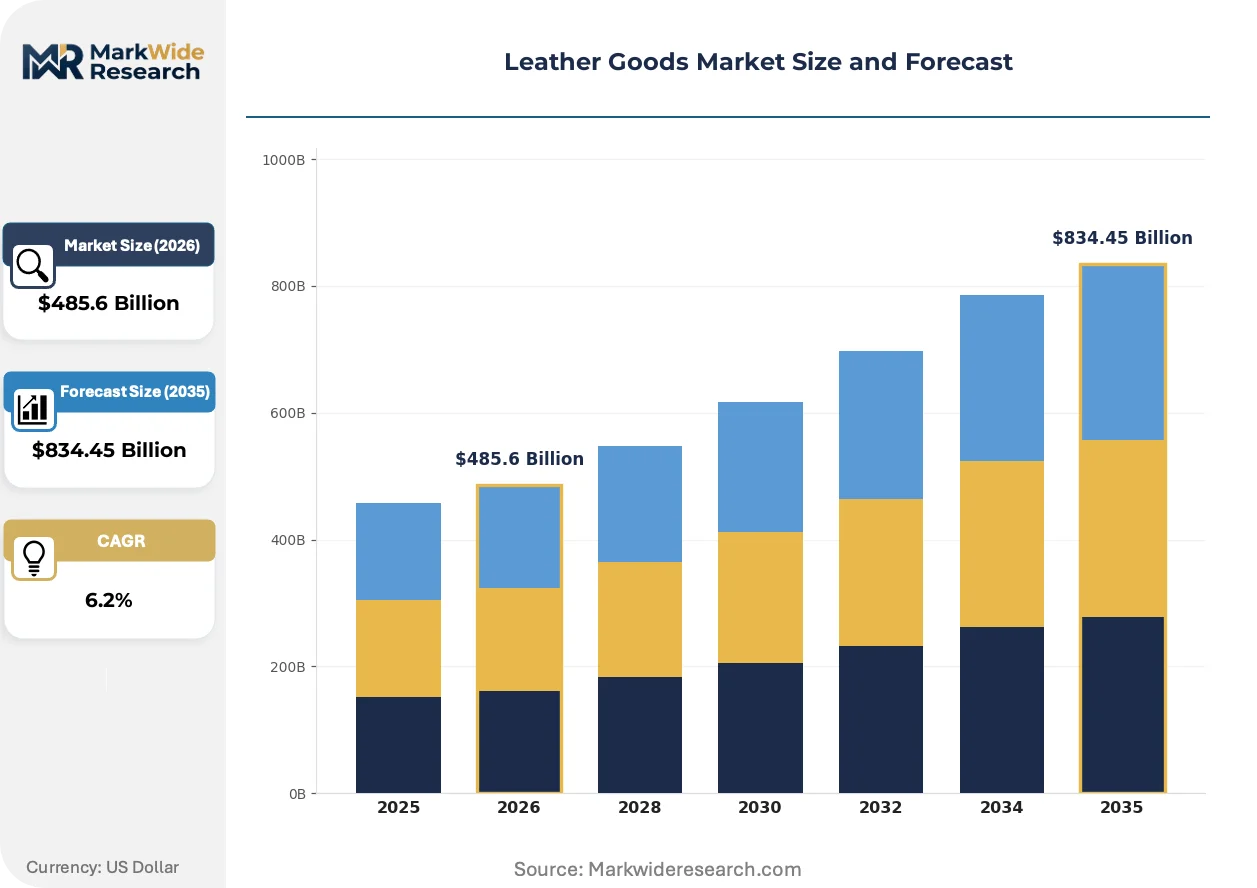
| Market Size in 2026 | $485.6 Billion |
| Market Size in 2035 | $834.45 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Wallets, Footwear, Belts Material Quality: Full Grain, Top Grain, Genuine Leather, Suede Manufacturing Process: Tanned Leather, Vegetable-Tanned, Chrome-Tanned, Synthetic Customer Type: Retail Consumers, Businesses, Wholesalers, E-commerce |
| Companies Covered | Tapestry, Richemont Group, LVMH, Capri Holdings, Burberry Group, Kering, Prada Group, Hugo Boss, Hermès International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leather Goods Market Emerging Trajectories
Digital traceability infrastructure and biobased chemistry are compressing traditional supply chain opacity while reshaping how authenticity claims reach end consumers.
Laser-etching personalization systems are miniaturizing from industrial cutting floors to in-store customization stations. Luxury retailers in Milan and Tokyo deploy compact units for same-day monogramming and pattern engraving. This capability is miniaturizing the production batch size economics that previously required centralized factory investment.
REACH substance restriction expansions now cover additional chromium compound categories beyond VI discharge limits. Tanneries in Veneto and Tuscany retrofit precipitation and membrane filtration systems to recover heavy metals from wastewater streams. Full-grain vegetable-tanned output from these regions commands sourcing preference among houses with Science-Based Targets commitments.
Secondary market authentication services are displacing traditional warranty relationships as the primary trust mechanism for pre-owned leather goods. Digital platforms in Paris and New York partner with independent assessors to verify patina age and craftsmanship provenance. This behavior concentrates transaction liquidity among heritage brands with documented production lineage.
Leather Goods Market Segmentation
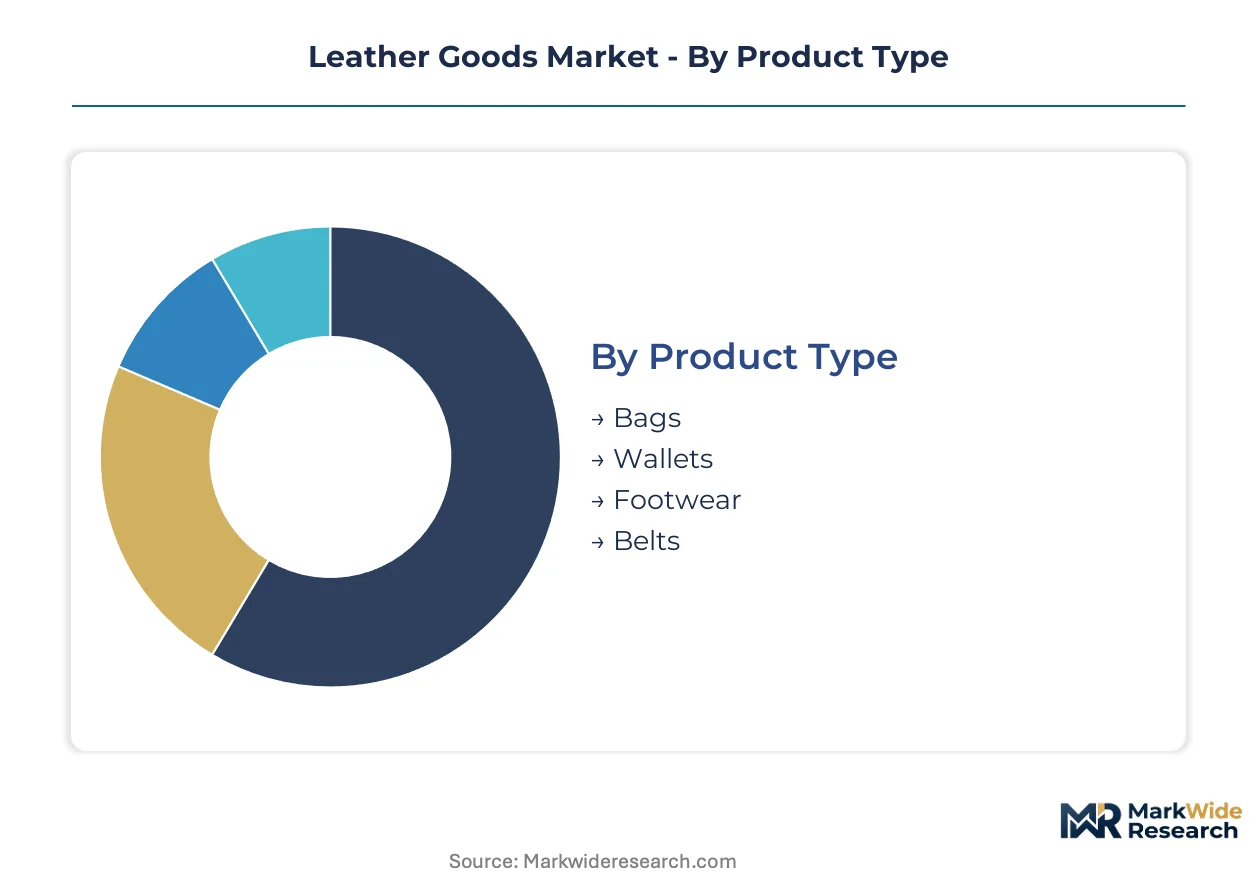
Leather goods segmentation reveals how regulatory pressure and craftsmanship scarcity reshape competitive positioning across material grades and production methods. Distinct buyer requirements for durability, sustainability credentials, and price accessibility fragment addressable volume into non-interchangeable supply chains.
Product Type:
REACH substance restrictions and LWG environmental certification now differentiate import eligibility across European wholesale channels, favoring suppliers with documented chemical recovery systems.
- Bags:Full-grain construction with reinforced stress points dominates heritage house collections in Milan and Paris. Demand concentrates among affluent retail consumers in Shanghai and Tokyo where craftsmanship provenance commands premium positioning.
- Wallets:Compact dimensions require precision cutting from premium hide sections to minimize waste. Gift-market elasticity in Guangzhou and New York drives repeat purchase frequency, though synthetic substitution erodes entry-level volume.
- Footwear:Unit engineering complexity peaks here with lasted construction and soling integration. Brazilian and Argentine hide supply volatility directly impacts mass-market producer margins.
- Belts:Standardized sizing enables automated cutting but limits differentiation. Functional accessory positioning captures volume in price-sensitive segments across Indian and Southeast Asian retail.
Established volume favors bags; emerging adoption favors footwear as direct-to-consumer channels compress traditional wholesale economics.
Material Quality:
Cost tier stratification separates captive tannery supply from commodity hide trading, with full-grain retention of the corium outermost layer commanding the steepest premium escalation.
- Full Grain:The intact surface layer develops distinctive patina through oxidation and handling. Hermès and LVMH secure dedicated supply through French and Italian heritage tanneries with multi-year allocation contracts.
- Top Grain:Sanded and finished surfaces sacrifice natural character for uniformity. Mass-market accessibility in Chinese domestic brands elevates this grade through provincial sourcing requirements.
- Genuine Leather:Corrected grain from lower hide sections meets price elasticity in entry-level accessories. EPA hazardous air pollutant guidelines constrain US finishing operations for this grade.
- Suede:Split leather with napped surface requires specialized tanning chemistry. Niche positioning in luxury footwear and small leather goods limits scalable volume.
Margin concentration favors full grain; volume accessibility favors top grain.
Manufacturing Process:
Application requirements for water resistance, color consistency, and biodegradability claims determine tanning chemistry selection, with EU Green Deal compliance forcing capital redeployment across Veneto and Tuscany facilities.
- Tanned Leather:General preservation category spanning chemical and vegetable methods. Regulatory fragmentation across EPA, REACH, and BIS jurisdictions complicates multi-market certification.
- Vegetable-Tanned:Natural tannin extracts from tree bark enable biodegradability claims and rich patina development. Northern European sustainability-oriented buyers concentrate demand here, though artisanal capacity bottlenecks limit output velocity.
- Chrome-Tanned:Chromium salt processing delivers colorfastness and water resistance at scale. Kering's controlled partnerships balance efficiency against REACH chromium VI discharge threshold compliance.
- Synthetic:Polyurethane and plant-based alternatives displace addressable volume in automotive and price-sensitive footwear segments. Material innovation from Japanese and South Korean chemical producers accelerates performance parity claims.
Scale efficiency favors chrome-tanned; sustainability positioning favors vegetable-tanned.
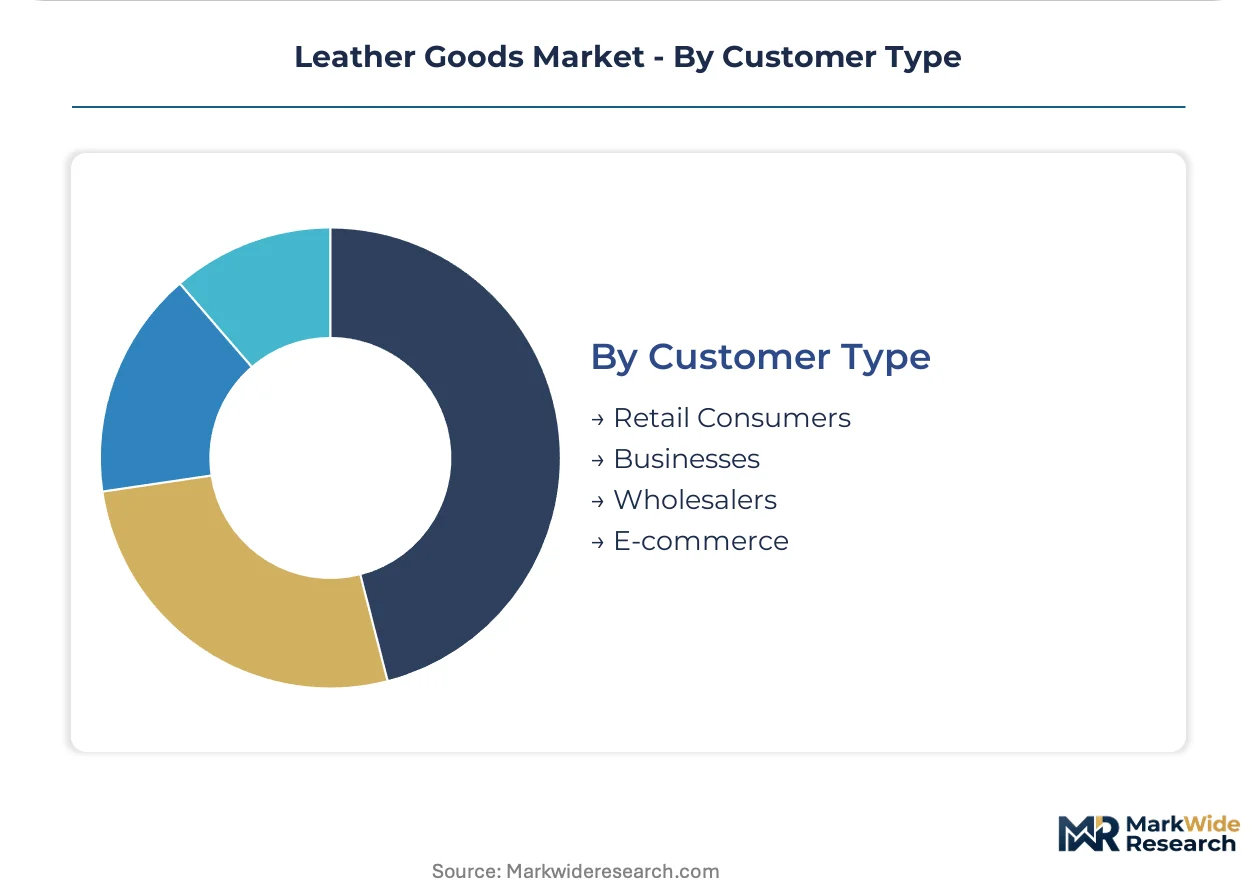
Customer Type:
Procurement patterns fragment between experiential flagship investment and algorithmic inventory management, with wholesale margin compression accelerating direct channel development.
- Retail Consumers:Individual purchasers seeking functional durability and status signaling. Tokyo, Paris, and New York flagship locations capture premium through in-store laser-etching personalization.
- Businesses:Corporate gifting and uniform programs require volume consistency and logo customization. BIS certification requirements in India standardize quality grades for export competitiveness to this segment.
- Wholesalers:Traditional distribution intermediaries face disintermediation as heritage producers deploy owned digital platforms. Margin pressure concentrates transaction liquidity toward direct relationships.
- E-commerce:Digital-native channels require secondary market authentication partnerships to verify provenance. Paris and New York platforms displace traditional warranty relationships as primary trust mechanisms.
Transaction control favors e-commerce; volume concentration favors businesses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH chemical disclosure mandates from the European Chemicals Agency anchor the most stringent regulatory environment, forcing tannery investment toward closed-loop water recovery across France and Italy while redirecting sourcing flows toward compliant suppliers in India and China.
France
Hermès International and LVMH sustain multi-year allocation contracts with heritage tanneries in the Limousin and Alsace regions. EU Green Deal compliance requirements accelerate vegetable-tanned output from these captive facilities. The Paris fashion cluster concentrates finishing operations and flagship experiential retail locations.
Italy
Artisanal tanning capacity bottlenecks in Veneto and Tuscany limit production velocity for full-grain vegetable-tanned hides. REACH chromium VI discharge thresholds force precipitation and membrane filtration retrofits across Arzignano and Santa Croce sull'Arno industrial zones. Kering's controlled chrome-tanning partnerships balance scale efficiency against environmental compliance costs.
China
Domestic brand elevation in Shanghai and Guangzhou concentrates demand for full-grain hides among provincial fashion houses. Local craftsmanship standards and sourcing requirements displace import dependency for premium accessories. The Pearl River Delta retains mass-market chrome-tanning scale despite sustainability-oriented buyer migration toward vegetable-tanned alternatives.
India
BIS certification requirements standardize leather quality grades for export competitiveness to European luxury houses. Kanpur and Kolkata tanneries capture duty-advantaged supply contracts as non-China sourcing accelerates. EPA hazardous air pollutant guidelines constrain US market access for untreated hide exports from smaller operators.
United States
Direct-to-consumer channels from heritage producers bypass wholesale margins through owned digital platforms and flagship locations in New York. EPA guidelines govern hazardous air pollutants from leather finishing operations, affecting import eligibility for untreated hides. Secondary market authentication services in New York displace traditional warranty relationships as primary trust mechanisms.
Leather Goods Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive tannery control separating premium positioning from commodity sourcing. Consolidated French and Italian competitors deploy multi-year allocation contracts to secure full-grain supply chains. Three archetypes dominate: heritage houses with apprenticeship programs, conglomerates with backward integration into tanning capacity, and scale-driven specialists with automated drum processing. Competitive moves concentrate on strategic partnerships for chemical recovery systems and geographic expansion through direct-to-consumer flagship deployment.
Within the integrated luxury tier, LVMH and Hermès International exemplify archetypes of captive supply chain control, while Kering occupies a position balancing scale efficiency with environmental compliance partnerships. These French-listed entities anchor the premium positioning vector through multi-decade tannery relationships and controlled production velocity.
| Leading Market Players |
|---|
| Tapestry |
| Richemont Group |
| LVMH |
| Capri Holdings |
| Burberry Group |
| Kering |
| Prada Group |
| Hugo Boss |
| Hermès International |
| Others |
Supply Flow & Price Mechanics
Automated drum processing scale economies in Arzignano and Santa Croce sull'Arno concentrate chrome-tanning output among consolidated Italian operators, anchoring price floors for mass-market grades while vegetable-tanned artisanal scarcity lifts heritage premiums. REACH compliance capital requirements widen the cost spread between closed-loop equipped facilities and smaller tanneries facing discharge limit retrofit burdens.
Pricing Analysis
Geographic price spreads between Veneto heritage output and Pearl River Delta mass production reflect divergent labor intensity and chemical recovery system investments. Three-tier pricing structure across premium, standard, and economy levels segments buyers by craftsmanship provenance and certification grade. Price differentiation centers on LWG environmental credentials and full-grain hide allocation contracts. Cost compression in entry-level wallets intensifies as polyurethane alternatives from South Korean chemical producers narrow performance gaps. Business procurement programs exhibit lowest price sensitivity due to volume consistency requirements, while individual retail consumers in price-sensitive Southeast Asian markets drive hardest bargain hunting.
Supply Chain Analysis
Inventory strategy preferences split between just-in-time hide procurement at automated scale facilities and strategic stockpiling of premium full-grain allocations by heritage houses. Raw material sourcing draws from Brazilian and Argentine cattle herds for mass-market chrome-tanned output, French Limousin and Italian Tuscan heritage tanneries for vegetable-tanned full-grain, and Kanpur processing clusters for BIS-certified export grades. Supply chain risk concentrates in South American hide supply volatility from herd fluctuations. Distribution runs through direct-to-consumer flagship channels in Tokyo, Paris, and New York alongside traditional wholesale intermediaries facing disintermediation pressure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across REACH, EPA, and BIS jurisdictions fragments supplier qualification criteria, creating white-space opportunities for tanneries that consolidate multi-market certification. Sustainability-oriented buyer migration toward vegetable-tanned alternatives opens niche positioning for new entrants with biobased chemistry capabilities.
For Market Incumbents: Secure captive full-grain supply through multi-year allocation contracts with Limousin and Alsace heritage tanneries before artisanal capacity contracts further. Invest in closed-loop water recovery systems to defend margin position against REACH chromium VI compliance cost escalation. Control direct-to-consumer flagship channels in experiential retail locations to bypass wholesale margin compression.
For New Entrants and Emerging Players: LWG certification fast-track enables supplier qualification to European luxury houses seeking non-China sourcing alternatives. Target Indian BIS-compliant tanneries in Kanpur and Kolkata for duty-advantaged export contracts. Pursue biobased tanning chemistry partnerships to claim water-neutral production credentials among Northern European sustainability-oriented buyers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors tanneries with enzymatic processing capabilities and bio-synthetic tanning agent integration. Long-term viability hinges on regulatory compliance infrastructure rather than commodity scale. Acquisition targets should demonstrate captive heritage relationships or certified sustainable chemistry pipelines. Watch for REACH substance restriction expansions beyond chromium VI as inflection indicator for vegetable-tanned capacity valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Tannery Acquisition | Secures multi-decade full-grain allocation contracts with Limousin and Alsace producers. |
| Closed-Loop Water Recovery Deployment | Enables REACH chromium VI discharge compliance across Veneto and Tuscany facilities. |
| Direct-to-Consumer Flagship Expansion | Captures experiential retail margins in Tokyo, Paris, and New York locations. |
| Biobased Tanning Chemistry Partnership | Unlocks water-neutral production claims for Science-Based Targets committed buyers. |
| Indian BIS Certification Investment | Opens duty-advantaged supply contracts with European luxury houses diversifying from China. |
Methodological Framework
The analysis maps full-grain, top-grain, and corrected-grain material tiers alongside chrome-tanned, vegetable-tanned, and synthetic processing methods, each validated through tannery operations directors, luxury house procurement leads, and retail category buyers. Primary interviews with heritage leatherworkers, chemical recovery system engineers, and sustainability certification auditors combined with secondary validation from REACH substance restriction filings, BIS quality grade standards, and LWG environmental audit databases. Customs records from Indian DGFT and European import eligibility criteria anchored supply flow quantification. Bottom-up tannery capacity modeling and top-down luxury house revenue attribution triangulated market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including material quality grade, tanning chemistry type, end-use product category, and customer procurement pattern throughout the forecast period. CAGRs derived from regression analysis of historical capacity utilization, regulatory compliance cost trajectories, and buyer willingness-to-pay shifts for sustainability credentials. Forecast inputs incorporated hide supply volatility indices from Brazilian and Argentine agricultural statistics and enzymatic processing technology adoption curves.
Decision-makers should treat outputs as directional under sustained REACH enforcement intensity and China domestic brand elevation assumptions; material deviation would warrant model refresh. Forecasts reflect these base conditions without guaranteeing specific trajectory realization. Revision becomes warranted when biobased tanning chemistry cost parity crosses commercial viability thresholds or when Indian BIS certification adoption accelerates beyond current compliance rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Fabric Freshener Market
Consumer Goods
Chile Vegan Cosmetics Market
Consumer Goods
Nail Lamps Market
Consumer Goods
Electric Rice Cooker Market
Consumer Goods
Body Cream Jars Market
Consumer Goods
UAE Dog Food Market
Consumer Goods
North America Gaming Accessories Market
Consumer Goods
Heated Towel Rail Market
Consumer Goods
Claw Machine Market
Consumer Goods
DIY Eyelash Extension Market
Consumer Goods
Thailand Skin Care Products Market
Consumer Goods
Thailand Pet Food Market
Consumer Goods
Smart Musical Instrument Market
Consumer Goods
Maternity Products Market
Consumer Goods
United States Major Home Appliances Market
Consumer Goods
Europe Fashion Accessories Market