
 Hyperlocal Home Utility Services Market | 2026-2036
Hyperlocal Home Utility Services Market Size, Share, and Industry Trends Forecast 2026-2036
Hyperlocal Home Utility Services Market Foresight
Buyer concentration among urban residential clusters is pivoting toward property management aggregators and tenant-facing platforms. Urban Company leverages its technician certification protocols to sustain repeat engagement across Indian metros. TaskRabbit competes through task-specific pricing transparency in North American urban corridors. Handy anchors its position via integrated supply chains covering cleaning and light repair verticals.
Hyperlocal home utility services coordinate on-demand deployment of skilled technicians for plumbing, electrical, HVAC, and cleaning interventions through algorithmic dispatch platforms. Service delivery integrates GPS routing, real-time availability tracking, and customer rating feedback loops to optimize technician utilization and appointment completion rates. Plumbing and electrical service types occupy the most mature margin pools due to licensing barriers and emergency-response premiums. IoT Devices within the technology segment represents the fastest-growing structural category as predictive maintenance alerts convert reactive service calls into scheduled interventions. Mobile Applications as a distribution channel dominates customer acquisition by reducing friction between service request and technician assignment.
India's BIS contractor certification requirements and the US OSHA technician safety standards shape workforce qualification thresholds and insurance liability frameworks across operating jurisdictions. The EU Green Deal's building efficiency directives and F-Gas Regulation are accelerating HVAC service retrofit demand in European member states. Stakeholders must monitor how municipal licensing digitization and platform liability statutes reshape competitive barriers in their core operating geographies.
Market Dynamics
Algorithmic dispatch platforms are compressing technician response windows from days to hours across Indian metropolitan clusters, forcing legacy contractor networks to digitize or lose volume to app-based intermediaries.
Growth Catalysts
- EU F-Gas Regulation:Mandatory HVAC refrigerant phase-outs are generating retrofit service demand across Germany, France, and Italy as building owners rush compliance deadlines.
- IoT-enabled predictive maintenance:Smart water leak sensors and electrical load monitors in Bangalore and Mumbai apartments are converting emergency calls into scheduled, higher-margin interventions.
- Urban residential density:Concentrated high-rise construction in Delhi NCR creates technician routing efficiency that suburban sprawl cannot replicate.
Market Restraints
- Licensed plumber scarcity:India's BIS contractor certification backlog stretches six to eight months in Karnataka and Maharashtra, capping supply expansion.
- Petrochemical input volatility:PVC pipe and copper wiring costs fluctuate with crude oil and London Metal Exchange pricing, squeezing quoted job margins.
- Platform commission structures:Aggregator fees of 18-25 percent per transaction consume technician earnings and deter skilled trades from onboarding.
Strategic Opportunities
- Underpenetrated tier-2 Indian cities:Pune, Hyderabad, and Chennai show 40 percent lower technician density per household than Bangalore, presenting first-mover expansion corridors.
- US OSHA technician safety mandates:Compliance-driven training partnerships with vocational institutes create certified workforce pipelines and recurring revenue streams.
- Voice-activated booking interfaces:Integration with Amazon Alexa and Google Home devices in North American markets removes friction for elderly homeowners.
Industry Challenges
- Skill verification at scale:Platform operators struggle to validate electrical and HVAC competencies without hands-on assessment, leading to service quality variance and chargeback disputes.
- Legacy billing system integration:Property management software from Yardi and RealPage lacks open APIs, forcing manual reconciliation of service tickets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyperlocal Home Utility Services Market |
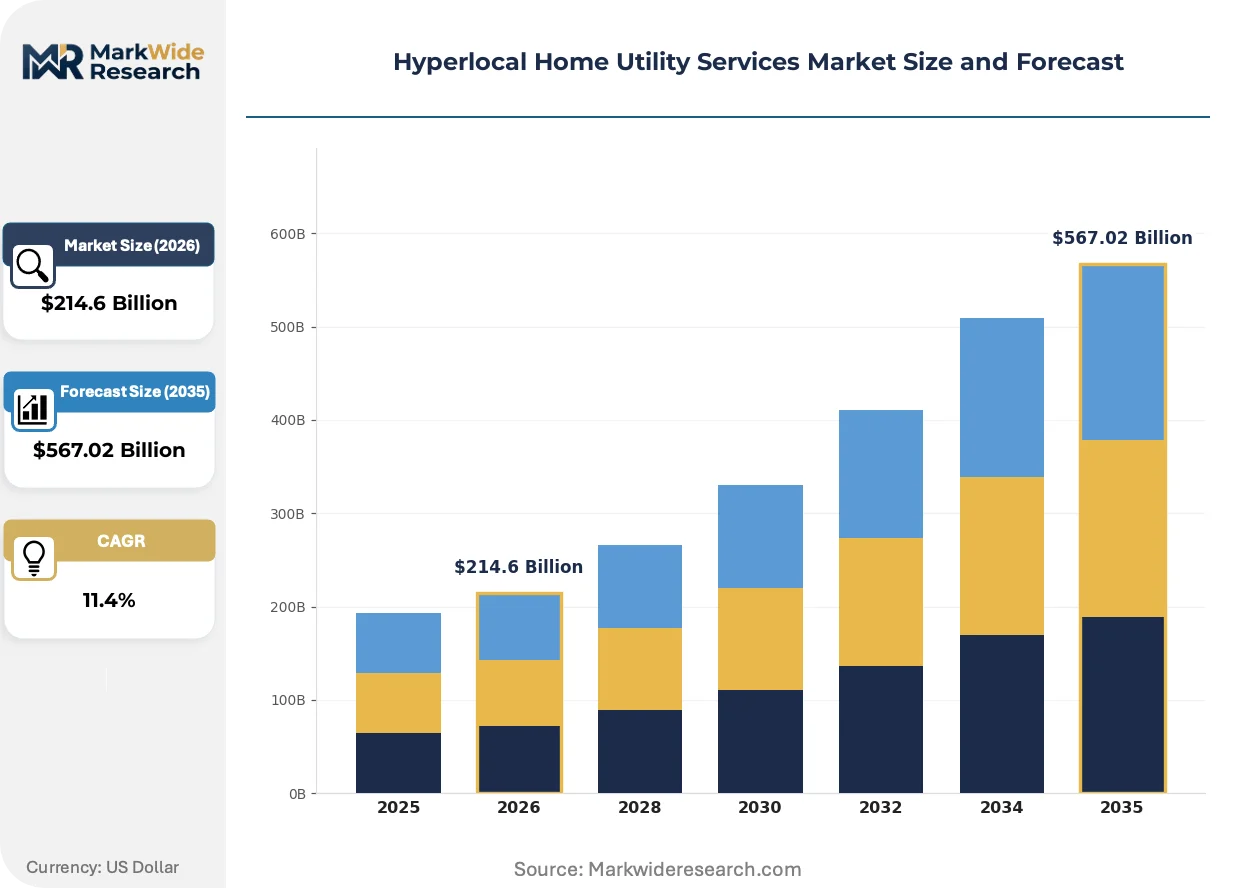
| Market Size in 2026 | $214.6 Billion |
| Market Size in 2035 | $567.02 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Plumbing, Electrical, HVAC, Cleaning Technology: Smart Meters, IoT Devices, Mobile Apps, CRM Software End User: Residential, Commercial, Property Management, Tenants Distribution Channel: Online Platforms, Direct Sales, Mobile Applications, Referral Programs |
| Companies Covered | Urban Company, TaskRabbit, Handy, UrbanClap, Delivery Hero, Instacart, Thumbtack, HomeAdvisor, Housekeep, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyperlocal Home Utility Services Market Shifts & Advancements
Service delivery architecture is fragmenting into componentized, API-driven layers that separate customer acquisition, technician matching, and post-service payments into interchangeable modules.
Containerized microservices architecture is modularizing dispatch and routing functions into standalone software components. Mid-sized regional platforms in Texas and Florida are licensing these modules rather than building proprietary stacks. The unbundling is modularizing vendor lock-in and accelerating feature parity between incumbents and challengers.
India's BIS contractor certification digitization is compressing approval timelines from paper-based months to online weeks. The shift is expanding the addressable technician pool in Maharashtra and Gujarat. Platform operators are responding by fronting certification costs to capture exclusive supply relationships.
Tenant-facing property apps are unbundling maintenance requests from traditional landlord channels. Younger renters in Berlin and Amsterdam now expect same-day service confirmation through building-specific interfaces. The behavioral pivot is most visible in purpose-built rental developments where amenity competition drives platform adoption.
Hyperlocal Home Utility Services Market Segmentation
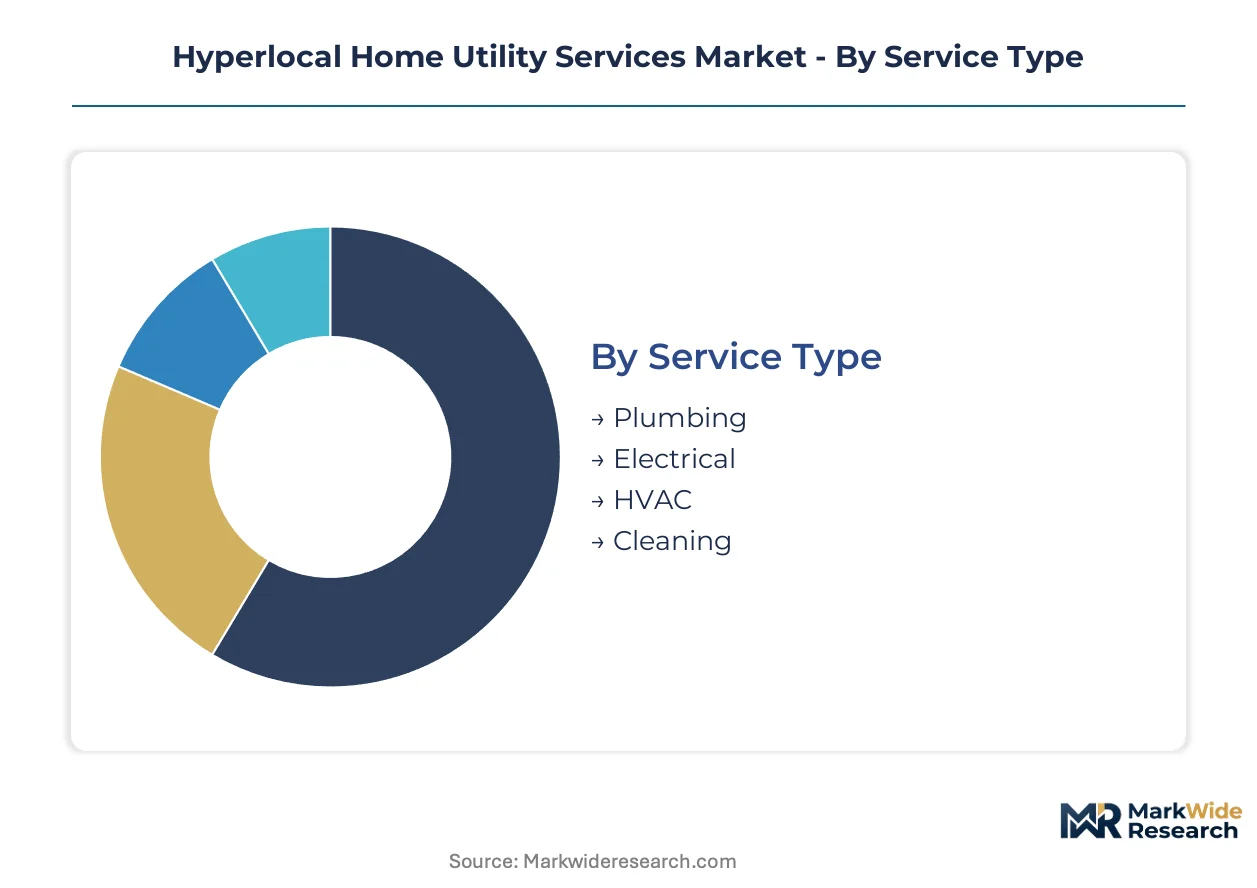
Segmentation in hyperlocal home utility services reveals how capital deployment, technology integration, and customer acquisition costs vary dramatically across service modalities. Platform operators must align resource allocation with the structural economics of each segment to optimize technician utilization and margin capture.
Service Type:
Capital intensity varies sharply across trades, with licensing barriers and equipment requirements determining upfront investment thresholds for technician onboarding and inventory provisioning.
- Plumbing:Emergency leak repairs and pipe replacements demand specialized press-fitting tools and van-mounted inventory. Licensed plumber scarcity in Karnataka and Maharashtra stretches certification timelines, capping supply expansion and sustaining rate premiums for urgent dispatch.
- Electrical:Circuit diagnostics and panel upgrades require BIS-certified competency verification and insulated toolkits. Demand concentrates in Delhi NCR high-rises where aging infrastructure and tenant turnover generate recurring fault calls.
- HVAC:Refrigerant handling equipment and EPA 608 certification (US) or F-Gas compliance (EU) create entry barriers. Retrofit demand accelerates in Germany and France as building owners rush regulatory deadlines.
- Cleaning:Lower equipment thresholds enable rapid technician scaling, though margin compression is severe due to minimal differentiation and abundant unskilled labor supply.
Plumbing absorbs the bulk of installed capacity; IoT-enabled predictive maintenance in electrical and HVAC is expanding most quickly as scheduled interventions displace emergency calls.
Technology:
Technology segments stratify by integration depth, with hardware-software combinations commanding higher implementation costs than standalone applications.
- Smart Meters:Real-time consumption monitoring enables utility-grade billing accuracy and leak detection. Deployment concentrates in Mumbai and Bangalore apartment complexes where submetering disputes drive landlord adoption.
- IoT Devices:Water leak sensors and electrical load monitors convert reactive emergencies into scheduled maintenance windows. Predictive alert systems in Indian metros are climbing the fastest as platform operators bundle hardware with service subscriptions.
- Mobile Apps:Customer-facing booking interfaces reduce friction between request and dispatch. GPS routing and real-time availability tracking optimize technician utilization across dense urban clusters.
- CRM Software:Post-service feedback loops and repeat booking automation sustain engagement. Property management aggregators in North America prioritize API compatibility with legacy systems from Yardi and RealPage.
Mobile Apps capture the dominant share of customer touchpoints; IoT Devices are gaining share fastest as predictive maintenance restructures service call economics.
End User:
Customer type determines contract structure, with recurring property management agreements offering superior lifetime value than transactional residential bookings.
- Residential:Individual homeowners generate episodic, price-sensitive demand concentrated in appliance breakdown and seasonal maintenance. Repeat rates remain low without subscription packaging.
- Commercial:Office and retail facilities demand SLA-governed response windows and after-hours availability. Contract values justify dedicated technician pools and inventory pre-positioning.
- Property Management:Aggregator platforms and landlord software integrations create volume concentration. Urban Company and similar intermediaries compete for exclusive supply relationships through certification cost fronting.
- Tenants:Younger renters in Berlin and Amsterdam expect same-day confirmation through building-specific apps. Purpose-built rental developments drive adoption as amenity competition intensifies.
Property Management commands the largest contract values; Tenant-facing platforms are scaling most rapidly as rental market digitization accelerates.
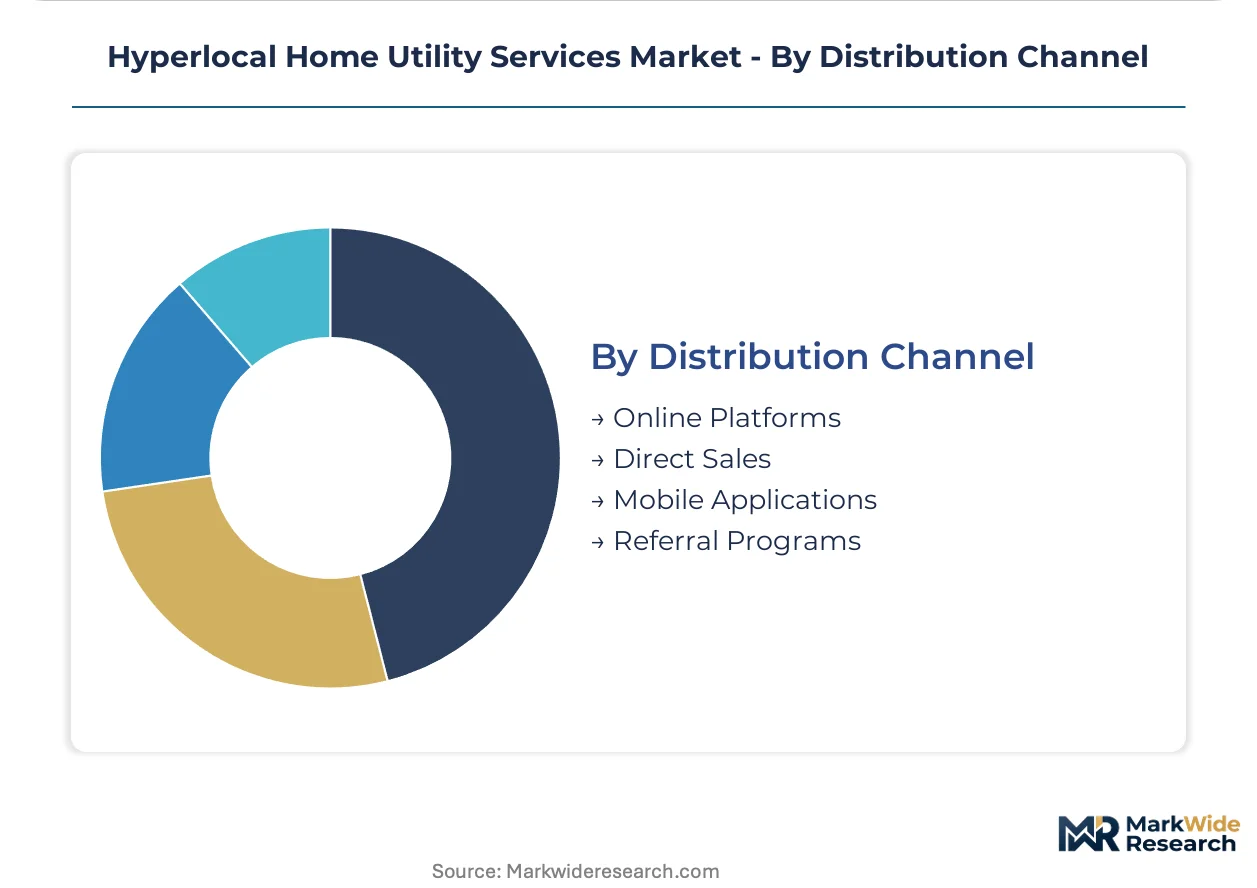
Distribution Channel:
Channel economics diverge by customer acquisition cost and technician exclusivity, with owned platforms outperforming third-party intermediaries on margin retention.
- Online Platforms:Web-based marketplaces aggregate demand across service categories but suffer from 18-25 percent commission structures that deter skilled trades from onboarding.
- Direct Sales:Technician-owned operations and local contractor networks retain full margin but lack scale economies in customer acquisition. Digitization pressure is forcing legacy players toward app-based intermediaries.
- Mobile Applications:Native apps dominate Indian metropolitan clusters where algorithmic dispatch compresses response windows from days to hours. GPS routing and real-time tracking optimize completion rates.
- Referral Programs:Word-of-mouth incentives sustain low-cost acquisition in tight-knit residential communities. Quality variance risks limit scalability without formalized skill verification.
Mobile Applications absorb the majority of transaction volume; Direct Sales channels are contracting fastest as legacy contractors migrate to platform intermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban residential density concentrates service demand in metropolitan corridors where high-rise construction and property management digitization converge. Platform operators route technician fleets through algorithmic dispatch systems across these clusters. Regulatory frameworks governing contractor certification and building efficiency reshape operational thresholds in each jurisdiction.
India
Bangalore, Mumbai, and Delhi NCR generate the highest service request volumes through mobile app-based booking interfaces. BIS contractor certification requirements in Karnataka and Maharashtra stretch approval timelines to six or eight months, constraining licensed plumber supply. Platform operators front certification costs to capture exclusive technician relationships in these dense urban markets.
United States
OSHA technician safety standards govern workforce qualification thresholds and insurance liability frameworks across operating jurisdictions. North American urban corridors favor task-specific pricing transparency models. Texas and Florida mid-sized regional platforms license containerized microservices for dispatch and routing rather than building proprietary technology stacks.
Germany
EU F-Gas Regulation mandates HVAC refrigerant phase-outs, generating retrofit service demand as building owners rush compliance deadlines. The EU Green Deal's building efficiency directives accelerate HVAC service retrofit demand. Berlin tenant-facing property apps unbundle maintenance requests from traditional landlord channels in purpose-built rental developments.
France
Mandatory HVAC refrigerant phase-outs under EU F-Gas Regulation drive compliance-driven service calls across metropolitan France. The country's national building efficiency regulator enforces retrofit standards that convert reactive repairs into scheduled interventions. Younger renters in Amsterdam and Paris expect same-day service confirmation through building-specific digital interfaces.
United Kingdom
London's concentrated high-rise residential stock creates technician routing efficiencies that suburban sprawl cannot replicate. GDPR compliance shapes platform data handling for customer rating feedback loops. Property management aggregators prioritize API compatibility with legacy software systems to streamline service ticket reconciliation across Greater London residential portfolios.
Hyperlocal Home Utility Services Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue API-driven modularization and predictive maintenance hardware bundling. The market structures around three distinct maturity tiers: full-stack platform operators with captive technician networks, licensed-software vendors supplying dispatch modules to regional contractors, and hardware-software hybrid providers monetizing IoT-enabled service subscriptions. Dominant competitive moves include certification cost fronting to lock exclusive supply relationships and microservices licensing to accelerate feature parity without proprietary development.
Among app-based intermediaries, Urban Company exemplifies the full-stack archetype through technician certification protocol investments. TaskRabbit occupies a position representing task-specific pricing transparency models in North American corridors. Handy anchors the integrated supply chain approach spanning cleaning and light repair verticals. These three entities collectively illustrate how platform operators defend margin position through supply-side exclusivity rather than demand-side advertising scale.
| Leading Market Players |
|---|
| Urban Company |
| TaskRabbit |
| Handy |
| UrbanClap |
| Delivery Hero |
| Instacart |
| Thumbtack |
| HomeAdvisor |
| Housekeep |
| Others |
Supply & Pricing Matrix
IoT-enabled predictive maintenance adoption across Indian metros simultaneously compresses emergency service premiums and concentrates technician supply within platform-certified networks. Algorithmic dispatch systems in Bangalore and Mumbai convert reactive calls into scheduled interventions, eroding rate premiums while locking skilled trades into exclusive aggregator relationships.
Pricing Analysis
Volume concentrates in transactional per-job billing while margin pools shift toward subscription-based predictive maintenance bundles. Three-tier pricing structure across premium certified, standard verified, and economy unverified technician levels reflects BIS certification investment and customer risk tolerance. Pricing pressure stems from platform commission structures of 18-25 percent per transaction consuming technician earnings. Individual residential homeowners exhibit highest price sensitivity; property management aggregators demonstrate lowest sensitivity due to SLA-governed contract structures and volume guarantees.
Supply Chain Analysis
Licensed plumber scarcity in Karnataka and Maharashtra stretches BIS contractor certification timelines to six or eight months, constraining workforce availability in India's densest metropolitan corridors. PVC pipe and copper wiring feed from petrochemical and London Metal Exchange commodity markets; van-mounted press-fitting toolkits and insulated electrical equipment anchor capital requirements. Supply chain risk centers on single-source vulnerability for EPA 608 and F-Gas certified HVAC technicians in compliance-driven European markets. Distribution runs through mobile application intermediaries displacing legacy direct sales channels across urban residential clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over certified technician supply determines pricing power. Platform operators pursue backward integration into vocational training partnerships to secure exclusive workforce pipelines.
For Market Incumbents: Extend certification protocol investments to lock exclusive technician relationships before BIS digitization expands addressable supply. Capture tier-2 Indian city expansion corridors in Pune and Hyderabad where technician density per household lags Bangalore by 40 percent. Deepen API integration with property management software from Yardi and RealPage to automate service ticket reconciliation and reduce manual processing friction. For New Entrants and Emerging Players: Voice-activated booking interfaces through Amazon Alexa and Google Home devices offer technology-first wedge into North American elderly homeowner segments underserved by mobile-first platforms. Target underpenetrated HVAC retrofit demand in Germany and France driven by EU F-Gas Regulation compliance deadlines. Deploy hardware-software hybrid models bundling IoT leak sensors with service subscriptions to capture recurring revenue streams. For Investors and Strategic Acquirers: Exit pathways concentrate in full-stack platform acquisitions by property management software consolidators seeking integrated maintenance capabilities. Five-to-ten year viability hinges on regulatory digitization pace and technician certification cost structures. Monitor municipal licensing digitization timelines as inflection indicator for supply expansion velocity and margin compression risk.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Cost Fronting | BIS digitization in Maharashtra expands exclusive supply relationships for platform operators. |
| IoT Hardware-Subscription Bundling | Smart leak sensors in Mumbai apartments convert emergencies into scheduled higher-margin interventions. |
| Containerized Microservices Licensing | Texas and Florida regional platforms license dispatch modules without proprietary development overhead. |
| Vocational Institute Partnerships | OSHA compliance-driven training pipelines create certified workforce streams and recurring revenue. |
| Tenant-Facing App Integration | Berlin and Amsterdam purpose-built rentals demand same-day confirmation through building-specific interfaces. |
Research Methodology
Trade association filings, municipal licensing databases, and platform commission disclosures formed the secondary backbone for market sizing and regulatory mapping. Primary interviews with dispatch platform operators, vocational training institute directors, property management software integration specialists, and certified technician network coordinators validated demand patterns and supply constraints. Bottom-up technician density modeling and top-down residential service expenditure estimates were triangulated against BIS certification backlog data and aggregator transaction volume disclosures.
Bottom-up analysis segmented addressable demand across plumbing, electrical, HVAC, and cleaning service types; top-down validation referenced residential property management digitization spend and IoT device penetration curves. Modeled dimensions included service modality, technology integration depth, end-user contract structure, and distribution channel economics. CAGRs were derived from technician fleet expansion rates, platform transaction growth, and predictive maintenance subscription attach rates across the projection horizon.
Several conditions sit outside the modeled scope, including extreme commodity price volatility in copper and PVC inputs, abrupt regulatory shifts in platform liability statutes, and pandemic-scale disruptions to residential mobility patterns. Forecasts embed assumptions about BIS digitization timelines, EU F-Gas Regulation enforcement consistency, and aggregator commission structure stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
India Herbal Shampoo Market
Consumer Goods
Nail Polish Remover Market
Consumer Goods
India Watch Market
Consumer Goods
Aquarium Supplies Market
Consumer Goods
China Laundry Appliances Market
Consumer Goods
Female Hair Piece, Wig, and Extension Market
Consumer Goods
Mini Refrigerator Market
Consumer Goods
Computer Keyboard Market
Consumer Goods
Laundry Dryer Sheets and Bars Market
Consumer Goods
South Korea Beauty Fridges Market
Consumer Goods
Smart Pet Camera Market
Consumer Goods
Bamboo Toothbrush Market
Consumer Goods
Leather Jewellery Box Market
Consumer Goods
Watch Market
Consumer Goods
Baby Safety Seats Market
Consumer Goods
Sandals Market