
 Leather Handbags Market | 2026-2036
Leather Handbags Market Size, Share, and Industry Trends Forecast 2026-2036
Leather Handbags Market Outlook
Italy is tilting toward specialized vegetable-tanned leather production for heritage-grade accessories. Coach leverages its North American retail footprint to sustain brand visibility in department store channels. Italian Artisan anchors its competitive stance on Florentine workshop methods and limited-batch output.
A leather handbag is a portable container constructed from tanned animal hide, typically featuring reinforced stitching, metal hardware, and interior compartmentalization, designed for personal item transport and fashion expression. Crossbody designs lead volume growth among urban commuters seeking hands-free mobility, while the luxury price tier captures the dominant margin pool due to brand equity and material exclusivity. Totes retain structural importance in professional segments where capacity and durability determine purchase decisions.
REACH compliance in Europe restricts chromium VI usage in tanning processes, redirecting investment toward vegetable and synthetic tanning alternatives. The FDA's oversight of leather chemical residues in imported goods shapes US market access protocols for foreign manufacturers. Stakeholders must monitor evolving traceability mandates and raw material certification requirements to secure supply chain continuity.
Market Dynamics
REACH chemical safety standards are redirecting tanning chemistry investment across European supply chains, forcing producers to abandon chromium VI processes and rebuild certification infrastructure around vegetable-tanned alternatives.
Growth Catalysts
- EU REACH Compliance Mandates:Leather processors in Italy and Spain are converting tanneries to vegetable-tanning systems, creating premium positioning for heritage-grade output certified under ECHA protocols.
- Urban Professional Commuter Demand:Crossbody configurations dominate volume expansion as hands-free mobility requirements reshape bag architecture for subway and bicycle transit users in dense metropolitan cores.
- China Tier-One City Concentration:Shanghai and Beijing consumers are expanding multi-bag wardrobes, sustaining parallel demand tracks for European heritage labels and ascending domestic design houses.
Market Restraints
- Raw Hide Input Volatility:Beef and dairy herd contraction in Brazil and Argentina is compressing hide availability, forcing tanneries to absorb price spikes or reformulate leather blends.
- Regulatory Friction from FDA Import Screening:US customs chemical residue testing protocols are extending clearance timelines for Asian-manufactured goods, adding working capital burden to offshore producers.
- Synthetic Leather Substitution:Polyurethane and bio-based alternatives from industrial chemical suppliers are capturing entry-level price tiers where brand equity remains undeveloped.
Strategic Opportunities
- Underpenetrated Indian Urban Centers:Mumbai and Delhi professional segments show nascent multi-bag purchasing patterns comparable to China five years prior, with limited domestic heritage competition.
- Blockchain Material Traceability:Convergence of distributed ledger systems with IoT tagging is enabling batch-level provenance verification that commands price premiums in European and North American channels.
- Direct-to-Consumer Channel Expansion:Owned digital storefronts bypass department store margin extraction while capturing behavioral data for configuration personalization.
Industry Challenges
- Artisan Skill Pipeline Collapse:Florentine and Cordoban workshop traditions face generational transfer gaps as younger workers migrate to technology sectors, compressing master-craftsperson availability.
- Multi-Jurisdiction Certification Overlap:Simultaneous compliance with REACH, FDA import protocols, and emerging state-level chemical disclosure laws in California creates documentation complexity and audit redundancy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leather Handbags Market |
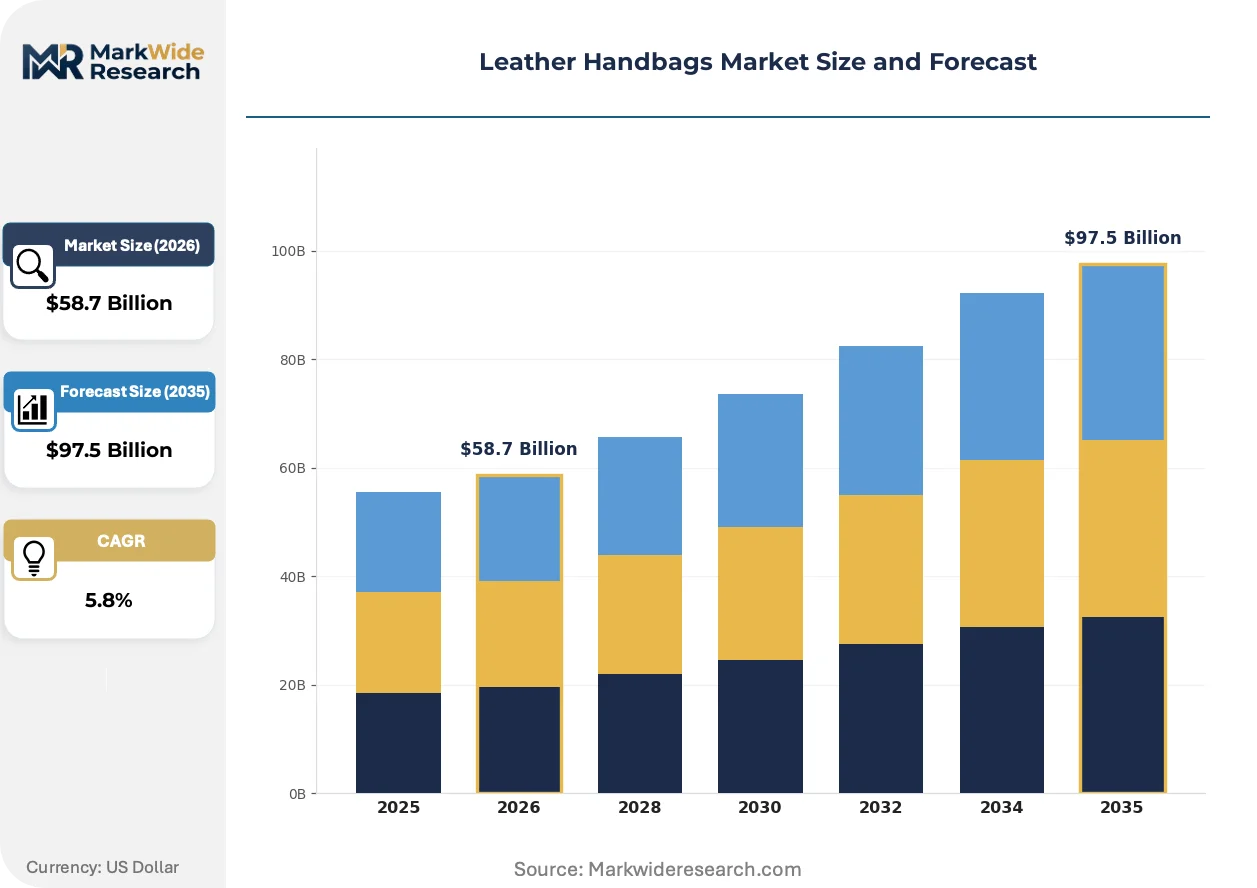
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $97.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Satchels, Totes, Crossbody, Clutches End User: Women, Men, Children, Unisex Distribution Channel: Online, Offline, Boutiques, Department Stores Price Tier: Luxury, Premium, Mid-range, Budget |
| Companies Covered | Coach, Saddleback Leather Co., Italian Artisan, Shinola, JW Hulme, Loipell, Fossil, Xinzirain, Niccoli Bags, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leather Handbags Market Strategic Shifts
Digital manufacturing tools and bio-engineered materials are compressing traditional production timelines while regulatory chemistry bans force process reinvention across tanning clusters.
Laser-cutting and CNC stitching automation is collapsing the cost structure for made-to-order small-batch production. Independent designers in Lisbon and Mexico City are adopting these systems to offer customization at near-mass-market price points. The technology is collapsing the historical tradeoff between personalization and unit economics that protected large-scale manufacturers.
REACH Annex XVII restrictions on chromium VI are forcing tannery reconversion across Veneto and Tuscany. Vegetable-tanning revival requires 30-60 day processing cycles versus chrome's 24-hour turnaround, reshaping inventory planning and supplier financing. Italian processors are responding by specializing in heritage-grade output where extended timelines signal authenticity rather than inefficiency.
Urban consumers are unbundling occasion-specific bag ownership from single investment-piece logic. Professional women in Seoul and São Paulo now maintain separate wardrobes for client-facing, travel, and casual contexts, compressing replacement cycles and expanding total category spend. This pattern is most visible in markets where department store consolidation has weakened, forcing brands to build direct relationships through subscription and trade-in programs.
Leather Handbags Market Segmentation
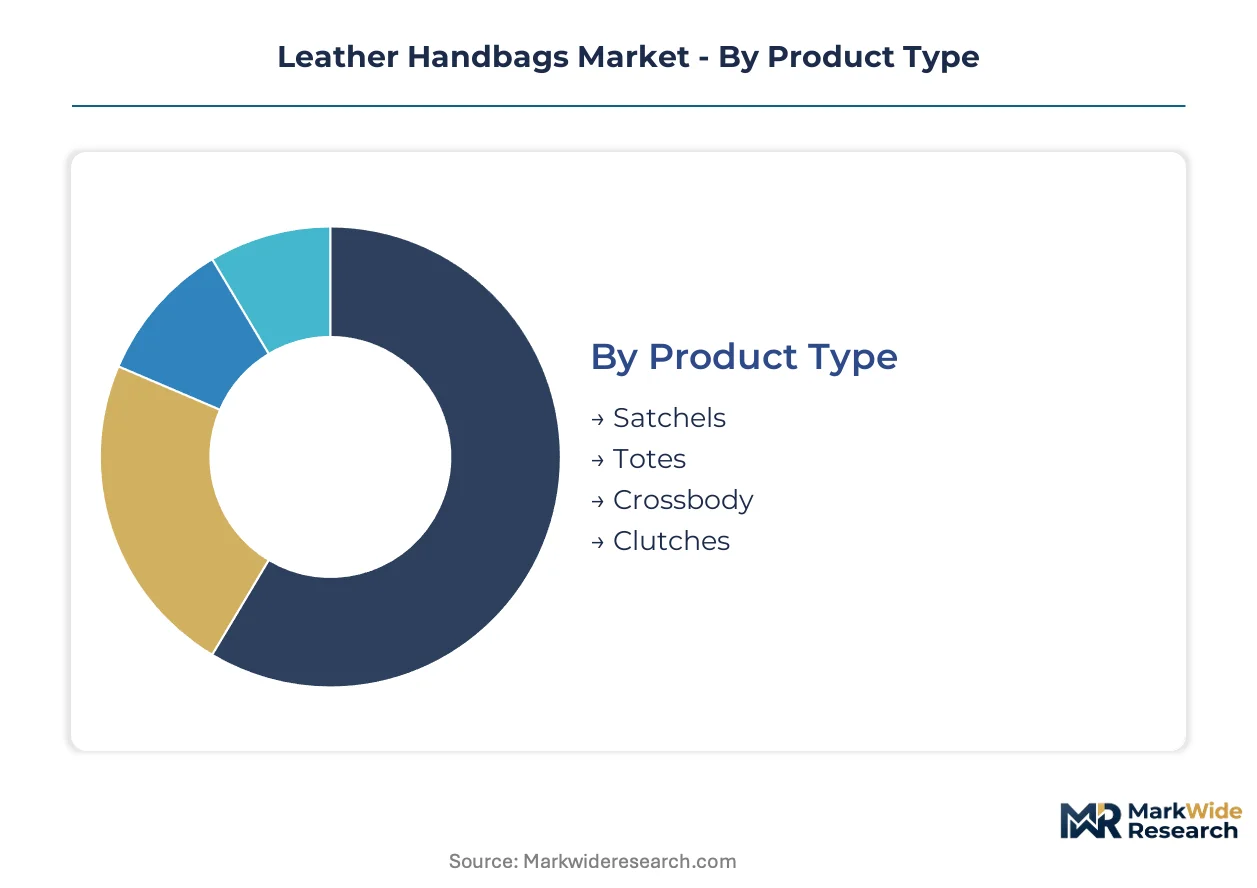
Leather handbag purchasing patterns fragment sharply across usage occasions, buyer demographics, and channel preferences. Manufacturers configure production lines and inventory planning around these divides, as each segment demands distinct material grades, hardware specifications, and margin structures.
Product Type:
Mature silhouettes dominate volume, while emerging configurations reshape commuter behavior and occasion-specific purchasing.
- Satchels:Structured designs with top handles and detachable shoulder straps, traditionally constructed from full-grain leather with reinforced base panels. Demand concentrates among legal and consulting professionals in London and New York, where document capacity and polished aesthetics drive replacement cycles.
- Totes:Open-top rectangular bodies with parallel shoulder straps, engineered for maximum cubic capacity. Professional segments in Shanghai and São Paulo sustain volume leadership, with durability requirements compressing acceptable price elasticity for reinforced stitching and metal feet.
- Crossbody:Compact horizontal or vertical bodies with adjustable long straps, optimized for bicycle and subway transit. Urban commuters in Seoul and Mexico City are expanding multi-unit ownership for hands-free mobility.
- Clutches:Handheld or wrist-strap enclosures without shoulder options, typically evening-oriented with minimal internal organization. Event-driven purchasing in Dubai and Mumbai supports seasonal collection turnover.
Totes retain volume leadership; crossbody holds the steepest expansion curve.
End User:
Customer archetypes span established female professional segments through emerging male and unisex demand pools with divergent design requirements.
- Women:Primary demand pool encompassing professional, travel, and occasion-specific wardrobes. Tier-one city professionals in China and India are expanding multi-bag collections beyond single investment-piece logic.
- Men:Compact messenger derivatives and minimalist totes gaining traction among creative and technology sector workers. Berlin and Tokyo early-adopter segments are normalizing leather accessories as daily carry items.
- Children:Scaled-down silhouettes with reinforced hardware and stain-resistant finishes. Gift purchasing in Milan and Paris supports seasonal volume spikes around academic calendar milestones.
- Unisex:Modular hardware and neutral palettes designed for shared household use. Direct-to-consumer channels in Copenhagen and Amsterdam are capturing this segment through configuration personalization.
Women's segments anchor revenue concentration; unisex represents the most rapid share gain.
Distribution Channel:
Channel economics split between high-touch physical validation and data-rich digital acquisition with divergent margin extraction profiles.
- Online:Owned digital storefronts and marketplace presence capturing behavioral data for personalization. Returns logistics complexity constrains profitability for made-to-order configurations.
- Offline:Flagship and mall-based retail sustaining tactile material validation. Italian heritage houses rely on Florence and Rome locations for brand narrative immersion.
- Boutiques:Curated independent retailers with edited brand rosters and high service intensity. Lisbon and Mexico City independent designers leverage these relationships for geographic expansion without capital-intensive direct retail.
- Department Stores:Consolidated floor space with shared traffic but margin compression through promotional calendars. North American channel contraction is redirecting brand investment toward owned channels.
Department stores retain historical volume share; online channels are climbing the fastest.
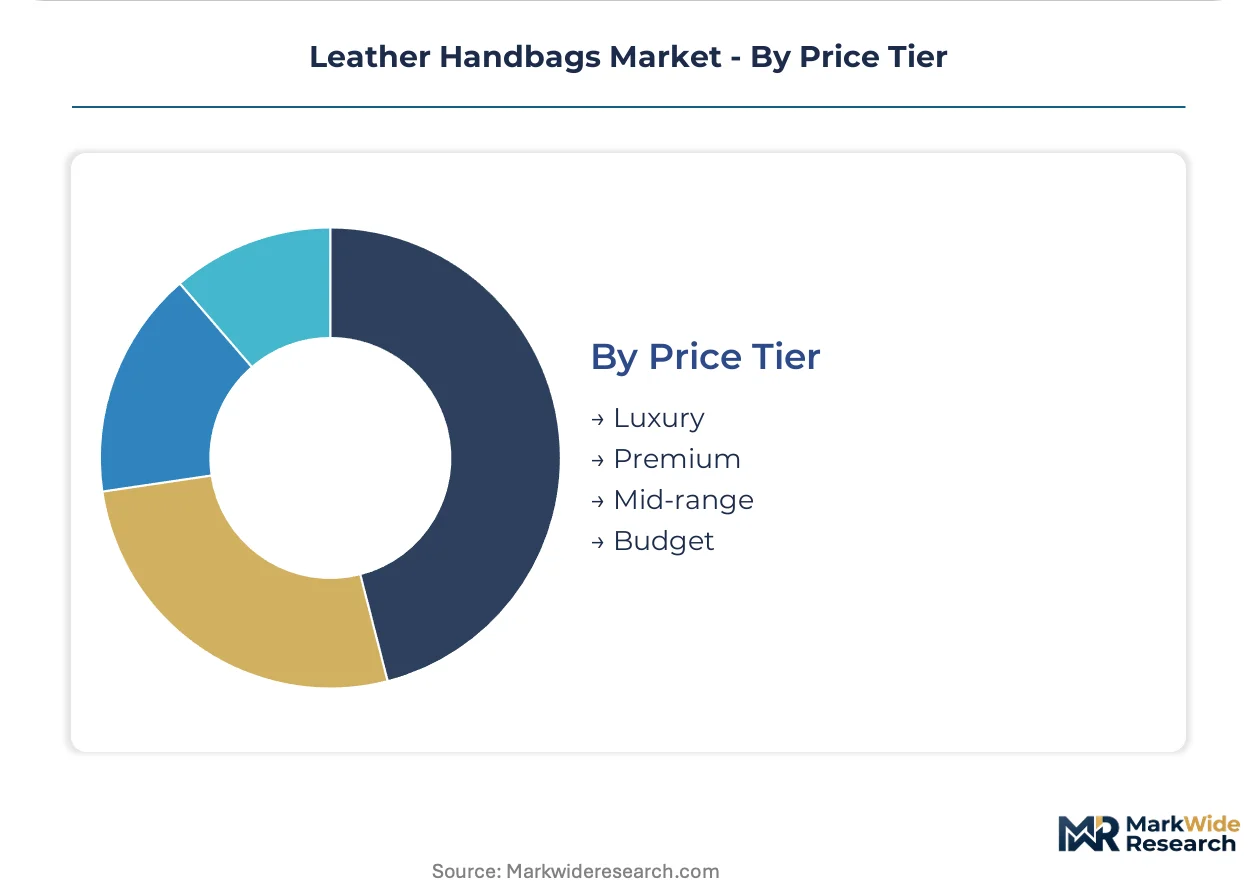
Price Tier:
Margin structures stratify across certification grades, origin claims, and batch-scale constraints with limited upward mobility between tiers.
- Luxury:Heritage-grade vegetable-tanned leather with artisan workshop provenance and limited-batch output. European tanneries in Veneto and Tuscany command price premiums through REACH-certified traceability.
- Premium:Full-grain leather with brand equity support and consistent quality grading. Professional segments in Mumbai and Delhi are expanding purchasing into this tier as domestic heritage competition remains limited.
- Mid-range:Corrected-grain leather with standardized hardware and scaled production. Volume concentration here faces displacement pressure from bio-based synthetic alternatives.
- Budget:Split leather and bonded materials with minimal durability guarantees. Entry-level positioning in Southeast Asian markets sustains unit volume despite compressed margins.
Luxury retains margin leadership; premium shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH Annex XVII restrictions on chromium VI tanning chemistry are redirecting investment flows across European tanneries while Chinese tier-one cities and Indian metros expand their share of leather handbag consumption. The report maps five national markets where regulatory frameworks and urban professional demand intersect.
United States
Urban professional commuters in New York and Chicago are expanding crossbody bag ownership for subway and bicycle transit. FDA import screening protocols for chemical residues extend clearance timelines for Asian-manufactured goods. Detroit-based Shinola anchors domestic heritage positioning through regional manufacturing narratives.
Italy
Florentine and Milanese consumers sustain demand for vegetable-tanned heritage-grade accessories with batch-level traceability. REACH compliance mandates from ECHA are forcing Veneto and Tuscany tanneries to abandon chrome processing entirely. Italian Artisan exemplifies workshop-scale output limited by generational craftsperson availability.
China
Shanghai and Beijing professional women are building multi-bag wardrobes beyond single investment-piece logic. SAMR oversight of product safety labeling shapes domestic market access for European heritage labels. Guangdong manufacturing clusters are absorbing technology transfer from Italian tanning specialists.
India
Mumbai and Delhi professional segments display nascent multi-bag purchasing patterns comparable to China five years prior. BIS certification requirements for leather product safety are elevating quality thresholds for imported materials. Domestic design houses face limited heritage competition in the premium tier.
United Kingdom
London legal and consulting professionals sustain satchel demand through document capacity requirements. UK REACH adoption post-Brexit maintains chemical safety alignment with EU protocols. British heritage positioning competes with Italian and French labels in domestic department store channels.
Leather Handbags Market Competitive Environment
Capability concentration sits with heritage-tier artisans commanding vegetable-tanning expertise; scale advantage sits with North American houses with department store retail footprints. The vendor base splits between Florentine workshop traditions and integrated brand-retail operators. Two strategic archetypes dominate: limited-batch heritage specialists and vertically integrated multi-channel houses. Competitive moves center on direct-to-consumer channel expansion and blockchain-enabled material traceability certification.
Among North American heritage houses, Coach and JW Hulme occupy positions anchored in retail network scale and regional manufacturing narratives respectively. Italian Artisan exemplifies the workshop-scale archetype where batch constraints signal authenticity. Xinzirain represents Asian manufacturing integration serving private-label and branded output. These three entities illustrate the geographic and structural segmentation defining competitive positioning.
| Leading Market Players |
|---|
| Coach |
| Saddleback Leather Co. |
| Italian Artisan |
| Shinola |
| JW Hulme |
| Loipell |
| Fossil |
| Xinzirain |
| Niccoli Bags |
| Others |
Value Chain & Pricing Dynamics
Raw hide input volatility from Brazilian and Argentine herd contraction compresses material availability for tanneries, forcing simultaneous decisions on pricing tier compression and supplier geography diversification. This squeeze propagates through luxury and premium tiers differently, widening spreads between heritage-grade vegetable-tanned output and corrected-grain alternatives.
Pricing Analysis
Geographic price spreads separate Italian heritage-grade output from Asian-manufactured alternatives by factors reflecting certification overhead and batch-scale constraints. Three-tier pricing structure across premium, standard, and economy levels anchors the market, with price differentiation driven by REACH certification status and artisan workshop provenance. Cost compression in the mid-range tier is intensifying because polyurethane and bio-based synthetic alternatives capture entry-level positioning. Budget-tier buyers in Southeast Asian markets exhibit highest price sensitivity, while luxury collectors in Shanghai and Beijing demonstrate lowest elasticity for batch-limited heritage pieces.
Supply Chain Analysis
Contract manufacturing concentration sits with Guangdong and Zhejiang integrated producers serving private-label and branded output for European and North American houses. Raw material flows draw from Italian vegetable-tanning clusters, Brazilian hide processors, and Argentinian wet-blue suppliers. Single-source vulnerability concentrates in Florentine and Cordoban workshop traditions facing generational craftsperson gaps. Distribution runs through department store networks in North America, owned flagship locations in Italian heritage centers, and direct-to-consumer digital storefronts capturing behavioral data for configuration personalization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Master-craftsperson availability in Florentine and Cordoban workshops constrains heritage-tier output expansion, creating asymmetric returns for actors securing artisan pipeline access or bypassing traditional production entirely through digital manufacturing tools.
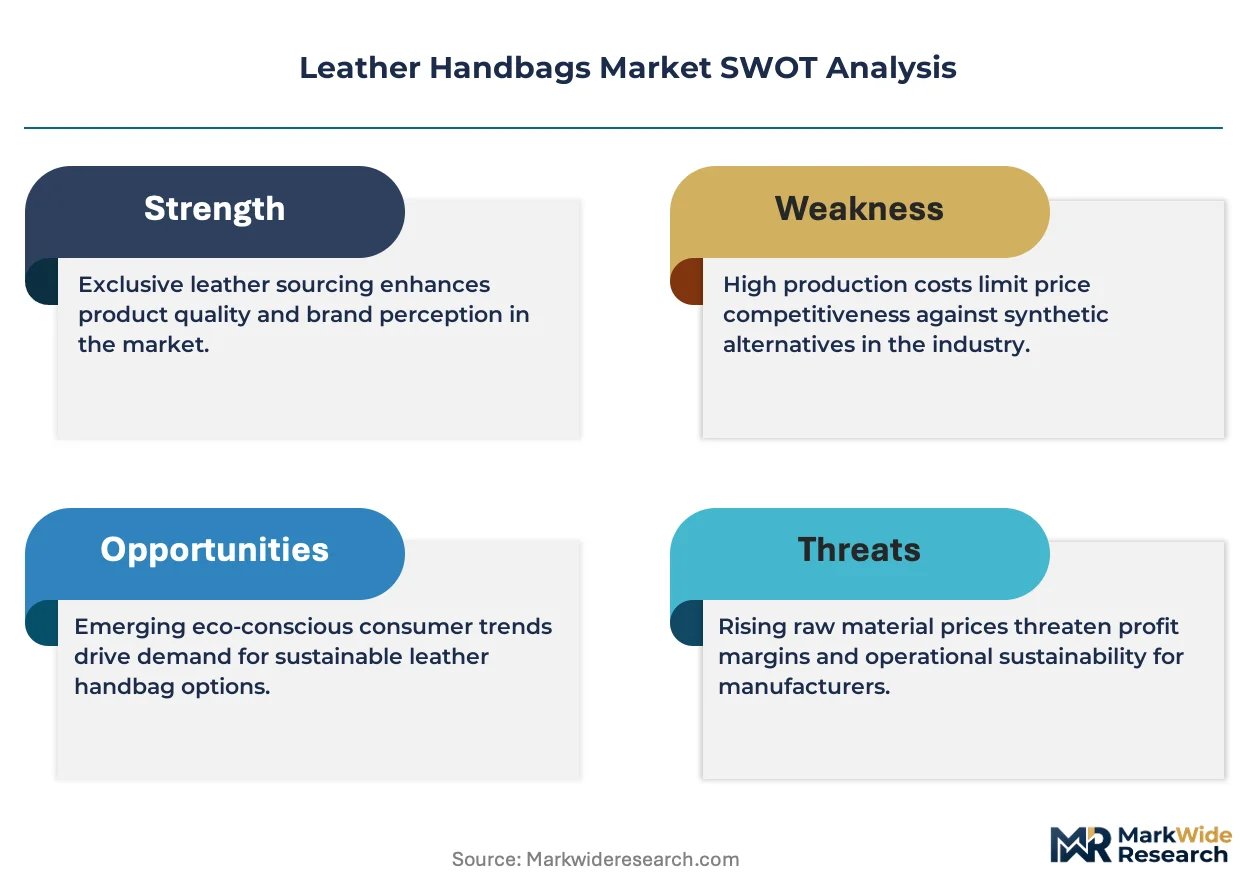
For Market Incumbents: Entrench workshop-scale authenticity positioning through blockchain-enabled batch traceability that synthetic competitors cannot replicate. Deepen backward integration into vegetable-tanning capacity in Veneto and Tuscany before ECHA compliance mandates eliminate chrome-processing alternatives. Prioritize direct-to-consumer channel control to escape department store margin extraction and capture personalization data. For New Entrants and Emerging Players: Establish a beachhead in Indian urban professional segments where multi-bag purchasing patterns resemble China five years prior with limited domestic heritage competition. Target Mumbai and Delhi premium-tier white space through laser-cutting and CNC stitching automation that collapses made-to-order economics. Lead with unisex modular configurations via owned digital storefronts in Copenhagen and Amsterdam where household-sharing behavior concentrates. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors vertically integrated houses with captive tanning capacity and certified traceability infrastructure. Long-term viability hinges on securing artisan skill pipelines or technology-enabled personalization capabilities that escape commodity leather pricing. The signal to watch is REACH Annex XVII enforcement intensity across Italian tannery clusters as inflection indicator for heritage-grade supply constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Vegetable-Tanning Capacity Conversion | ECHA REACH mandates eliminate chrome processing, rewarding early tannery reconversion in Veneto and Tuscany. |
| Blockchain Material Traceability | Distributed ledger verification commands price premiums in European and North American heritage channels. |
| Direct-to-Consumer Channel Expansion | Owned digital storefronts bypass department store margin extraction while capturing behavioral personalization data. |
| Artisan Skill Pipeline Securement | Florentine workshop tradition transfer gaps compress master-craftsperson availability for heritage-grade output. |
| Synthetic Leather Substitution Defense | Bio-based alternatives from industrial chemical suppliers threaten mid-range positioning without brand equity differentiation. |
Study Parameters
A spread of perspectives from tannery operations managers, luxury brand supply chain directors, department store category buyers, and direct-to-consumer platform operators converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade records, ECHA regulatory filings, and SEC disclosures from publicly traded heritage houses. Bottom-up demand modeling across product types and price tiers was triangulated against top-down macroeconomic indicators and urban professional demographic projections.
Demand-supply balance dynamics shaped the analytical framework, with segmentation across product configuration, end-user archetype, distribution channel, and price tier modeled throughout the forecast period. CAGRs were derived from trajectory fitting against historical replacement cycle compression and multi-bag wardrobe expansion patterns. Forecast inputs incorporated REACH compliance cost pass-through assumptions and Chinese tier-one city consumption saturation curves.
Stress conditions across raw hide availability, ECHA enforcement intensity, and synthetic substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about artisan skill pipeline continuity and regulatory chemistry phase-out timelines. Quarterly review of tannery conversion progress, hide futures pricing, and digital channel share metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Middle East Fragrances Market
Consumer Goods
Tobacco Films Market
Consumer Goods
Baby Skincare Market
Consumer Goods
Europe Hair and Skincare Market
Consumer Goods
Powered Lawn Mowers Market
Consumer Goods
Disposable Shower Caps Market
Consumer Goods
Skateboard Ramp Market
Consumer Goods
Europe Pet Food Market
Consumer Goods
Washing Machine Market
Consumer Goods
North America Fire Pits Market
Consumer Goods
Cosmetics Foundation Market
Consumer Goods
Wearable Communicator Market
Consumer Goods
UK Lifestyle Sneakers Market
Consumer Goods
Mexico Small Home Appliances Market
Consumer Goods
Consumer Electronics Market
Consumer Goods
Facial Epilator Market