
 Histidine Market | 2026-2036
Histidine Market Size, Share, and Industry Trends Forecast 2026-2036
Histidine Market Foresight
Market Context
The capital-intensity divergence between fermentation-based specialists and chemical synthesis players is rotating competitive advantage toward bioprocess scale-up capabilities. Ajinomoto Co., Inc. leverages decades of microbial fermentation expertise to anchor supply security for pharmaceutical-grade histidine. Kyowa Hakko Bio Co., Ltd. sustains premium positioning through continuous R&D investment in strain optimization. Evonik Industries AG differentiates via integrated downstream processing that controls impurity profiles for injectable-grade applications.
Technical Definition and Segments
Histidine is an essential alpha-amino acid with an imidazole side chain, functioning as a metal chelator, pH buffer, and precursor for histamine biosynthesis in mammalian physiology. Industrial production relies primarily on microbial fermentation using Corynebacterium glutamicum or Escherichia coli strains, yielding L-histidine with purity thresholds exceeding 98.5% for pharmaceutical applications. Pharmaceutical-grade histidine commands the deepest margin pool due to stringent endotoxin and heavy-metal specifications for parenteral formulations. Powder form dominates volume throughput across nutraceutical and animal nutrition channels, while liquid formulations are gaining traction in automated bioprocessing workflows. Food-grade histidine remains mature, with price competition intensifying among Chinese fermentation houses.
Regulatory Framework
The US FDA and EMA enforce divergent pharmacopeial standards for amino acid excipients, with USP-NF Chapter 1046 and Ph. Eur. 2.4.24 specifying distinct impurity limits that fragment qualification pathways. China's NMPA aligns with ICH Q3D guidelines for elemental impurities, accelerating local pharmaceutical-grade certification timelines. Japan's PMDA maintains additional bioburden testing requirements that favor suppliers with dedicated clean-room finishing capacity. Stakeholders must monitor evolving endotoxin testing harmonization between USP 85 and Ph. Eur. 2.6.14, as divergence threatens multi-regional filing strategies for parenteral nutrition products.
Market Dynamics
Fermentation process intensification is compressing unit economics for pharmaceutical-grade histidine, forcing chemical synthesis players to either retrofit bioprocess capacity or retreat to lower-margin feed-grade segments.
Growth Catalysts
- Injectable biologics expansion:Parenteral nutrition formulations and monoclonal antibody buffers are consuming pharmaceutical-grade histidine at accelerating rates, tightening spot availability for qualified suppliers.
- China's NMPA alignment with ICH Q3D:Streamlined elemental impurity testing protocols are compressing certification timelines for domestic fermentation houses targeting export markets.
- Continuous fermentation systems:Automated bioprocessing workflows are supplanting batch operations, improving titer consistency and reducing downstream purification burden.
Market Restraints
- Corn syrup price volatility:Feedstock costs for Corynebacterium glutamicum fermentation swing with drought cycles in the US Corn Belt, compressing margin predictability for non-integrated producers.
- Supply concentration in Shandong Province:Three Chinese fermentation clusters control over half of exportable pharmaceutical-grade capacity, creating single-point vulnerability for multi-regional formulators.
- Endotoxin specification divergence:USP 85 and Ph. Eur. 2.6.14 testing methodologies produce discordant results, forcing parallel qualification runs that extend batch release timelines.
Strategic Opportunities
- Cell culture media specialization:Serum-free and chemically defined media formulations are demanding ultra-low endotoxin histidine grades that command 40-60% premiums over standard pharmaceutical specifications.
- India's PLI scheme for active pharmaceutical ingredients:Production-linked incentives are attracting fermentation investment for amino acid backward integration, creating alternative supply nodes to Chinese concentration.
- AI-driven strain optimization:Machine learning platforms are converging with CRISPR editing to accelerate metabolic pathway engineering, compressing R&D cycles for yield-enhanced Corynebacterium variants.
Industry Challenges
- Clean-room finishing capacity scarcity:Pharmaceutical-grade packaging requires ISO 7 or better environments, yet qualified facility expansion demands 18-24 month construction and validation cycles.
- Multi-regional pharmacopeial compliance:Simultaneous adherence to USP-NF, Ph. Eur., and JP specifications requires redundant analytical methods and documentation systems that strain quality organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Histidine Market |
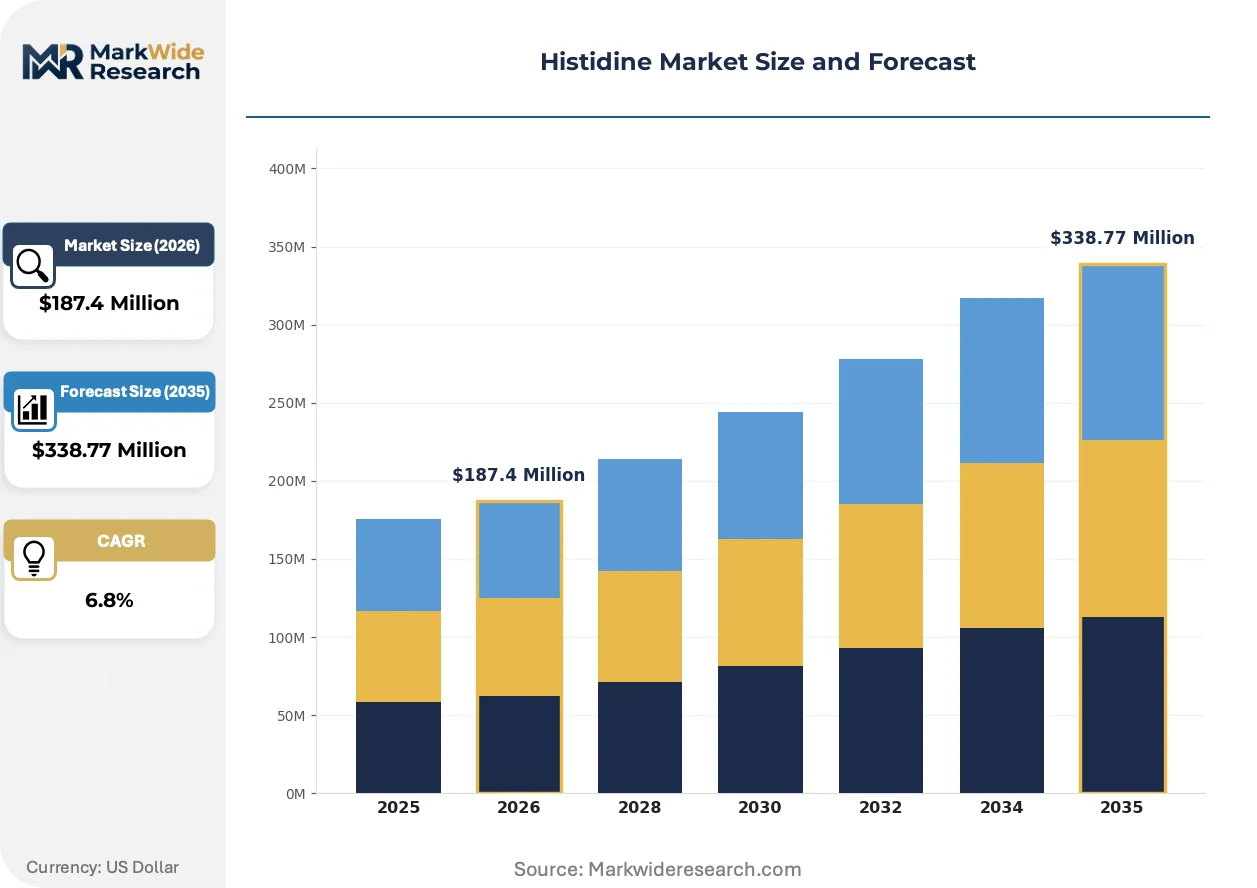
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Feed Grade Application: Nutraceuticals, Pharmaceuticals, Food Additives, Animal Nutrition End User: Food Industry, Pharmaceutical Companies, Academic Institutions, Research Organizations Form: Powder, Tablet, Capsule, Liquid |
| Companies Covered | Ajinomoto Co., Inc., Kyowa Hakko Bio Co., Ltd., Shine Star (Hubei) Biological Engineering Co., Ltd., Evonik Industries AG, Merck KGaA, Huaheng Biological, CJ CheilJedang Corp., Daesang Corporation, Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Histidine Market Shifts & Advancements
Bioprocess digitization and modular manufacturing architectures are restructuring how histidine capacity scales, enabling smaller-footprint production nodes closer to pharmaceutical demand clusters.
CRISPR-Cas9 metabolic engineering is supplanting traditional mutagenesis for Corynebacterium glutamicum strain development. Contract development organizations are adopting genome-edited starter strains within 12-18 month project timelines. This precision approach is compressing the yield gap between established Japanese fermentation houses and emerging Chinese competitors.
The EU's CSRD sustainability disclosure requirements are mandating Scope 3 emissions tracking for amino acid excipients used in pharmaceutical formulations. Large molecule manufacturers are now screening suppliers on carbon intensity metrics alongside traditional quality specifications. German and Swiss formulators are prioritizing fermentation partners with verified renewable energy procurement.
Long-term offtake contracting is displacing spot market purchasing for pharmaceutical-grade histidine. Biologics manufacturers are locking in 3-5 year supply agreements with qualified fermentation houses to secure buffer inventory against geopolitical disruption. This preference shift is most visible among US and European CDMOs serving parenteral nutrition and vaccine adjuvant markets.
Histidine Market Segmentation
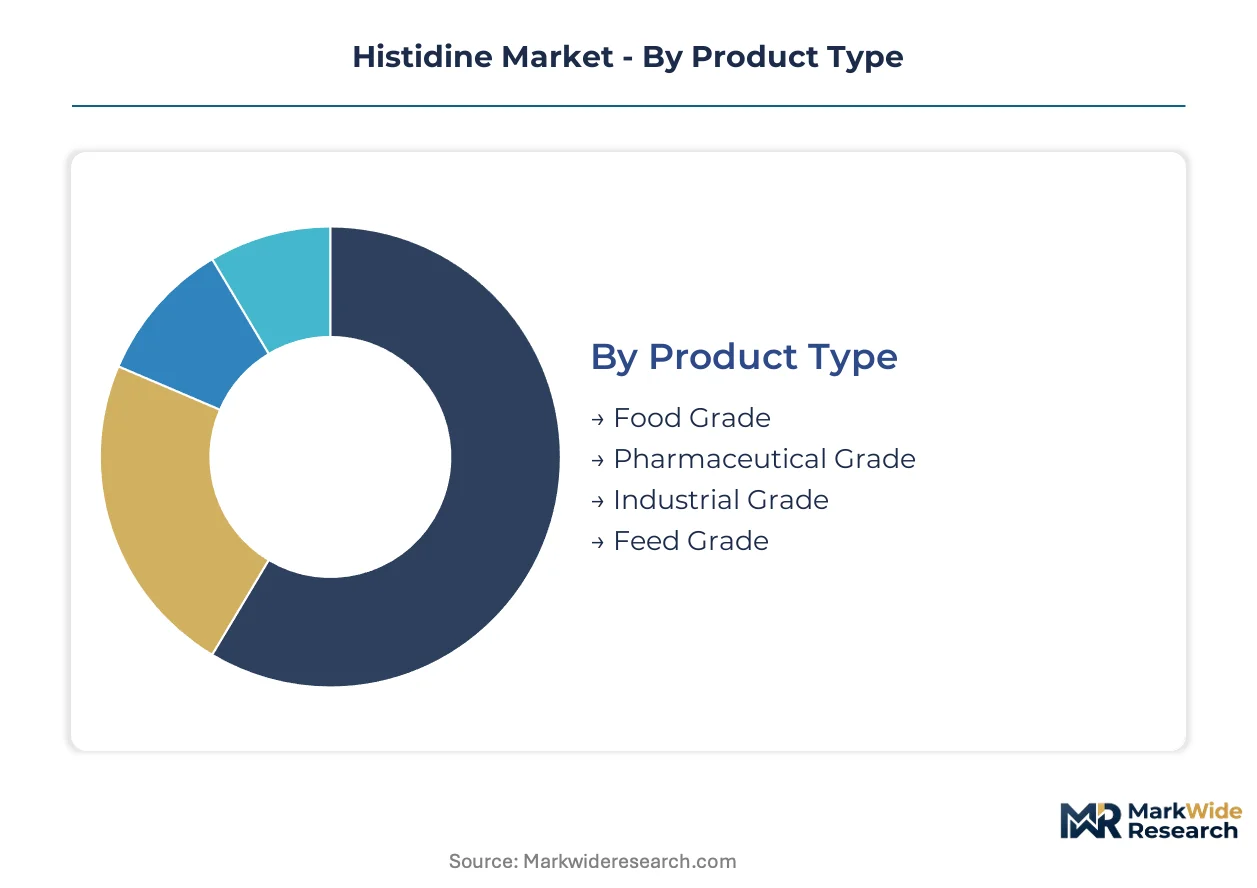
Histidine market segmentation reveals how purity specifications and delivery formats fragment procurement patterns across pharmaceutical, nutritional, and industrial channels. Understanding these divides exposes where margin pools concentrate and where capacity investments yield asymmetric returns.
Product Type:
Margin pools concentrate in pharmaceutical-grade certification, where endotoxin and heavy-metal specifications create steep barriers to entry that protect pricing power.
- Pharmaceutical Grade:Purity thresholds exceeding 98.5% with stringent USP-NF Chapter 1046 and Ph. Eur. 2.4.24 compliance requirements. Demand concentrates in parenteral nutrition formulations and monoclonal antibody buffers, where injectable specifications command substantial premiums over standard grades.
- Food Grade:Lower purity thresholds suitable for protein fortification and flavor modulation applications. Chinese fermentation houses dominate volume production, with price competition intensifying as domestic capacity scales in Shandong Province.
- Industrial Grade:Technical specifications for metal chelation and polymer synthesis applications.
- Feed Grade:Cost-optimized formulations for livestock nutrition, where corn syrup feedstock volatility compresses margin predictability for non-integrated producers.
The dominant share belongs to pharmaceutical grade, while food grade is closing the gap fastest as Chinese fermentation capacity expands export volumes.
Application:
Cost tier stratification separates premium parenteral formulations from commoditized feed additives, with regulatory burden determining profitability thresholds.
- Pharmaceuticals:Parenteral nutrition and biologic buffer applications consume qualified supply at accelerating rates. US and European CDMOs are locking in long-term offtake agreements to secure inventory against supply concentration risks in Shandong Province.
- Nutraceuticals:Dietary supplement formulations targeting athletic recovery and cognitive function. Powder form dominates volume throughput, with direct-to-consumer brands driving SKU proliferation across capsule and tablet formats.
- Animal Nutrition:Swine and poultry feed formulations where histidine supplementation optimizes growth performance.
- Food Additives:Flavor enhancement and protein fortification in processed foods, where clean-label trends are reshaping procurement specifications toward natural-source fermentation credentials.
Pharmaceuticals capture the steepest expansion trajectory, while nutraceuticals are gaining share fastest as wellness consumerization deepens.
End User:
Customer type determines contract structure, with pharmaceutical companies demanding multi-year supply agreements while research organizations sustain spot-market liquidity.
- Pharmaceutical Companies:Integrated biologics manufacturers and CDMOs serving parenteral nutrition markets. Procurement is shifting toward 3-5 year offtake contracts with qualified fermentation houses to buffer against geopolitical disruption.
- Food Industry:Processed food manufacturers and ingredient suppliers. Volume concentration in China is driving procurement localization, with domestic formulators prioritizing nearby fermentation capacity to reduce logistics exposure.
- Research Organizations:Contract research organizations and biotechnology startups.
- Academic Institutions:University laboratories and government research facilities.
Pharmaceutical companies anchor demand volume, while research organizations are expanding fastest as CRISPR-driven strain development accelerates.
Form:
Volume scale separates powder commodity flows from specialized liquid and solid-dose formats requiring additional processing investment.
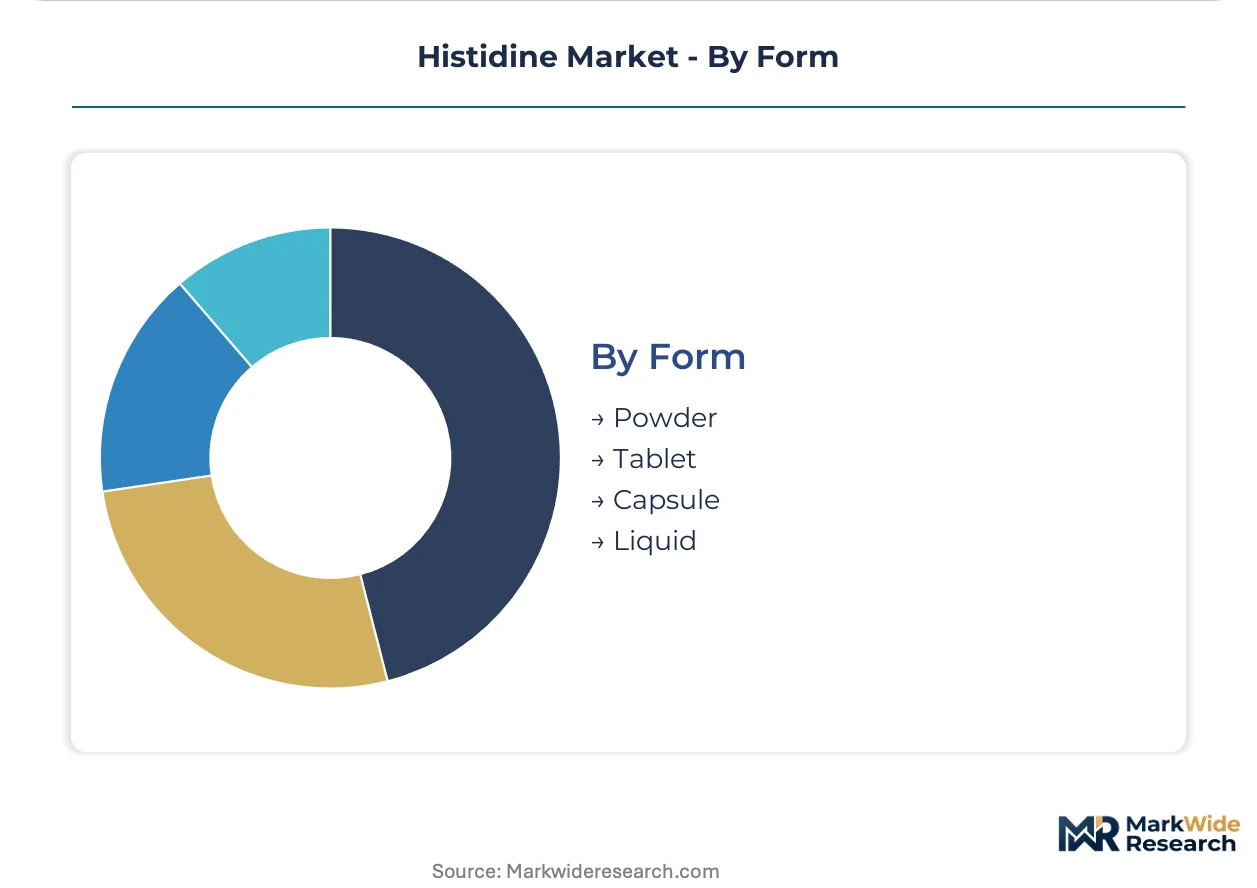
- Powder:Bulk crystalline form dominating nutraceutical and animal nutrition channels. Automated bioprocessing workflows are supplanting batch operations, improving titer consistency and reducing downstream purification burden for fermentation houses.
- Liquid:Aqueous solutions gaining traction in automated bioprocessing workflows and cell culture media preparation. Serum-free and chemically defined media formulations are demanding ultra-low endotoxin grades that command substantial premiums over standard specifications.
- Capsule:Pre-measured solid-dose formats for nutraceutical retail channels.
- Tablet:Compressed solid-dose formats for dietary supplement applications.
Powder maintains volume leadership, while liquid is climbing the fastest as bioprocess automation reshapes pharmaceutical manufacturing workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese fermentation houses command 40-60% premiums over Chinese pharmaceutical-grade output, while Shandong Province suppliers dominate volume flows into Southeast Asian feed markets. This pricing-power asymmetry reflects divergent regulatory qualification burdens and clean-room finishing capabilities across East Asian supply nodes.
United States
FDA enforcement of USP-NF Chapter 1046 for parenteral nutrition excipients drives demand for ultra-low endotoxin histidine grades. The Inflation Reduction Act's domestic manufacturing incentives are accelerating fermentation capacity investment in the Midwest Corn Belt. Indianapolis and Raleigh-Durham clusters host CDMOs locking in 3-5 year offtake agreements to secure buffer inventory.
China
NMPA alignment with ICH Q3D guidelines is compressing certification timelines for Shandong Province fermentation houses targeting export markets. The dual carbon goals policy is mandating renewable energy procurement for amino acid manufacturers in the Yangtze River Delta. Qingdao and Weifang industrial zones concentrate over half of exportable pharmaceutical-grade capacity.
Germany
EMA pharmacopeial standards under Ph. Eur. 2.4.24 fragment qualification pathways for amino acid excipients entering European parenteral formulations. The EU CSRD sustainability disclosure requirements are mandating Scope 3 emissions tracking for histidine used in biologic buffers. Frankfurt and Ludwigshafen chemical clusters prioritize fermentation partners with verified renewable energy contracts.
India
The PLI scheme for active pharmaceutical ingredients is attracting fermentation investment for amino acid backward integration in Maharashtra and Gujarat. CDSCO streamlined approval pathways for ICH-compliant excipients are accelerating import substitution for pharmaceutical-grade histidine. Hyderabad and Mumbai industrial corridors are emerging as alternative supply nodes to Chinese concentration.
Japan
PMDA maintains additional bioburden testing requirements that favor suppliers with dedicated clean-room finishing capacity for injectable-grade applications. METI industrial policy supports strain optimization R&D in the Kanto region's biotechnology corridor. Tokyo and Osaka pharmaceutical clusters sustain premium positioning through decades of microbial fermentation expertise.
Histidine Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with Japanese fermentation houses commanding premium positioning and Chinese suppliers driving volume commoditization. The vendor base fragments across three tiers: integrated bioprocess specialists with decades of strain optimization heritage, mid-scale fermentation houses scaling pharmaceutical-grade certification, and commodity producers retreating to feed-grade segments. Dominant competitive moves include long-term offtake contracting with biologics manufacturers and AI-driven metabolic pathway engineering to compress yield gaps.
Within the integrated specialist tier, Ajinomoto Co., Inc. and Kyowa Hakko Bio Co., Ltd. exemplify decades-long microbial fermentation expertise that anchors supply security for pharmaceutical-grade applications. Evonik Industries AG occupies a position emphasizing integrated downstream processing capabilities. Among Chinese fermentation houses, Shine Star (Hubei) Biological Engineering Co., Ltd. represents the mid-scale archetype scaling pharmaceutical-grade certification for export markets.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Kyowa Hakko Bio Co., Ltd. |
| Shine Star (Hubei) Biological Engineering Co., Ltd. |
| Evonik Industries AG |
| Merck KGaA |
| Huaheng Biological |
| CJ CheilJedang Corp. |
| Daesang Corporation |
| Thermo Fisher Scientific Inc. |
| Others |
Supply & Pricing Matrix
Fermentation process intensification replacing legacy chemical synthesis routes is redrawing supply geography toward Shandong Province fermentation clusters while compressing margin structures for non-integrated producers. This substitution dynamic simultaneously concentrates pharmaceutical-grade capacity in Chinese industrial zones and erodes pricing power for European chemical synthesis players retreating to feed-grade segments.
Pricing Analysis
The customization-premium spread between standard pharmaceutical-grade and ultra-low endotoxin cell culture specifications reaches 40-60% above baseline, with contract-based long-term offtake agreements dominating procurement for biologics manufacturers. Price differentiation hinges on endotoxin certification tier and clean-room finishing capability, with Japanese fermentation houses commanding substantial premiums over Chinese output. Cost compression in food-grade segments is intensifying because Shandong Province capacity expansion outpaces demand absorption. Feed-grade buyers exhibit highest price sensitivity, while cell culture media specialists demonstrate inelastic demand for qualified ultra-low endotoxin grades.
Supply Chain Analysis
Inbound logistics costs from Qingdao and Weifang industrial zones to European pharmaceutical clusters fluctuate with container availability on Asia-Europe trade lanes, creating margin volatility for non-integrated distributors. Supply concentrates in China, Japan, and Germany, with raw material dependencies on corn syrup feedstocks, specialized Corynebacterium glutamicum starter strains, and pharmaceutical-grade packaging materials. Single-source vulnerability in Shandong Province fermentation capacity creates structural risk for multi-regional formulators. Distribution runs through qualified fermentation houses to CDMOs and integrated biologics manufacturers, with direct pharmaceutical procurement displacing spot-market intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The histidine market operates as a substitution defense against synthetic biology alternatives and recombinant protein production methods that could displace fermentation-derived amino acids in cell culture applications. Incumbents must navigate this substitute threat while consolidating qualification advantages.
For Market Incumbents: Fortify pharmaceutical-grade certification moats by investing in ISO 7 clean-room finishing capacity and securing 3-5 year offtake agreements with US and European CDMOs. Strain optimization R&D in Corynebacterium glutamicum metabolic pathways anchors yield advantages against emerging Chinese competitors scaling pharmaceutical-grade output.
For New Entrants and Emerging Players: Lead with India's PLI scheme incentives for amino acid backward integration in Maharashtra and Gujarat industrial corridors, where CDSCO streamlined approval pathways create penetrable regulatory entry. Target cell culture media specialization as the most accessible premium segment, leveraging ultra-low endotoxin demand from serum-free formulation trends.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated fermentation specialists with established strain heritage and multi-regional pharmacopeial qualification. Long-term viability across the projection horizon rests on carbon intensity verification under EU CSRD disclosure requirements. Monitor NMPA export certification timelines for Shandong Province fermentation houses as inflection indicator for Chinese supply expansion pace.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Locks in 3-5 year offtake contracts with US CDMOs to buffer Shandong concentration risk. |
| Backward Integration | Captures corn syrup feedstock supply in US Midwest Corn Belt to stabilize margin predictability. |
| Green Manufacturing Transition | Secures renewable energy procurement contracts to satisfy EU CSRD Scope 3 disclosure mandates. |
| Capacity Expansion | Adds ISO 7 clean-room finishing capability to capture cell culture media premium tier demand. |
| Joint Venture | Combines Japanese strain optimization expertise with Indian PLI scheme manufacturing incentives. |
Research Methodology
Desk research of fermentation technology patents, NMPA and FDA excipient guidance documents, and EU CSRD sustainability disclosure frameworks preceded structured interviews with pharmaceutical procurement directors, amino acid plant managers, CDMO supply chain leads, and regulatory affairs specialists at fermentation houses. Secondary validation drew from customs trade data, SEC filings of listed amino acid manufacturers, and ICH Q3D implementation status reports. Bottom-up capacity modeling and top-down demand triangulation from parenteral nutrition formulation trends converged on segment-level outputs.
Variance decomposition across pharmaceutical grade, food grade, and feed grade tiers anchored the analytical framework, with additional segmentation by powder versus liquid delivery format and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion schedules throughout the forecast period. Strain yield improvement curves and clean-room facility construction timelines served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in US FDA, EMA, and NMPA pharmacopeial standards; material policy shifts in endotoxin testing harmonization or elemental impurity thresholds would require re-modeling. Corn syrup price volatility, geopolitical disruption to Shandong Province export flows, and synthetic biology substitution advances constitute specific risk factors that could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Copaiba Essential Oil Market
Extracts
Nootkatone Market
Extracts
White Willow Bark Extract Market
Extracts
Plum Extract Market
Extracts
Asia-Pacific Mineral Turpentine Market
Extracts
Asia-Pacific Spirulina Extract Market
Extracts
Natural Rosemarine Extract Market
Extracts
Bidens Pilosa Extract Market
Extracts
Functional Extract Market
Extracts
Helichrysum Oil Market
Extracts
Peppermint Leaf Powder Market
Extracts
Belladonna Market
Extracts
Cosmetic Grade Portulaca Oleracea Extract Market
Extracts
Flower Extract Market
Extracts
Sandalwood Oil Market
Extracts
Ovalbumin Powder Market