
 Menswear Market | 2026-2036
Menswear Market Size, Share, and Industry Trends Forecast 2026-2036
Menswear Market Intelligence
Market Context
Subscription-based wardrobe services and membership-driven replenishment models is consolidating around repeat-purchase menswear, shifting unit economics from one-time transactions to lifetime value calculations. Everlane leverages transparent pricing and direct-to-consumer channels to sustain margin control across its basics assortment. Patagonia anchors its positioning through repair-and-resale programs that extend product lifecycles and deepen customer retention. Buck Mason differentiates via vertical manufacturing in Los Angeles, competing on speed-to-market against offshore-dependent rivals.
Technical Definition and Segment Structure
Menswear encompasses all garments engineered for male body proportions, constructed through processes including pattern grading, fused or canvassed interlining, and seam sealing for performance variants, serving functions from thermal regulation to professional identity signaling. Casual Wear leads volume contribution as workplace norms relax, while Activewear captures the fastest expansion due to fiber innovations in moisture-wicking polyester blends and four-way stretch constructions. Cotton dominates Fabric Type demand for skin-contact layers, though wool commands premium positioning in formal outerwear where Professionals drive replacement cycles.
Regulatory Environment and Outlook
REACH governs chemical inputs across European textile supply chains, while the EU Green Deal mandates fiber traceability disclosures that reshape sourcing decisions for brands selling into member states. In the United States, FTC textile labeling rules enforce fiber content accuracy, and California's SB 657 transparency requirements extend accountability to tier-two suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks that will determine which distribution channels bear end-of-life collection costs.
Market Dynamics
Hybrid work normalization is collapsing the formal-casual boundary in professional wardrobes, forcing brands to engineer garments that signal competence across video calls and in-person meetings without category-specific inventory duplication.
Growth Catalysts
- EU Green Deal fiber traceability mandates:Disclosure requirements are accelerating investment in blockchain-enabled supply chain mapping, creating competitive advantage for early compliant brands in European markets.
- Moisture-wicking polyester blend innovation:Four-way stretch constructions in Activewear are capturing replacement cycles from traditional Casual Wear as consumers prioritize comfort-to-professionalism ratios.
- China domestic brand concentration:Localized design capabilities and compressed lead times are shifting volume capture from Western labels to domestic menswear producers in the world's largest demand pool.
Market Restraints
- Cotton input cost volatility:Weather-driven supply fluctuations and speculative commodity positioning are compressing margin predictability for basics-dependent assortments.
- REACH chemical disclosure friction:European textile finishing processes face compliance timeline uncertainty as ECHA expands restricted substance lists faster than reformulation cycles.
- Technical limitation in biodegradable synthetics:Performance degradation in moisture management and durability remains unresolved for brands pursuing full material transition.
Strategic Opportunities
- India underpenetrated premium tier:Rising disposable income concentration in Mumbai, Delhi, and Bangalore metros is creating whitespace for positioned international entrants before domestic competitors consolidate.
- Repair-and-resale channel innovation:Product lifecycle extension services are unlocking recurring revenue streams and customer data depth unavailable through traditional wholesale.
- Dual carbon goals regulatory tailwind:China's MEE enforcement is creating preferential market access for brands with verified low-carbon production credentials against non-compliant rivals.
Industry Challenges
- Pattern engineering talent scarcity:Hybrid garment requirements demand computational design skills rare in traditional menswear technical teams, extending development timelines.
- California SB 657 tier-two supplier accountability:Transparency documentation requirements are exposing sourcing complexity that brands cannot resolve without supply chain restructuring investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Menswear Market |
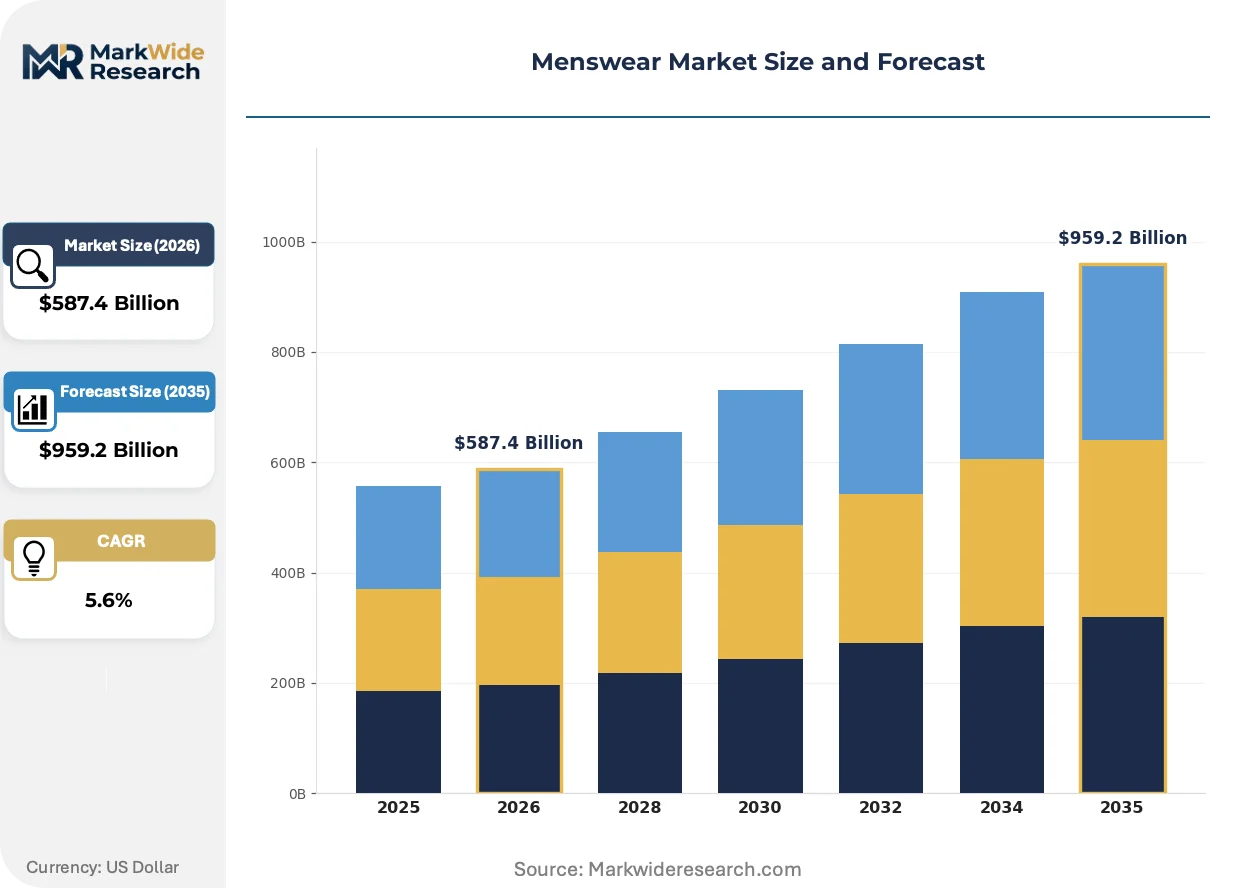
| Market Size in 2026 | $587.4 Billion |
| Market Size in 2035 | $959.2 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Formal Wear, Casual Wear, Sportswear, Activewear Fabric Type: Cotton, Linen, Wool, Polyester Customer Type: Millennials, Gen X, Baby Boomers, Professionals Distribution Channel: Online Retail, Department Stores, Specialty Shops, Outlets |
| Companies Covered | Everlane, Banana Republic, Mack Weldon, Madewell, COS, Bonobos, Patagonia, UNTUCKit, Buck Mason, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Menswear Market Strategic Shifts & Innovations
Digital fabrication and biomaterial science are converging to collapse the traditional seasonal development calendar, compressing the gap between trend identification and commercial availability from months to weeks.
AI-assisted pattern grading is rewriting size inclusivity economics in menswear. Machine learning algorithms now generate proportion-adjusted patterns across extended size ranges from single base designs, enabling small-batch profitability. Direct-to-consumer brands with narrow initial assortments are adopting this fastest, compressing the cost advantage of scale-dependent competitors.
REACH chemical restriction expansion is forcing reformulation of durable water-repellent finishes across European-bound production. Fluorocarbon alternatives face performance validation gaps that delay product launches. Outdoor and performance-oriented sub-segments bear the highest compliance burden, accelerating relocation of finishing operations to jurisdictions with transitional enforcement timelines.
Subscription-based wardrobe curation is displacing traditional replenishment purchasing among urban professionals aged 25-40. Stylists algorithmically matched to preference profiles are replacing self-directed browsing, concentrating customer data with platform operators. This pattern is most visible in London, New York, and Tokyo, where closet space constraints and mobility preferences amplify rental and rotation model appeal.
Menswear Market Segmentation
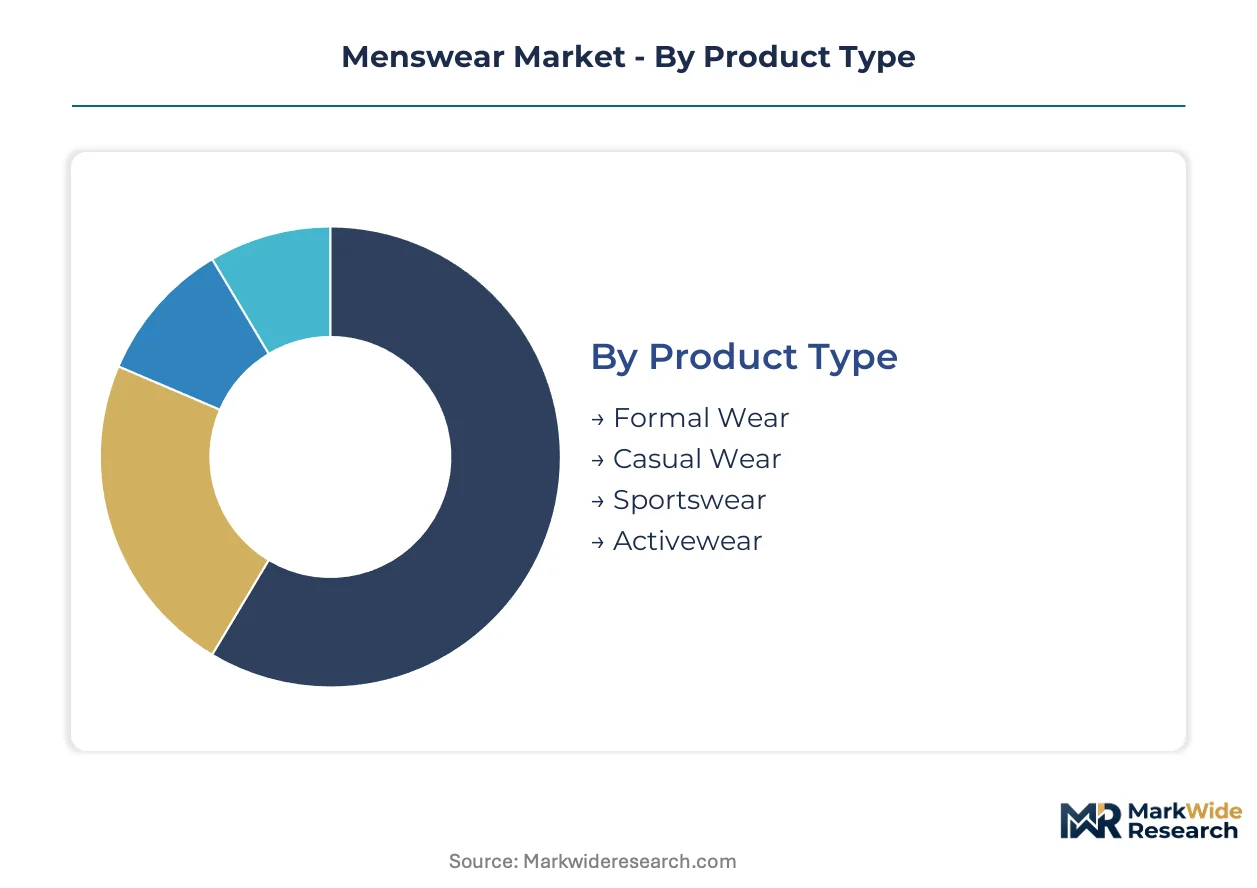
Segmentation in menswear separates volume concentration from margin extraction. Understanding where replacement cycles accelerate versus where premium pricing holds reveals which product-fabric-customer combinations deserve capital allocation.
Product Type:
Upgrade cycles vary dramatically across occasion-based categories, with workplace norms rewriting replacement frequency for garments once purchased seasonally.
- Casual Wear:Garments engineered for relaxed professional and social contexts dominate unit volume as hybrid dress codes normalize. Demand concentrates in China and the United States where domestic brands capture share through localized design and compressed lead times.
- Activewear:Four-way stretch constructions and moisture-wicking polyester blends define this fastest-expanding category. Replacement cycles accelerate among urban professionals aged 25-40 who prioritize comfort-to-professionalism ratios in wardrobes serving both gym and video-call contexts.
- Formal Wear:Canvassed and fused interlining techniques sustain premium positioning in wedding and ceremonial end-uses. Wool-dominant fabric specifications face shrinking replacement frequency as workplace formality declines.
- Sportswear:Performance-oriented constructions with seam-sealed variants serve athletic-specific demand. Technical specifications lag Activewear in fiber innovation, limiting expansion velocity.
Casual Wear sits at the top of the volume ranking, with Activewear climbing the fastest.
Fabric Type:
Cost tier separation in raw material inputs determines margin architecture across branded and private-label assortments.
- Cotton:Skin-contact layer dominance in basics and casual shirts sustains volume leadership. Weather-driven supply fluctuations and speculative commodity positioning compress margin predictability for dependent brands.
- Wool:Premium outerwear positioning commands price multiples in formal and cold-weather categories. REACH chemical disclosure requirements on finishing processes add compliance friction for European-bound production.
- Polyester:Moisture-wicking blend innovations drive Activewear performance specifications. Technical limitation in biodegradable variants constrains sustainability transitions without durability trade-offs.
- Linen:Breathability specifications serve warm-climate and resort-season demand. Seasonal concentration and wrinkle-prone handling limit year-round adoption.
Cotton commands the highest absolute volume, with polyester gaining share fastest through performance blend adoption.
Customer Type:
Generational transition in purchasing authority shifts channel preference and price elasticity simultaneously.
- Millennials:Subscription-based wardrobe curation and algorithmic styling displace traditional replenishment. Concentration in London, New York, and Tokyo amplifies rental and rotation model appeal amid closet space constraints.
- Professionals:Hybrid work requirements demand garments signaling competence across video and in-person contexts. Replacement cycles compress as single garments must serve previously distinct occasion categories.
- Gen X:Established brand loyalty and higher average transaction values sustain department store and specialty shop traffic. Slower adoption of direct-to-consumer channels preserves traditional retail dependence.
- Baby Boomers:Size-adjusted pattern requirements and repair-oriented consumption extend product lifecycles. Demographic contraction limits volume contribution despite higher per-unit spending.
Millennials drive the steepest channel shift, with Professionals representing the most concentrated margin pool.
Distribution Channel:
Supply concentration in direct-to-consumer infrastructure separates inventory-turn velocity from customer data depth.
- Online Retail:Transparent pricing and direct customer relationships sustain margin control for vertically integrated brands. AI-assisted pattern grading enables small-batch profitability across extended size ranges.
- Department Stores:Foot traffic dependence and promotional calendar compression challenge full-price realization. Tier-two supplier accountability requirements under California SB 657 expose sourcing complexity.
- Specialty Shops:Curation authority and localized assortment depth defend position against platform consolidation. Higher operating costs limit geographic scalability.
- Outlets:Off-price inventory clearance sustains brand accessibility without full-price dilution. Margin extraction depends on manufacturing cost discipline in core collection production.
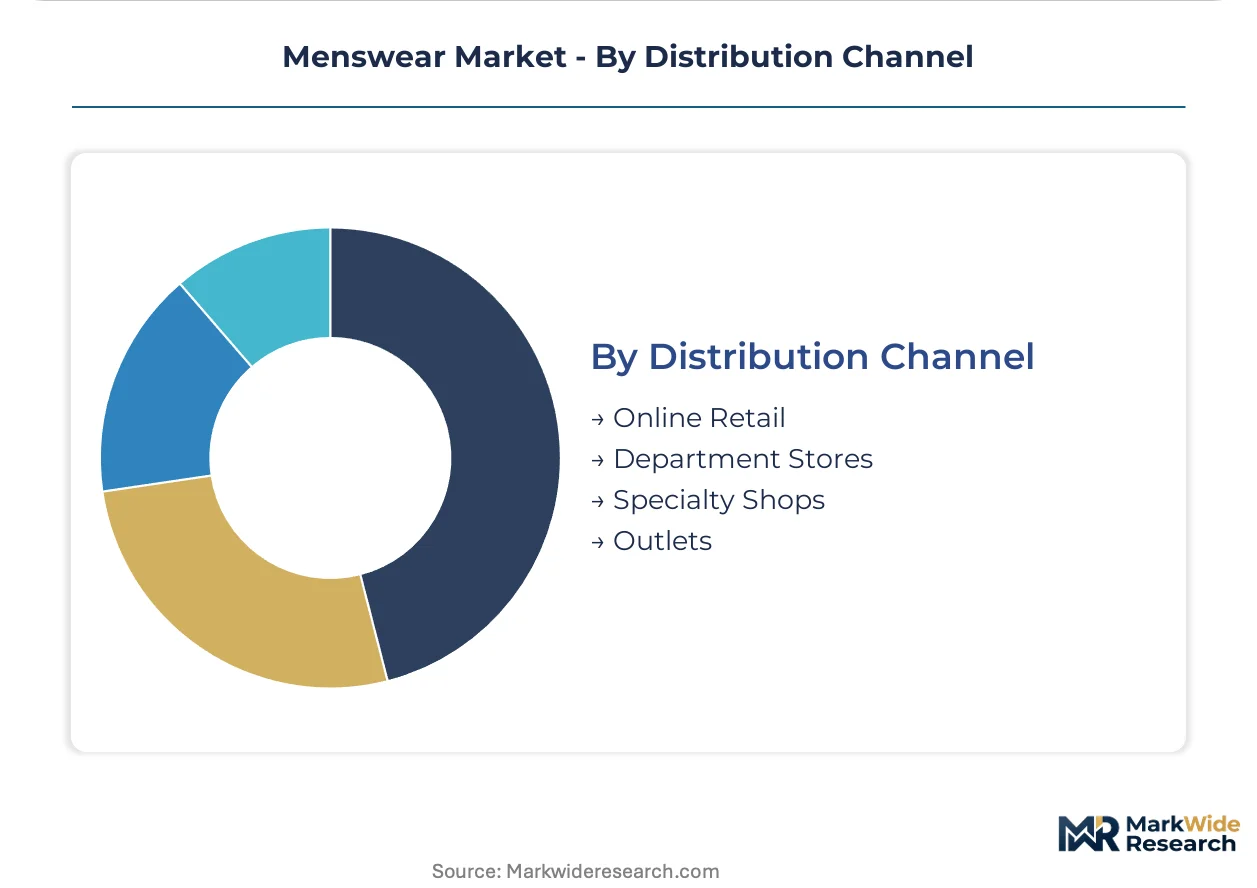
Online Retail sits at the top of the volume ranking, with Specialty Shops climbing the fastest through experiential differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China captures volume leadership through domestic brand acceleration while the United States sustains premium pricing power through direct-to-consumer infrastructure. India presents whitespace for international entrants before local consolidation hardens. European markets face compliance friction from chemical disclosure mandates. Japan maintains steady demand through quality-centric purchasing patterns.
China
Domestic menswear producers are displacing Western labels through localized design and compressed lead times. The Ministry of Ecology and Environment enforces dual carbon goals that create preferential market access for verified low-carbon production credentials. Shanghai and Guangzhou host the densest concentration of vertically integrated manufacturing clusters serving both domestic consumption and regional export.
United States
Subscription-based wardrobe curation and algorithmic styling displace traditional replenishment among urban professionals aged 25-40. The FTC enforces textile labeling rules on fiber content accuracy while California's SB 657 extends accountability to tier-two suppliers. Los Angeles anchors vertical manufacturing operations competing on speed-to-market against offshore-dependent rivals.
India
Rising disposable income concentration in Mumbai, Delhi, and Bangalore metros creates whitespace for positioned international entrants. The Bureau of Indian Standards governs quality certifications for textile products entering formal retail channels. Maharashtra and Gujarat host expanding manufacturing capacity serving both domestic demand and export-oriented production.
Germany
Hybrid work normalization drives demand for garments signaling competence across video and in-person contexts. ECHA administers REACH chemical disclosure requirements that reshape sourcing decisions for textile finishing processes. Bavaria and North Rhine-Westphalia concentrate specialty retail and e-commerce logistics infrastructure serving European distribution.
Japan
Quality-centric purchasing patterns sustain steady replacement cycles despite demographic contraction. METI oversees industrial standards coordination while consumer preferences favor durability and repair-oriented consumption. The Kanto region around Tokyo maintains the highest concentration of premium menswear retail and domestic brand headquarters.
Menswear Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with direct-to-consumer verticals capturing margin expansion while wholesale-dependent operators face promotional pressure. Market structure concentrates around three tiers: transparent pricing disruptors, heritage outdoor specialists, and digitally native basics purveyors. Competitive moves center on repair-and-resale channel innovation and AI-assisted pattern grading for size inclusivity.
Within the transparent pricing tier, Everlane exemplifies margin control through direct customer relationships and cost disclosure protocols. Among heritage-positioned operators, Patagonia anchors customer retention through repair-and-resale programs that extend product lifecycles. At the vertically integrated end, Buck Mason occupies a position competing on speed-to-market through Los Angeles-based manufacturing.
| Leading Market Players |
|---|
| Everlane |
| Banana Republic |
| Mack Weldon |
| Madewell |
| COS |
| Bonobos |
| Patagonia |
| UNTUCKit |
| Buck Mason |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap specialists concentrated in Italy's Veneto and Tuscany regions anchor premium menswear pricing through captive atelier networks and multi-generational supplier relationships that resist cost compression. Their ownership structure insulates pricing discipline from quarterly earnings pressure while sustaining investment in artisan finishing techniques that command sustained price premiums against offshore competitors.
Pricing Analysis
Capacity additions in Vietnam and Bangladesh are reshaping price floors for mid-tier casual wear, forcing established brands to differentiate through certification tiers or vertical integration. Three-tier pricing structure across premium, standard, and economy levels stratifies by fiber provenance and finishing location, with REACH compliance adding cost layers for European-bound production. Pricing pressure stems from cotton commodity volatility and speculative positioning in futures markets. Price sensitivity concentrates among urban millennials prioritizing subscription access over ownership, while professionals aged 35-50 exhibit lower elasticity for hybrid-work-appropriate garments.
Supply Chain Analysis
Direct-to-brand channels handle replenishment demand from vertically integrated operators, while wholesale-dependent brands rely on tiered distributor networks with longer inventory cycles. Manufacturing concentrates in China, Vietnam, and Bangladesh, with Portugal and Romania serving European quick-turn requirements. Raw material dependencies center on cotton futures, wool auctions, and petroleum-derived polyester feedstocks. Single-source vulnerability in Chinese dyeing and finishing capacity exposes brands to regulatory enforcement shifts under MEE dual carbon mandates. Distribution runs through direct-to-consumer platforms, specialty retail partnerships, and department store concessions with varying margin extraction profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The menswear market reads as a late-cycle quality story, with hybrid work normalization shifting replacement cycles toward premium specifications that signal competence across video and in-person contexts simultaneously.
For Market Incumbents: Extend repair-and-resale infrastructure to capture recurring revenue streams and deepen customer data assets unavailable through wholesale channels. Consolidate pattern engineering talent through acquisition of computational design studios to compress development timelines threatened by AI-assisted grading adoption among direct-to-consumer entrants. Channel control through owned retail footprints defends margin position against promotional calendar compression in department stores. For New Entrants and Emerging Players: Size-inclusive professionals aged 40-55 represent an underserved buyer archetype with unmet demand for algorithmically graded extended sizing in premium casual categories. India's underpenetrated metros offer whitespace before domestic competitors consolidate, particularly in Mumbai and Bangalore where disposable income concentration accelerates. A direct-to-consumer launch with transparent pricing and localized design capabilities captures share from slower Western incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among wholesale-dependent heritage brands with repair infrastructure potential but undermonetized customer databases. Long-term viability across the analysis window hinges on successful transition from transactional retail to subscription or membership models with predictable recurring revenue. Acquisition targets with verified low-carbon production credentials command preferential access to Chinese and European markets. The signal to watch is tier-two supplier disclosure compliance under California SB 657 and REACH expansion timelines, which will separate compliant operators from restructuring liabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Repair-and-Resale Platform Launch | Patagonia's lifecycle extension programs demonstrate retention economics unavailable through traditional wholesale channels. |
| AI-Assisted Pattern Grading Investment | Machine learning adoption by Buck Mason and Everlane compresses cost advantages of scale-dependent competitors. |
| Vertical Manufacturing Consolidation | Los Angeles-based production clusters compete on speed-to-market against offshore-dependent rivals in trend-responsive categories. |
| REACH Compliance Certification | ECHA chemical disclosure requirements reshape sourcing decisions for brands selling into European member states. |
| Subscription Wardrobe Curation | Algorithmic styling platforms in London and New York concentrate customer data with operators displacing self-directed browsing. |
Research Approach
Coverage spans China, the United States, India, Germany, and Japan, with primary inputs from each market's stakeholder ecosystem. The research combines structured interviews with brand managers, category buyers at major retailers, supply chain directors, and technical pattern engineers with secondary validation from customs records, textile trade databases, and SEC filings from publicly traded apparel companies. Bottom-up demand modeling triangulates against top-down market sizing from production volume and trade flow analysis.
Segmentation dimensions include product type, fabric specification, customer generation, and distribution channel, with regional regulatory clusters modeled separately for REACH, FTC, and dual carbon goal compliance impacts. CAGRs derive from trend extrapolation moderated by replacement cycle analysis and channel shift elasticity. Forecast inputs incorporate fiber innovation adoption curves, hybrid work normalization velocity, and domestic brand share capture rates in China.
Inputs from brand executives and retail procurement officers were available through the study window; gaps in tier-two supplier disclosure documentation introduce uncertainty bands around compliance cost projections. Forecasts reflect assumptions regarding sustained hybrid work patterns and continued ECHA chemical restriction expansion. Periodic stress-testing of base assumptions is recommended against macroeconomic shifts in discretionary spending and regulatory enforcement timeline acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Bra Market
Apparel & Footwear
Ethnic Wear Market
Apparel & Footwear
Sleepwear Market
Apparel & Footwear
India Denim Jeans Market
Apparel & Footwear
Hats Market
Apparel & Footwear
Men's Coats and Jackets Market
Apparel & Footwear
Denim Jeans Market
Apparel & Footwear
Global Silk Pajamas Market
Apparel & Footwear
Ice Hockey Apparel Market
Apparel & Footwear
US Fanny Packs Market
Apparel & Footwear
Apparel and Leather Products Market
Apparel & Footwear
Australia Denim Jeans Market
Apparel & Footwear
Golf Outfit Market
Apparel & Footwear
Global Leggings Market
Apparel & Footwear
Sports Apparel Embellishment Market
Apparel & Footwear
Global Adaptive Clothing Market