
 Europe Headwear Market | 2026-2036
Europe Headwear Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Headwear Market Foresight
Aftermarket customization and limited-edition collaborations is reshaping margin capture in the Europe headwear market. Nike Inc. leverages its athlete endorsement network to sustain premium pricing on performance caps across Southern Europe. Adidas AG anchors its position through retro heritage lines that dominate urban streetwear channels. New Era Cap specializes in licensed sports headwear, controlling distribution through select retail partnerships in France and the United Kingdom.
Headwear encompasses fitted, adjustable, and brimmed coverings manufactured from woven, knitted, or molded materials with specifications spanning crown height, brim width, and moisture-wicking performance ratings, serving functions from ultraviolet protection to thermal insulation and corporate identity display. Baseball caps and beanies lead volume due to their casual style penetration across age demographics, while fedoras represent a concentrated margin pool within formal style segments. Wool and cotton materials sustain premium positioning as REACH-compliant organic certifications expand among environmentally positioned buyers.
EMA guidelines on skin-contact textiles and the EU Green Deal's circular economy requirements are tightening chemical disclosure standards, compelling manufacturers to reformulate dyes and finishes. France's ANSM enforces additional testing protocols for infant headwear, creating compliance barriers for non-EU suppliers. Stakeholders must monitor evolving ECHA substance restrictions and decide whether to absorb certification costs or consolidate supplier bases within the European Economic Area.
Market Dynamics
REACH compliance on textile chemicals and the EU Green Deal's sustainability mandates are redirecting material sourcing toward organic cotton and recycled polyester, compressing margins for suppliers unable to certify.
Growth Catalysts
- EU Green Deal circular economy requirements:Mandates for recycled content in textiles are pulling demand toward certified recycled polyester blends across German and French retail channels.
- Athleisure adoption among urban professionals:Performance headwear purchases are expanding across Western Europe as workplace dress codes relax.
- France:Fashion-conscious consumers in Paris and Lyon are driving premium segment growth through demand for heritage wool craftsmanship.
Market Restraints
- Organic cotton input cost volatility:Weather-sensitive harvests in Turkey and Egypt are compressing margins for REACH-certified suppliers.
- ECHA substance restrictions:Evolving chemical disclosure standards are forcing reformulation of dyes and finishes, extending product development timelines.
- Technical limitation in moisture-wicking performance:Natural fiber blends struggle to match synthetic benchmarks in high-intensity athletic applications.
Strategic Opportunities
- Italy:Underpenetrated sustainable headwear segments in Milan and Rome offer white space for organic-certified premium positioning.
- Regulatory tailwind from CSRD:Corporate sustainability reporting requirements are creating procurement preference for traceable supply chains among enterprise buyers.
- Direct-to-consumer channel innovation:Customization platforms are capturing margin previously allocated to wholesale distributors in the United Kingdom.
Industry Challenges
- REACH certification timeline compression:ECHA's accelerated substance restriction reviews are outpacing supplier reformulation capacity.
- Skill gap in circular design:Shortage of technicians trained in mechanical recycling integration for textile headwear production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Headwear Market |
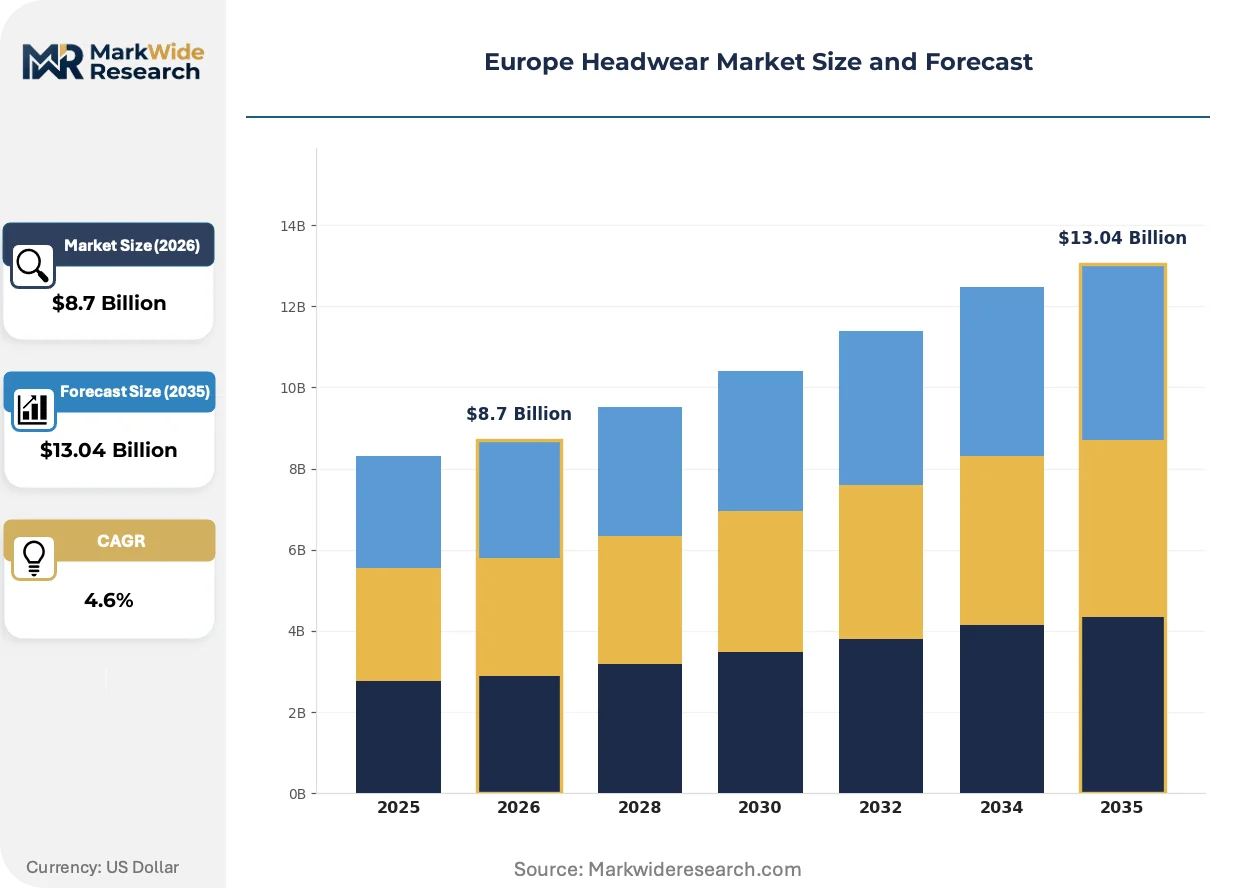
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baseball Caps, Beanies, Sun Hats, Fedoras Material: Cotton, Polyester, Wool, Straw Gender: Men, Women, Unisex, Children Style: Casual, Formal, Sports, Fashion |
| Companies Covered | Nike Inc., New Era Cap, Adidas AG, Puma SE, Under Armour Inc., Superdry PLC, Pipolaki, Kangol Limited, Lock & Co. Hatters, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Headwear Market Shifts & Advancements
Material science convergence and regulatory disclosure mandates are compressing traditional product development cycles while opening premium positioning for certified sustainable alternatives.
Recycled ocean plastic fiber technology is hybridizing with traditional wool felting processes to create performance-driven formal headwear. Italian mill operators are piloting these blends for autumn-winter collections. The structural consequence is hybridizing supply chains, forcing previously separate athletic and formalwear suppliers to share certification infrastructure.
France's ANSM infant headwear testing protocols are tightening chemical migration limits beyond baseline REACH requirements. Manufacturers serving this segment must duplicate testing regimes for products crossing French borders. Premium children's labels in the United Kingdom and Germany are absorbing these costs to maintain cross-channel distribution.
Corporate uniform procurement is consolidating vendor relationships around single-source sustainability certification. Facility managers in Germany and the Netherlands are replacing fragmented supplier bases with integrated headwear-apparel-footwear contracts. This consolidation is most visible in logistics and hospitality verticals where ESG reporting requirements intersect with high-volume replenishment needs.
Europe Headwear Market Segmentation
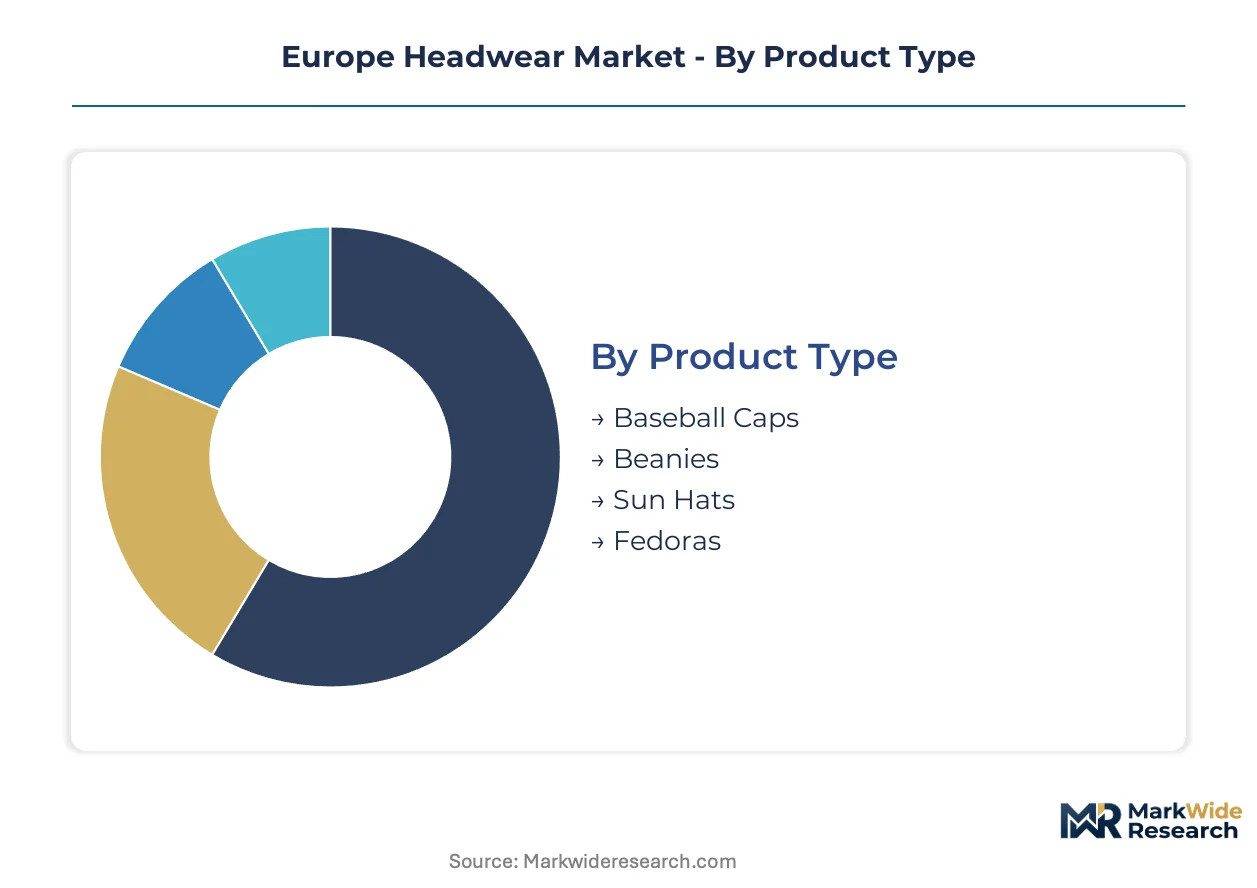
Segmentation in the Europe headwear market exposes divergent margin structures across material certifications and end-use applications. Product type and material composition determine regulatory compliance burden, while gender and style dimensions shape channel strategy and pricing architecture.
Product Type:
Volume concentration across the continent clusters around casual headwear formats with the deepest retail penetration.
- Baseball Caps:Structured crown with adjustable or fitted closure systems, typically six-panel construction. German and French urban consumers drive replacement cycles through athleisure integration, with workplace dress code relaxation accelerating purchase frequency among professionals aged 25-40.
- Beanies:Knitted close-fitting caps without brim, manufactured in wool or acrylic blends. Cold-weather demand concentrates in Nordic markets and Alpine regions, where thermal performance ratings influence premium positioning during autumn-winter retail windows.
- Sun Hats:Wide-brimmed designs with UPF-rated materials for ultraviolet protection.
- Fedoras:Felt or straw constructions with pinched crown and flexible brim, anchoring formalwear segments.
Baseball caps command the established base. The steepest expansion runs through beanies.
Material:
Certification requirements under REACH and the EU Green Deal are reconfiguring procurement priorities across supplier networks.
- Cotton:Natural cellulose fiber requiring substantial water input, now subject to organic certification demand. Italian and Spanish mills are converting capacity to GOTS-certified production to capture premium positioning in Paris and Milan retail channels.
- Polyester:Synthetic polymer derived from petroleum, increasingly manufactured from post-consumer recycled feedstock. German retailers are mandating recycled content thresholds, compressing margins for non-certified suppliers unable to verify ocean plastic or PET bottle sourcing.
- Wool:Animal fiber with natural moisture-wicking and thermal properties.
- Straw:Plant-based fiber woven for breathable summer constructions.
Polyester holds volume leadership through cost efficiency. Cotton is climbing the fastest on sustainability premiums.
Gender:
Demographic targeting determines design complexity and inventory depth at the retail tier.
- Men:Traditional sizing with standardized crown dimensions dominates sports licensing and corporate uniform procurement. United Kingdom and Netherlands facility managers consolidate vendor relationships around single-source contracts spanning headwear through footwear.
- Women:Expanded size gradations and decorative embellishments create higher SKU density. French and Italian fashion retailers demand shorter production cycles to align with seasonal trend velocity.
- Unisex:Adjustable closure systems with neutral color palettes.
- Children:Smaller circumference specifications with safety-compliant components.
Men's segments anchor institutional procurement volume. Women's lines are expanding most quickly through direct-to-consumer channels.
Style:
End-use occasion defines performance specifications and margin capture potential.
- Casual:Unstructured designs prioritizing comfort and versatility across daily wear contexts. Beaches and urban parks in Southern Europe sustain steady replenishment demand for cotton and straw constructions.
- Sports:Technical fabrics with moisture-wicking and aerodynamic properties. Performance running and cycling communities in Germany and Belgium drive specifications for laser-perforated panels and reflective detailing.
- Formal:Structured silhouettes with refined finishing.
- Fashion:Trend-responsive designs with limited-edition positioning.
Casual styling commands the established base. The steepest expansion runs through sports applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across Europe. German buyers prioritize certified sustainable materials in corporate procurement. French and Italian consumers drive heritage craftsmanship premiums. Nordic markets emphasize thermal performance in technical beanies.
Germany
Corporate uniform consolidation and athleisure workplace integration sustain volume demand. CSRD reporting requirements push facility managers toward single-source certified suppliers. Berlin and Hamburg logistics hubs anchor integrated headwear-apparel-footwear procurement contracts for hospitality and transport verticals.
France
Paris and Lyon fashion consumers sustain premium heritage wool positioning. ANSM infant headwear testing protocols exceed baseline REACH requirements, duplicating compliance costs for cross-border suppliers. Mill operators in Normandy convert capacity to GOTS-certified production for autumn-winter collections.
Italy
Milan and Rome present underpenetrated sustainable premium segments despite established luxury apparel infrastructure. EU Green Deal circular economy mandates accelerate recycled polyester adoption in technical sportswear. Biella textile cluster pilots hybrid wool-recycled ocean plastic blends for formal headwear lines.
United Kingdom
Direct-to-consumer customization platforms capture margin from wholesale distributors in London and Manchester retail channels. ECHA substance restriction timelines compress supplier reformulation capacity. Heritage mill towns in Yorkshire and Scotland sustain wool felt production for formalwear exports.
Netherlands
Rotterdam and Amsterdam facility managers consolidate vendor relationships around integrated sustainability certification. REACH-compliant organic cotton procurement concentrates through Dutch trading houses with Turkish and Egyptian supply chain control. Technical education partnerships address circular design skill gaps in mechanical recycling integration.
Europe Headwear Market Competitive Landscape
Capability concentration sits with heritage craftsmanship specialists; scale advantage sits with integrated sportswear conglomerates. The vendor base organizes around three strategic archetypes: licensed sports licensors with controlled distribution, athleisure conglomerates leveraging athlete endorsement networks, and heritage mill operators preserving wool felting traditions. Competitive moves center on sustainability certification acquisition and direct-to-consumer channel bypass of wholesale intermediaries.
Within the sportswear conglomerate tier, Nike Inc. and Adidas AG exemplify scale-driven positioning through athlete endorsement networks and retro heritage line architecture. New Era Cap occupies a specialist position in licensed sports headwear with selective retail partnership control across France and the United Kingdom. Heritage craftsmanship capability concentrates with mill-based operators like Kangol Limited and Lock & Co. Hatters, representing traditional wool felting and bespoke formalwear archetypes respectively.
| Leading Market Players |
|---|
| Nike Inc. |
| New Era Cap |
| Adidas AG |
| Puma SE |
| Under Armour Inc. |
| Superdry PLC |
| Pipolaki |
| Kangol Limited |
| Lock & Co. Hatters |
| Others |
Supply & Pricing Matrix
Turkish and Egyptian organic cotton harvest concentration anchors margin capture for REACH-certified suppliers serving Paris and Milan premium retail channels. Certification cost absorption separates certified organic tier pricing from conventional cotton alternatives, compressing non-compliant supplier margins.
Pricing Analysis
Long-term offtake contracts dominate procurement between German facility managers and integrated headwear-apparel-footwear suppliers, locking volume commitments across CSRD reporting cycles. Price differentiation hinges on GOTS certification tier and customization depth, with direct-to-consumer platforms capturing premium spreads previously allocated to wholesale distributors. Cost compression in conventional polyester tier is intensifying because German retailers mandate recycled content thresholds. Enterprise buyers with ESG reporting obligations exhibit lowest price sensitivity; mass-market casual wear consumers remain most responsive to unit cost shifts.
Supply Chain Analysis
Extended payment terms from Dutch trading houses to Turkish and Egyptian cotton growers are restructuring working capital requirements across the supplier tier. Raw material sourcing draws from organic cotton fields in Turkey and Egypt, recycled PET feedstock from ocean plastic recovery operations, and wool from Yorkshire and Scottish heritage mill towns. Single-source vulnerability concentrates in GOTS-certified spinning capacity serving Italian luxury channels. Distribution runs through selective retail partnerships in France and the United Kingdom, direct-to-consumer platforms in London and Manchester, and integrated corporate uniform contracts across German logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where REACH certification entrenchment creates switching costs for enterprise buyers locked into CSRD-compliant supplier relationships.
For Market Incumbents: Build certification moats through accelerated GOTS and REACH compliance investment ahead of ECHA's accelerated substance restriction reviews. Secure backward integration into Turkish organic cotton supply to defend against input cost volatility from weather-sensitive harvests. Consolidate channel control through exclusive partnerships with Dutch trading houses and German facility managers replacing fragmented supplier bases.
For New Entrants and Emerging Players: Build out white-space positioning in Italy's underpenetrated sustainable premium segments despite established luxury apparel infrastructure. Target Milan and Rome fashion consumers through heritage wool craftsmanship positioning with GOTS-certified autumn-winter collections. Deploy direct-to-consumer customization platforms to bypass wholesale margin extraction in United Kingdom retail channels.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed heritage mill operators in Yorkshire and Scotland possessing wool felting capability but lacking circular design technical capacity. Five-to-ten year viability favors suppliers with integrated certification infrastructure spanning organic cotton sourcing through finished headwear production. Monitor ECHA substance restriction timeline compression as inflection indicator for supplier consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| GOTS Certification Acceleration | Captures premium positioning in Paris and Milan retail channels ahead of regulatory tightening. |
| Backward Integration into Organic Cotton | Secures supply chain control over Turkish harvests vulnerable to climate-induced input volatility. |
| Direct-to-Consumer Platform Launch | Bypasses wholesale margin extraction in United Kingdom and German urban retail channels. |
| Recycled Ocean Plastic Fiber Adoption | Aligns with EU Green Deal mandates pulling German retailers toward certified polyester blends. |
| Heritage Mill Capability Acquisition | Preserves wool felting tradition while injecting circular design technical capacity from technical education partnerships. |
Research Methodology
Initial hypotheses were tested against primary input from brand managers at sportswear conglomerates, category buyers at French and Italian fashion retailers, supply planners at Dutch trading houses, and technical R&D directors at Italian mill operators and refined through secondary validation against ECHA substance restriction databases, EU Green Deal circular economy implementation reports, GOTS certification registry data, and customs records for organic cotton trade flows. Bottom-up demand modeling across product type, material certification tier, gender targeting, and style occasion segments was triangulated against top-down market sizing from corporate sustainability procurement disclosures.
Demand-supply balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type, material composition, gender demographic, and style occasion. CAGRs were derived from regression analysis of historical premium segment expansion rates and projected athleisure workplace adoption curves. Industry-specific forecast inputs included CSRD reporting timeline acceleration and ECHA substance restriction review velocity.
Stress conditions across organic cotton harvest yield variance, ECHA regulatory timeline compression, and athleisure workplace dress code adoption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding certification cost absorption capacity and supplier consolidation velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Erotic Lingerie Market
Apparel & Footwear
Polo Shirt Market
Apparel & Footwear
US Fanny Packs Market
Apparel & Footwear
Smart Heating Scarf Market
Apparel & Footwear
Intimate Wear Market
Apparel & Footwear
Mexico Denim Jeans Market
Apparel & Footwear
Jeans Market
Apparel & Footwear
Sports Apparel Market
Apparel & Footwear
Global Women Pajamas Suits Market
Apparel & Footwear
Gym Apparel Market
Apparel & Footwear
Secondhand Apparel Market
Apparel & Footwear
Maternity Apparels Market
Apparel & Footwear
Ice Hockey Apparel Market
Apparel & Footwear
Football Jerseys Market
Apparel & Footwear
Denim Jeans Market
Apparel & Footwear
Outdoor Sports Apparel Market