
 North America Functional Pet Treat Market | 2026-2036
North America Functional Pet Treat Market Size, Share, and Industry Trends Forecast 2026-2036
North America Functional Pet Treat Market Insights
Canada is reconfiguring its functional pet treat manufacturing footprint with new capacity in Ontario and British Columbia. General Mills leverages its supply chain infrastructure to sustain distribution density across mass retail channels. Mars Incorporated anchors its position through veterinary-exclusive formulations that compete directly with clinical nutrition brands. Blue Buffalo differentiates via grain-free positioning and controls premium shelf space in specialty pet retailers.
Functional pet treats are formulated consumables delivering targeted health outcomes through bioactive ingredients, extrusion or cold-pressed processing, and controlled release matrices designed for palatability and nutrient stability. Soft chews lead product type demand due to their medication-masking utility and senior pet accessibility, while grain-free ingredient positioning commands margin premiums despite formulation complexity. Joint support and digestive health benefit categories attract the fastest-growing customer type segment, online consumers, who cross-reference veterinary recommendations with direct-to-subscription offerings.
The FDA enforces Current Good Manufacturing Practice regulations for animal food under FSMA, while the Association of American Feed Control Officials establishes nutrient profiles and ingredient definitions that shape product development timelines. Health Canada and the Canadian Food Inspection Agency maintain parallel standards that create cross-border compliance obligations for integrated North American supply chains. Stakeholders must monitor evolving state-level raw material sourcing requirements and veterinary channel credentialing standards that will determine market access trajectories.
Market Dynamics
Millennial pet owners are forcing a premiumization wave that restructures formulation priorities across the North America Functional Pet Treat Market, with human-grade ingredient sourcing now table stakes for shelf placement in specialty retail channels.
Growth Catalysts
- FSMA Current Good Manufacturing Practice:The FDA's enforcement of preventive controls for animal food is accelerating consolidation among contract manufacturers capable of compliance investments.
- Soft chew medication masking:Veterinary clinics are expanding dispensing of functional treats as adherence tools for chronic condition management in senior companion animals.
- California-Texas urban corridor concentration:Pet owner density in these metropolitan clusters is pulling cold-chain distribution infrastructure toward regional fulfillment hubs.
Market Restraints
- Protein input cost volatility:Wild-caught fish and novel protein sourcing face price instability from climate-impacted fisheries and livestock supply constraints.
- Cross-border compliance friction:Health Canada and the Canadian Food Inspection Agency maintain ingredient approval timelines that lag FDA determinations, complicating integrated North American supply chains.
- Grain-free formulation complexity:Alternative carbohydrate binders require specialized extrusion equipment that limits contract manufacturing capacity.
Strategic Opportunities
- Direct-to-subscription channel expansion:Online consumers cross-referencing veterinary recommendations represent underpenetrated lifetime value capture for condition-specific formulations.
- Joint support category extension:Glucosamine and omega-3 delivery formats targeting mobility concerns in aging pets open formulation white space beyond conventional chews.
- State-level raw material sourcing incentives:Emerging agricultural programs in Ontario and British Columbia are creating captive supply opportunities for integrated manufacturers.
Industry Challenges
- Veterinary channel credentialing timelines:Professional endorsement protocols for clinical nutrition competitors extend product launch cycles and delay reimbursement integration.
- Controlled release matrix R&D capacity:Bioavailability engineering expertise concentrates in limited formulation houses, creating talent scarcity for palatability optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Functional Pet Treat Market |
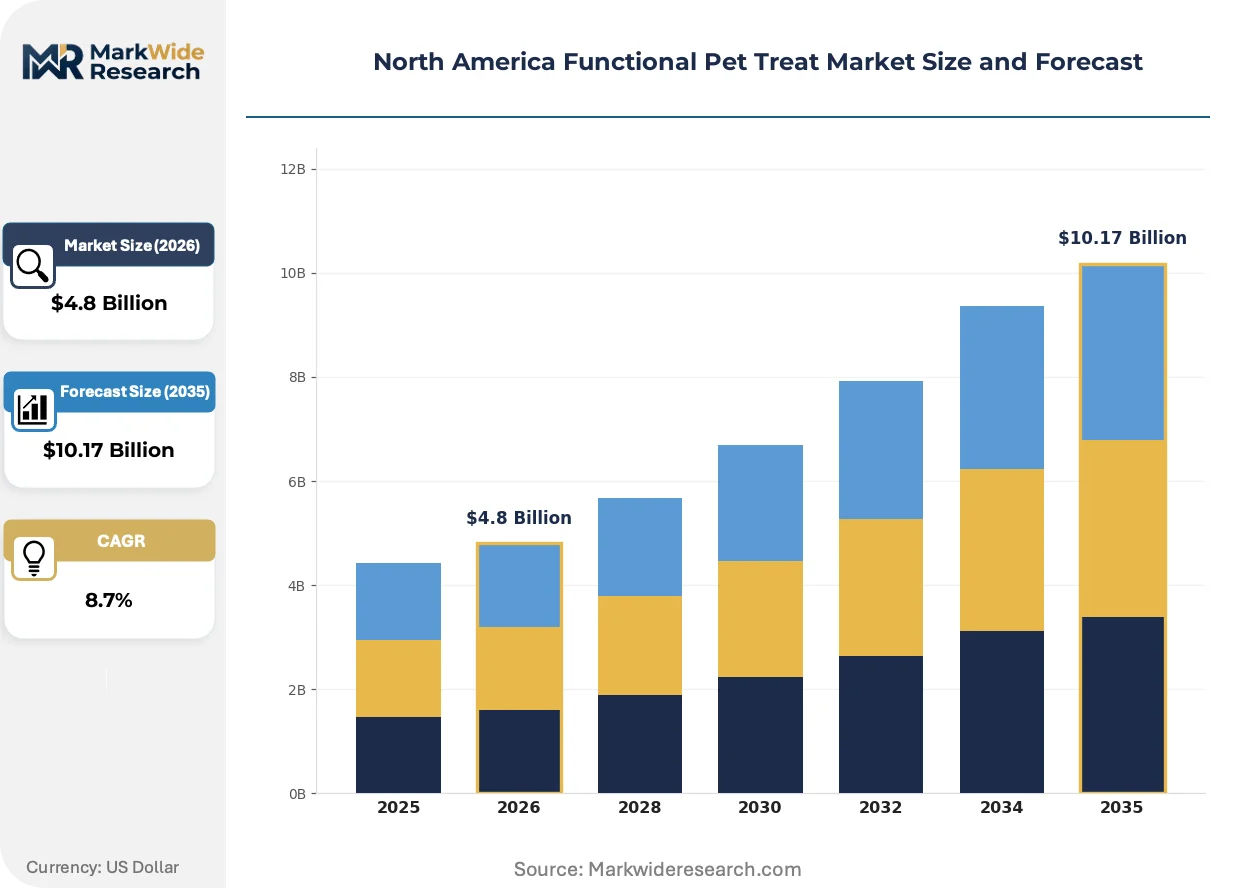
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Chews, Crunchy Treats, Biscuits, Others Ingredient Type: Organic, Natural, Grain-Free, Animal-Sourced Customer Type: Pet Owners, Pet Retailers, Online Consumers, Veterinarians Health Benefits: Digestive Health, Joint Support, Skin & Coat, Dental Care |
| Companies Covered | General Mills, Blue Buffalo, Mars Incorporated, Nulo Pet Food, Petcurean Pet Nutrition, Nestlé Purina PetCare, The J.M. Smucker Company, VēRUS Pet Foods, Hill's Pet Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Functional Pet Treat Market Trends and Innovations
Cold-pressed processing methods are disrupting thermal degradation assumptions in nutrient stability, while regulatory scrutiny of ingredient claims is compressing marketing timelines across the North America Functional Pet Treat Market.
Encapsulation technology for sensitive bioactives is migrating from pharmaceutical applications into pet treat manufacturing, enabling probiotic survival through gastric transit. Premium and veterinary-exclusive brands are adopting these systems fastest, with shelf-stable digestive health formulations now displacing refrigerated alternatives in specialty retail. The structural consequence is a compression of formulation development cycles as manufacturers race to match stability claims.
The FDA's evolving enforcement posture on structure-function claims is tightening substantiation requirements for joint support and cognitive health marketing. This regulatory pressure is forcing reformulation of legacy products and accelerating clinical trial investments among brands seeking veterinary endorsement. California and Texas markets are experiencing the most immediate compliance activity due to state attorney general scrutiny of pet product advertising.
Subscription-based replenishment models are displacing episodic retail purchasing among urban millennial pet owners, particularly for chronic condition management categories. Veterinary clinics are responding by white-labeling their own functional treat lines to capture recurring revenue. This channel shift is most visible in Toronto and Vancouver metropolitan areas, where direct-to-consumer penetration exceeds national averages.
North America Functional Pet Treat Market Segmentation
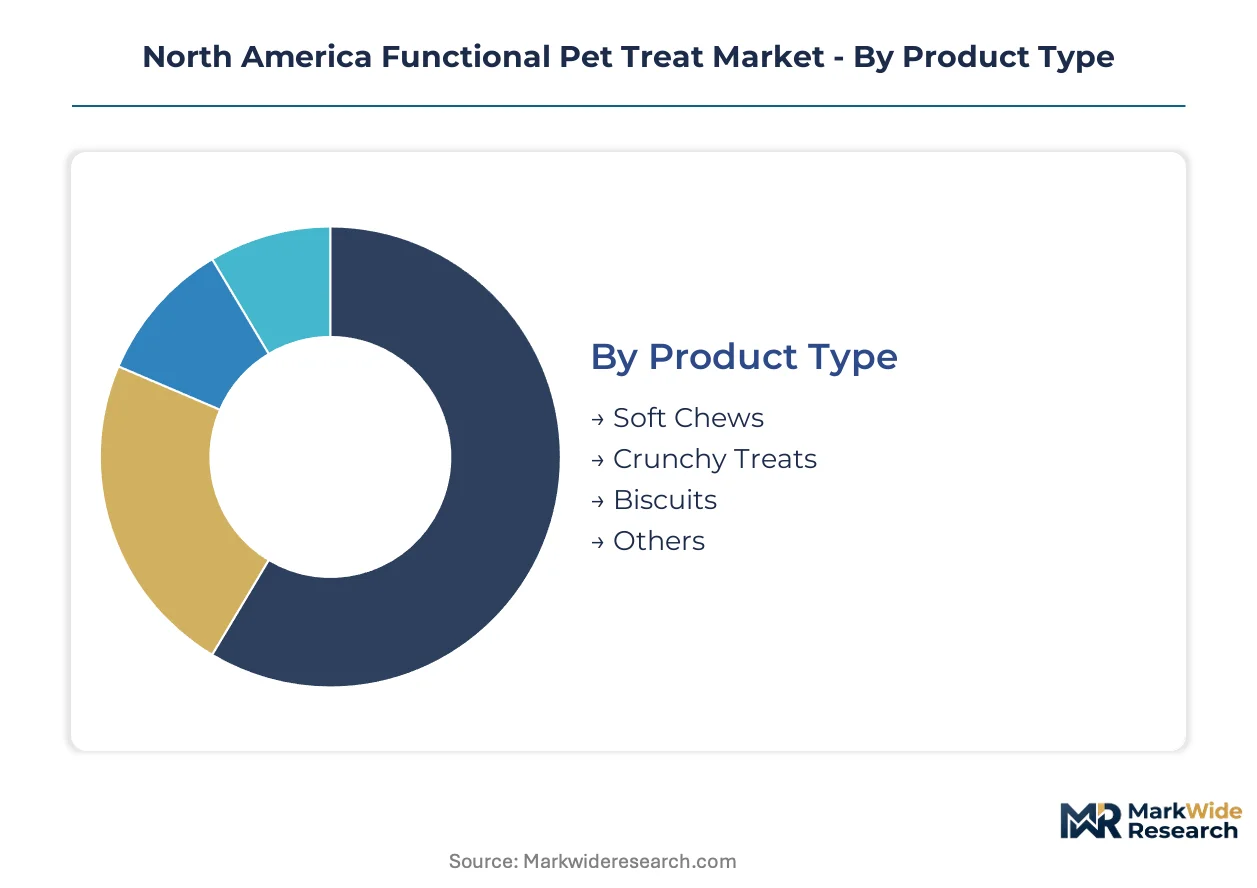
Functional pet treat manufacturers calibrate formulation complexity and channel strategy against four distinct segmentation axes. Product format determines processing investment and palatability engineering priorities. Ingredient positioning governs margin capture and regulatory substantiation burdens. Customer channel shapes packaging, dosing guidance, and professional endorsement requirements. Health benefit focus drives bioactive selection and clinical validation spend.
Product Type:
Cost tier differentiation separates mass-market accessible formats from premium-positioned alternatives requiring specialized equipment and controlled-release engineering.
- Soft Chews:Moist, pliable matrices incorporate active ingredients through cold-pressed or extrusion methods that preserve heat-sensitive bioactives. Veterinary clinics in California and Texas urban corridors stock these as medication-masking tools for senior pet adherence. Palatability engineering and controlled-release formulation complexity sustain margin premiums.
- Crunchy Treats:Baked or extruded dry formats achieve shelf stability through low water activity and oxygen barrier packaging. Pet retailers in Ontario and British Columbia allocate premium shelf space to these for their dental abrasion utility and storage convenience. Manufacturing scales efficiently on conventional pet food equipment.
- Biscuits:Dense, oven-baked products carry lower active ingredient payloads due to thermal degradation limits during processing. Traditional mass retail channels favor these for price-accessible positioning.
- Others:Emerging formats include freeze-dried bites, liquid supplements, and topical applicators serving niche delivery preferences.
Soft chews command the established base. The steepest expansion runs through emerging freeze-dried and liquid formats gaining traction in direct-to-subscription channels.
Ingredient Type:
Application-driven sourcing requirements separate human-grade supply chains from commodity feed-grade alternatives, with regulatory scrutiny intensifying for structure-function claims.
- Grain-Free:Alternative carbohydrate binders—tapioca, pea starch, sweet potato—replace wheat and corn to address digestive sensitivity positioning. Texas and California markets show concentrated demand from millennial pet owners cross-referencing online veterinary guidance. Specialized extrusion equipment limits contract manufacturing capacity and sustains price premiums.
- Organic:Certified organic ingredient sourcing requires audited supply chains from farm to finished good, with USDA National Organic Program compliance adding documentation burden. Premium specialty retailers in Toronto and Vancouver metropolitan areas prioritize these for shelf differentiation.
- Natural:Minimally processed ingredient positioning without synthetic preservatives or artificial colors captures mid-tier price positioning across mass and specialty channels.
- Animal-Sourced:Wild-caught fish, novel proteins, and organ meat concentrates deliver omega-3 fatty acids and bioactive peptides for targeted health outcomes.
Grain-free positioning commands the established base. The steepest expansion runs through organic-certified formulations as agricultural programs in Ontario and British Columbia expand captive supply.
Customer Type:
Volume concentration varies dramatically by channel, with professional endorsement requirements and replenishment frequency shaping customer lifetime value capture.
- Online Consumers:Direct-to-subscription purchasers cross-reference veterinary recommendations with auto-replenishment platforms, showing highest lifetime value for chronic condition management categories. Toronto and Vancouver metropolitan areas exceed national penetration averages.
- Veterinarians:Clinical dispensing channels require FDA-compliant structure-function claim substantiation and often reimbursement integration, extending product launch cycles but locking in professional endorsement.
- Pet Owners:Episodic retail purchasers in California and Texas urban corridors drive trial volume through specialty pet retailers and mass merchandisers.
- Pet Retailers:Independent and chain specialty stores curate premium assortments and influence discovery through shelf placement and staff recommendation.
Pet owners command the established base. The steepest expansion runs through online consumers adopting subscription models for condition-specific formulations.
Health Benefits:
Margin structure correlates with clinical validation depth and veterinary channel penetration, separating lifestyle positioning from therapeutic-adjacent claims.
- Joint Support:Glucosamine, chondroitin, and omega-3 delivery formats target mobility concerns in aging companion animals. Veterinary-exclusive brands compete directly with clinical nutrition lines through encapsulation technology enabling bioavailability claims.
- Digestive Health:Probiotic and prebiotic formulations leverage encapsulation advances from pharmaceutical applications to achieve shelf-stable gastric transit survival. California markets see accelerated FDA enforcement on substantiation requirements.
- Skin & Coat:Omega fatty acid and biotin positioning addresses cosmetic concerns with lower regulatory burden than therapeutic-adjacent claims.
- Dental Care:Mechanical abrasion and enzymatic formulations compete with professional cleaning services through daily-use convenience positioning.
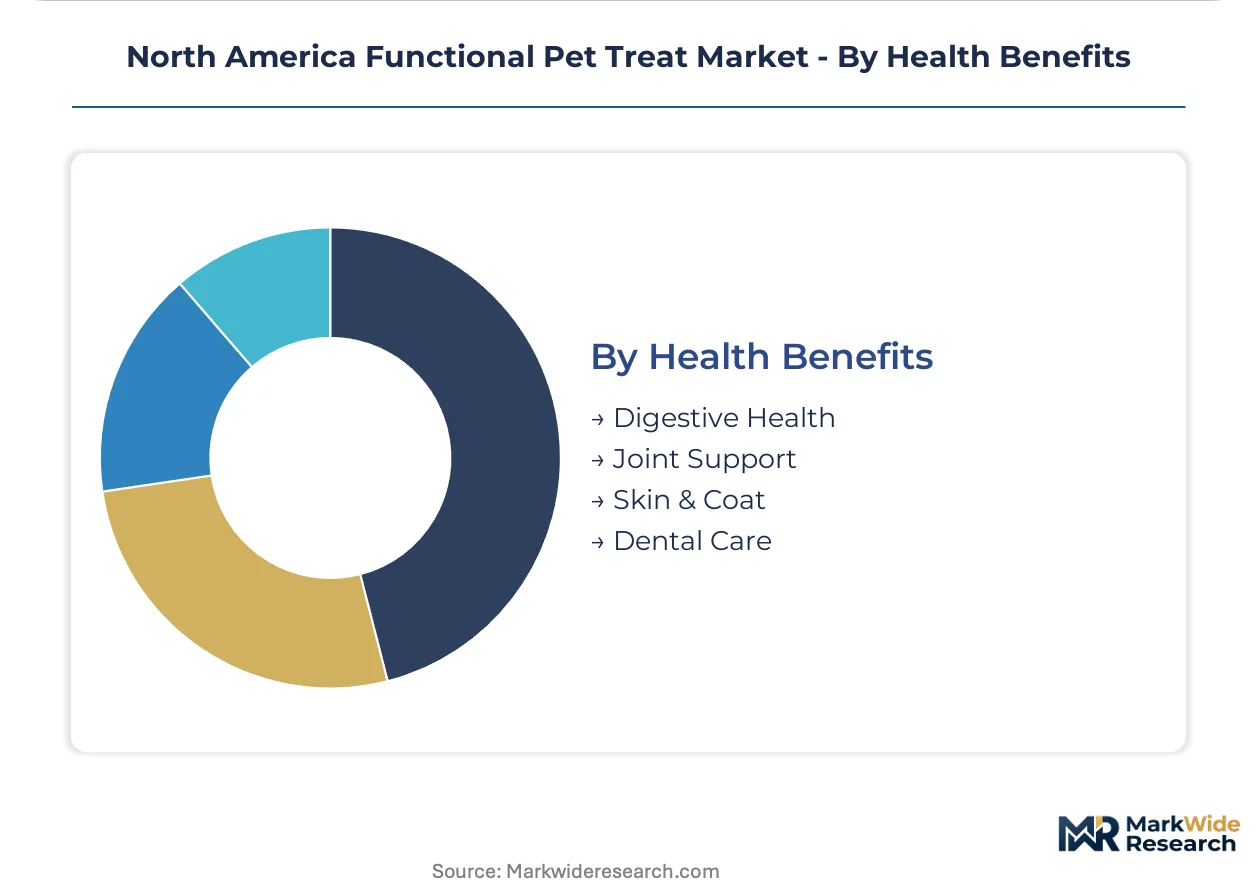
Skin and coat positioning commands the established base. The steepest expansion runs through joint support as veterinary channel credentialing protocols mature and reimbursement integration advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract manufacturing capacity clusters in Ontario and British Columbia, pulling cold-chain infrastructure toward regional fulfillment hubs that serve cross-border distribution networks. FDA and Health Canada regulatory divergence creates compliance friction that shapes facility siting decisions. Metropolitan pet owner density in California and Texas urban corridors concentrates demand pull.
United States
California and Texas urban corridors generate concentrated demand from millennial pet owners cross-referencing veterinary guidance with subscription platforms. FDA enforcement of FSMA preventive controls for animal food accelerates consolidation among contract manufacturers capable of compliance investments. Greater Los Angeles and Dallas-Fort Worth anchor cold-chain distribution infrastructure serving regional fulfillment networks.
Canada
Ontario and British Columbia manufacturing expansion targets captive supply opportunities from emerging agricultural programs. Health Canada and the Canadian Food Inspection Agency maintain ingredient approval timelines that lag FDA determinations, complicating integrated North American supply chains. Toronto and Vancouver metropolitan areas exceed national averages for direct-to-consumer subscription penetration.
Mexico
Mexico City Metro and Nuevo León manufacturing zones leverage proximity to US border logistics for cost-competitive production serving mass retail channels. Federal Commission for the Protection against Sanitary Risk enforces feed safety standards that align with FDA frameworks to facilitate export eligibility. Bajío Region agricultural output supports novel protein sourcing for grain-free formulation inputs.
North America Functional Pet Treat Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in bioactive sourcing and controlled-release engineering. The vendor base stratifies across three tiers: multinational CPG conglomerates with veterinary channel infrastructure, mid-cap specialists with premium positioning in specialty retail, and contract manufacturers with FSMA-compliant capacity. Two strategic archetypes dominate competitive dynamics: veterinary-exclusive formulators competing with clinical nutrition brands, and mass-market players leveraging supply chain density for retail shelf presence. M&A activity concentrates on acquiring encapsulation technology capabilities and expanding cold-pressed processing capacity.
Within the veterinary-exclusive tier, Mars Incorporated and Hill's Pet Nutrition exemplify clinical-channel positioning that extends product launch cycles in exchange for professional endorsement lock-in. Among CPG conglomerates, General Mills and Nestlé Purina PetCare occupy scale-driven positions sustaining distribution density across mass retail channels. Blue Buffalo anchors the premium specialty tier through grain-free positioning that controls shelf space in independent pet retailers.
| Leading Market Players |
|---|
| General Mills |
| Blue Buffalo |
| Mars Incorporated |
| Nulo Pet Food |
| Petcurean Pet Nutrition |
| Nestlé Purina PetCare |
| The J.M. Smucker Company |
| VēRUS Pet Foods |
| Hill's Pet Nutrition |
| Others |
Pricing and Supply Chain Analysis
FSMA compliance cost volatility determines both pricing tier spreads and supply chain shape across the North America Functional Pet Treat Market, forcing manufacturers to absorb preventive control investments or pass them through premium positioning. The regulatory chokepoint concentrates pricing power among FSMA-compliant contract manufacturers while fragmenting supply base alternatives.
Pricing Analysis
FDA Current Good Manufacturing Practice regulations dictate the pricing tier structure by imposing compliance cost burdens that stratify manufacturers into premium veterinary-exclusive, mid-tier specialty retail, and mass-market accessible segments. Three-tier pricing structure across premium, standard, and economy levels separates human-grade ingredient formulations from feed-grade alternatives and commodity-positioned biscuits. Pricing pressure stems from protein input cost volatility in wild-caught fish and novel protein sourcing, compressing margins in the standard tier. Mass retail channels exhibit highest price sensitivity, while veterinary clinics accept premium positioning for professional endorsement lock-in.
Supply Chain Analysis
Upstream feedstock sourcing draws from Ontario and British Columbia agricultural programs for grain-free carbohydrate binders, US wild-caught fisheries for omega-3 inputs, and Bajío Region livestock operations for novel proteins. Raw material dependencies center on tapioca and pea starch alternatives, cold-pressed processing equipment, and encapsulation technology for bioactive stability. Single-source vulnerability concentrates in limited formulation houses with controlled-release matrix expertise. Distribution runs through California-Texas urban corridor fulfillment hubs serving direct-to-subscription and veterinary clinic channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Functional Pet Treat Market sits in a premiumization-driven cyclical upswing as millennial pet owner spending patterns recover toward pre-inflation discretionary levels. Veterinary channel credentialing maturity and subscription model penetration provide cyclical support.
For Market Incumbents: Insulate margin position through backward integration into Ontario and British Columbia captive supply for grain-free binders, and accelerate FSMA-compliant capacity additions ahead of regulatory enforcement waves. Emerging contract manufacturers with cold-pressed processing capabilities threaten specialty retail positioning. Channel control through veterinary-exclusive formulation investments locks in professional endorsement.
For New Entrants and Emerging Players: Establish a beachhead in direct-to-subscription joint support formulations targeting Toronto and Vancouver metropolitan areas, where penetration exceeds national averages and customer lifetime value concentrates. The online consumer segment for chronic condition management remains underpenetrated by condition-specific entrants. Go-to-market execution should leverage veterinary recommendation cross-referencing in subscription platform design.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that targets encapsulation technology specialists and FSMA-compliant contract manufacturers with regional fulfillment infrastructure. Long-term viability across the analysis window favors platform integrators with veterinary channel access over pure-play commodity manufacturers. Monitor Health Canada-FDA regulatory convergence timelines as inflection indicator for cross-border supply chain investment decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulation Technology Acquisition | Enables probiotic survival claims that displace refrigerated alternatives in California specialty retail. |
| Cold-Pressed Processing Capacity Expansion | Preserves heat-sensitive bioactives for soft chew formulations serving senior pet adherence needs. |
| Veterinary Channel Credentialing Investment | Extends product launch cycles in exchange for professional endorsement lock-in against clinical nutrition brands. |
| Direct-to-Subscription Platform Launch | Captures recurring revenue from millennial pet owners cross-referencing online veterinary guidance. |
| Ontario-British Columbia Supply Integration | Creates captive grain-free binder sourcing from emerging provincial agricultural programs. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA FSMA enforcement documentation, Association of American Feed Control Officials ingredient definitions, and Health Canada regulatory filings. Interviews with veterinary clinic dispensing managers, specialty pet retailer category buyers, contract manufacturing operations directors, and direct-to-subscription platform executives informed demand-side validation. Secondary sources include customs trade data for protein input flows, Nielsen retail audit data for channel penetration patterns, and SEC filings for CPG conglomerate pet segment disclosures. Bottom-up segmentation modeling triangulates against top-down market sizing from regulatory framework analysis.
Forecast inputs incorporate product format processing cost differentials, ingredient certification tier premiums, customer channel replenishment frequency patterns, and health benefit category clinical validation spend across the projection horizon. Segmentation dimensions span soft chew versus crunchy treat versus emerging freeze-dried formats, grain-free versus organic versus natural ingredient positioning, online consumer versus veterinarian versus pet owner versus pet retailer channels, and joint support versus digestive health versus skin and coat versus dental care benefit categories. CAGRs derive from regression analysis against pet owner demographic shifts and veterinary recommendation adoption curves, with cold-chain distribution infrastructure buildout and encapsulation technology diffusion as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in disposable income trends among millennial households and protein commodity price indices would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement pacing and veterinary channel credentialing protocol maturation. Cross-checking against Nielsen retail audit channel shift data and veterinary dispensing survey benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Thunder Jacket for Dogs Market
Pet Care Products
North America Pet Diet Market
Pet Care Products
Gcc Pet Food Market
Pet Care Products
Cat Bed Market
Pet Care Products
Pet Pee Pads Market
Pet Care Products
Household Pet Water Dispenser Market
Pet Care Products
Smart Cat Eye Market
Pet Care Products
Mobile Pet Care Market
Pet Care Products
Organic Pet Food Market
Pet Care Products
Saudi Arabia Pet Food Market
Pet Care Products
Outdoor Cat House Market
Pet Care Products
Pet Odor Absorber Market
Pet Care Products
Dog Hats Market
Pet Care Products
Europe Pet Clothing Market
Pet Care Products
Cat Scratchers and Trees Market
Pet Care Products
UAE Pet Boarding Market