
 Asia-Pacific Business Process As a Service (Bpaas) Market | 2026-2036
Asia-Pacific Business Process As a Service (Bpaas) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Business Process As a Service (Bpaas) Market Outlook
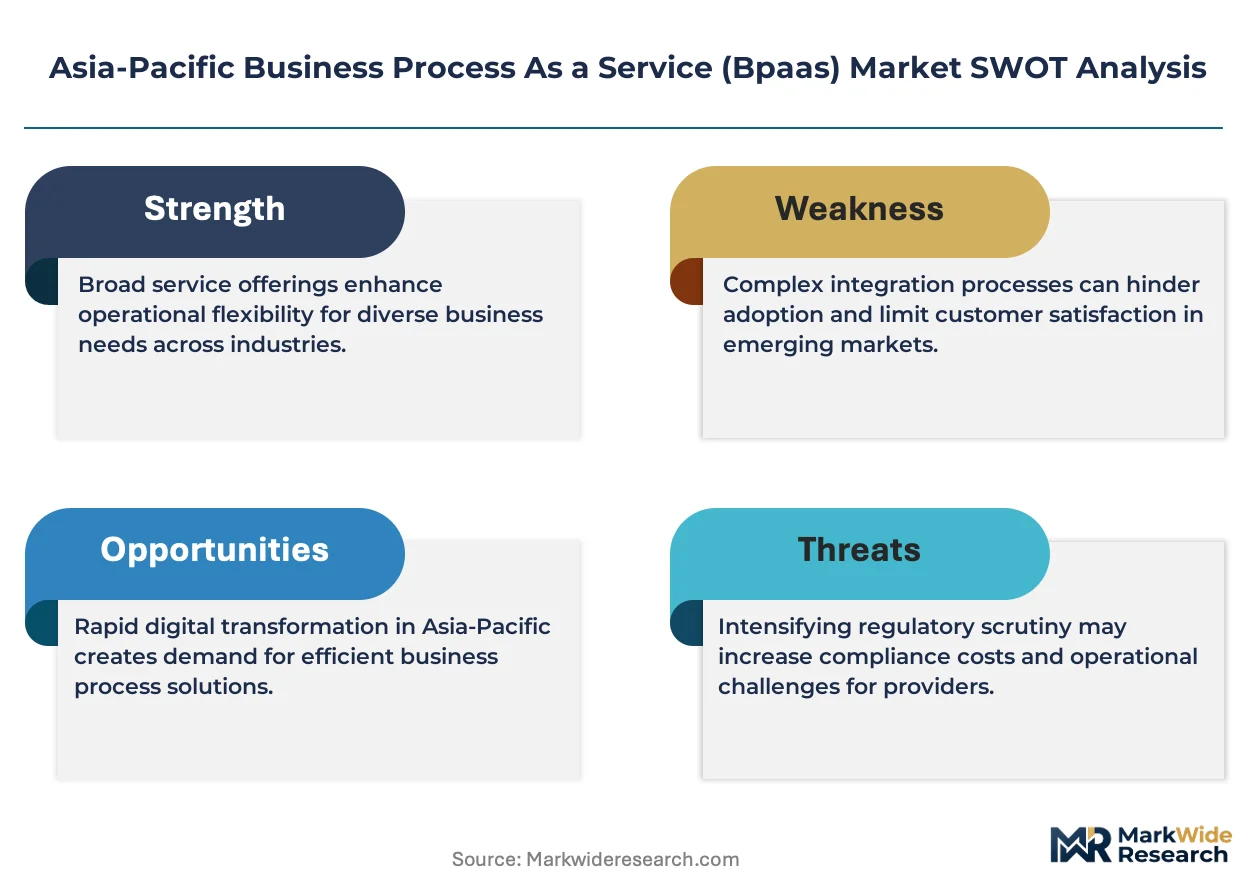
A widening capability gap in AI-augmented process automation is rotating competitive advantage toward firms with proprietary platforms. Accenture PLC leverages its pre-built industry vertical solutions to anchor premium engagements across banking clients in Singapore and Sydney. Tata Consultancy Services Ltd. sustains cost leadership through its massive Bengaluru and Hyderabad delivery campuses. Fujitsu Limited differentiates via deep integration with Japanese enterprise systems and hybrid cloud orchestration tools.
Business Process As a Service (BPaaS) denotes the outsourcing of entire business functions through cloud-hosted, standardized platforms that combine workflow automation, analytics layers, and compliance modules into subscription-based delivery. These platforms typically operate on multi-tenant architectures with API-first integration to client ERP and CRM systems, enabling real-time process orchestration without on-premise infrastructure ownership. Finance Management and HR Management segments command the largest current revenue pools due to their regulatory complexity and repeatable transaction volumes. Multi-Cloud deployment is expanding fastest as large enterprises in Australia and Japan seek to avoid single-vendor lock-in while meeting data residency requirements. Customer Support services retain thinner margins but scale rapidly through AI-assisted chatbot layers and voice analytics.
India's TRAI data localization advisories and the RBI's cloud outsourcing guidelines shape how financial services BPaaS providers architect their infrastructure. Japan's METI cybersecurity frameworks for critical infrastructure operators impose additional compliance layers on IT Services and Customer Support contracts. Australia's Privacy Act and Notifiable Data Breaches scheme influence hybrid cloud adoption patterns across healthcare and retail verticals. Stakeholders must weigh delivery location diversification against the operational complexity of fragmented regulatory compliance across the region.
Market Dynamics
AI-augmented process automation is fragmenting traditional service delivery models across Asia-Pacific banking and financial services, forcing providers to reconstitute their value propositions around proprietary platforms rather than labor arbitrage alone.
Growth Catalysts
- India's PLI scheme for IT and BPM services:The production-linked incentive framework accelerates delivery campus buildout in Bengaluru and Hyderabad, expanding service capacity for financial institutions seeking cloud-hosted HR and finance functions.
- Multi-Cloud deployment architectures:Large enterprises in Australia and Japan demand API-first integration across hybrid environments to satisfy data residency requirements while avoiding vendor lock-in.
- Japanese enterprise system integration:Deep embedding with legacy ERP infrastructure creates sticky relationships in Tokyo and Osaka, particularly among manufacturing conglomerates migrating finance operations to subscription platforms.
Market Restraints
- Data localization mandates:India's TRAI advisories and RBI cloud outsourcing guidelines impose infrastructure duplication costs, fragmenting architecture decisions for financial services providers.
- Delivery hub concentration:Over-reliance on India and the Philippines creates geographic risk exposure, with limited immediate alternatives matching scale and English-language capability depth.
- AI talent scarcity:Shortage of machine learning engineers with process domain expertise inflates compensation costs in Singapore and Sydney, compressing margins on automation-heavy engagements.
Strategic Opportunities
- Vietnam and Indonesia emergence:Alternative delivery locations gain traction as Japanese and Korean clients seek linguistic alignment and cost structures below established hubs.
- Healthcare vertical expansion:Australia's Privacy Act and Notifiable Data Breaches scheme create compliance complexity that specialized BPaaS platforms can monetize through embedded security modules.
- Voice analytics convergence:Integration of natural language processing with real-time transcription opens premium pricing for customer support contracts in Australian retail banking.
Industry Challenges
- Legacy ERP integration complexity:Japanese enterprises operate decades-old customized systems that resist standard API connections, extending implementation timelines and eroding subscription economics.
- Cybersecurity certification delays:METI frameworks for critical infrastructure operators impose multi-stage approval processes that stall contract execution with energy and utilities clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Business Process As a Service (Bpaas) Market |
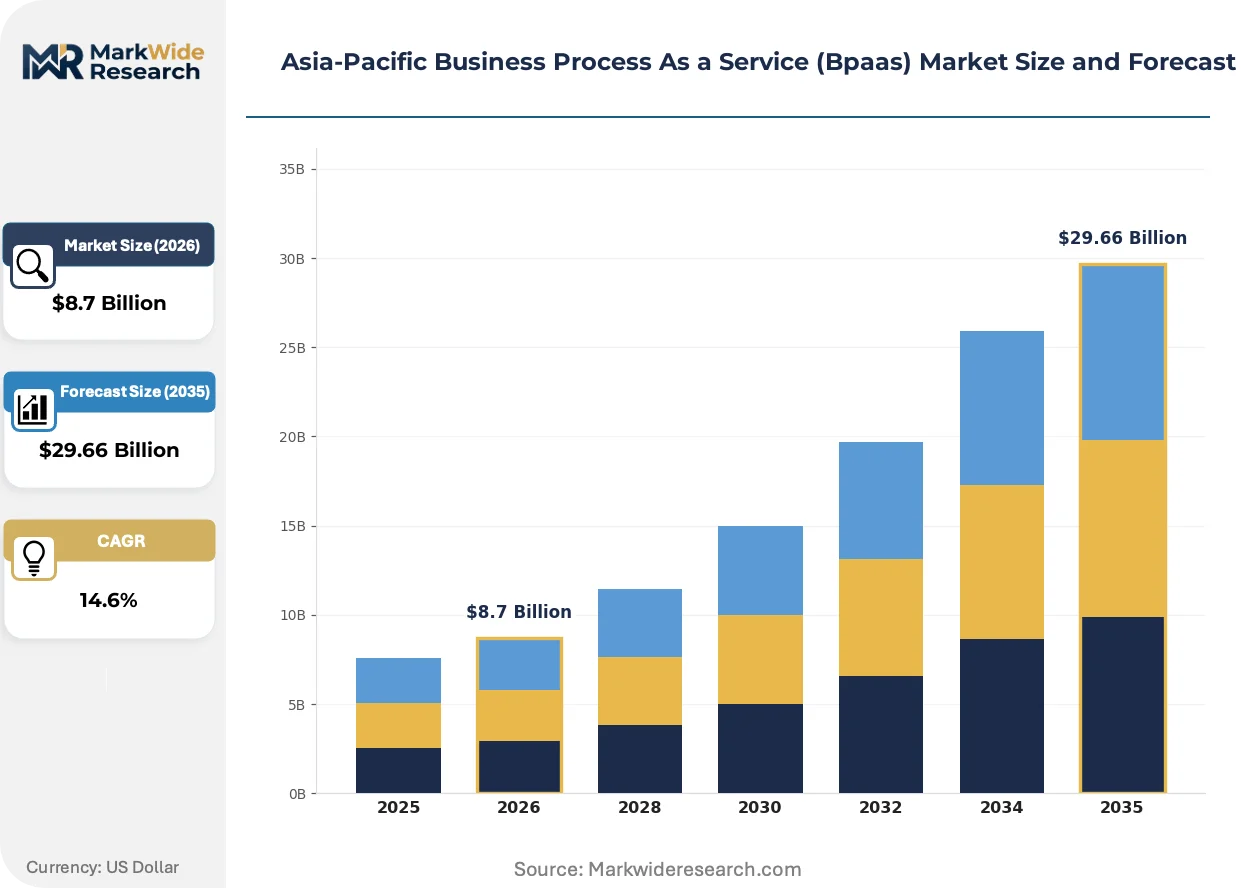
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Finance Management, HR Management, IT Services, Customer Support Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Industry Vertical: Healthcare, Retail, Manufacturing, Telecommunications End User: Small Enterprises, Large Enterprises, Startups, Corporates |
| Companies Covered | Accenture PLC, Cognizant Technology Solutions Corporation, HCL Technologies Ltd., NTT Data Corporation, Capgemini SE, Fujitsu Limited, IBM Corporation, Infosys Limited, Tata Consultancy Services Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Business Process As a Service (Bpaas) Market Strategic Shifts
Platform standardization is colliding with regulatory fragmentation across Asia-Pacific financial services, compelling providers to architect modular compliance layers that can be activated by jurisdiction without core system rewrites.
Generative AI is decomposing traditional process documentation and exception-handling workflows in Philippine and Indian delivery centers. Banking clients in Singapore deploy large language models for real-time contract analysis, compressing manual review cycles from days to hours. This capability shift is decomposing the traditional pyramid of junior analysts supporting senior reviewers, forcing workforce restructuring toward prompt engineering and quality assurance functions.
Australia's Privacy Act amendments and the Notifiable Data Breaches scheme are tightening consent management requirements for cloud-hosted HR platforms. Healthcare providers in Melbourne and Sydney now mandate audit-ready data lineage as a procurement precondition, not a post-contract add-on. Retail and insurance verticals are responding by embedding privacy-by-design modules into standard subscription tiers rather than offering them as premium upgrades.
Buyer concentration among Asia-Pacific banking conglomerates is compressing vendor evaluation cycles and demanding outcome-linked pricing structures. Procurement teams in Sydney and Tokyo now require proof-of-concept deployments with defined automation thresholds before full-platform commitments. This pattern is most visible in Australian superannuation funds and Japanese regional banks, where CFOs seek to transfer operational risk to providers through gain-sharing arrangements tied to headcount reduction targets.
Asia-Pacific Business Process As a Service (Bpaas) Market Segmentation
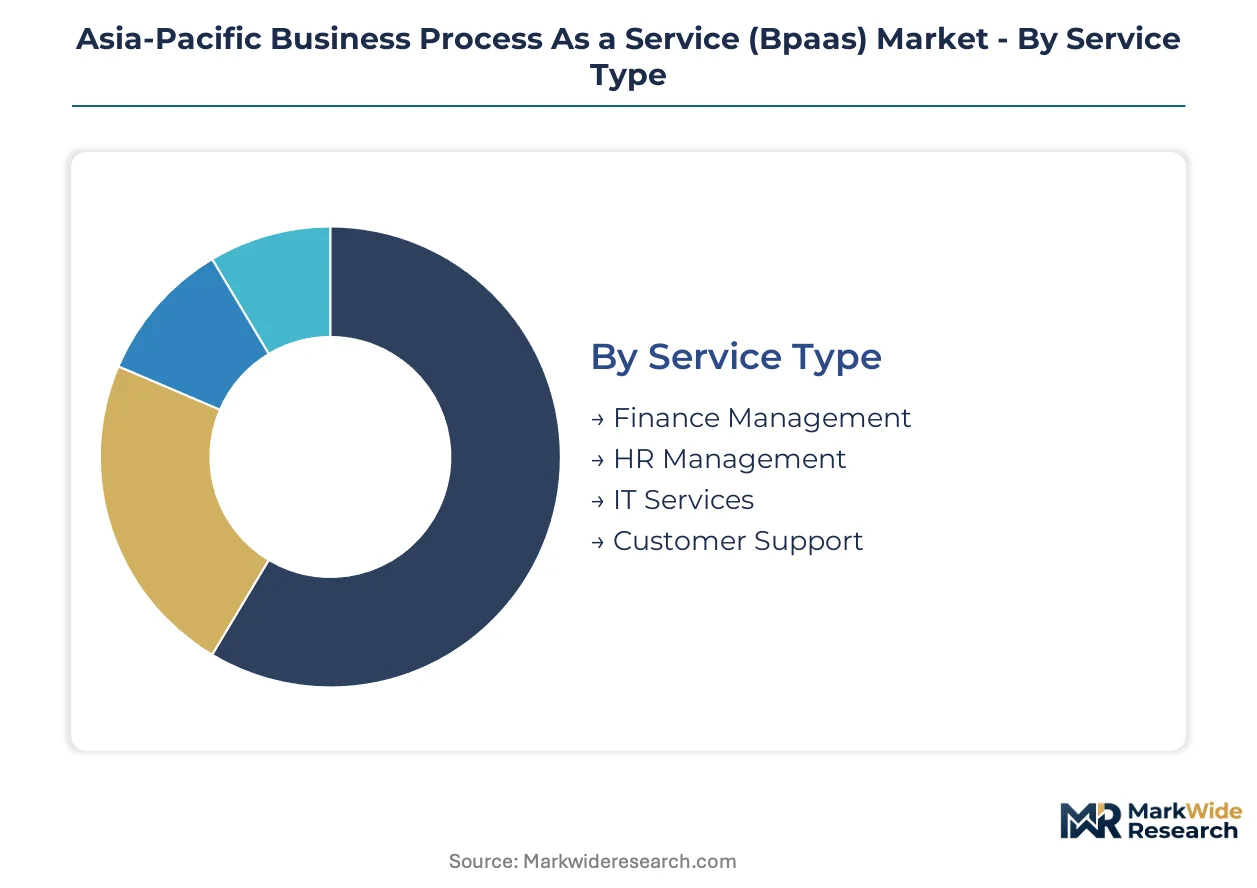
Segmentation in Asia-Pacific BPaaS reveals how delivery models and client requirements fragment across regulatory environments and legacy infrastructure maturity. Each dimension exposes distinct substitution pressures from in-house automation, captive centers, and alternative outsourcing geographies.
Service Type:
Finance Management and HR Management face the strongest substitution pressure from rapidly maturing robotic process automation tools that enterprises can deploy internally without vendor dependency.
- Finance Management:Cloud-hosted platforms consolidate accounts payable, receivable, and regulatory reporting through multi-tenant architectures with embedded compliance modules. Banking conglomerates in Sydney and Tokyo drive demand for subscription-based general ledger and tax automation that transfers operational risk to providers. Finance Management retains volume leadership; IT Services holds the steepest expansion curve.
- HR Management:Standardized payroll, benefits administration, and talent acquisition workflows operate on API-first integration with client ERP systems. Australian healthcare providers and Indian IT firms mandate audit-ready data lineage for workforce platforms under tightening privacy requirements.
- IT Services:Infrastructure monitoring, service desk operations, and cloud orchestration delivered through hybrid deployment models. Japanese manufacturing conglomerates seek deep embedding with legacy systems that resist standard API connections.
- Customer Support:AI-assisted chatbot layers and voice analytics for retail banking and telecommunications clients. Philippine delivery centers deploy generative AI for real-time transcription, though margins remain thinner than back-office functions.
Finance Management retains volume leadership; IT Services holds the steepest expansion curve.
Deployment:
Cost tier differentiation separates enterprise-grade multi-tenant solutions from single-tenant private deployments required by regulated financial institutions.
- Public Cloud:Shared infrastructure with subscription economics suited to startups and mid-market enterprises without data residency constraints. Indian IT services firms and Australian retail chains adopt public cloud HR platforms for rapid deployment timelines.
- Private Cloud:Dedicated single-tenant environments meeting RBI cloud outsourcing guidelines for Indian banks and TRAI data localization advisories. Higher operational overhead transfers to clients through premium pricing tiers.
- Hybrid Cloud:Workload distribution across on-premise legacy systems and cloud-hosted automation layers. Japanese enterprises with decades-old customized ERP infrastructure require this architecture for finance function migration.
- Multi-Cloud:API-first integration across AWS, Azure, and domestic providers to avoid vendor lock-in while satisfying Australia's Privacy Act and Japan's METI cybersecurity frameworks. Australian superannuation funds and Tokyo banking conglomerates drive fastest adoption.
Public Cloud dominates transaction volume; Multi-Cloud is climbing the fastest as regulatory fragmentation intensifies.
Industry Vertical:
Application-specific requirements create divergent procurement patterns based on compliance complexity and legacy system age.
- Healthcare:Patient billing, claims processing, and workforce management with embedded privacy-by-design modules. Melbourne and Sydney providers mandate audit-ready data lineage under Australia's Notifiable Data Breaches scheme.
- Retail:Supply chain finance, customer support, and seasonal workforce scaling through AI-assisted platforms. Australian retail banking integrates voice analytics for real-time customer interaction analysis.
- Manufacturing:Deep ERP integration for procurement and production planning workflows. Japanese conglomerates in Tokyo and Osaka operate customized legacy systems that extend implementation timelines.
- Telecommunications:High-volume customer support and billing operations with real-time process orchestration. Philippine delivery centers serve regional telcos with English-language capability depth.
Healthcare commands premium pricing; Retail scales most rapidly through standardized platform deployment.
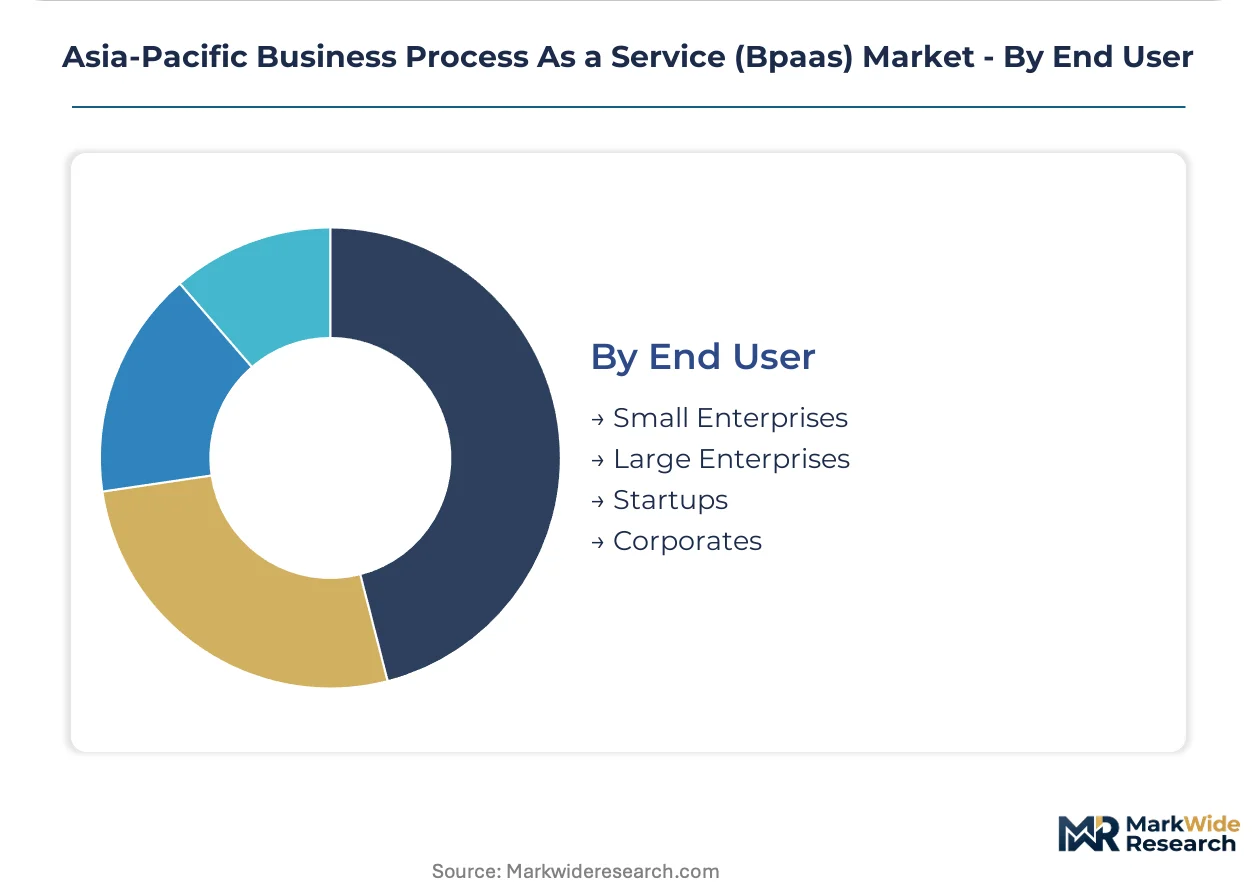
End User:
Customer type determines procurement sophistication and willingness to accept outcome-linked pricing structures.
- Small Enterprises:Standardized subscription tiers with rapid deployment and minimal customization requirements. Indian startups and Australian professional services firms adopt cloud-hosted finance platforms without dedicated IT staff.
- Large Enterprises:Complex multi-function engagements with gain-sharing arrangements tied to headcount reduction targets. Sydney superannuation funds and Tokyo regional banks demand proof-of-concept deployments before full-platform commitments.
- Startups:Flexible month-to-month contracts with API-first integration to rapidly evolving tech stacks. Bengaluru and Singapore venture-backed firms prioritize speed over customization depth.
- Corporates:Divisional rollouts across geographic footprints with centralized governance requirements. Korean and Japanese conglomerates seek linguistic alignment with delivery centers in Vietnam and Indonesia.
Large Enterprises anchor revenue concentration; Startups are gaining share fastest as platform standardization reduces deployment friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Singapore and Sydney, where banking conglomerates demand outcome-linked contracts, while Indian delivery hubs compete on cost leadership through scale-driven campus operations.
India
Bengaluru and Hyderabad delivery campuses anchor regional capacity expansion for finance and HR functions. TRAI data localization advisories and RBI cloud outsourcing guidelines force infrastructure duplication for financial services clients. The PLI scheme for IT and BPM services accelerates service delivery buildout, positioning India as the dominant cost-optimized hub.
Japan
Tokyo and Osaka manufacturing conglomerates drive demand for deep legacy ERP integration that resists standard API connections. METI cybersecurity frameworks for critical infrastructure operators impose multi-stage approval processes on IT services and customer support contracts. Hybrid cloud orchestration dominates deployment architecture as enterprises migrate finance operations to subscription platforms.
Australia
Sydney superannuation funds and Melbourne healthcare providers mandate audit-ready data lineage for cloud-hosted HR platforms. The Privacy Act and Notifiable Data Breaches scheme tighten consent management requirements, embedding privacy-by-design as a procurement precondition. Multi-cloud adoption accelerates fastest here as buyers seek to avoid vendor lock-in while satisfying data residency obligations.
Singapore
Regional banking headquarters in Singapore deploy AI-augmented contract analysis platforms, compressing manual review cycles from days to hours. Monetary Authority guidelines on technology risk management shape how providers architect cloud-hosted solutions for financial institutions. The city-state commands premium pricing through outcome-linked engagements with defined automation thresholds.
Philippines
Manila and Cebu delivery centers scale customer support operations through AI-assisted chatbot layers and voice analytics for retail banking and telecommunications clients. English-language capability depth sustains competitive positioning against emerging alternatives. Generative AI deployment for real-time transcription is decomposing traditional analyst pyramids toward prompt engineering functions.
Asia-Pacific Business Process As a Service (Bpaas) Market Competitive Environment
Concentration sits with diversified IT services conglomerates that combine proprietary platforms with massive delivery scale. The vendor base spans three tiers: global consultancies with pre-built vertical solutions, Indian-origin firms with cost-optimized campus networks, and Japanese specialists with deep legacy system integration capabilities. Strategic moves center on AI-augmented platform development and geographic diversification into Vietnam and Indonesia to reduce India-Philippines concentration risk.
Within the diversified IT services tier, Accenture PLC and Tata Consultancy Services Ltd. exemplify contrasting competitive positions—one leveraging pre-built industry vertical solutions for premium banking engagements, the other sustaining cost leadership through massive Bengaluru and Hyderabad delivery campuses. Fujitsu Limited occupies a distinct position among Japanese-origin providers, differentiated by deep embedding with domestic enterprise systems and hybrid cloud orchestration tools. These three anchors illustrate how competitive advantage is rotating from labor arbitrage toward proprietary AI-augmented platforms and regulatory-compliant architecture design.
| Leading Market Players |
|---|
| Accenture PLC |
| Cognizant Technology Solutions Corporation |
| HCL Technologies Ltd. |
| NTT Data Corporation |
| Capgemini SE |
| Fujitsu Limited |
| IBM Corporation |
| Infosys Limited |
| Tata Consultancy Services Ltd. |
| Others |
Value Chain & Pricing Dynamics
Outcome-linked contracts with gain-sharing arrangements lock in multi-year platform commitments while anchoring price visibility for Australian superannuation funds and Japanese regional banks. These structures transfer operational risk to providers through headcount reduction targets, embedding cost predictability into subscription economics across the Asia-Pacific delivery network.
Pricing Analysis
The customization-premium spread separates standard multi-tenant SaaS subscriptions from private cloud deployments with embedded compliance modules. Subscription-tiered pricing dominates, with differentiation driven by data residency certification levels and vertical integration depth in legacy ERP connectors. Cost compression in standard tiers intensifies as robotic process automation tools mature, enabling in-house deployment without vendor dependency. Small enterprises exhibit highest price sensitivity through rapid public cloud adoption, while large enterprises absorb premium tiers for audit-ready data lineage and hybrid orchestration capabilities.
Supply Chain Analysis
India and the Philippines anchor service delivery capacity, with Vietnam and Indonesia emerging as alternative production locations for Japanese and Korean linguistic alignment. The supply chain draws from cloud infrastructure providers, machine learning engineering talent pools, and specialized compliance certification bodies. Single-source vulnerability concentrates in Bengaluru and Hyderabad campus networks, where English-language capability depth lacks immediate substitutes. Distribution runs through direct enterprise sales teams and systems integrator partnerships into banking and healthcare verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market faces substitution pressure from rapidly maturing in-house robotic process automation platforms that enterprises can deploy without vendor dependency. Incumbents must architect defensive moats around proprietary AI-augmented platforms and regulatory-compliant infrastructure to preserve engagement stickiness.
For Market Incumbents: Consolidate delivery scale through campus expansion in Vietnam and Indonesia to reduce India-Philippines concentration risk. Deepen vertical integration into proprietary AI platforms with pre-built industry solutions that resist substitution by generic automation tools. Accentuate compliance module development for RBI cloud outsourcing guidelines and Australia's Privacy Act amendments to embed switching costs.
For New Entrants and Emerging Players: METI cybersecurity certification fast-tracks open contract execution pathways with Japanese critical infrastructure operators stalled by multi-stage approval processes. Target healthcare verticals in Melbourne and Sydney where audit-ready data lineage mandates create procurement preconditions unmet by incumbent platforms. Pursue voice analytics convergence for Australian retail banking as a differentiated entry angle with premium pricing potential.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with deep legacy ERP integration capabilities in Tokyo and Osaka manufacturing conglomerates. Long-term viability hinges on proprietary platform ownership rather than labor arbitrage positioning. Watch for inflection signals in generative AI deployment velocity across Philippine delivery centers, where workforce restructuring toward prompt engineering functions indicates capability transition maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary AI Platform Development | Accenture's pre-built vertical solutions anchor premium banking engagements in Singapore and Sydney. |
| Geographic Delivery Diversification | Vietnam and Indonesia campuses reduce exposure to India-Philippines hub concentration for Japanese clients. |
| Compliance Module Embedding | Privacy-by-design tiers satisfy Australia's Notifiable Data Breaches scheme without premium upgrade friction. |
| Legacy ERP Integration Depth | Fujitsu's hybrid cloud orchestration penetrates decades-old Japanese manufacturing systems resistant to standard APIs. |
| Outcome-Linked Contract Structuring | Gain-sharing arrangements with Sydney superannuation funds transfer operational risk through defined automation thresholds. |
Study Parameters
Two parallel data streams informed the analysis: structured conversations with CTOs, IT procurement officers, platform engineers, and integration specialists across banking and healthcare verticals; and secondary validation through RBI cloud outsourcing guidelines, TRAI data localization advisories, METI cybersecurity frameworks, and SEC filings from diversified IT services conglomerates. Bottom-up service line estimates triangulated against top-down regional demand projections.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning deployment architecture, service type, industry vertical, and end-user sophistication tier. CAGRs were derived from capacity expansion trajectories under India's PLI scheme and automation adoption velocity in Australian financial services. Forecast inputs incorporated delivery campus buildout timelines and generative AI workforce restructuring patterns.
Underlying assumptions cover sustained regulatory fragmentation across data residency requirements, with deviation risk concentrated in accelerated in-house automation adoption or abrupt talent pool migration from established hubs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Business Processing Outsourcing Market
Business Process Outsourcing (BPO)
Contact Center Outsourcing Market
Business Process Outsourcing (BPO)
North America Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Global Insurance Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Call Center Outsourcing Market
Business Process Outsourcing (BPO)
Direct to Customer Outsourced Fulfillment Market
Business Process Outsourcing (BPO)
North America Business Process-As-A-Service (Bpaas) Market
Business Process Outsourcing (BPO)
Business Process As a Service (Bpaas) Market
Business Process Outsourcing (BPO)
Global Knowledge Process Outsourcing Market
Business Process Outsourcing (BPO)
Asia-Pacific Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Global Application Outsourcing Market
Business Process Outsourcing (BPO)
Business Process Automation (BPA) Market
Business Process Outsourcing (BPO)
Middle East and Africa Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Customer Relationship Management (CRM) Outsourcing Market
Business Process Outsourcing (BPO)
Payroll Outsourcing Services Market
Business Process Outsourcing (BPO)
Global Document Outsourcing Market