
 Global Social Media Market | 2026-2036
Global Social Media Market Size, Share, and Industry Trends Forecast 2026-2036
Global Social Media Market Foresight
Buyer concentration among advertisers is restructuring as small and medium enterprises fragment across self-serve ad tools while large consumer brands consolidate spending with top-tier platforms. Facebook leverages its dual-app ecosystem to sustain cross-platform attribution dominance. TikTok competes through short-form video formats that anchor Gen Z engagement patterns.
Social media encompasses internet-based communication ecosystems enabling user-generated content exchange, real-time interaction, and algorithmic content curation across fixed and mobile networks. These platforms function as digital infrastructure for attention aggregation, converting user engagement into addressable advertising inventory and transactional commerce pathways. The advertising revenue model dominates value capture, though subscription tiers and sponsored content formats are expanding margin pools. Messaging apps and media sharing platforms are gaining structural importance as private communication supplants public feeds in user time allocation. Social networking retains the largest user base but faces maturity pressure in North American and Western European markets.
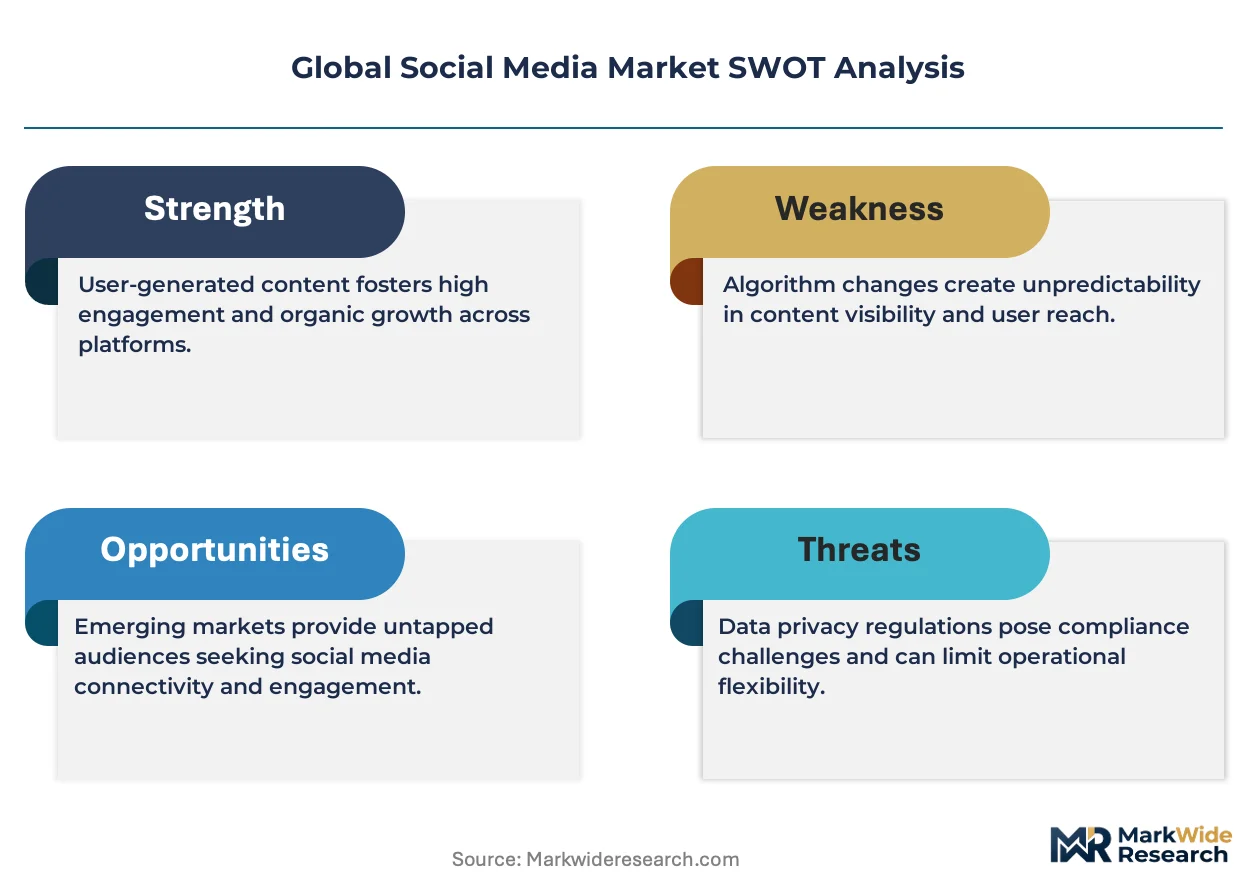
The EU AI Act, GDPR, and CSRD collectively impose algorithmic audit obligations and data processing constraints that elevate compliance costs for platforms operating across European jurisdictions. The US FTC and FCC maintain separate enforcement tracks on deceptive advertising and telecommunications infrastructure, creating a multi-regulator compliance landscape. Stakeholders must monitor emerging interoperability mandates and content liability frameworks that could force architectural changes to platform business models.
Market Dynamics
Algorithmic transparency mandates from the EU AI Act and GDPR enforcement are forcing platforms to reengineer content curation systems, elevating compliance costs while fragmenting advertiser confidence across jurisdictions.
Growth Catalysts
- Self-serve advertising tools:Small and medium enterprises are migrating budgets from traditional channels to targeted social campaigns, expanding addressable advertiser pools without direct sales overhead.
- GDPR enforcement evolution:Stricter data processing requirements are accelerating first-party data infrastructure investments, creating competitive moats for compliant platforms.
- Mobile internet penetration:India and Brazil are experiencing rapid connectivity expansion among youthful demographics, concentrating new user acquisition in high-engagement markets.
Market Restraints
- Cross-border data transfer friction:GDPR adequacy decisions and Schrems II rulings are complicating transatlantic data flows for US-headquartered platforms.
- Algorithmic audit costs:EU AI Act conformity assessments impose recurring compliance expenditures that compress margins for mid-tier platforms.
- Attention fragmentation:Messaging apps and private communication channels are displacing public feed engagement, reducing monetizable inventory per user hour.
Strategic Opportunities
- Commerce integration:Social platforms are absorbing transactional functionality, enabling direct purchase pathways that capture margin from e-commerce intermediaries.
- Brazilian market expansion:Underpenetrated SME advertiser segments in São Paulo and Rio de Janeiro offer self-serve tool penetration upside.
- Subscription tier diversification:Ad-free and creator-monetization offerings are creating revenue streams insulated from programmatic advertising volatility.
Industry Challenges
- Content moderation workforce scaling:Multi-language trust and safety operations require specialized labor pools that concentrate operational risk in Southeast Asian outsourcing hubs.
- Legacy system interoperability:Interoperability mandates under the Digital Markets Act are forcing architectural modifications to messaging protocols and data portability frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Social Media Market |
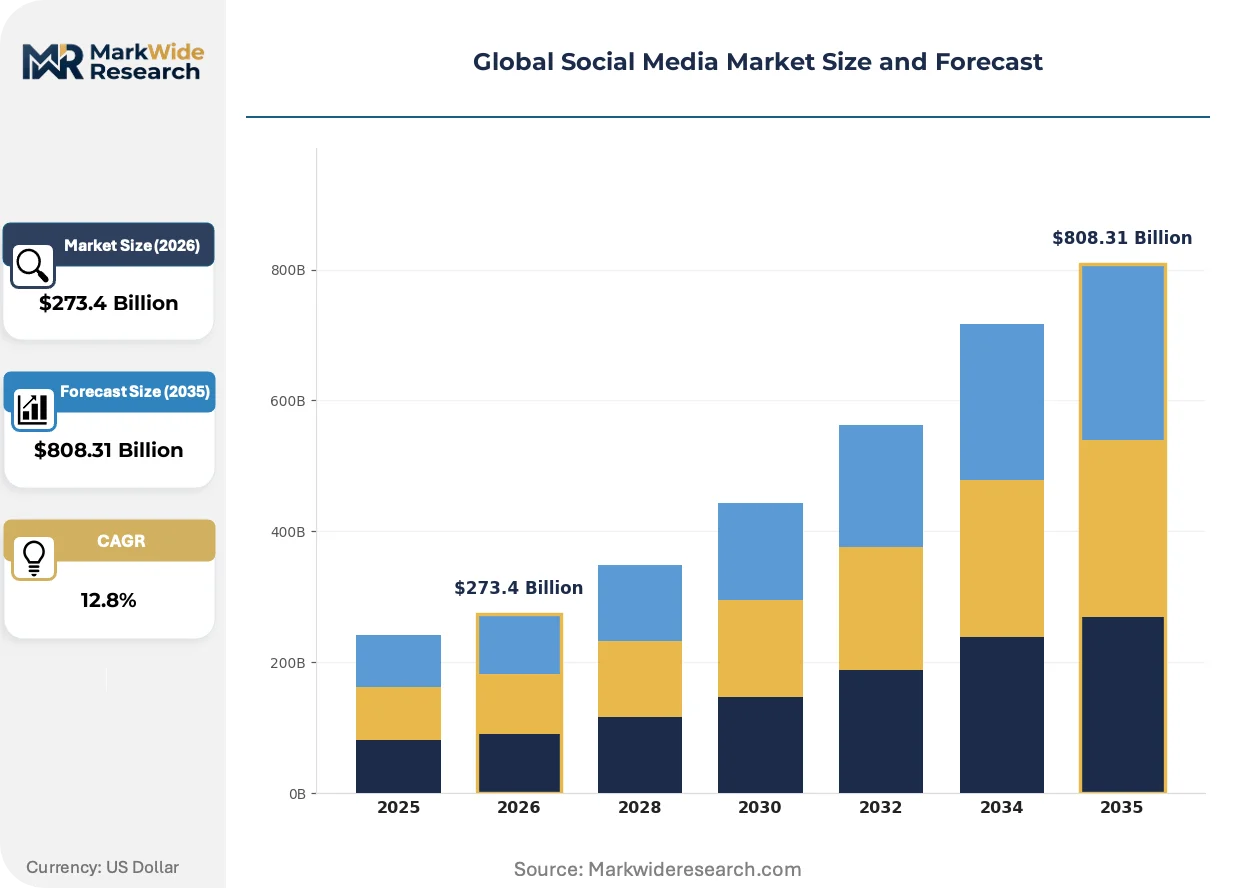
| Market Size in 2026 | $273.4 Billion |
| Market Size in 2035 | $808.31 Billion |
| CAGR (2026 – 2036) | 12.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Social Networking, Microblogging, Media Sharing, Discussion Forums, Messaging Apps User Age Group: Teens, Young Adults, Adults, Middle Aged, Seniors Revenue Model: Advertising, Subscription, Freemium, Affiliate Marketing, Sponsored Content User Purpose: Networking, Entertainment, Information Sharing, Business Promotion, Community Building |
| Companies Covered | Facebook, YouTube, Instagram, WhatsApp, TikTok, WeChat, Twitter, Telegram, Snapchat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Social Media Market Shifts & Advancements
Short-form video formats are compressing content consumption patterns while regulatory pressure on algorithmic systems is accelerating transparency tooling investments across major platforms.
Generative AI content creation tools are absorbing creative production workflows for advertiser segments with limited in-house design resources. Small and medium enterprises are adopting these capabilities at accelerating velocity, reducing dependency on agency intermediaries. This compression of creative production costs is absorbing margin from traditional advertising services and enabling higher campaign frequency at fixed budgets.
The EU AI Act's risk-based classification system is imposing documentation and human oversight requirements on algorithmic recommendation engines. Platforms operating across European jurisdictions must maintain audit trails for content ranking decisions and provide user-facing explanations for automated curation. High-risk system providers are responding by restructuring product development cycles to embed compliance checkpoints earlier in the design process.
First-party data strategies are supplanting third-party cookie dependency as browsers deprecate cross-site tracking capabilities. Advertisers are restructuring audience targeting around authenticated user relationships and platform-native identity graphs. This behavioral pivot is most visible in North American markets where Safari and Firefox restrictions have already compressed addressable audiences, forcing budget reallocation toward logged-in environments.
Global Social Media Market Segmentation
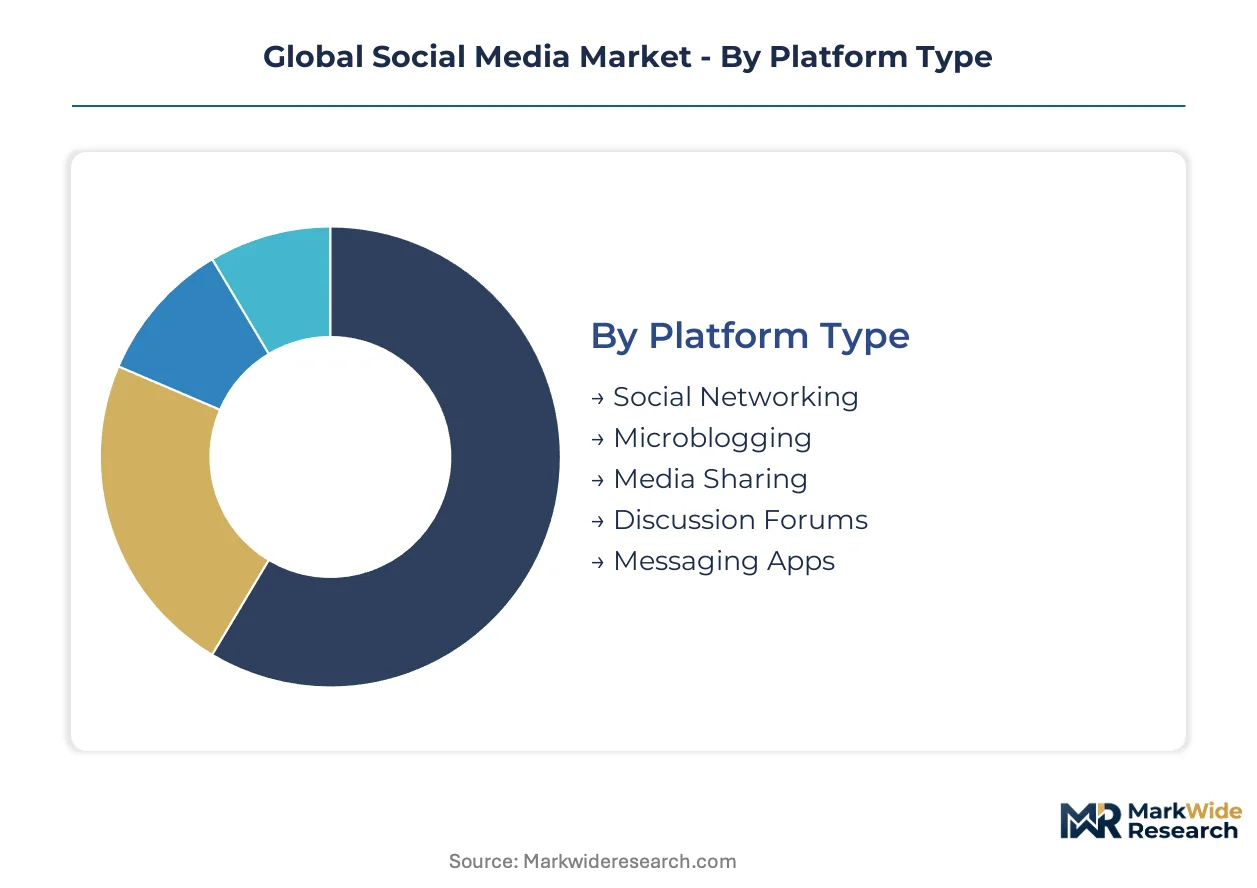
Platform architecture and user demographics determine monetization pathways in social media. Revenue model diversity and purpose-driven engagement patterns further stratify competitive positioning across the ecosystem.
Platform Type:
GDPR and EU AI Act compliance obligations vary sharply by platform architecture, with algorithmic recommendation engines facing the heaviest audit burdens.
- Social Networking:Profile-based connection systems enabling persistent identity and relationship mapping. Demand concentrates among advertisers in India and Brazil seeking authenticated audience reach, constrained by first-party data infrastructure investments forced by browser cookie deprecation.
- Messaging Apps:Private communication channels with end-to-end encryption protocols. Growth accelerates in Southeast Asian markets where WhatsApp and LINE dominate commercial messaging, though Digital Markets Act interoperability mandates threaten platform control over messaging protocols.
- Microblogging:Short-form public broadcast systems organized around follower graphs and real-time feeds.
- Media Sharing:Visual and video content repositories with algorithmic distribution.
- Discussion Forums:Topic-threaded community spaces with nested comment hierarchies.
Leading the category by volume: Social Networking. Growing fastest: Messaging Apps.
User Age Group:
Advertiser spending power and platform design priorities segment sharply across generational cohorts, with regulatory attention intensifying on teen user protections.
- Young Adults:Users aged 18-34 with peak platform engagement hours and highest commercial intent signals. Demand concentrates in short-form video consumption patterns, driven by TikTok's algorithmic curation dominance and Instagram Reels competitive response.
- Teens:Users under 18 subject to heightened GDPR and emerging national age-verification mandates. Regulatory pressure from the US FTC and UK Ofcom is forcing parental control infrastructure investments, constraining ad targeting precision for this cohort.
- Adults:Users aged 35-54 with established purchasing power and professional networking needs.
- Middle Aged:Users aged 55-64 increasingly adopting platforms for family connectivity.
- Seniors:Users 65+ representing emerging market penetration opportunities with simplified interface requirements.
Young Adults command the highest advertiser CPMs. Teens face the steepest regulatory headwinds.
Revenue Model:
Margin structure and volatility exposure diverge fundamentally between advertising-dependent and subscription-insulated revenue streams.
- Advertising:Programmatic and direct-sold inventory converting attention into impressions. Revenue concentrates with Meta and Google in North American and Western European markets, pressured by GDPR consent requirements and Safari's Intelligent Tracking Prevention.
- Subscription:Recurring fees for ad-free experiences or premium feature tiers. Growth accelerates in markets with high disposable income and privacy-conscious user bases, driven by YouTube Premium and X Premium competitive positioning.
- Freemium:Tiered access models with basic free and enhanced paid tiers.
- Affiliate Marketing:Performance-based commerce referral commissions.
- Sponsored Content:Native advertising integrated into creator-produced material.
Advertising retains volume dominance. Subscription is climbing the fastest as platforms seek revenue diversification.
User Purpose:
Engagement depth and monetization conversion rates map directly to stated user intent, with commercial purpose segments commanding premium advertiser pricing.
- Business Promotion:Professional profile cultivation, lead generation, and B2B relationship development. Demand concentrates among SME advertisers in Brazil and India migrating from traditional channels, enabled by self-serve ad tools reducing agency dependency.
- Entertainment:Passive content consumption and algorithmic discovery. Engagement hours peak in short-form video formats, driven by TikTok's recommendation engine and YouTube Shorts competitive response, though attention fragmentation into private channels constrains public feed monetization.
- Networking:Personal and professional relationship maintenance.
- Information Sharing:News dissemination and real-time event commentary.
- Community Building:Niche interest group formation and moderation.
Business Promotion delivers the highest revenue per user hour. Entertainment captures the greatest total engagement volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India and Brazil concentrate new user acquisition as youthful demographics and expanding mobile internet penetration reshape advertiser budget allocation across emerging markets.
United States
Self-serve advertising tools attract SME migration from traditional channels while the FTC maintains separate enforcement tracks on deceptive advertising. California's tech clusters in Silicon Valley and Los Angeles anchor platform headquarters concentration and creator economy infrastructure development.
Germany
GDPR enforcement evolution accelerates first-party data infrastructure investments among privacy-conscious advertisers. The EU AI Act imposes algorithmic audit obligations that elevate compliance costs for platforms operating across European jurisdictions. Berlin and Munich host emerging trust and safety operations serving continental markets.
India
Rapid mobile internet expansion among 18-34 year olds concentrates demand in short-form video consumption patterns. TRAI regulations on data localization influence platform infrastructure placement decisions. Mumbai and Bangalore clusters attract platform investment in regional content moderation and creator monetization programs.
Brazil
Underpenetrated SME advertiser segments in São Paulo and Rio de Janeiro drive self-serve tool penetration upside. ANVISA and national data protection frameworks shape platform operational requirements. São Paulo anchors Latin American headquarters concentration for major platforms seeking regional scale.
United Kingdom
Ofcom regulatory pressure on teen user protections forces parental control infrastructure investments constraining ad targeting precision. GDPR adequacy decisions maintain transatlantic data flow pathways for US-headquartered platforms. London clusters concentrate European advertising technology development and platform sales operations.
Global Social Media Market Competitive Landscape
US-based platforms anchor one tier with dual-app ecosystems and cross-platform attribution dominance; Chinese specialists hold scale positions in integrated messaging-commerce super-apps. The vendor structure concentrates around three to five global platforms commanding majority advertising revenue share, with mid-tier regional players fragmenting across niche formats. Strategic archetypes include ecosystem consolidators, short-form video specialists, and messaging-first platforms. Competitive moves center on commerce integration absorbing transactional functionality and subscription tier diversification insulating revenue from programmatic volatility.
Among US-based platforms, Meta Platforms Inc., ByteDance Ltd., and Snap Inc. occupy distinct positioning archetypes. Meta exemplifies the ecosystem consolidator model through cross-platform identity graphs. ByteDance anchors short-form video algorithmic curation dominance. Snap represents the messaging-origin platform pivoting toward augmented reality and creator monetization infrastructure. Each occupies a tier defined by audience scale, advertiser tool sophistication, and geographic penetration depth rather than interchangeable feature competition.
| Leading Market Players |
|---|
| YouTube |
| TikTok |
| Telegram |
| Snapchat |
| Others |
Supply & Pricing Matrix
Trust and safety workforce concentration in Southeast Asian outsourcing hubs compresses operational labor costs, widening spreads between premium enterprise advertising tiers and self-serve economy tiers as platforms pass through compliance expenditure differentials.
Pricing Analysis
Volume concentrates in programmatic advertising auctions while margins accrue to subscription tiers and creator monetization tools. Three-tier pricing structure across premium managed-service accounts, standard self-serve dashboards, and economy automated-bidding tiers reflects advertiser sophistication and campaign scale. Pricing pressure stems from SME budget fragmentation across multiple platforms, forcing CPM compression in mid-market segments. SME advertisers exhibit highest price sensitivity, while large consumer brands accept premium rates for cross-platform attribution guarantees.
Supply Chain Analysis
Content moderation workforce availability in the Philippines, India, and Malaysia anchors operational cost structures for trust and safety functions. Cloud infrastructure draws from hyperscaler data centers in the United States, Ireland, and Singapore, with GPU compute for recommendation engines resting on NVIDIA supply allocations. Single-source vulnerability concentrates in Taiwan semiconductor fabrication for AI training hardware. Distribution runs through direct platform interfaces and programmatic exchange integrations with agency trading desks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over first-party data infrastructure and creator monetization tools determines pricing power and advertiser retention.
For Market Incumbents: Anchor cross-platform identity graphs through authentication requirements that deepen logged-in user bases, insulating against browser cookie deprecation. Fortify first-party data moats via GDPR-compliant consent frameworks that exceed minimum regulatory thresholds, raising rival compliance costs. Prioritize backward integration into creator monetization infrastructure to capture margin from agency intermediaries and reduce advertiser churn.
For New Entrants and Emerging Players: Capture underpenetrated SME advertiser segments in São Paulo and Rio de Janeiro through localized self-serve tools with Portuguese-language creative templates and payment flexibility. Exploit messaging-commerce integration white space in Southeast Asian markets where WhatsApp and LINE commerce functionality remains fragmented. Deploy influencer-native acquisition strategies that leverage creator credibility to bypass incumbent brand-safety barriers.
For Investors and Strategic Acquirers: The window for entry favors platforms with authenticated user bases and regional content moderation capabilities that meet EU AI Act audit requirements. Long-term viability hinges on commerce integration depth and subscription revenue diversification insulating against programmatic volatility. Monitor Digital Markets Act interoperability mandate implementation timelines as inflection indicators for messaging protocol control valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| First-Party Data Infrastructure Buildout | GDPR-compliant identity graphs reduce third-party cookie dependency and raise rival compliance barriers. |
| Creator Monetization Platform Launch | Direct tipping and subscription tools capture margin from Patreon and agency intermediaries. |
| Commerce Integration Expansion | In-app checkout absorbs transactional functionality from Shopify and Amazon storefronts. |
| Regional Trust and Safety Hub Establishment | Berlin and Mumbai clusters satisfy EU AI Act audit proximity requirements and Indian data localization. |
| Subscription Tier Diversification | Ad-free and creator-support offerings insulate revenue from programmatic advertising cyclicality. |
Research Methodology
Multi-period observation of advertiser budget allocation shifts and platform user engagement metrics anchored the trend analysis, supplemented by interviews with platform monetization executives, trust and safety operations directors, SME marketing managers, and programmatic trading desk leads. Secondary validation drew from SEC 10-K filings, EU regulatory impact assessments, TRAI consultation papers, and hyperscaler capex disclosures. Bottom-up segment sizing triangulated against top-down market value estimates across the analysis window.
Segment-weighting approaches distributed value estimates across platform type, user age cohort, revenue model, and geographic penetration depth. CAGRs derived from regression analysis of historical advertising expenditure patterns and projected mobile internet penetration curves. Modeling incorporated EU AI Act compliance cost assumptions and first-party data infrastructure investment trajectories as industry-specific forecast inputs throughout the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory interoperability mandates and attention fragmentation into private messaging channels. Assumptions reflect current enforcement trajectories for GDPR and EU AI Act obligations. Material deviation in Digital Markets Act implementation timelines or Schrems II data transfer rulings warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Social Media and Influencer Economy
Social Media Content Creation Market
Social Media and Influencer Economy
Online Virtual Youtuber Model Market
Social Media and Influencer Economy
Global Influencer Market
Social Media and Influencer Economy
Global Blogging Platforms Market
Social Media and Influencer Economy
Virtual Influencer Market
Social Media and Influencer Economy
User Generated Content Platform Market
Social Media and Influencer Economy
Metaverse Social Media Platforms Market
Social Media and Influencer Economy
LAMEA User Generated Content Platform Market
Social Media and Influencer Economy
Influencer Marketing Market
Social Media and Influencer Economy
Photo Sharing Market
Social Media and Influencer Economy
Influencer Marketing Platform Market
Social Media and Influencer Economy
Virtual Content Creation Market
Social Media and Influencer Economy
Global Short Video Sharing Platform Market
Social Media and Influencer Economy
Online Love Rush Market
Social Media and Influencer Economy
Asia-Pacific User Generated Content Platform Market
Social Media and Influencer Economy
Europe User Generated Content Platform Market