
 Social Media Content Creation Market | 2026-2036
Social Media Content Creation Market Size, Share, and Industry Trends Forecast 2026-2036
Social Media Content Creation Market Analytics
India is narrowing its creator economy infrastructure gap with new studio complexes and localized platform tools. Adobe Inc. leverages its Creative Cloud ecosystem to anchor professional-grade production pipelines. Canva sustains mass-market accessibility through template-driven design automation. Fiverr International Ltd. competes by connecting freelance creators directly to brand procurement channels.
Social media content creation encompasses the production, editing, and optimization of digital assets distributed across networked platforms, typically involving resolution specifications between 1080p and 4K for video and RGB color profiles for static imagery. Its commercial purpose centers on audience engagement, brand narrative distribution, and conversion-oriented communication within platform-native formats. Video content commands the largest share of creator investment due to platform algorithmic prioritization and higher engagement retention. Strategy development services capture expanding margin pools as brands seek integrated campaign architecture rather than isolated asset production. Image-based content remains mature with slower growth but stable baseline demand across retail and hospitality verticals.
The Federal Trade Commission enforces disclosure requirements for sponsored creator content in the United States, compelling brands and influencers to maintain transparent commercial relationships. The EU AI Act imposes emerging obligations on automated content recommendation and generation tools deployed across European platforms. Platform-specific content moderation policies from Meta and ByteDance additionally shape permissible creative formats and monetization eligibility. Stakeholders must monitor evolving transparency mandates and algorithmic accountability rules to preserve market access and audience trust.
Market Dynamics
Platform algorithmic prioritization of short-form video is compressing production timelines and forcing creator tool vendors to embed real-time editing automation directly into cloud-based workflows.
Growth Catalysts
- FTC disclosure mandates:The United States Federal Trade Commission enforces transparent sponsorship labeling, compelling brands to professionalize creator partnerships and invest in compliant content management systems.
- Short-form video infrastructure:ByteDance and Meta platforms reward motion-based formats with algorithmic reach, pulling enterprise marketing budgets toward 1080p to 4K video production services.
- AI-assisted editing adoption:Machine learning tools for automated captioning, color correction, and clip sequencing are reducing post-production hours for independent creators and agency teams alike.
Market Restraints
- Compute cost volatility:Cloud rendering and AI inference workloads for video processing face pricing pressure from concentrated GPU supply chains dominated by NVIDIA and hyperscaler data centers.
- Platform dependency risk:Creator monetization eligibility and content distribution remain captive to unilateral policy changes by Meta, ByteDance, and Alphabet without recourse.
- EU AI Act compliance friction:Automated content generation and recommendation tools deployed across European platforms face emerging transparency and accountability obligations that increase development overhead.
Strategic Opportunities
- Brazilian creator economy expansion:Underpenetrated studio infrastructure and rising smartphone penetration present whitespace for localized production tool vendors and training ecosystems.
- Strategy development services:Brands are shifting procurement from isolated asset production toward integrated campaign architecture, opening margin pools for consultative creative agencies.
- 5G-enabled live production:The convergence of edge computing and low-latency mobile networks is enabling real-time collaborative editing workflows previously restricted to desktop environments.
Industry Challenges
- Cross-platform format fragmentation:Distinct aspect ratio, duration, and metadata requirements across TikTok, Instagram Reels, YouTube Shorts, and LinkedIn force redundant production pipelines.
- Creator talent scarcity:Shortage of professionals fluent in both narrative strategy and technical toolchains compresses hiring timelines for enterprise in-house studios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Social Media Content Creation Market |
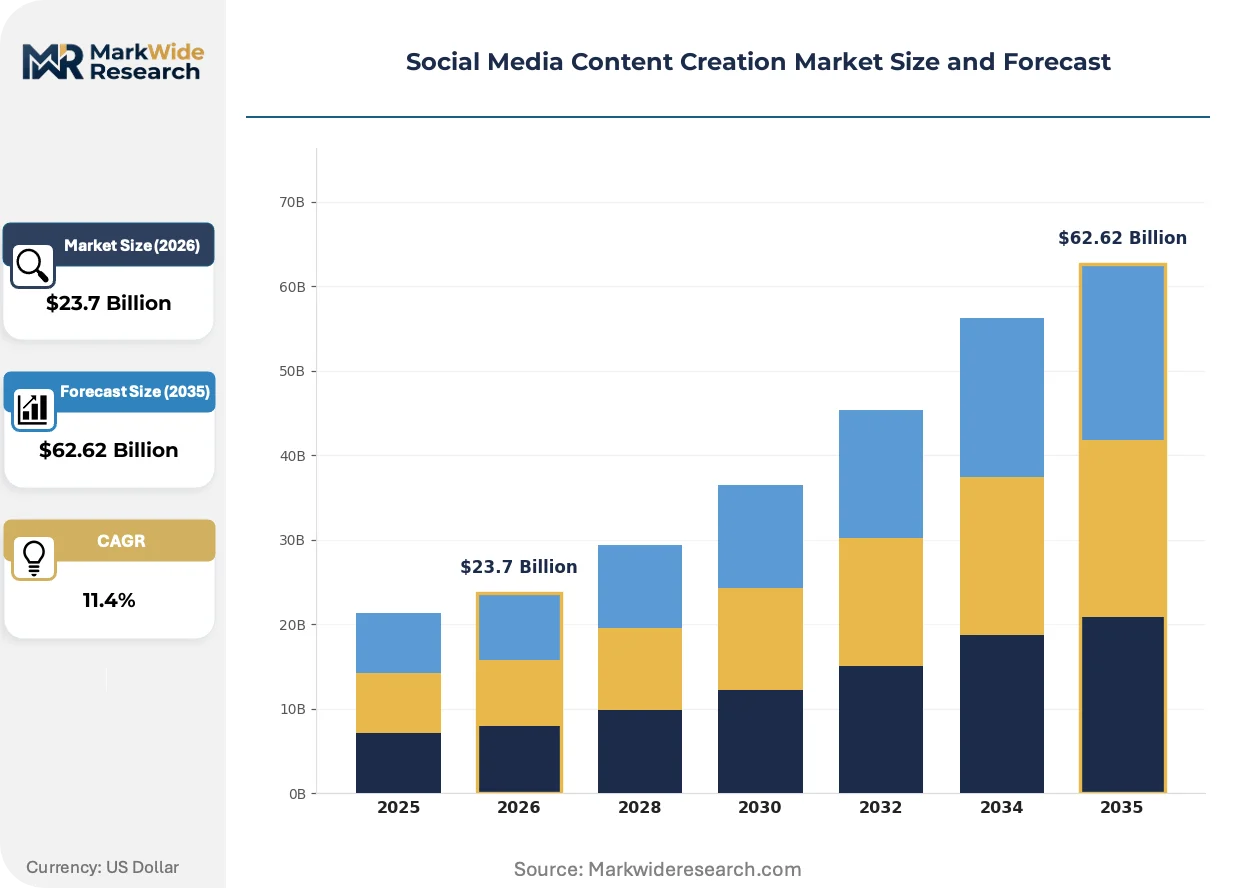
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Images, Videos, Infographics, Blogs End User: Individuals, Brands, Influencers, Agencies Platform: Instagram, Facebook, TikTok, Twitter Service Type: Editing, Strategy Development, Analytics, Management |
| Companies Covered | Adobe Inc., Canva, Fiverr International Ltd., Hootsuite, Sprout Social, Buffer Inc., Lumen5, Animoto, Vidyard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Social Media Content Creation Market Evolving Landscape
Production workflows are fragmenting across specialized tools as creators demand modularity over monolithic suites, with automation embedding at every stage from ideation to platform-native optimization.
Generative AI for video scripting and rough-cut assembly is migrating from experimental beta programs to core workflow infrastructure. Mid-sized marketing agencies and solo creators are adopting these tools weekly rather than quarterly. This compression of pre-production labor is enabling smaller teams to match output volumes previously requiring dedicated editorial departments.
The EU AI Act imposes documentation and human oversight requirements on automated content recommendation systems deployed across European platforms. Industrial consequence includes mandatory risk assessments for algorithmic curation tools that rank creator content. Video-centric social platforms operating in EU member states are responding by building audit trails and explanation interfaces into their ranking systems.
Brand procurement of creator services is consolidating around long-term retainer relationships rather than transactional per-campaign contracts. Talent agencies and managed creator marketplaces are displacing direct freelance hiring for enterprise accounts. This shift is most visible in the United States and United Kingdom, where CMOs prioritize consistent narrative continuity over viral one-off activations.
Social Media Content Creation Market Segmentation
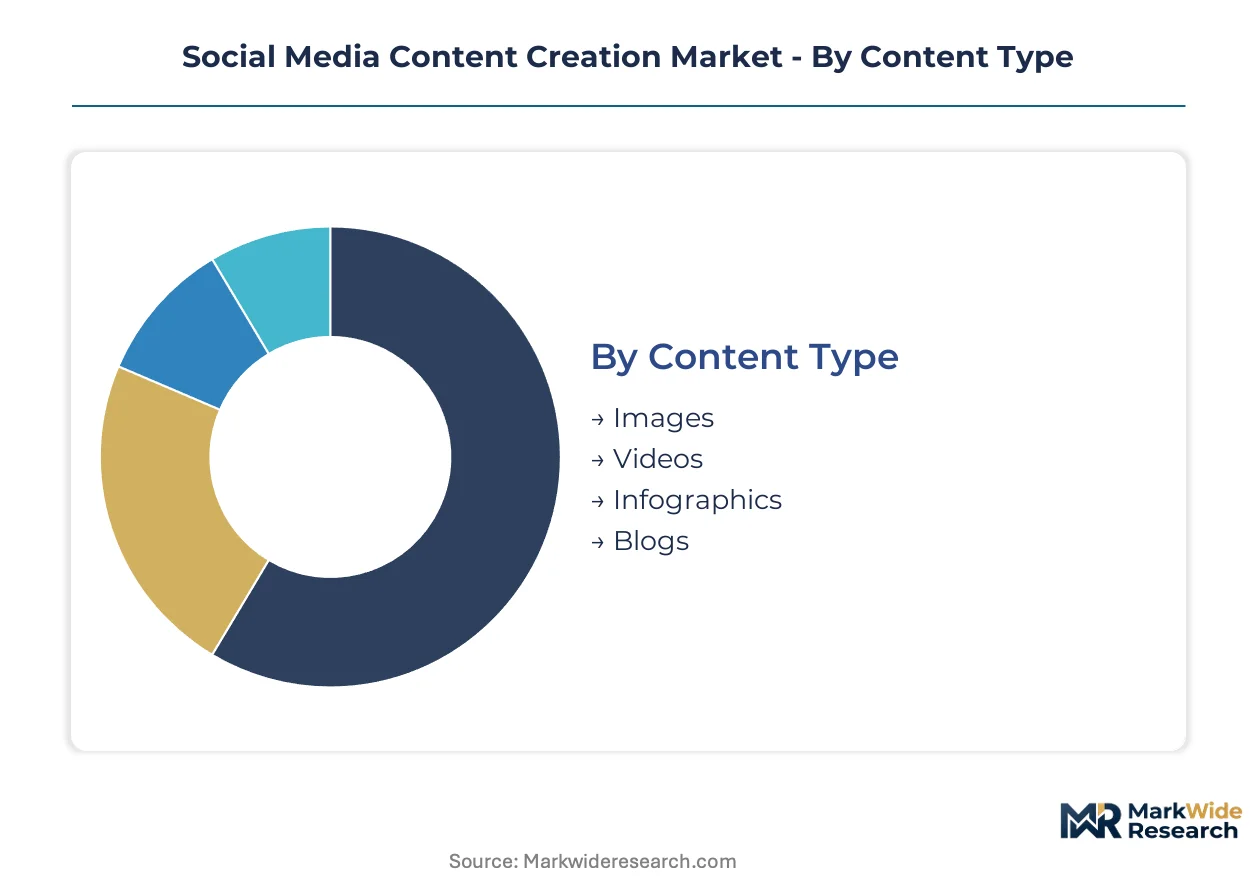
Content creation workflows fragment across specialized formats and service tiers as creators optimize for platform-native distribution. Procurement patterns diverge sharply between individual creators seeking automation tools and enterprise teams demanding integrated campaign architecture.
Content Type:
The use-case spectrum spans static brand assets to algorithm-optimized motion content, with production complexity and monetization potential varying dramatically across formats.
- Videos:Motion content produced at 1080p to 4K resolution dominates creator investment due to platform algorithmic prioritization. Enterprise marketing teams in the United States and India concentrate spending here as ByteDance and Meta platforms reward video with expanded reach.
- Images:Static assets employing RGB color profiles remain foundational for retail and hospitality verticals, though growth has flattened as budgets migrate toward motion formats. Adobe Creative Cloud and Canva compete intensely for production workflow dominance in this mature segment.
- Infographics:Data visualization formats serve B2B thought leadership and educational content distribution on LinkedIn and Twitter.
- Blogs:Long-form written content persists as SEO infrastructure and newsletter substrate, increasingly repurposed into short-form video scripts.
The dominant share belongs to Videos, while Infographics is closing the gap fastest among static formats as data storytelling gains platform traction.
End User:
Customer archetypes range from solo creators operating on thin margins to procurement-heavy enterprises with compliance obligations and retainer-based agency relationships.
- Brands:Corporate marketing departments with dedicated social budgets drive premium service demand, particularly for FTC-compliant sponsored content disclosure systems and integrated campaign architecture.
- Agencies:Creative services firms capture expanding margin pools as enterprise procurement consolidates around long-term retainer relationships rather than transactional per-campaign contracts.
- Influencers:Individual content creators with established audience monetization face platform dependency risk from unilateral policy changes by Meta and ByteDance.
- Individuals:Hobbyist and aspirational creators represent volume demand for template-driven automation tools and AI-assisted editing subscriptions.
Brands command the largest revenue concentration, though Agencies are expanding wallet share fastest as consultative creative services displace direct freelance hiring.
Platform:
Distribution channels impose distinct technical specifications and content moderation frameworks that reshape production requirements and monetization eligibility.
- TikTok:ByteDance's short-form video platform compresses production timelines with algorithmic reach rewards for 9:16 vertical format and sub-60-second duration. The EU AI Act imposes documentation requirements on its automated recommendation systems operating across European member states.
- Instagram:Meta's visual-first ecosystem spans Reels, Stories, and feed posts with fragmented aspect ratio requirements forcing redundant production pipelines. Brand procurement concentrates here for consistent narrative continuity in the United States and United Kingdom.
- Facebook:The original Meta platform retains utility for community management and older demographic targeting despite declining creator investment.
- Twitter:Text-thread and short-video hybrid formats serve real-time engagement and news-cycle responsive content with limited production infrastructure demands.
TikTok leads creator time investment, while Instagram Reels is narrowing the engagement gap through aggressive algorithmic promotion of motion content.
Service Type:
The value chain segments between executable production tasks and strategic advisory functions, with margin structure favoring consultative offerings over commoditized editing.
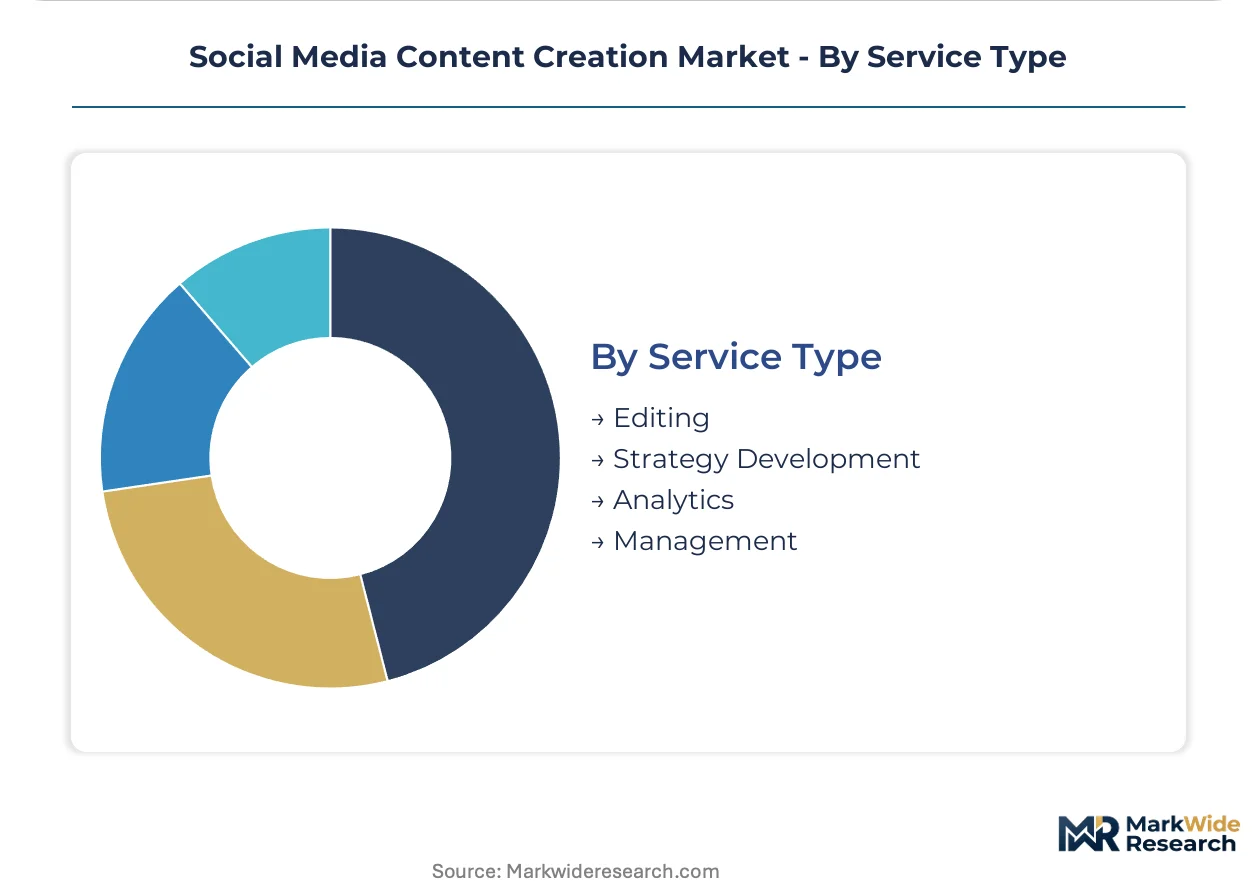
- Strategy Development:Integrated campaign architecture and narrative planning command premium pricing as brands shift procurement from isolated asset production. This segment captures expanding margin pools across the United States and United Kingdom where CMOs prioritize continuity over viral one-offs.
- Editing:Post-production labor faces compression from AI-assisted automation tools for captioning, color correction, and clip sequencing. Cloud rendering costs create pricing pressure from concentrated GPU supply chains dominated by NVIDIA.
- Analytics:Performance measurement and attribution services support optimization loops and ROI demonstration for enterprise procurement.
- Management:Community engagement, scheduling, and platform-specific optimization represent operational overhead increasingly bundled into agency retainers.
Strategy Development holds the highest margin profile, while Editing is experiencing the steepest transformation from manual labor to automated workflow infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure for video rendering clusters in the United States, India, and Brazil, while creator tool development concentrates in Silicon Valley and Bangalore. Regulatory fragmentation across FTC disclosure rules, EU AI Act obligations, and India's emerging digital content framework is reshaping vendor compliance architecture.
United States
Enterprise marketing teams in New York and Los Angeles drive premium demand for FTC-compliant content management systems and integrated campaign architecture. The Federal Trade Commission enforces transparent sponsorship labeling that compels brands to professionalize creator partnerships. Austin and Miami have emerged as secondary hubs where mid-sized agencies cluster around short-form video production pipelines.
India
Localized platform tools and new studio complexes in Mumbai and Bangalore are narrowing the creator economy infrastructure gap with Western markets. The Telecom Regulatory Authority of India shapes data localization requirements that affect cloud-based editing workflows. Hyderabad's film industry corridor is repurposing technical talent toward social-first content production at 1080p to 4K resolution specifications.
Brazil
Rising smartphone penetration and underpenetrated studio infrastructure in São Paulo present whitespace for production tool vendors and training ecosystems. ANVISA, Brazil's national health regulator, influences disclosure standards for sponsored wellness and pharmaceutical content. Rio de Janeiro's creative districts are attracting regional brand headquarters seeking Portuguese-language campaign localization.
Germany
The EU AI Act imposes documentation and human oversight requirements on automated content recommendation systems operating across European platforms. Berlin's startup ecosystem hosts specialized vendors building audit trails and explanation interfaces for algorithmic curation tools. Munich's corporate marketing sector demands consultative strategy services over commoditized editing labor.
United Kingdom
CMOs in London prioritize consistent narrative continuity over viral one-off activations, consolidating procurement around long-term agency retainers. The UK's Information Commissioner's Office enforces GDPR-aligned transparency for automated content generation tools. Manchester's media production clusters are expanding capacity for platform-native optimization across TikTok, Instagram Reels, and YouTube Shorts.
Social Media Content Creation Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in editing automation and analytics modules. The vendor base separates between full-stack creative suites and point-solution disruptors, with consolidation pressure building at the mid-market junction. Three archetypes dominate: legacy creative software incumbents with cloud migration strategies, template-driven mass-market platforms, and freelance marketplace connectors. Competitive moves center on embedding AI-assisted workflows directly into browser-based interfaces and bundling strategy advisory into production tool subscriptions.
Within the creative software tier, Adobe Inc. anchors professional-grade production pipelines through its Creative Cloud ecosystem. Canva exemplifies the mass-market accessibility archetype with template-driven design automation. Fiverr International Ltd. occupies the marketplace connector position, linking freelance creators directly to brand procurement channels. Each represents a distinct strategic vector rather than direct overlap, with specialization in resolution specifications, color profile management, or talent liquidity respectively.
| Leading Market Players |
|---|
| Adobe Inc. |
| Canva |
| Fiverr International Ltd. |
| Hootsuite |
| Sprout Social |
| Buffer Inc. |
| Lumen5 |
| Animoto |
| Vidyard |
| Others |
Value Network & Pricing Analysis
Undercapacity in Indian cloud rendering clusters is forcing enterprise marketing teams toward premium SaaS tiers, compressing margins for independent creators while concentrating pricing power with GPU-dependent vendors. This utilization squeeze simultaneously accelerates automation adoption and reshapes procurement patterns across the United States, Brazil, and European Union markets.
Pricing Analysis
FTC disclosure mandates dictate the pricing tier structure across the Social Media Content Creation Market, separating premium compliance-integrated suites from standard automation tools and economy template libraries. Price differentiation rests on certification grade for algorithmic transparency and volume scale for enterprise retainers. Cost compression in the economy tier is intensifying because GPU supply concentration limits cloud rendering affordability. Individual creators exhibit highest price sensitivity, while enterprise brands absorb premium pricing for integrated campaign architecture.
Supply Chain Analysis
Export controls on advanced GPU architectures are restricting cloud infrastructure flows from NVIDIA-dominated supply chains into Indian and Brazilian markets. Production gravity centers on the United States, India, and Brazil for video rendering capacity, with raw material dependencies spanning semiconductor wafers, specialized memory modules, and cooling systems. Single-source vulnerability from NVIDIA's data center dominance creates structural risk for AI-assisted editing vendors. Distribution runs through hyperscaler marketplaces and direct SaaS subscriptions to enterprise and individual buyer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as enterprise marketing teams consolidate procurement around long-term agency retainers, fragmenting the vendor landscape and squeezing mid-market tool providers. This consolidation rewards scale players while threatening point-solution specialists.
For Market Incumbents: Harden platform dependency resilience by diversifying across TikTok, Instagram Reels, and YouTube Shorts rather than anchoring to single-platform algorithmic reach. Invest in FTC-compliant disclosure automation to capture enterprise procurement shifting toward integrated campaign architecture. Vertical integration into cloud rendering infrastructure mitigates GPU cost volatility threatening margin profiles.
For New Entrants and Emerging Players: Brazilian studio infrastructure underpenetration presents whitespace for localized production tool vendors and training ecosystems targeting Portuguese-language campaign localization. Target mid-sized marketing agencies in São Paulo and Rio de Janeiro with modular AI-assisted editing subscriptions rather than full-suite displacement. A channel partnership with regional talent agencies accelerates brand procurement access.
For Investors and Strategic Acquirers: Capital is best deployed toward consultative strategy development services capturing expanding margin pools as CMOs prioritize narrative continuity over viral one-off activations. Long-term viability favors vendors bundling advisory functions into production tool subscriptions across the United States and United Kingdom. The signal to watch is EU AI Act enforcement intensity affecting automated recommendation system deployments.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding AI-assisted workflows directly into browser-based interfaces reduces friction for Adobe and Canva users. |
| Geographic Expansion | Localized studio complexes in Mumbai and Bangalore narrow India's creator economy infrastructure gap with Western markets. |
| Strategic Partnership | Long-term retainer relationships between talent agencies and enterprise brands displace direct freelance hiring channels. |
| Acquisition of Specialist Firm | Consultative creative agencies capturing strategy development margin pools become attractive targets for tool vendors. |
| Product Launch | 5G-enabled live production tools unlock real-time collaborative editing workflows previously restricted to desktop environments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, platform policy documentation, and trade data from the United States, India, and Brazil. Interviews with creative agency heads, enterprise CMOs, platform policy leads, and freelance content creators anchor demand-side validation. Bottom-up triangulation across content type, end user archetype, and platform-specific requirements converges with top-down macroeconomic calibration.
Forecast inputs span content format evolution, algorithmic prioritization shifts by ByteDance and Meta, AI-assisted editing adoption curves, and regional regulatory enforcement intensity across the projection horizon. Segmentation dimensions include content type, end user category, distribution platform, and service tier. CAGRs derive from modeled adoption rates and pricing trajectory assumptions. Cloud infrastructure capacity expansion and GPU supply chain dynamics inform scenario-weighted outcomes.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscaler-backed editing suites or sudden platform policy reversals would shift outcomes. Material shifts in EU AI Act enforcement, FTC disclosure mandate expansion, or NVIDIA supply allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Social Media and Influencer Economy
Social Publishing Application Market
Social Media and Influencer Economy
Asia-Pacific User Generated Content Platform Market
Social Media and Influencer Economy
Europe User Generated Content Platform Market
Social Media and Influencer Economy
Influencer Marketing Platform Market
Social Media and Influencer Economy
Virtual Influencer Market
Social Media and Influencer Economy
Content Creation Market
Social Media and Influencer Economy
Online Love Rush Market
Social Media and Influencer Economy
Virtual Content Creation Market
Social Media and Influencer Economy
User Generated Content Platform Market
Social Media and Influencer Economy
Global Blogging Platforms Market
Social Media and Influencer Economy
Global Influencer Market
Social Media and Influencer Economy
Global Social Media Market
Social Media and Influencer Economy
LAMEA User Generated Content Platform Market
Social Media and Influencer Economy
Metaverse Social Media Platforms Market
Social Media and Influencer Economy
Photo Sharing Market
Social Media and Influencer Economy
Global Short Video Sharing Platform Market