
 Europe User Generated Content Platform Market | 2026-2036
Europe User Generated Content Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Europe User Generated Content Platform Market Insights
The gap between premium enterprise suites and self-serve commodity tools is repositioning vendor strategies across Europe. Bazaarvoice sustains its foothold in large retail accounts through deep API ecosystems and managed services. Flowbox competes in the mid-market by anchoring its offering on shoppable Instagram integrations and Nordic retail density. Yotpo differentiates through loyalty-UGC bundling that extends customer lifetime value metrics for subscription brands.
A user generated content platform is a software infrastructure that aggregates, moderates, and distributes consumer-created media across commercial channels, typically processing image formats up to 4K resolution and video streams with automated rights-clearance workflows. Its primary commercial purpose is to convert authentic customer expression into searchable, commerce-embedded assets that reduce paid media dependency. Video sharing platforms capture the fastest structural expansion as short-form formats displace static imagery in conversion funnels. Advertising-based monetization still dominates revenue pools, though subscription models for creator toolkits are gaining traction among influencer-centric brands in Southern Europe.
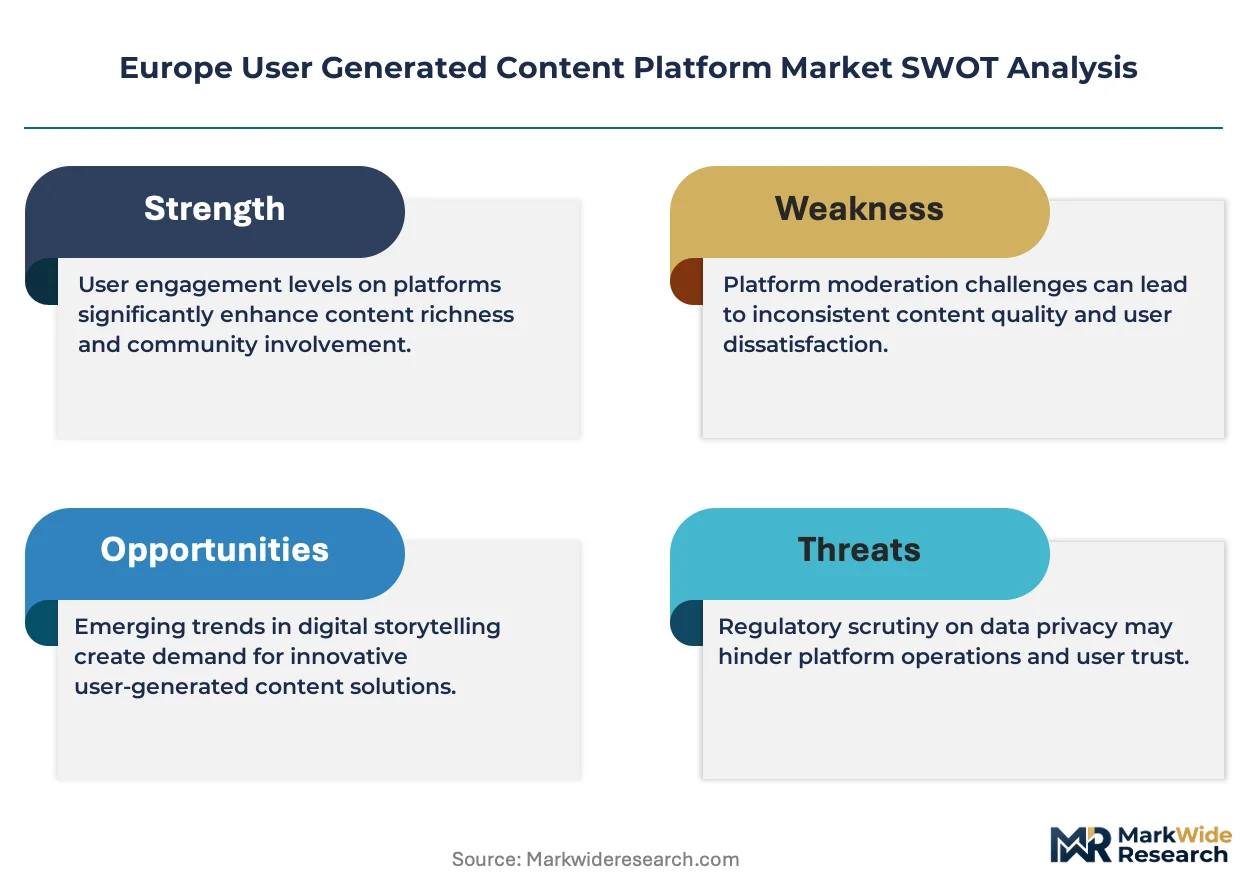
GDPR enforcement by national data protection authorities and the EU Digital Services Act's transparency mandates are tightening content provenance requirements and liability frameworks for platform operators. REACH and the EU AI Act are beginning to touch automated moderation systems, forcing disclosure of training data sources and bias testing. Stakeholders must weigh compliance investment against the speed of feature rollout as regulatory fragmentation between member states intensifies.
Market Dynamics
The EU Digital Services Act's algorithmic transparency mandates are forcing platform operators to rearchitect content moderation pipelines, while short-form video formats compress conversion funnels and displace static imagery across European retail channels.
Growth Catalysts
- Visual Commerce Integration:European e-commerce retailers deploy shoppable UGC galleries to reduce product return rates and lift basket conversion in fashion and home goods verticals.
- GDPR-Compliant Consent Frameworks:Automated rights-clearance workflows now embed granular consent capture at upload, enabling lawful commercial reuse of creator content across German and French markets.
- Creator Economy Infrastructure:Dedicated studio spaces and talent management platforms in London, Berlin, and Paris lower production barriers for micro-influencer cohorts serving D2C subscription brands.
Market Restraints
- Compute Cost Volatility:Cloud-based video transcoding and AI moderation services face input cost pressure from energy price spikes affecting Nordic and German data center operations.
- Regulatory Fragmentation Risk:Divergent national interpretations of the EU AI Act's automated decision-making disclosures create compliance complexity between French CNIL and German KBA enforcement postures.
- Static Imagery Substitution:Legacy image-based UGC repositories face displacement as TikTok and Instagram Reels formats capture advertiser budget reallocation toward motion content.
Strategic Opportunities
- Southern Europe Creator Toolkits:Spain and Italy present underpenetrated demand for subscription-based influencer analytics platforms serving mid-market fashion and tourism verticals.
- CSRD-Aligned Reporting:The EU Corporate Sustainability Reporting Directive creates procurement tailwinds for UGC platforms that document content provenance and supply chain emissions for brand ESG disclosures.
- Live Shopping Convergence:Integration of real-time streaming commerce with UGC curation tools opens new channel formats for UK and German electronics retailers targeting Gen-Z purchase behavior.
Industry Challenges
- Algorithmic Bias Auditing:Automated content moderation systems require specialized machine learning operations talent scarce in European labor markets, slowing deployment timelines for mid-tier vendors.
- Legacy CMS Integration:Enterprise retailers operating on decade-old e-commerce stacks face API compatibility friction when embedding dynamic UGC feeds into rigid page architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe User Generated Content Platform Market |
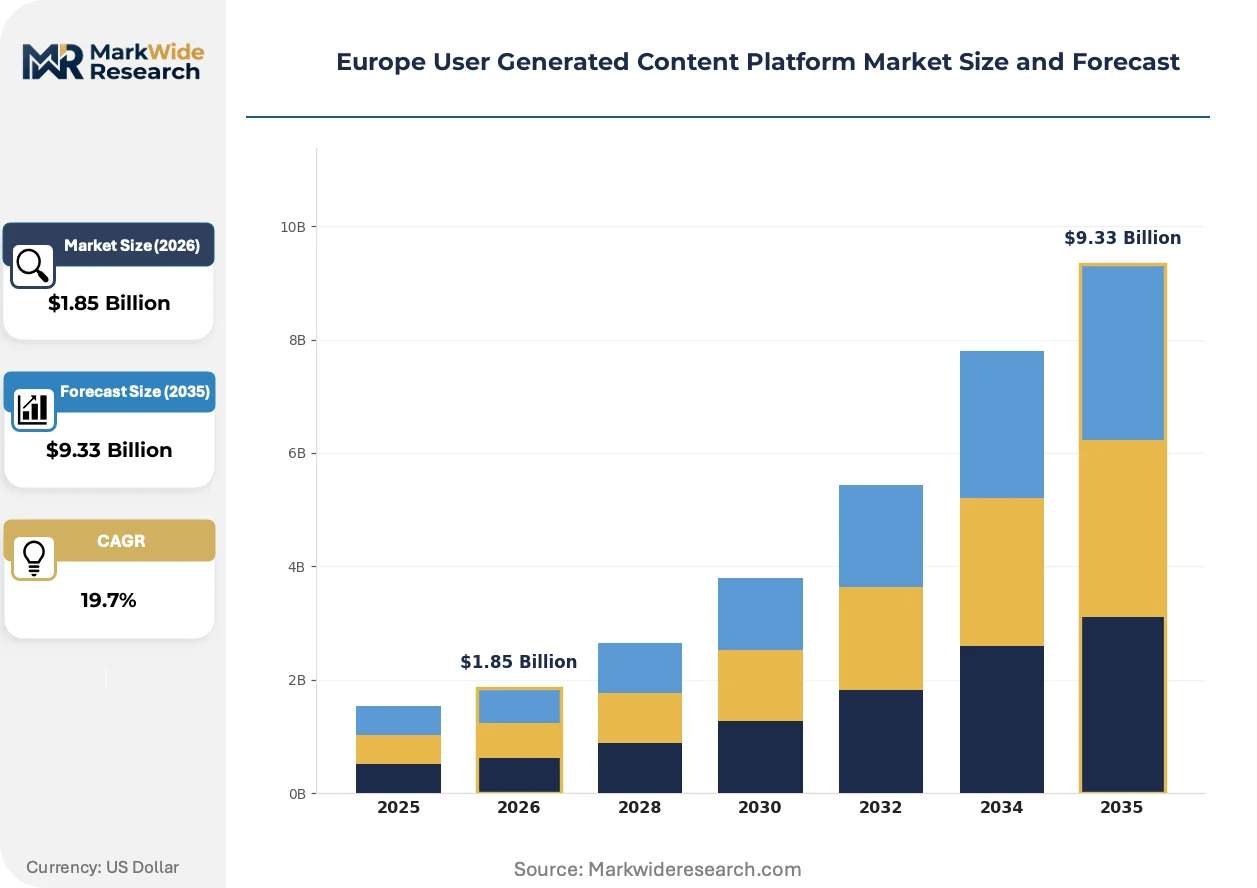
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $9.33 Billion |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Social Media, Blogging, Video Sharing, Review Platforms Content Format: Text, Images, Videos, Podcasts User Type: Individuals, Brands, Influencers, Organizations Monetization Model: Advertising, Subscription, Affiliate Marketing, Sponsored Content |
| Companies Covered | Pixlee TurnTo, Synup, Flowbox, Walls.io, Later, Yotpo, Taggbox, REVIEWS.io, Bazaarvoice, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe User Generated Content Platform Market Trends and Innovations
Blockchain-based content attribution systems are gaining traction among European platforms seeking to satisfy the EU Digital Services Act's provenance requirements while enabling creator royalty tracking across resale markets.
Federated learning architectures for content moderation are decentralizing AI training across edge devices, reducing cross-border data transfer volumes. Nordic platform operators adopt these frameworks most aggressively to preempt GDPR enforcement actions. The approach compresses centralized infrastructure costs while complicating bias audit standardization.
The EU AI Act's risk-classification system for automated content filtering is forcing disclosure of training data sourcing and bias testing protocols. Platform operators serving French and German markets now document moderation decision logic to national regulators. High-risk system providers face extended certification timelines that delay feature rollout schedules.
Brand procurement of UGC services is compressing toward outcome-based performance contracts tied to conversion lift metrics rather than content volume. UK retailers lead this shift, unbundling creative production from media placement. The model displaces retainer-based agency relationships in favor of direct platform subscriptions with embedded analytics.
Europe User Generated Content Platform Market Segmentation
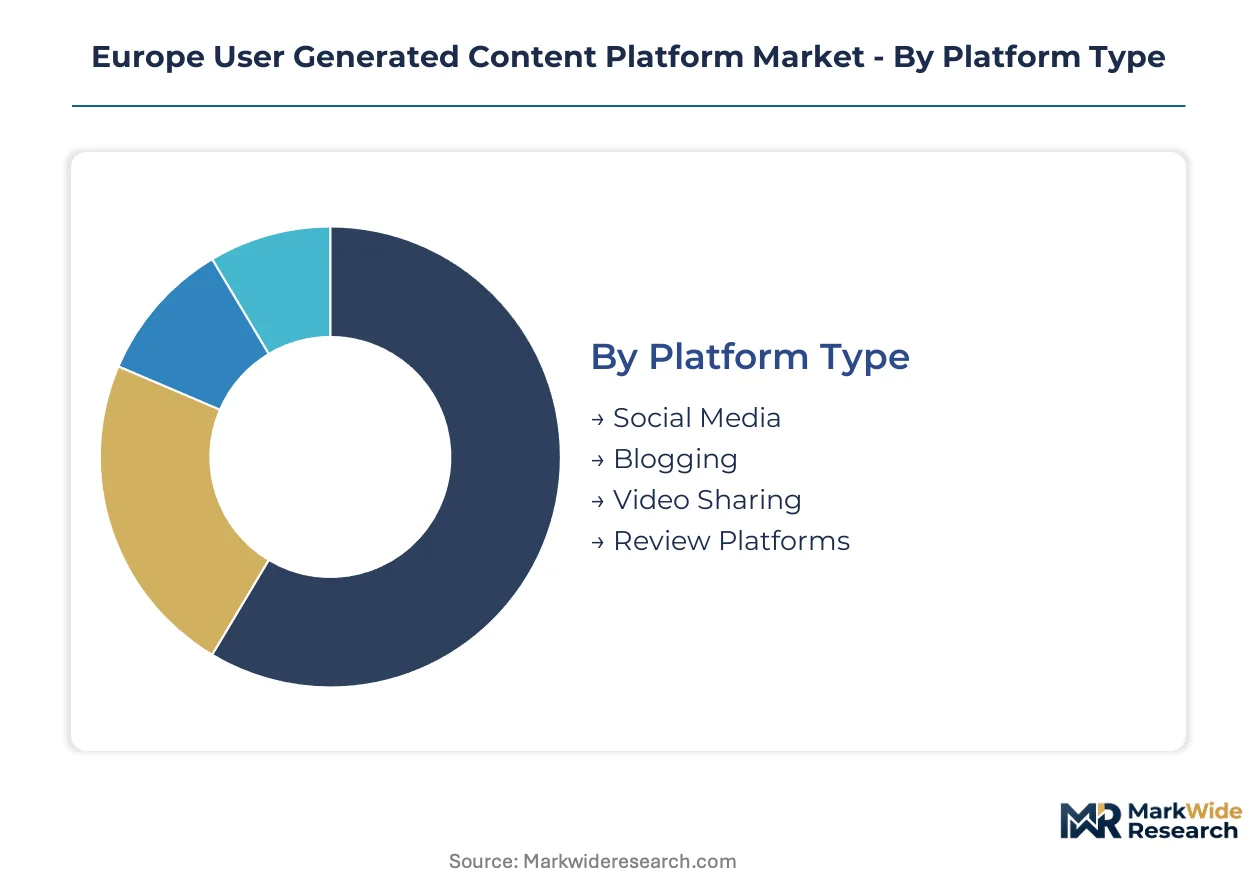
Platform segmentation in the European UGC market reveals divergent buyer priorities across content creation workflows, compliance requirements, and revenue models. Vendors configure feature sets and pricing tiers around these structural differences rather than offering undifferentiated suites.
Platform Type:
Buyer investment patterns split between commerce-embedded tools and standalone content hubs.
- Video Sharing:Short-form video infrastructure processes 4K streams with automated rights-clearance workflows. German and UK retailers concentrate demand here as TikTok and Instagram Reels displace static imagery in conversion funnels.
- Social Media:Aggregation platforms ingest multi-channel creator content into shoppable galleries. French fashion verticals drive adoption through GDPR-compliant consent frameworks that enable lawful commercial reuse.
- Blogging:Long-form text platforms serve SEO-centric publishers and B2B thought leadership programs.
- Review Platforms:Structured feedback systems integrate with e-commerce stacks to reduce return rates in home goods categories.
Volume sits with Social Media; growth tilts toward Video Sharing.
Content Format:
Technical specifications and processing costs differentiate buyer segments by creative output requirements.
- Videos:Motion content demands cloud transcoding infrastructure with AI moderation pipelines. Nordic data centers face energy price volatility that compresses margins for processing-intensive workloads.
- Images:Static visual assets up to 4K resolution anchor shoppable UGC galleries. Italian and Spanish mid-market retailers represent underpenetrated demand as visual commerce adoption lags Northern Europe.
- Text:Structured and unstructured written content serves review aggregation and blogging use cases.
- Podcasts:Audio-first formats require distinct hosting and distribution infrastructure with limited commerce integration.
Deployment concentrates in Images; expansion runs steepest in Videos.
User Type:
Commercial sophistication and procurement scale separate segments across the creator economy value chain.
- Brands:Enterprise retailers operating on legacy e-commerce stacks require API compatibility layers for dynamic UGC feed embedding. UK electronics retailers lead live shopping convergence with real-time streaming commerce tools.
- Influencers:Micro-creator cohorts in London, Berlin, and Paris leverage dedicated studio spaces and talent management platforms. Southern European subscription fashion brands drive demand for analytics-enabled creator toolkits.
- Individuals:Casual content creators generate volume without structured commercial intent.
- Organizations:Non-commercial entities deploy UGC for community engagement and advocacy campaigns.
Revenue pools concentrate in Brands; creator economy infrastructure expands fastest among Influencers.
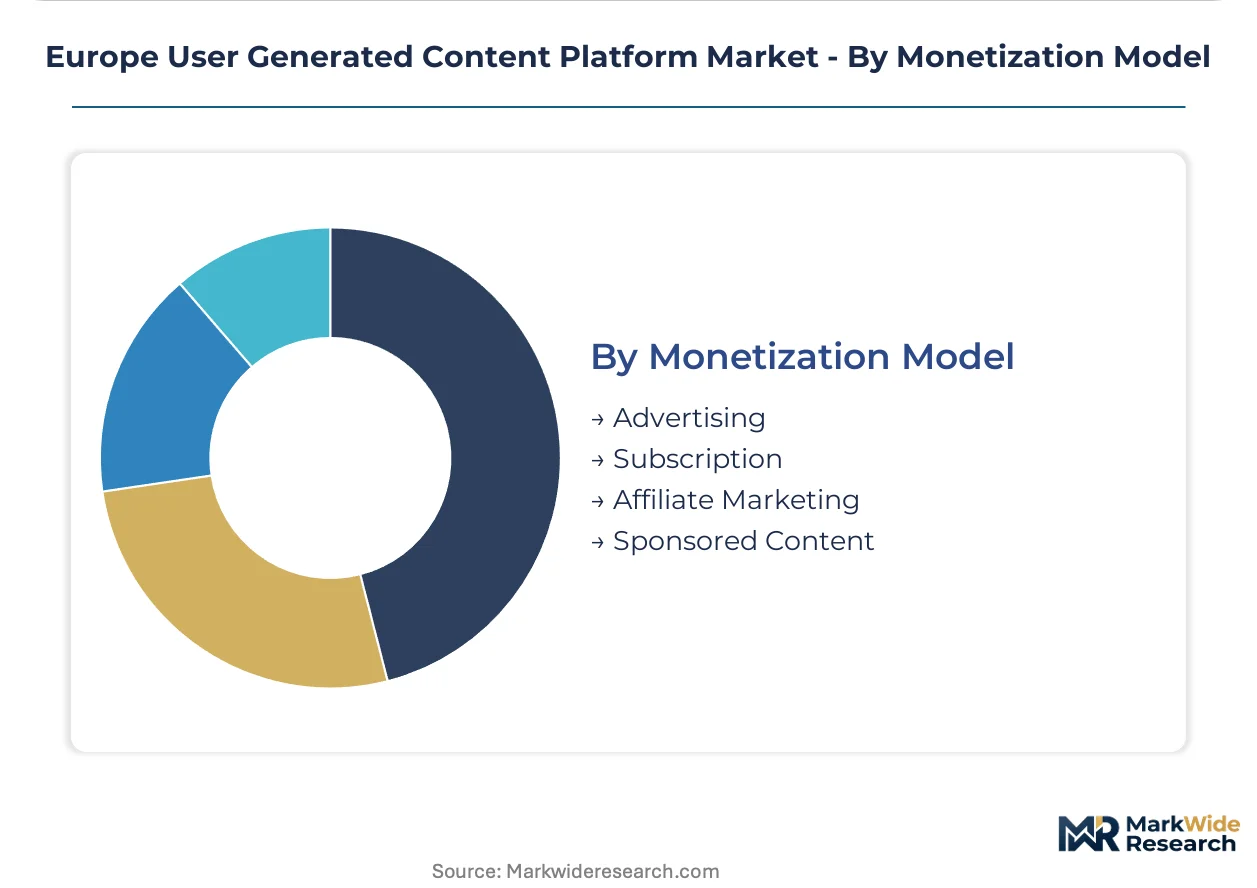
Monetization Model:
Revenue architecture determines platform operator exposure to advertising cycle volatility versus recurring subscription stability.
- Advertising:Auction-based inventory systems dominate revenue pools but face budget reallocation toward short-form video formats. French and German enforcement of the EU Digital Services Act tightens algorithmic transparency requirements for ad-targeting systems.
- Subscription:Recurring creator toolkit access gains traction among influencer-centric brands in Spain and Italy. CSRD-aligned reporting features create procurement tailwinds for platforms documenting content provenance.
- Affiliate Marketing:Performance-linked commerce commissions require robust attribution tracking across resale markets.
- Sponsored Content:Direct brand-creator arrangements demand disclosure compliance under national advertising standards.
Advertising captures current volume; subscription models gain share fastest in Southern Europe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London anchors European UGC platform activity through its dense concentration of creator economy infrastructure, talent management platforms, and D2C brand headquarters. The city's studio networks and influencer agencies lower production barriers for micro-creator cohorts serving subscription fashion brands.
Germany
German retailers drive demand for video sharing infrastructure as TikTok and Instagram Reels displace static imagery in conversion funnels. The KBA and BfDI enforce GDPR-compliant consent frameworks that embed granular rights-clearance at upload. Berlin's creator studios and Hamburg's e-commerce clusters anchor platform adoption for mid-market fashion verticals.
United Kingdom
UK electronics retailers pioneer live shopping convergence with real-time streaming commerce tools targeting Gen-Z purchase behavior. The Information Commissioner's Office tightens algorithmic transparency requirements under the EU Digital Services Act's UK alignment measures. Manchester and Birmingham emerging as secondary hubs for influencer analytics platform procurement.
France
French fashion verticals concentrate demand for social media aggregation platforms with GDPR-compliant consent frameworks enabling lawful commercial reuse. The CNIL mandates disclosure of automated moderation decision logic to national regulators. Paris houses the densest cluster of luxury brand digital teams deploying shoppable UGC galleries.
Italy
Italian mid-market retailers represent underpenetrated demand for visual commerce tools as adoption lags Northern Europe. The Garante per la Protezione dei Dati Personali enforces consent management requirements for creator content commercialization. Milan's fashion district and Rome's tourism boards drive initial subscription-based creator toolkit adoption.
Spain
Spanish influencer-centric brands fuel traction for subscription models in analytics-enabled creator toolkits. The AEPD enforces the EU AI Act's risk-classification system for automated content filtering systems. Barcelona's startup ecosystem and Madrid's advertising agencies anchor Southern Europe's fastest-expanding UGC platform demand.
Europe User Generated Content Platform Market Competitive Landscape
Capital-heavy platform operators compete with asset-light SaaS vendors across the European UGC market. The vendor base splits between consolidated enterprise suites and fragmented specialist tools serving vertical niches. Three archetypes dominate: API-first enterprise providers, shoppable social integrators, and loyalty-UGC bundlers. Competitive moves concentrate on M&A for consent-management capabilities and strategic partnerships with Nordic data center operators.
Within the enterprise suite tier, Bazaarvoice and Yotpo exemplify divergent bundling strategies, while Flowbox occupies a position bridging mid-market accessibility with Nordic retail density. Pixlee TurnTo and Taggbox sit within the specialist integrator archetype, anchoring geographic clusters where API compatibility layers prove decisive for legacy e-commerce stack penetration.
| Leading Market Players |
|---|
| Pixlee TurnTo |
| Synup |
| Flowbox |
| Walls.io |
| Later |
| Yotpo |
| Taggbox |
| REVIEWS.io |
| Bazaarvoice |
| Others |
Pricing and Supply Chain Analysis
GDPR-compliant consent management mandates from German BfDI and French CNIL are forcing platform operators to embed granular rights-clearance infrastructure at upload, compressing margins for vendors serving mid-market retailers while creating pricing power for enterprise suites with pre-certified workflows.
Pricing Analysis
Outcome-based contracts tied to conversion lift metrics anchor pricing for UK retailers unbundling creative production from media placement. Three-tier pricing structure across premium, standard, and economy levels separates API-first enterprise suites from shoppable social integrators and self-serve commodity tools. Cost compression in the mid-market intensifies because Nordic data center energy price volatility raises cloud transcoding expenses. Individual creators and micro-influencers exhibit highest price sensitivity, while enterprise brands prioritize compliance bundling over per-seat costs.
Supply Chain Analysis
Reverse-logistics for content rights—automated takedown workflows, creator royalty recalculation, and resale market attribution—consume engineering resources at Nordic platforms adopting federated learning architectures. Cloud infrastructure draws from Ireland, Germany, and Sweden, while AI moderation training data sources from UK and French annotation providers. Single-source vulnerability concentrates in hyperscaler compute contracts for 4K video transcoding. Distribution runs through direct platform subscriptions and agency retainer displacement toward embedded analytics partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into consent-management technology and creator royalty tracking systems defines competitive positioning, as platform operators race to control upstream compliance architecture and downstream resale attribution.
For Market Incumbents: Deepen API ecosystem lock-in through managed services bundling that embeds GDPR-compliant consent workflows for German retail accounts. Acquire specialized machine learning operations talent scarce in European labor markets to accelerate algorithmic bias audit deployment. Defend against asset-light SaaS vendors by anchoring enterprise suites on legacy CMS compatibility layers that mid-tier competitors cannot replicate. For New Entrants and Emerging Players: Blockchain-based content attribution systems offer a technology-first wedge into French and German markets where EU Digital Services Act provenance requirements create procurement tailwinds. Target underpenetrated Italian and Spanish mid-market fashion verticals with subscription-based creator analytics platforms. Pursue partnership-first go-to-market angles with Barcelona and Madrid advertising agencies already advising influencer-centric brands. For Investors and Strategic Acquirers: The window for entry favors consent-management capability acquisition over organic feature build, as regulatory certification timelines extend and delay rollout schedules. Long-term viability hinges on platforms documenting content provenance for CSRD-aligned ESG disclosures. Monitor divergence between French CNIL and German KBA enforcement postures on EU AI Act automated decision-making disclosures as inflection indicator for compliance cost fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Consent-Management Acquisition | Pre-certified GDPR workflows from German BfDI enforcement create procurement advantage in enterprise retail. |
| Federated Learning Deployment | Edge-device AI training reduces cross-border data transfers vulnerable to Nordic GDPR enforcement actions. |
| Live Shopping Integration | Real-time streaming commerce tools capture Gen-Z electronics purchase behavior in UK and German markets. |
| Creator Studio Partnership | London and Berlin talent management platforms lower production barriers for micro-influencer cohorts. |
| CSRD Reporting Feature Build | Content provenance documentation aligns with EU Corporate Sustainability Reporting Directive procurement requirements. |
Research Methodology
Multi-period observation of platform adoption rates, consent management investment patterns, and creator economy infrastructure buildout anchored the trend analysis, supplemented by interviews with platform engineering directors, retail e-commerce procurement leads, influencer agency account managers, and data protection compliance officers. Secondary validation drew from EU Digital Services Act implementation guidance, GDPR enforcement action databases, hyperscaler capex disclosures, and creator economy funding round announcements. Bottom-up segment sizing triangulated against top-down market boundary definitions.
Input-output matrices modeled deployment scale against monetization model mix across the analysis window, with segmentation dimensions spanning platform type, content format, user archetype, and regional regulatory cluster. CAGRs derived from slope consistency checks against historical adoption curves and forward-looking procurement pipeline indicators. Forecast inputs incorporated cloud infrastructure cost trajectories and EU AI Act risk-classification implementation timelines.
Several conditions sit outside the modeled scope, including pre-emptive national data protection authority enforcement shifts and hyperscaler pricing restructuring for AI moderation services. Forecasts reflect assumptions around stable regulatory interpretation divergence between member states. Practitioners should monitor TikTok and Instagram Reels budget reallocation velocity and Nordic data center energy price volatility for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Social Media and Influencer Economy
Content Creation Market
Social Media and Influencer Economy
User Generated Content Platform Market
Social Media and Influencer Economy
Social Publishing Application Market
Social Media and Influencer Economy
LAMEA User Generated Content Platform Market
Social Media and Influencer Economy
Global Social Media Market
Social Media and Influencer Economy
Virtual Content Creation Market
Social Media and Influencer Economy
Online Virtual Youtuber Model Market
Social Media and Influencer Economy
Social Media Content Creation Market
Social Media and Influencer Economy
Global Blogging Platforms Market
Social Media and Influencer Economy
Influencer Marketing Platform Market
Social Media and Influencer Economy
Virtual Influencer Market
Social Media and Influencer Economy
Global Short Video Sharing Platform Market
Social Media and Influencer Economy
Asia-Pacific User Generated Content Platform Market
Social Media and Influencer Economy
Online Love Rush Market
Social Media and Influencer Economy
Global Influencer Market
Social Media and Influencer Economy
Metaverse Social Media Platforms Market