
 Online Love Rush Market | 2026-2036
Online Love Rush Market Size, Share, and Industry Trends Forecast 2026-2036
Online Love Rush Market Insights
Mobile app distribution is reconfiguring how Chinese consumers access relationship services, bypassing traditional web portals for instant-match interfaces. TaoBao leverages its e-commerce infrastructure to embed dating-adjacent social commerce features. ZhuanZhuan anchors its secondhand marketplace ecosystem with community-driven trust mechanisms that extend into personal connection tools. Red Book competes through content-to-commerce loops where lifestyle influencers drive discovery of matchmaking services.
Online Love Rush encompasses digital platforms and services facilitating romantic partner discovery, relationship formation, and interpersonal connection maintenance through algorithmic matching, real-time communication protocols, and user-generated content ecosystems. The primary commercial purpose centers on reducing search friction in partner selection while monetizing user attention through subscription tiers, virtual gifting, and advertising placements. Dating apps command the largest addressable base among service types, though matchmaking services extract premium fees from time-constrained urban professionals. Video chat features within the feature dimension generate disproportionate session duration, while mobile platforms dominate usage frequency relative to desktop alternatives.
SAMR oversees platform compliance for algorithmic transparency and consumer protection in digital services, while MIIT governs data localization and telecommunications licensing for real-time communication functions. The country's dual carbon goals indirectly pressure data center operators hosting these platforms toward renewable energy sourcing, affecting infrastructure cost structures. Stakeholders must weigh regulatory tightening on algorithmic recommendation systems against user demand for hyper-personalized matching precision.
Market Dynamics
Live-streaming matchmaking technology is compressing courtship timelines while MIIT data-localization mandates reshape platform architecture costs. Algorithmic transparency requirements from SAMR force operators to disclose recommendation logic, altering competitive moats.
Growth Catalysts
- Dual carbon goals:Renewable energy mandates for data centers reduce long-term hosting costs for video-intensive platforms. Operators in Shanghai and Beijing secure carbon-compliant infrastructure faster than peers.
- Mobile-first interfaces:Instant-match protocols on smartphones capture commute-time usage windows that desktop portals cannot access. Young professionals in tier-one cities drive session frequency.
- Virtual gifting monetization:Real-time communication protocols enable micro-transaction revenue streams alongside subscription tiers. Content creators in live-streaming matchmaking extract higher per-user value than traditional dating apps.
Market Restraints
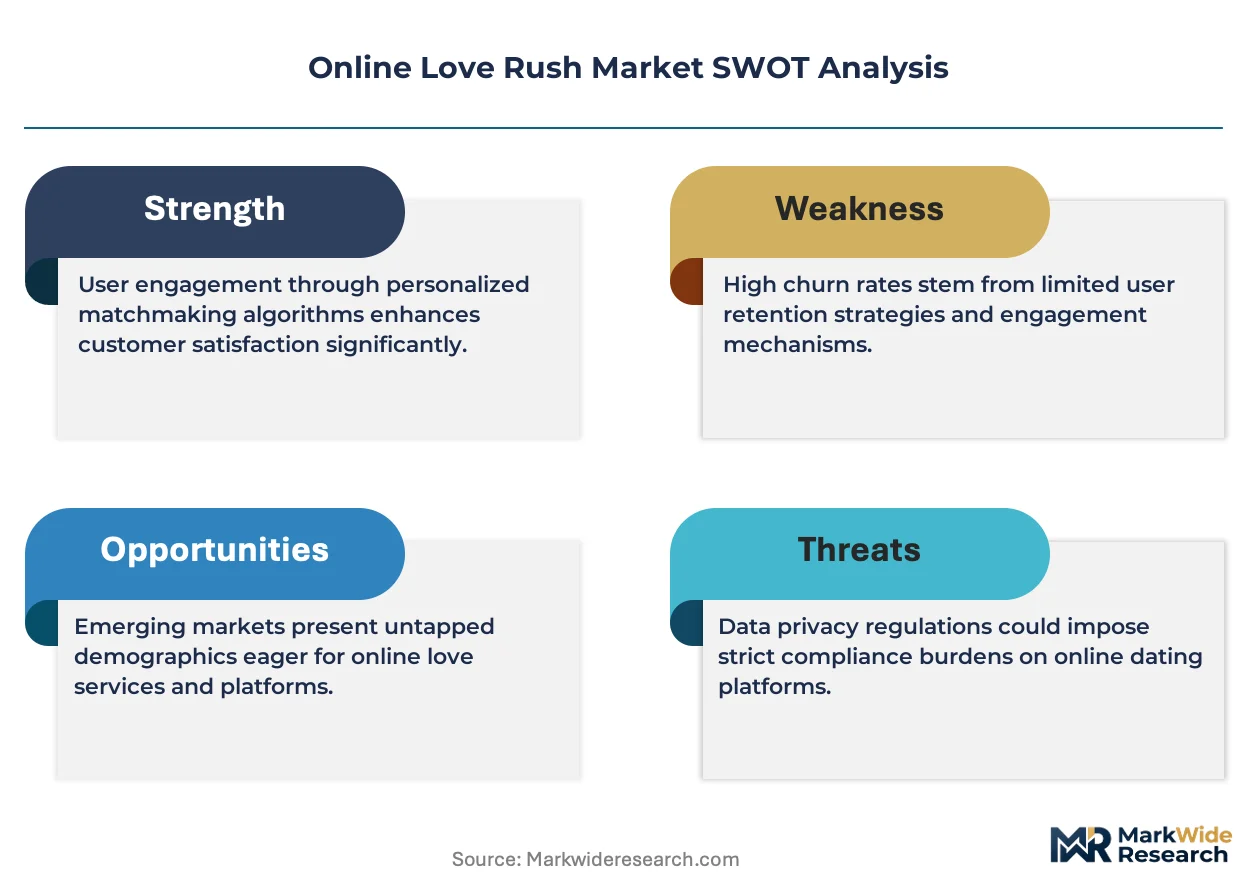
- Algorithmic audit costs:SAMR compliance mandates require ongoing disclosure of recommendation system mechanics. Platform operators face persistent legal and technical overhead.
- Data center energy price volatility:Renewable energy sourcing requirements under dual carbon goals expose operators to spot-market electricity fluctuations in eastern provinces.
- Social stigma substitution:Offline matchmaking services via family networks retain preference among older demographics in lower-tier cities, capping digital penetration.
Strategic Opportunities
- Second-tier city expansion:Chengdu and Hangzhou exhibit rising professional density with underdeveloped platform competition. Early entrants capture network effects before saturation.
- Content-to-commerce convergence:Lifestyle influencer ecosystems on social platforms drive discovery of premium matchmaking services. Red Book-style loops reduce customer acquisition costs.
- Video chat feature premiumization:Extended session duration on real-time video functions supports tiered subscription models. Operators monetize attention through virtual gifting overlays.
Industry Challenges
- Trust algorithm engineering:Community-driven verification systems require scarce machine-learning talent familiar with both social graph analysis and fraud detection. Recruitment lags platform growth.
- Cross-platform identity synchronization:Users maintain fragmented profiles across e-commerce, social, and dating apps. Data unification without violating MIIT localization rules demands complex architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Love Rush Market |
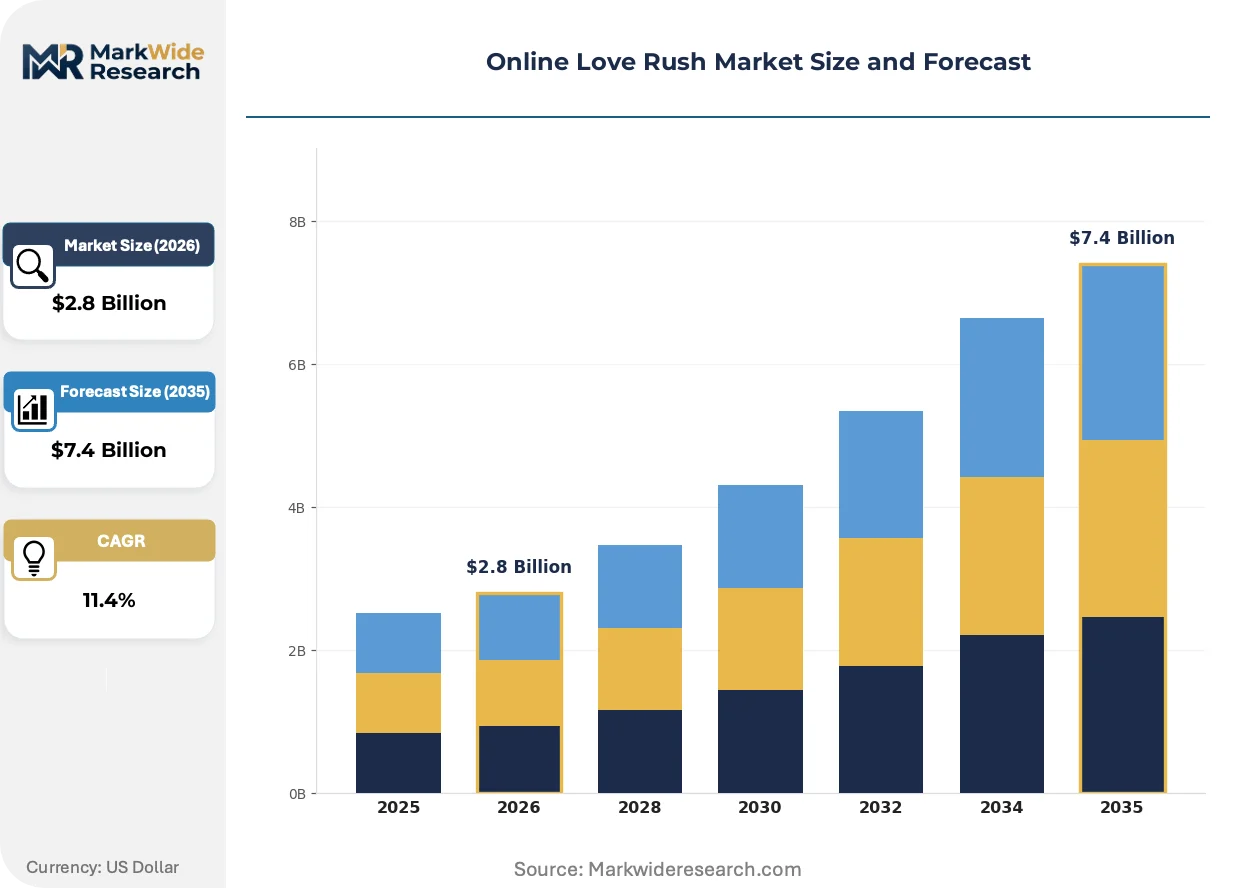
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dating Apps, Matchmaking Services, Online Workshops, Relationship Coaching Customer Type: Singles, Couples, Divorced Individuals, LGBTQ+ Community Feature: Video Chat, Messaging, Profile Matching, Virtual Events Platform: Mobile, Web, Social Media, Desktop |
| Companies Covered | XianYu, ZhuanZhuan, TongCheng APP, Red Book, TaoBoao, Pin Duoduo, BaiDu TieBa, ZhiHu, Team.blue, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Love Rush Market Trends and Innovations
Real-time interaction layers are displacing static profile browsing as the primary engagement mode. Platforms now compete on immersion depth rather than database size.
Live-streaming matchmaking is virtualizing the traditional introduction ritual. Host-mediated video rooms enable simultaneous multi-party courtship, reducing one-to-one messaging fatigue. Urban professionals in Shanghai adopt these formats within three months of platform registration, compressing the path from discovery to offline meeting. This technology is virtualizing geographic proximity as a matching prerequisite, enabling cross-city relationships previously impractical.
SAMR algorithmic transparency guidelines now require disclosure of recommendation system training data sources. Platform operators must document how user behavior inputs generate match suggestions, exposing previously proprietary ranking mechanics. Dating apps with complex collaborative filtering face higher compliance burdens than simpler rule-based systems, advantaging newer entrants with cleaner architectures.
Subscription unbundling is fragmenting how users pay for relationship services. Young professionals reject annual commitments in favor of event-based purchases tied to specific live-streaming sessions or virtual gifting moments. This pattern concentrates in Beijing, where disposable income supports impulse micro-transactions but subscription fatigue limits recurring revenue capture.
Online Love Rush Market Segmentation
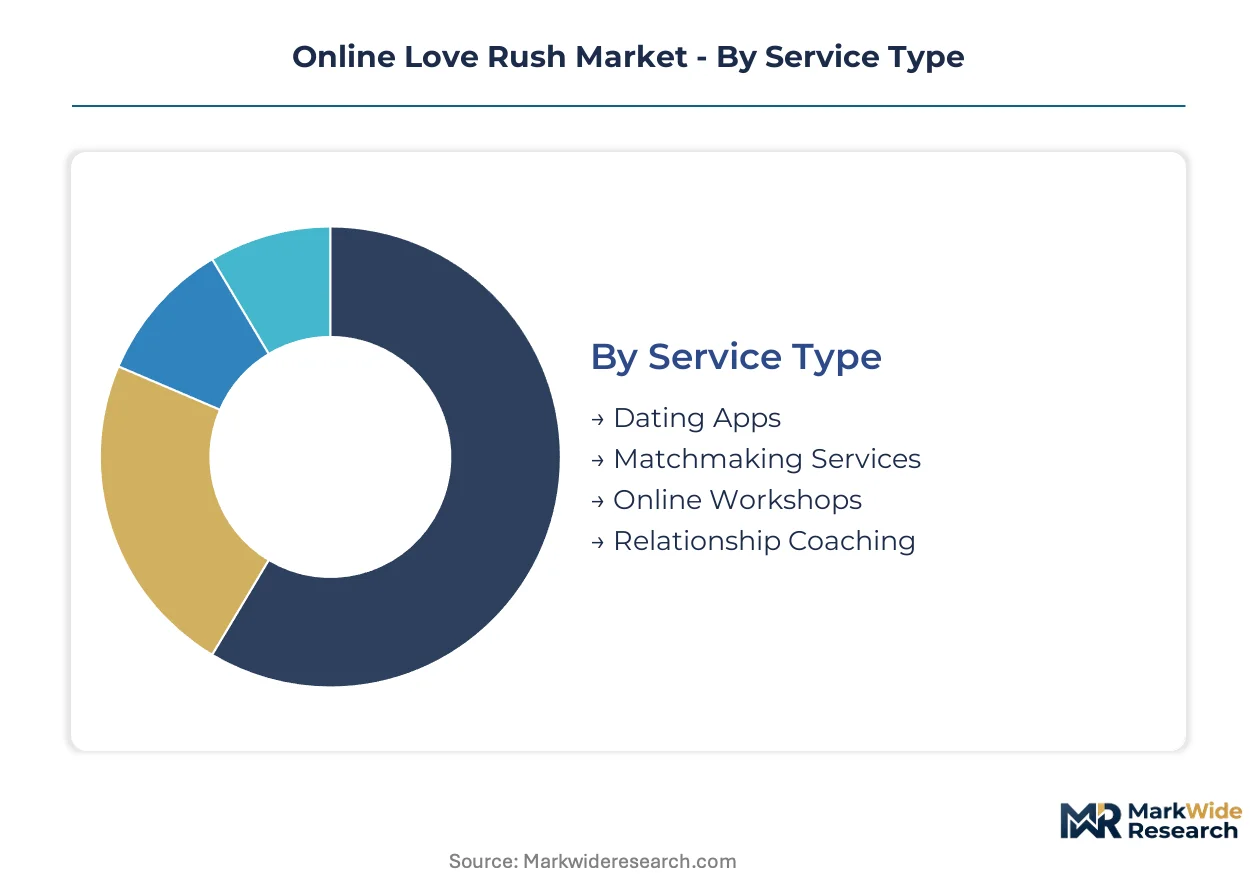
Segmentation in the Online Love Rush Market reveals how platform operators monetize distinct user behaviors and relationship stages. Service architecture, customer life cycle positioning, feature engagement patterns, and access channel preferences each create addressable revenue pools with divergent margin profiles.
Service Type:
Mature subscription models coexist with emerging micro-transaction formats across the service spectrum.
- Dating Apps:Algorithmic matching engines process user preference data to generate partner recommendations, with swipe-based interfaces dominating session initiation. Young professionals in Shanghai and Beijing generate the highest daily active user density, though subscription fatigue in these markets pressures annual plan conversion rates.
- Matchmaking Services:Human-curated introductions command premium fees through personalized screening and date coordination. Time-constrained urban professionals in tier-one cities absorb per-introduction pricing that exceeds annual dating app subscriptions by multiples, sustaining operator margins despite limited scale.
- Online Workshops:Group-based relationship education delivered through scheduled virtual sessions attracts pre-couple users seeking skills before partner search.
- Relationship Coaching:One-on-one guidance for established partnerships extends customer lifetime value beyond the initial match phase.
Dating apps retain volume leadership; matchmaking services hold the steepest expansion curve.
Customer Type:
Cost tier stratification separates mass-market accessibility from specialized service premiums.
- Singles:The core addressable base spans never-married individuals across age cohorts, with platform design optimizing for high-volume profile discovery and rapid matching cycles. Beijing and Shanghai concentrate the highest density of single professionals with disposable income for premium tier upgrades.
- Couples:Existing partnerships generate recurring revenue through relationship maintenance tools and shared experience features. Joint account functionality and couples-oriented content loops reduce churn compared to individual user acquisition costs.
- Divorced Individuals:This segment exhibits elevated willingness to pay for privacy-enhanced matching and age-appropriate partner pools.
- LGBTQ+ Community:Specialized platforms address safety concerns and community verification needs absent from mainstream services.
Singles command absolute user volume; the LGBTQ+ community shows the most rapid platform adoption velocity.
Feature:
Application intensity varies dramatically by engagement depth and infrastructure requirements.
- Video Chat:Real-time audiovisual communication generates session durations exceeding text-based alternatives by substantial multiples. Live-streaming matchmaking hosts in Beijing monetize these extended engagements through virtual gifting overlays that capture impulse purchase behavior.
- Messaging:Asynchronous text exchange remains the entry-level engagement mode with lowest infrastructure cost per interaction. High message volume in tier-one cities supports advertising insertion opportunities between conversation threads.
- Profile Matching:Algorithm-driven compatibility scoring determines initial connection quality and user satisfaction with platform outcomes.
- Virtual Events:Scheduled group experiences create low-pressure introduction environments for users hesitant about one-on-one initiation.
Messaging retains volume leadership; video chat displays the sharpest monetization trajectory.
Platform:
Customer type and usage context dictate channel selection across device categories.
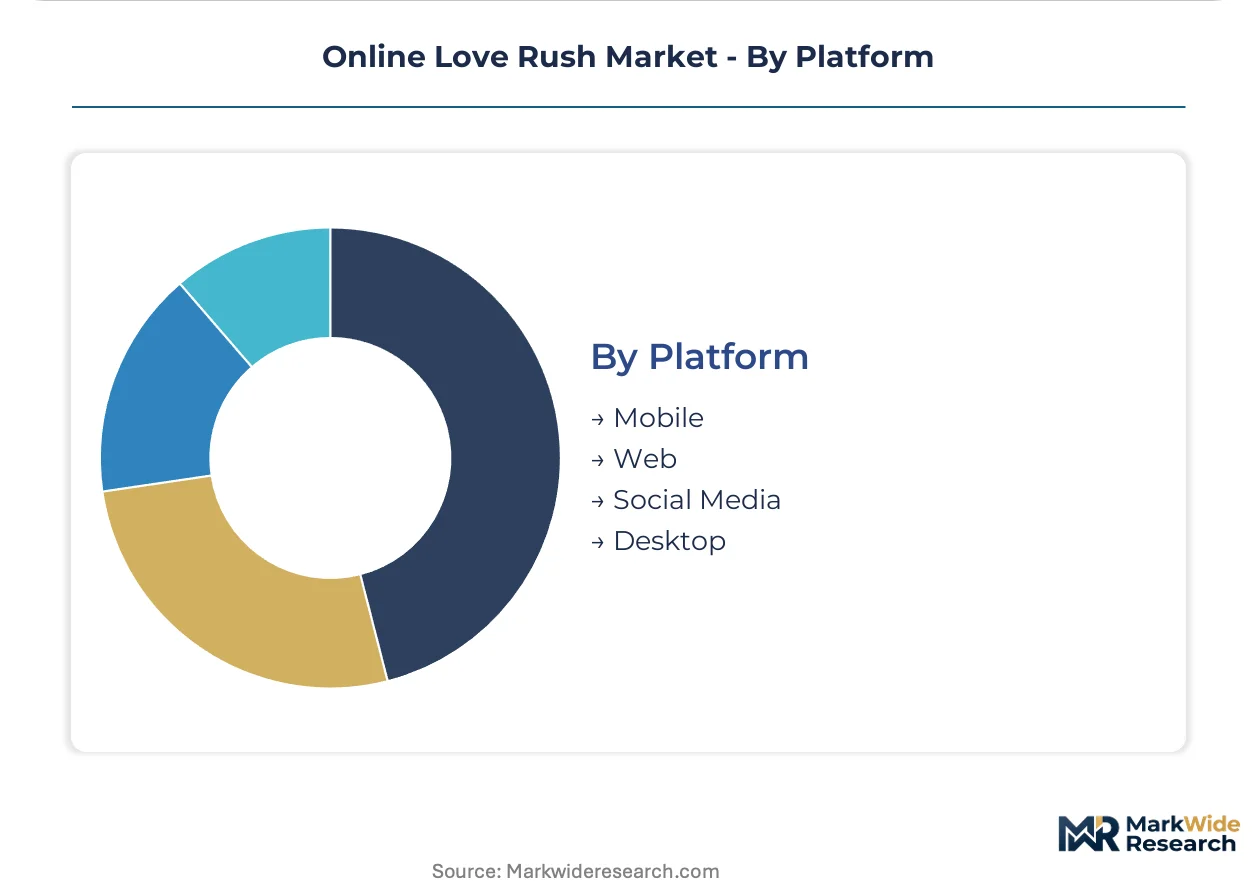
- Mobile:Smartphone-native interfaces capture commute-time usage windows and location-based matching opportunities. Young professionals across China demonstrate session frequency patterns that desktop alternatives cannot replicate, with instant-match protocols optimized for fragmented attention spans.
- Web:Browser-based access serves users prioritizing larger-screen profile review and keyboard-intensive communication. Office workers in Beijing access web portals during workday breaks where mobile app installation faces employer restrictions.
- Social Media:Embedded discovery through existing social graphs reduces customer acquisition costs for operators leveraging content-to-commerce loops.
- Desktop:Full-featured applications attract power users managing multiple platform accounts simultaneously.
Mobile retains volume leadership; social media integration shows the fastest adoption acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Beijing-Shanghai high-speed rail corridor compresses courtship logistics for cross-city relationships, anchoring China's concentration of live-streaming matchmaking infrastructure. Tier-one urban clusters drive platform monetization through density effects that secondary cities cannot yet replicate.
China
Young professionals in Shanghai and Beijing generate the highest per-user revenue through virtual gifting overlays during live-streaming sessions. SAMR algorithmic transparency mandates force disclosure of recommendation training data sources, raising compliance costs for established platforms. Chengdu and Hangzhou emerge as expansion targets where professional density rises faster than platform saturation.
United States
Coastal metropolitan corridors concentrate dating app usage through smartphone penetration rates exceeding national averages by substantial margins. FCC telecommunications licensing governs real-time video communication protocols that underpin premium feature tiers. The San Francisco Bay Area and New York Metro anchor venture capital flows into relationship-tech startups seeking to replicate Chinese live-streaming formats.
India
TRAI data localization requirements reshape platform hosting architectures for foreign operators entering the market. Mumbai and Delhi-NCR concentrate English-proficient user bases willing to pay premium subscription tiers. Arranged marriage traditions in lower-tier cities sustain demand for family-mediated digital matchmaking rather than individual-discovery apps.
Japan
METI oversight of telecommunications infrastructure affects video chat quality thresholds that platforms must meet for market access. Tokyo and Osaka metropolitan areas exhibit aging demographics that shift platform focus toward remarriage and late-life partnership services. Declining birth rates pressure operators to extend customer lifetime value beyond initial match phases.
South Korea
MFDS data protection standards intersect with real-time communication licensing under broader ICT governance frameworks. Seoul Capital Area users demonstrate highest adoption velocity for AI-driven compatibility scoring among East Asian markets. Busan-Ulsan industrial corridor workers drive demand for shift-schedule-aware matching algorithms.
Online Love Rush Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in algorithmic matching engines and payment infrastructure. The vendor structure concentrates around super-app ecosystems that embed dating-adjacent features within broader commerce and social functions. Three archetypes dominate: e-commerce platforms extending into social discovery, dedicated matchmaking apps with subscription monetization, and content-to-commerce loops leveraging influencer networks. Consolidation pressure operates through strategic partnerships between telecom infrastructure providers and platform operators, plus vertical integration into live-streaming talent agencies.
Within the super-app tier, TaoBao and Pin Duoduo exemplify e-commerce platforms that embed relationship-adjacent social features within existing transaction ecosystems. Red Book occupies a position anchoring content-to-commerce discovery loops where lifestyle influencers drive matchmaking service adoption. ZhuanZhuan represents the community-trust archetype, extending secondhand marketplace verification mechanisms into personal connection tools. These three companies illustrate how Chinese platform economics blur category boundaries between commerce, content, and courtship.
| Leading Market Players |
|---|
| XianYu |
| ZhuanZhuan |
| TongCheng APP |
| Red Book |
| TaoBoao |
| Pin Duoduo |
| BaiDu TieBa |
| ZhiHu |
| Team.blue |
| Others |
Pricing and Supply Chain Analysis
Shanghai data center clusters anchor platform hosting capacity for video-intensive matchmaking services, with renewable energy compliance under dual carbon goals feeding directly into infrastructure cost pass-through to subscription tiers. Operators in this corridor leverage scale economies to extract pricing power over smaller regional competitors facing spot-market electricity volatility in eastern provinces.
Pricing Analysis
Volume-discount tiering structures dominate monetization, with annual subscriptions commanding per-month rates 40% below monthly plans. Premium-mid-economy pricing differentiation separates live-streaming hosts with verified audiences from standard algorithmic matching users. Pricing pressure stems from subscription fatigue among Beijing young professionals who favor impulse micro-transactions over recurring commitments. Singles in tier-one cities exhibit lowest price sensitivity for virtual gifting overlays, while second-tier city users drive standard tier volume.
Supply Chain Analysis
Upstream feedstock for real-time communication infrastructure draws from semiconductor fabrication concentrated in Taiwan, South Korea, and the United States. GPU accelerators and high-bandwidth memory modules constitute critical component dependencies for video encoding pipelines. Single-source vulnerability around advanced node chipsets exposes operators to export control restrictions affecting MIIT licensing timelines. Distribution runs through cloud service provider partnerships with domestic data center operators rather than direct hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Online Love Rush Market sits in cyclical recovery as live-streaming matchmaking technology re-engages users previously fatigued by static profile browsing, compressing courtship timelines and restoring session growth trajectories.
For Market Incumbents: Pre-empt second-tier city saturation by securing carbon-compliant data center capacity in Chengdu and Hangzhou before network effects lock in competitors. Threats from Red Book-style content-to-commerce loops demand backward integration into influencer talent networks to defend customer acquisition economics. Channel control through telecom infrastructure partnerships offers the strongest defensive lever against super-app encroachment.
For New Entrants and Emerging Players: Pursue underdeveloped matchmaking service penetration among divorced individuals in tier-two cities, where privacy-enhanced offerings command premium pricing with limited incumbent presence. The LGBTQ+ community segment offers fastest platform adoption velocity with specialized verification needs unmet by mainstream services. Go-to-market positioning through community-driven trust mechanisms rather than algorithmic scale reduces initial capital requirements.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among matchmaking services with human-curated introductions, though scalability constraints limit addressable market. Long-term viability across the analysis window favors platforms with diversified monetization beyond subscription dependency. Acquisition targets should demonstrate live-streaming host retention rates and virtual gifting revenue mix as inflection indicators of engagement depth.
| Strategic Initiative | Industry Significance |
|---|---|
| Live-Streaming Host Talent Acquisition | Secures content creators capable of driving virtual gifting revenue in Beijing and Shanghai. |
| Carbon-Compliant Data Center Partnership | Aligns infrastructure expansion with dual carbon goals while reducing long-term electricity cost exposure. |
| Second-Tier City Geographic Expansion | Captures rising professional density in Chengdu and Hangzhou before network effect saturation. |
| Algorithmic Transparency Compliance Investment | Preempts SAMR audit costs through cleaner recommendation architectures that reduce legal overhead. |
| Content-to-Commerce Loop Integration | Leverages lifestyle influencer ecosystems on Red Book-style platforms to reduce customer acquisition costs. |
Research Methodology
The analysis maps dating apps, matchmaking services, video chat features, and live-streaming technology layers, each validated through platform product managers, data center infrastructure planners, SAMR compliance officers, and virtual gifting payment processors. Primary interviews with these stakeholders combined with secondary triangulation against MIIT telecommunications licensing databases, SAMR algorithmic disclosure filings, hyperscaler capex reports, and mobile app analytics platforms. Bottom-up user segmentation modeling and top-down market sizing approaches converged through iterative reconciliation.
Assumption sets held regulatory enforcement intensity and renewable energy cost trajectories fixed while varying user adoption curves across city tiers and feature engagement patterns. The projection horizon spans service type, customer life cycle stage, platform access channel, and feature monetization depth as segmentation dimensions. CAGRs derived from historical penetration rates applied to demographic and infrastructure build-out forecasts, with video chat session duration and virtual gifting conversion rates as critical industry-specific inputs.
Sensitivities concentrate around SAMR algorithmic audit implementation timelines and spot-market electricity price volatility in eastern provinces affecting data center economics. Cross-checking against MIIT real-time communication license issuance rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Social Media and Influencer Economy
Global Social Media Market
Social Media and Influencer Economy
LAMEA User Generated Content Platform Market
Social Media and Influencer Economy
Influencer Marketing Platform Market
Social Media and Influencer Economy
Photo Sharing Market
Social Media and Influencer Economy
Online Virtual Youtuber Model Market
Social Media and Influencer Economy
Content Creation Market
Social Media and Influencer Economy
Influencer Marketing Market
Social Media and Influencer Economy
Virtual Influencer Market
Social Media and Influencer Economy
Global Blogging Platforms Market
Social Media and Influencer Economy
Social Publishing Application Market
Social Media and Influencer Economy
Asia-Pacific User Generated Content Platform Market
Social Media and Influencer Economy
Metaverse Social Media Platforms Market
Social Media and Influencer Economy
Virtual Content Creation Market
Social Media and Influencer Economy
User Generated Content Platform Market
Social Media and Influencer Economy
Global Short Video Sharing Platform Market
Social Media and Influencer Economy
Global Influencer Market