
 Global Influencer Market | 2026-2036
Global Influencer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Influencer Market Foresight
Market Dynamics
Brand procurement of influencer services is pivoting from experimental pilot budgets to centralized, always-on programs managed by dedicated teams. Sprout Social, Inc. leverages its social media management suite to anchor enterprise clients seeking unified campaign orchestration. Grin Technologies Inc. specializes in e-commerce integrations that connect creator content directly to purchase attribution. Upfluence competes across mid-market segments with self-serve discovery tools that reduce agency dependency.
Technical Definition and Segment Structure
An influencer is a content creator who cultivates audience trust within a specific niche and monetizes that relationship through sponsored collaborations, affiliate commissions, or platform revenue sharing, typically measured by engagement rate, follower count, and audience demographic alignment. The primary commercial purpose is to transfer parasocial trust into measurable consumer action for brands seeking alternatives to interruptive advertising. Nano Influencers and Micro Influencers now capture disproportionate budget share as brands prioritize engagement depth over reach volume, with Fashion & Beauty and Consumer Electronics representing the most mature Application Sectors where standardized performance metrics have emerged. Content Platform segmentation shows TikTok and Instagram dominating short-form video allocations while YouTube sustains long-form tutorial and review formats with higher production thresholds.
Regulatory Environment and Outlook
The Federal Trade Commission in the United States mandates clear disclosure of material connections through its Endorsement Guides, while the EU Digital Services Act imposes algorithmic transparency requirements on platforms distributing sponsored content. China's SAMR enforces advertising law compliance for live-stream commerce, creating divergent compliance architectures across major markets. Stakeholders must monitor evolving platform-native disclosure tools and jurisdiction-specific liability frameworks as regulatory enforcement intensifies.
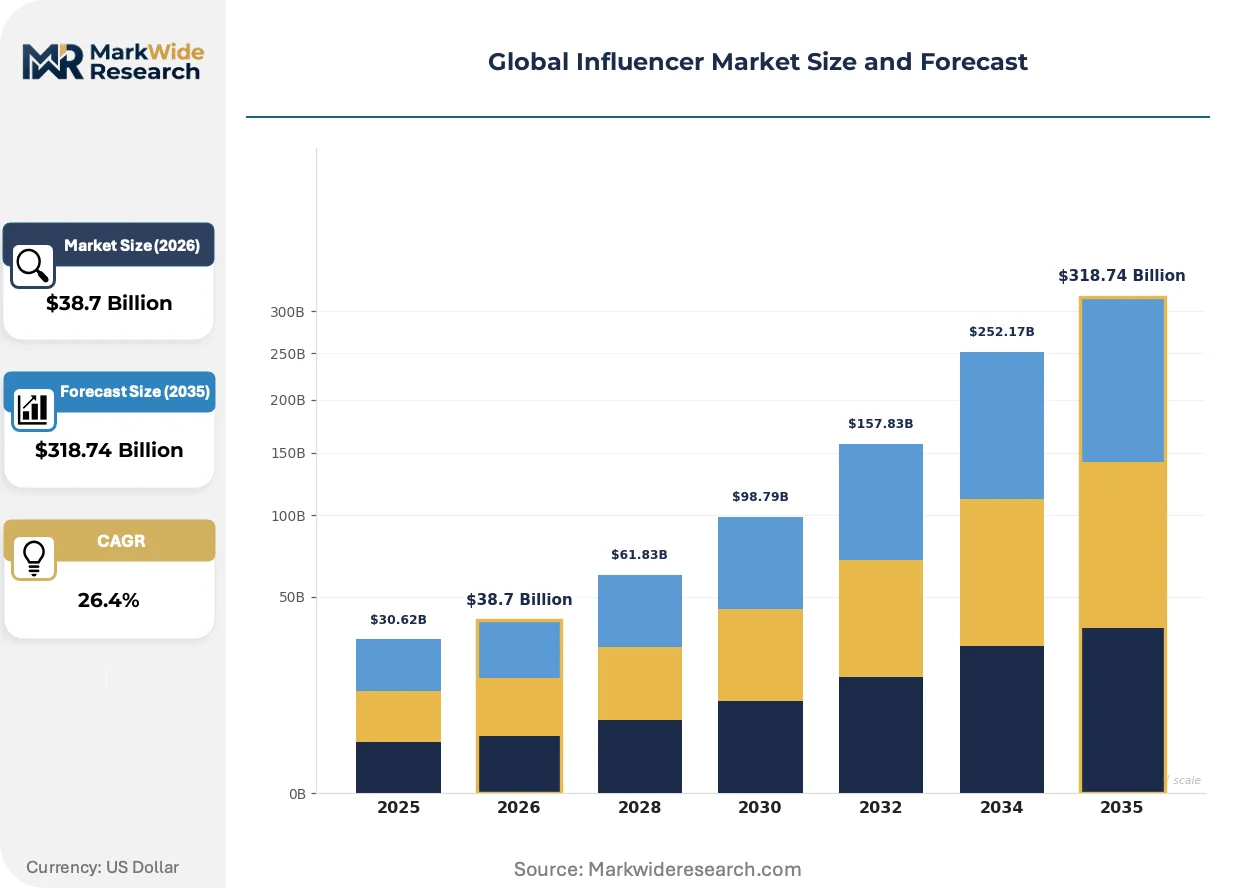
Market Dynamics
Platform algorithmic shifts toward short-form video distribution have compressed creator monetization windows, forcing brands to accelerate content production cycles and restructure campaign measurement frameworks around engagement velocity rather than reach accumulation.
Growth Catalysts
- EU Digital Services Act:The transparency mandates on content amplification are normalizing disclosure standards that reduce brand risk in sponsored partnerships, accelerating enterprise budget commitments to creator channels.
- Live-stream commerce infrastructure:China's SAMR enforcement of advertising law compliance has professionalized the format, creating exportable operational templates for real-time product demonstration and instant purchase conversion.
- Engagement depth metrics:Nano and Micro Influencer segments now capture disproportionate budget allocation as brands prioritize comment-to-view ratios and save rates over follower counts in performance evaluation.
Market Restraints
- Platform dependency risk:Algorithmic distribution control concentrates with TikTok and Instagram parent Meta, creating single-point-of-failure exposure for campaign reach guarantees.
- Attribution technology gaps:Cross-platform user journey tracking remains technically constrained, limiting accurate ROI measurement for multi-channel influencer strategies.
- GDPR data portability friction:EU restrictions on audience data extraction complicate creator migration between platforms and brand direct-relationship building.
Strategic Opportunities
- Brazil creator infrastructure:Underdeveloped agency representation and rising platform penetration create first-mover advantage for localized content production networks.
- B2B professional services:SaaS and financial services verticals remain underpenetrated by creator partnerships relative to consumer categories, offering expansion white space.
- AI-generated content disclosure frameworks:Emerging platform policies on synthetic media labeling will reward early compliance investment with algorithmic preference.
Industry Challenges
- Creator talent pipeline constraints:Specialized video editing and platform-native storytelling skills command premium compensation that compresses campaign margins.
- Cross-border payment complexity:Multi-currency creator compensation and withholding tax compliance create administrative overhead for international campaign execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Influencer Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $318.74 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Influencer Tier: Nano Influencers, Micro Influencers, Macro Influencers, Mega Influencers, Celebrity Influencers Content Platform: Instagram, YouTube, TikTok, Twitch, LinkedIn, Pinterest End User Type: Brands, Agencies, Nonprofits, Emerging Startups, Established Enterprises Application Sector: Fashion & Beauty, Consumer Electronics, Food & Beverage, Travel & Hospitality, Sports & Fitness |
| Companies Covered | Sprout Social, Inc., Grin Technologies Inc., Upfluence, AspireIQ, Inc., Traackr, Inc., Klear (Meltwater), CreatorIQ, Brandwatch, Captiv8, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Influencer Market Shifts & Advancements
Artificial intelligence tools are compressing content production timelines while fragmenting audience attention across platform-native formats, reshaping how brands structure creator relationships from campaign-based to continuous engagement models.
Generative AI content assistance is integrating into creator workflows through automated caption generation, thumbnail optimization, and posting-time prediction. Mid-tier influencers with 100,000 to 500,000 followers are adopting these tools fastest to maintain posting frequency without proportional production cost increases. The technology is integrating previously separate functions of creative ideation and performance analytics into unified dashboard environments.
GDPR enforcement on automated decision-making is tightening consent requirements for algorithmic content recommendation systems across European markets. Platforms must now provide meaningful explanation when sponsored posts are amplified or suppressed by automated ranking systems. Fashion and beauty brands operating multi-market campaigns face the steepest compliance adaptation costs as they reconcile EU transparency mandates with platform-native disclosure tools.
Enterprise procurement of influencer services is consolidating from dispersed team experimentation into centralized always-on programs with dedicated operational staff. The agency middle layer faces compression as self-serve discovery platforms and direct creator relationship tools displace traditional representation functions. This pattern is most visible in the United States, where Fortune 500 marketing departments have completed organizational restructuring to embed creator strategy within core media planning functions.
Global Influencer Market Segmentation
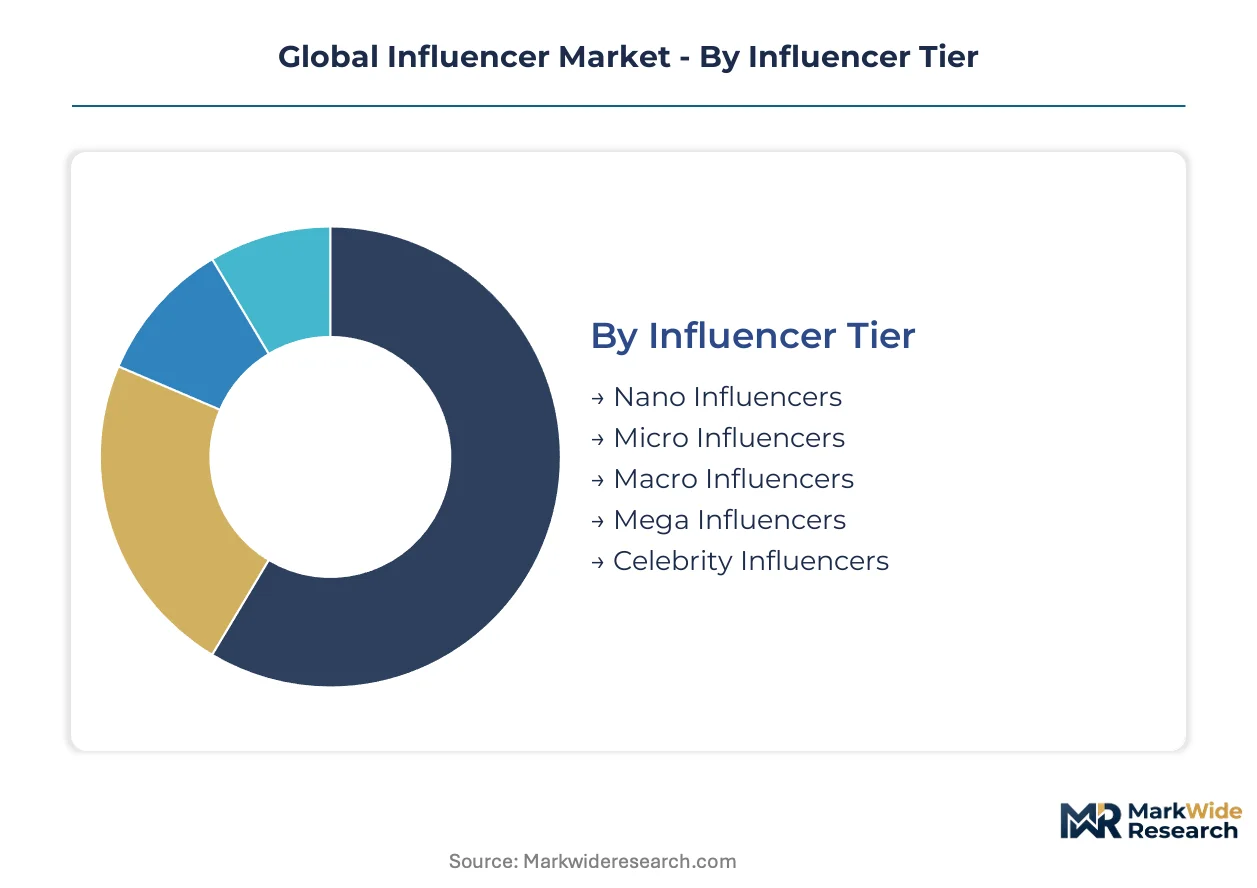
Segmentation in the influencer market determines pricing architecture, campaign measurement frameworks, and regulatory exposure. Brands structure procurement differently across tier, platform, and application boundaries. Understanding these divisions reveals where parasocial trust converts most efficiently to commercial action.
Influencer Tier:
Customization intensity varies sharply across this category—from highly standardized celebrity contracts to bespoke nano-creator relationship programs requiring individual negotiation.
- Nano Influencers:Creators with 1,000 to 10,000 followers command engagement rates often exceeding larger tiers. United States DTC brands concentrate procurement here for comment-to-view ratio optimization and community authenticity.
- Micro Influencers:Reach between 10,000 and 100,000 followers enables scalable campaign deployment with retained audience intimacy. European fashion labels prioritize this tier for GDPR-compliant direct messaging and localized content adaptation.
- Macro Influencers:Mid-tier reach of 100,000 to 1 million followers suits product launch velocity requirements. Standardized rate cards reduce negotiation overhead for recurring campaign series.
- Mega Influencers:1 million to 5 million follower bases deliver mass awareness with measurable but diluted engagement. China live-stream commerce infrastructure has professionalized this tier's conversion mechanics.
- Celebrity Influencers:Above 5 million followers, these partnerships require complex rights management and FTC disclosure compliance. Luxury automotive and beauty sectors dominate spending concentration here.
Leading the category by volume: Micro Influencers. Expanding most quickly: Nano Influencers.
Content Platform:
Production cost tiers separate this category—from low-threshold short-form video to capital-intensive long-form production environments.
- Instagram:Meta's platform anchors image and Reels distribution with mature shopping integration. United States beauty brands allocate the largest share of platform-specific budgets here for Stories-to-checkout attribution.
- YouTube:Long-form tutorial and review formats sustain higher production thresholds and extended content lifecycles. Consumer electronics brands depend on this platform for technical demonstration depth and search discoverability.
- TikTok:ByteDance's algorithm prioritizes engagement velocity over follower accumulation. Fashion and entertainment sectors exploit compressed trend cycles for viral amplification.
- Twitch:Live streaming infrastructure serves gaming and technology verticals with real-time audience interaction. Subscription and donation monetization reduces pure sponsorship dependency.
- LinkedIn:Professional context enables B2B influencer activation for SaaS and financial services. Content performance metrics emphasize lead generation over vanity engagement.
- Pinterest:Visual discovery engine supports home décor and food verticals with extended content half-lives. Shopping integration lags Instagram but conversion intent runs higher.
Dominating budget allocation: Instagram. Gaining share fastest: TikTok.
End User Type:
Customer maturity and procurement sophistication create distinct service requirements across this category.
- Brands:Direct advertiser relationships with creators, managed through in-house teams or platform tools. Enterprise CPG companies in the United States have completed organizational restructuring to embed this function within media planning.
- Agencies:Intermediary representation faces margin compression from self-serve discovery platforms. Traditional full-service models are pivoting toward creator strategy and measurement consulting.
- Nonprofits:Cause-driven partnerships leverage mission alignment for reduced rate negotiation. Disclosure requirements under FTC Endorsement Guides apply equally to charitable campaigns.
- Emerging Startups:Limited budgets force equity-for-promotion structures and performance-only compensation. Platform algorithmic shifts create existential campaign risk for unproven brands.
- Established Enterprises:Centralized always-on programs with dedicated operational staff and multi-year creator relationship contracts. Compliance infrastructure spans FTC, GDPR, and platform-native disclosure tools.
Concentrating procurement volume: Established Enterprises. Climbing the fastest: Emerging Startups leveraging AI content tools.
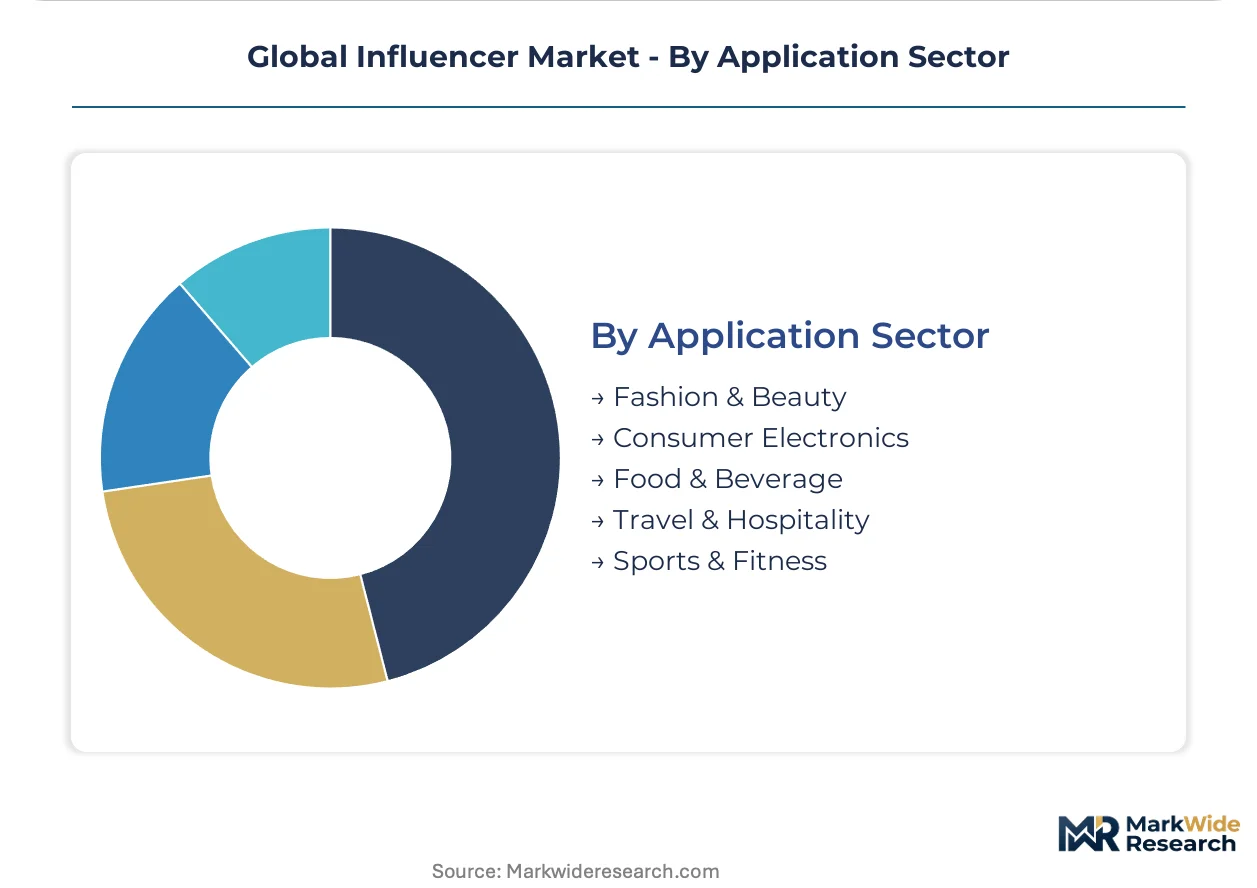
Application Sector:
Regulatory exposure and measurement standardization separate mature verticals from emerging adoption.
- Fashion & Beauty:Most mature sector with standardized performance metrics and established disclosure conventions. EU Digital Services Act compliance costs concentrate here due to multi-market campaign complexity.
- Consumer Electronics:Technical review formats demand platform-native expertise and extended production timelines. YouTube sustains dominant share for unboxing and tutorial content.
- Food & Beverage:Health claim restrictions and FDA disclosure requirements constrain messaging flexibility. Live-stream commerce adoption lags fashion but accelerates through TikTok Shop integration.
- Travel & Hospitality:Visual destination content performs on Instagram and Pinterest with seasonal demand volatility. Post-pandemic recovery has restored budget allocation to pre-crisis levels.
- Sports & Fitness:Athlete influencer partnerships intersect with NIL regulation and platform content policies. Supplement and apparel sub-verticals drive monetization concentration.
Highest revenue concentration: Fashion & Beauty. Steepest expansion trajectory: Food & Beverage through live-stream commerce infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Creator economy infrastructure concentrates where digital advertising spend and platform-native talent pools intersect, with the United States, China, United Kingdom, Germany, and Brazil representing distinct maturity archetypes.
United States
Fortune 500 marketing departments anchor enterprise procurement with dedicated creator strategy teams embedded in core media planning functions. FTC Endorsement Guides mandate clear disclosure of material connections, normalizing transparency protocols that reduce brand risk. Los Angeles and New York City sustain the densest creator talent clusters, where specialized video editing and platform-native storytelling skills command premium compensation.
China
Live-stream commerce infrastructure has professionalized real-time product demonstration and instant purchase conversion at unmatched scale. SAMR enforces advertising law compliance that creates exportable operational templates for other markets. Shanghai and Hangzhou concentrate the technical talent and platform engineering resources that power ByteDance's algorithmic distribution systems.
United Kingdom
London's advertising heritage produces sophisticated agency intermediaries now pivoting toward creator strategy consulting as self-serve platforms compress margins. GDPR enforcement on automated decision-making tightens consent requirements for algorithmic content recommendation. The city's fintech and professional services verticals remain underpenetrated by creator partnerships relative to consumer categories.
Germany
Industrial and automotive brands allocate substantial digital budgets toward creator partnerships with standardized performance metrics. EU Digital Services Act transparency mandates on content amplification accelerate enterprise budget commitments to creator channels. Berlin's startup ecosystem incubates specialized influencer marketing technology providers serving mid-market segments.
Brazil
Rising platform penetration and underdeveloped agency representation create first-mover advantage for localized content production networks. General functional oversight from the country's national advertising regulator applies disclosure requirements to sponsored content. São Paulo anchors the largest creator talent concentration in Latin America, with Portuguese-language content serving export markets across Portugal and Africa.
Global Influencer Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in AI-assisted content generation and cross-platform attribution. The vendor base distributes across social media management suites, e-commerce integration specialists, and self-serve discovery platforms. Three strategic archetypes dominate: enterprise campaign orchestration tools, direct-to-purchase attribution systems, and mid-market agency displacement platforms. Competitive moves concentrate on M&A for technology tuck-ins and strategic partnerships with retail media networks.
Within the enterprise orchestration tier, Sprout Social, Inc. and CreatorIQ exemplify the shift toward unified campaign management for centralized always-on programs. Grin Technologies Inc. occupies a position among e-commerce integration specialists, connecting creator content directly to purchase attribution. These three entities anchor the competitive structure, representing distinct bets on whether brands prioritize workflow consolidation, conversion measurement, or talent relationship depth.
| Leading Market Players |
|---|
| Sprout Social, Inc. |
| Grin Technologies Inc. |
| Upfluence |
| AspireIQ, Inc. |
| Traackr, Inc. |
| Klear (Meltwater) |
| CreatorIQ |
| Brandwatch |
| Captiv8 |
| Others |
Supply & Pricing Matrix
Nano-creator rate compression versus celebrity premium retention creates a bifurcated cost structure that reshapes both procurement budgets and talent sourcing geography. Brands pursuing engagement depth absorb higher per-creator administrative overhead for micro-segment relationships, while consolidated enterprise programs extract volume discounts from macro-tier rate cards that reflect Los Angeles and New York talent cluster scarcity.
Pricing Analysis
Usage rights bundling separates campaign-based transactional pricing from always-on retainer structures with embedded exclusivity clauses. SaaS-tiered platform subscriptions dominate mid-market discovery tools, while enterprise orchestration commands premium-mid-economy pricing differentiation based on API integration depth and cross-platform analytics granularity. Pricing pressure stems from algorithmic distribution uncertainty that compresses campaign margin predictability. Emerging startups exhibit highest price sensitivity; established enterprises absorb premium tiers for compliance infrastructure and dedicated account management.
Supply Chain Analysis
Direct-to-brand channels handle hyperscale buyer demand through self-serve discovery platforms that displace traditional agency intermediaries. Creator talent concentrates in the United States, China, and Brazil, with São Paulo anchoring Latin American Portuguese-language production capacity. Raw material dependencies span specialized video editing software, platform-native analytics tools, and cross-border payment infrastructure. Single-source vulnerability runs through TikTok and Meta algorithmic distribution control. Distribution runs through platform-native creator marketplaces and direct relationship management systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
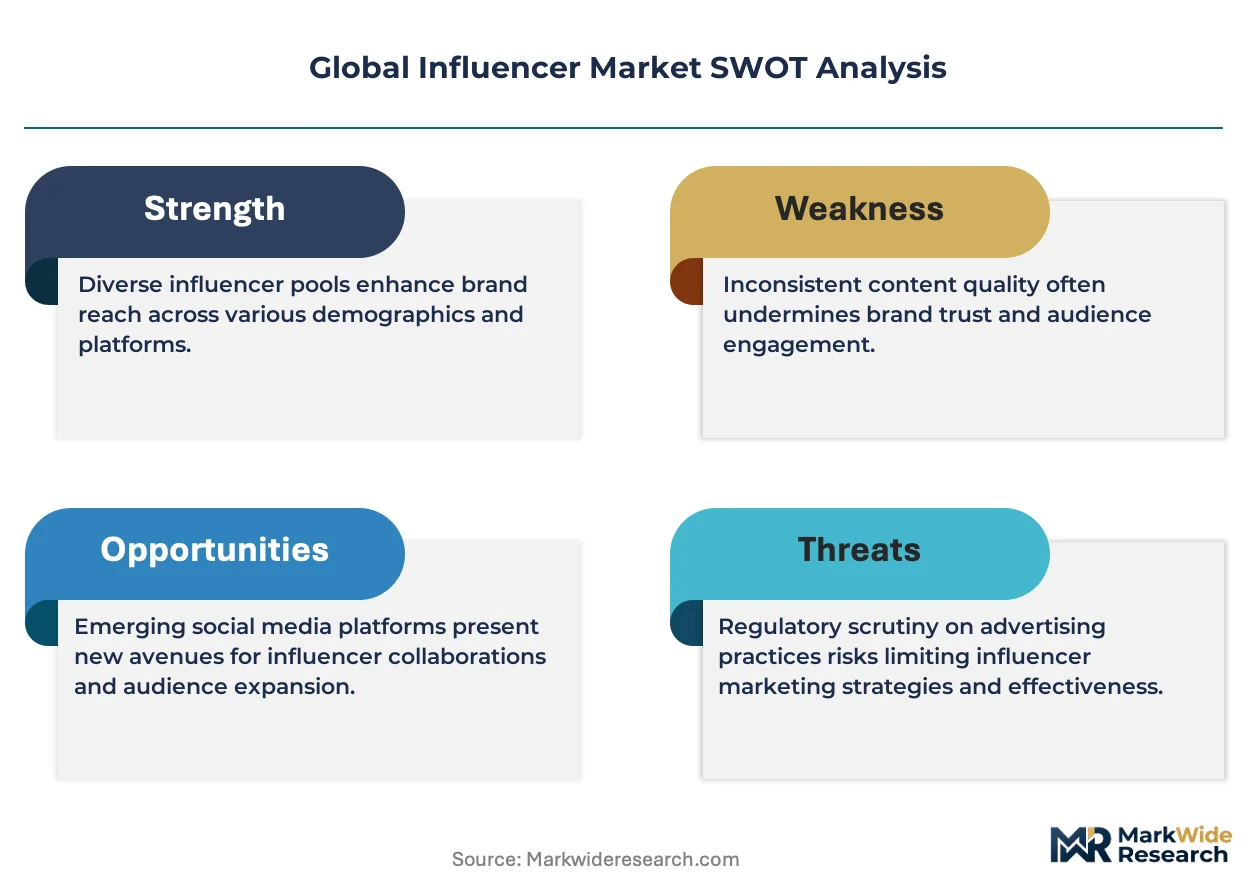
The Global Influencer Market operates as a cost-of-compliance story where EU Digital Services Act transparency mandates erect barrier-to-entry moats favoring enterprises with dedicated legal infrastructure and multi-jurisdiction operational capability.
For Market Incumbents: Hedge platform dependency risk by diversifying creator relationships across TikTok, Instagram, and YouTube rather than concentrating algorithmic exposure with single distributors. Invest in proprietary first-party data infrastructure to reduce GDPR-constrained audience portability friction. Vertical integration into in-house content production studios in Los Angeles and Berlin secures talent pipeline access against wage inflation in specialized video editing roles.
For New Entrants and Emerging Players: Capture underdeveloped B2B professional services verticals where SaaS and financial services segments remain penetrable relative to saturated consumer categories. Brazil's rising platform penetration and thin agency representation offers first-mover localization advantage for Portuguese-language content networks. Go-to-market execution should emphasize performance-only compensation structures that align creator incentives with conversion outcomes rather than vanity reach metrics.
For Investors and Strategic Acquirers: Re-rating potential sits with AI-assisted content generation platforms given emerging disclosure framework compliance advantages and algorithmic preference for synthetic media labeling transparency. Long-term viability favors technology providers serving mid-market segments with self-serve tools that compress agency margins and capture procurement decentralization trends. Signal to monitor: regulatory enforcement intensity on automated decision-making consent requirements across European markets.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Content Disclosure Compliance Investment | Early alignment with platform synthetic media labeling policies secures algorithmic distribution preference before mandate enforcement. |
| Cross-Platform Attribution Technology Development | Unified measurement dashboards address the technical constraints limiting ROI accuracy for multi-channel influencer strategies. |
| Live-Stream Commerce Infrastructure Export | China's SAMR-compliant operational templates transfer to Brazil and Southeast Asian markets with rising platform penetration. |
| Creator Talent Pipeline Localization | São Paulo and Berlin studio networks reduce dependency on Los Angeles and New York wage premiums for specialized production skills. |
| First-Party Data Infrastructure Buildout | Proprietary audience relationship systems mitigate GDPR data portability friction and enable direct creator-brand connections. |
Research Methodology
Independent corroboration across brand marketing executives, creator talent managers, platform policy leads, and regulatory affairs specialists underwrites the qualitative findings in this study. Primary interviews with Fortune 500 media planning directors, nano-creator community founders, and EU compliance officers combined with secondary validation from SEC filings of social media management SaaS providers, FTC enforcement action databases, and platform transparency reports. Bottom-up segment sizing triangulates against top-down digital advertising spend allocation data from national statistical agencies.
Comparable-period anchoring to historical reference periods spanning platform algorithmic shifts and regulatory enforcement waves structured the projection framework. The model segments by influencer tier, content platform, end user type, and application sector across the analysis window. CAGRs derive from trend extrapolation adjusted for saturation dynamics in mature verticals and infrastructure buildout trajectories in emerging markets. Forecast inputs incorporate live-stream commerce penetration rates and AI content tool adoption curves.
The model holds under stable platform algorithmic distribution policies and consistent regulatory enforcement intensity; deviation in major jurisdiction advertising law revisions or ByteDance/Meta strategic pivots would shift trajectory assumptions. Forecasts reflect documented base-case conditions subject to stress-testing. Periodic stress-testing of base assumptions is recommended given platform dependency concentration and cross-border payment complexity variables.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Social Media and Influencer Economy
Global Blogging Platforms Market
Social Media and Influencer Economy
Online Virtual Youtuber Model Market
Social Media and Influencer Economy
Content Creation Market
Social Media and Influencer Economy
Asia-Pacific User Generated Content Platform Market
Social Media and Influencer Economy
Influencer Marketing Platform Market
Social Media and Influencer Economy
Global Social Media Market
Social Media and Influencer Economy
Social Media Content Creation Market
Social Media and Influencer Economy
User Generated Content Platform Market
Social Media and Influencer Economy
Global Short Video Sharing Platform Market
Social Media and Influencer Economy
Metaverse Social Media Platforms Market
Social Media and Influencer Economy
LAMEA User Generated Content Platform Market
Social Media and Influencer Economy
Europe User Generated Content Platform Market
Social Media and Influencer Economy
Influencer Marketing Market
Social Media and Influencer Economy
Social Publishing Application Market
Social Media and Influencer Economy
Online Love Rush Market
Social Media and Influencer Economy
Photo Sharing Market