
 Virtual Content Creation Market | 2026-2036
Virtual Content Creation Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Content Creation Market Analytics
Shortages of prompt engineers and technical artists is reorganizing how production pipelines scale across the Virtual Content Creation Market. Genies leverages its avatar technology stack to sustain dominance in digital identity tooling for celebrities and brands. Wooshii anchors its competitive position through geographic concentration in London, where it controls a network of freelance video production talent. Kaedim differentiates by specializing in AI mesh generation that converts 2D inputs into production-ready 3D assets for game developers.
Virtual Content Creation encompasses the design, synthesis, and distribution of digital media assets through software platforms that employ procedural generation, neural rendering, and real-time compositing pipelines, typically outputting at 4K resolution or higher for immersive playback environments. The primary commercial purpose centers on reducing production latency and unit cost for marketing, entertainment, and educational media. Video content under the Content Type segment occupies the largest revenue pool due to entrenched advertiser budgets, while AI within the Technology segment represents the fastest-expanding margin category as inference costs decline and generative models mature. The End User segment shows Educators emerging as an underpenetrated cohort with rising procurement of interactive courseware.
The Federal Trade Commission and the European Union's AI Act framework jointly shape disclosure requirements for synthetic media, forcing platforms to label AI-generated outputs and maintain audit trails. Content authenticity standards from ISO and emerging national deepfake statutes are tightening product specifications for enterprise buyers. Stakeholders must monitor whether regulatory divergence between Washington and Brussels fragments platform compliance architectures or drives consolidation around interoperable transparency protocols.
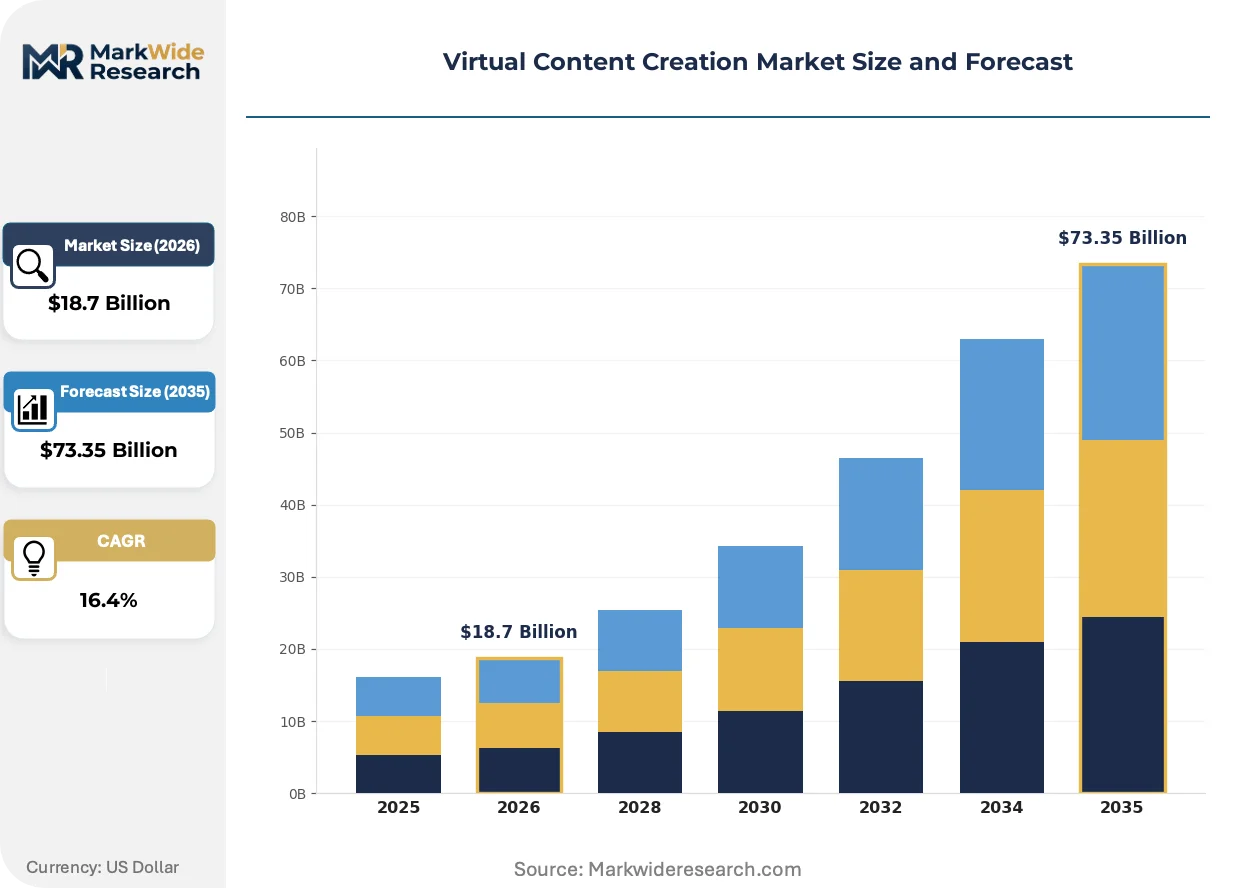
Market Dynamics
Neural rendering pipelines are compressing production timelines from weeks to hours, forcing studios to restructure asset creation workflows around real-time inference rather than traditional offline rendering farms.
Growth Catalysts
- EU AI Act disclosure mandates:Synthetic media labeling requirements are accelerating enterprise investment in provenance-tracking infrastructure to maintain platform eligibility across European markets.
- Procedural generation:Environment and texture synthesis tools are reducing manual artist hours by enabling automated variation at scale for open-world game development.
- Silicon Valley venture deployment:Concentrated funding flows into avatar engines and neural capture systems are expanding accessible tooling for mid-sized creator studios.
Market Restraints
- GPU cluster scarcity:Training and inference workloads for diffusion models face allocation bottlenecks at major cloud providers, throttling smaller studio access.
- Input cost volatility:Licensing fees for foundational model weights and training data corpora are experiencing unpredictable escalation as commercial usage terms tighten.
- Technical limitation:Current mesh generation from 2D inputs produces topology artifacts requiring manual cleanup, limiting true hands-off automation.
Strategic Opportunities
- Educational courseware:Interactive 3D instructional content remains underpenetrated across K-12 and vocational training institutions, representing greenfield deployment for immersive learning modules.
- Neural radiance fields + haptics:Convergence of NeRF-based environments with force-feedback hardware is opening spatial design applications for architectural visualization and retail.
- FTC disclosure guidance:Emerging transparency requirements for synthetic media create compliance service opportunities for platforms serving US-based advertisers and publishers.
Industry Challenges
- Prompt engineering scarcity:The specialized skill set bridging natural language inputs and controlled generative outputs commands premium compensation, constraining team scaling.
- Legacy pipeline integration:Existing asset management systems and version control workflows require substantial modification to accommodate non-deterministic AI-generated outputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Content Creation Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Video, Animation, Graphics, Text End User: Enterprises, Influencers, Educators, Marketers Delivery Platform: Web, Mobile, Social Media, Virtual Reality Technology: AI, AR, 3D Modeling, Cloud Computing |
| Companies Covered | Modash.io, Siege Media, Genies, Wooshii, uSERP, Kaedim, Padlet, Verblio, vidIQ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Content Creation Market Evolving Landscape
Generative workflows are fragmenting production roles and collapsing traditional department boundaries, as real-time synthesis tools enable simultaneous iteration across previously sequential disciplines.
Diffusion-based texture synthesis is bifurcating asset creation into high-fidelity hero production and automated background fill, with AAA studios adopting hybrid pipelines where neural tools handle environmental clutter while human artists concentrate on character and narrative elements, compressing overall art department headcount requirements without sacrificing output volume.
The EU AI Act's algorithmic transparency provisions are mandating technical documentation and audit trail maintenance for automated content systems, forcing platforms to embed provenance metadata at generation time, with marketing technology vendors in Germany and France accelerating compliance tooling development to preserve cross-border service eligibility.
Enterprise procurement of virtual content is migrating from per-asset licensing toward capacity-based subscriptions, with media buyers in Los Angeles and London negotiating unlimited generation tiers capped by compute hours rather than deliverable counts, displacing traditional freelance commission structures for recurring campaign work.
Virtual Content Creation Market Segmentation
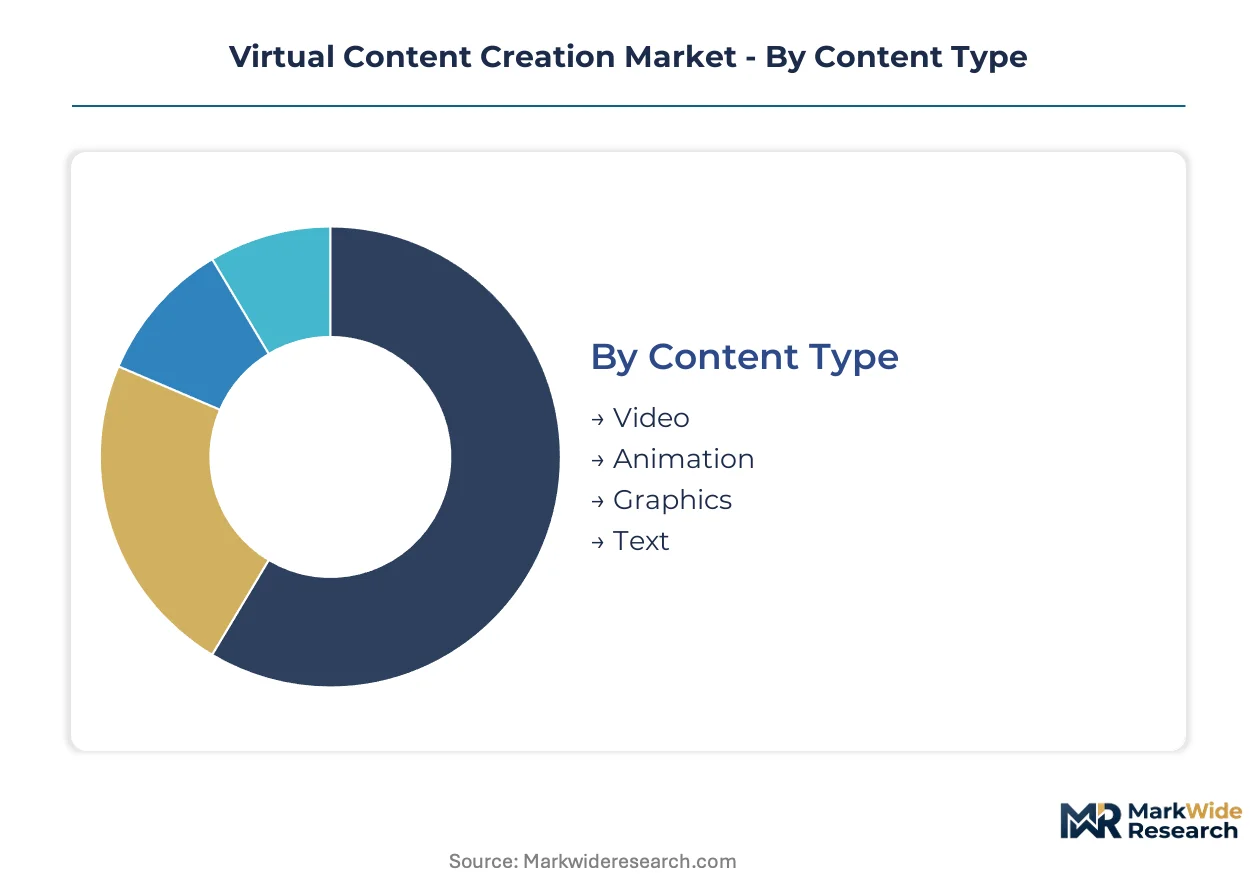
Segmentation in virtual content creation determines compliance architecture, compute procurement patterns, and talent allocation across production pipelines. Each dimension carries distinct regulatory exposure and margin profiles that reshape vendor positioning.
Content Type:
EU AI Act disclosure mandates apply asymmetrically across formats, with synthetic video facing stricter provenance documentation than static assets.
- Video:Synthesized footage at 4K+ resolution dominates advertiser procurement budgets. Los Angeles-based media buyers and London campaign studios drive volume for influencer marketing and branded documentary content, though FTC transparency requirements add compliance overhead.
- Animation:Procedural rigging and neural motion capture compress frame production timelines. Gaming studios in Tokyo and Vancouver concentrate demand for cinematic cutscenes and interactive character sequences, constrained by GPU cluster scarcity at major cloud providers.
- Graphics:Static visual assets for UI/UX and print-to-digital conversion.
- Text:Synthetic copy and localized narrative scripts for interactive media.
Video handles the majority of throughput; Animation is expanding most quickly on share.
End User:
Customer type dictates pricing tolerance, with enterprise procurement migrating toward capacity-based subscriptions rather than per-asset licensing.
- Enterprises:Fortune 500 marketing departments and internal creative agencies negotiate unlimited generation tiers capped by compute hours. Procurement concentrates among technology and retail verticals seeking campaign velocity at reduced unit cost.
- Marketers:Agency holding companies and independent performance marketing shops. Demand clusters in New York and Berlin for real-time A/B testing of synthetic creative variants, though input cost volatility for foundational model licensing squeezes margins.
- Influencers:Individual creators and talent-managed digital personalities monetizing avatar-driven content.
- Educators:K-12 districts and vocational training institutions represent greenfield deployment for interactive 3D courseware.
Enterprises contribute the dominant revenue pool; Educators show the steepest expansion trajectory.
Delivery Platform:
Hardware-software coupling determines rendering fidelity and latency requirements, with immersive environments demanding specialized optimization.
- Social Media:Short-form vertical video and ephemeral content formats optimized for algorithmic distribution. Meta and TikTok creator ecosystems in São Paulo and Jakarta concentrate volume, driving demand for real-time avatar generation and automated localization.
- Virtual Reality:Spatial computing environments requiring stereoscopic rendering and six-degrees-of-freedom interactivity. Enterprise training simulations and architectural visualization in Munich and Singapore anchor adoption, constrained by headset penetration rates.
- Web:Browser-based streaming and progressive web applications for cross-device accessibility.
- Mobile:Native iOS and Android applications leveraging on-device neural inference where permitted.
Social Media captures the largest addressable audience; Virtual Reality gains share fastest among immersive use cases.
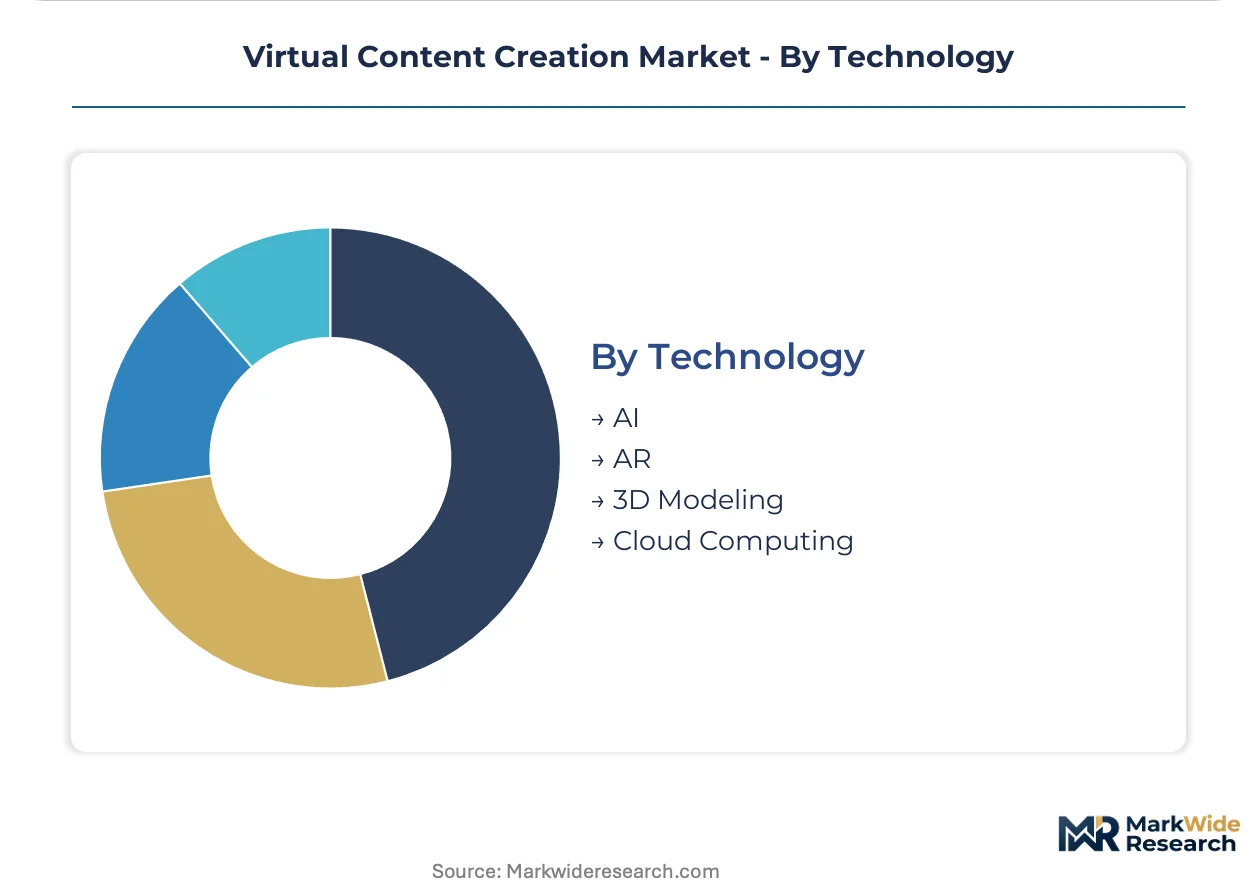
Technology:
Technology stack selection determines regulatory exposure under emerging algorithmic transparency frameworks and compute cost structures.
- AI:Diffusion models and transformer architectures for generative synthesis. Inference cost declines and model weight commercialization are expanding accessible tooling for mid-sized creator studios, though prompt engineering scarcity constrains team scaling.
- 3D Modeling:Mesh generation, photogrammetry, and neural radiance fields for spatial asset creation. Game development pipelines in Stockholm and Montreal concentrate demand, with topology artifacts from 2D-to-3D conversion requiring manual cleanup.
- AR:Spatial anchoring and real-world occlusion for mobile and wearable overlay experiences.
- Cloud Computing:Distributed rendering farms and elastic compute orchestration for burst production workloads.
AI commands the highest margin expansion; 3D Modeling underpins the largest installed base of production pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns in virtual content creation diverge sharply across geographies, with the United States prioritizing celebrity avatar monetization while European markets emphasize regulatory-compliant synthetic media infrastructure and Asian economies concentrate on gaming-optimized asset pipelines.
United States
Silicon Valley venture deployment and Los Angeles creator-economy infrastructure concentrate demand for neural capture systems and real-time avatar engines. The FTC's emerging transparency guidance for synthetic media shapes disclosure requirements for advertisers and publishers. New York-based media buyers negotiate capacity-based subscriptions for campaign velocity, displacing traditional freelance commission structures.
Germany
Enterprise training simulations and architectural visualization in Munich anchor adoption of spatial computing environments with force-feedback integration. The EU AI Act's algorithmic transparency provisions mandate technical documentation and audit trail maintenance for automated content systems. Marketing technology vendors in Berlin accelerate compliance tooling development to preserve cross-border service eligibility.
United Kingdom
London campaign studios and freelance video production networks drive volume for influencer marketing and branded documentary content. GDPR and emerging deepfake statutes tighten product specifications for enterprise buyers. The city's concentration of agency holding companies supports real-time A/B testing of synthetic creative variants for performance marketing.
Japan
Tokyo and Osaka gaming studios concentrate procurement for cinematic cutscenes and interactive character sequences using procedural rigging and neural motion capture. METI oversight of digital content standards influences platform specifications for immersive playback environments. Cloud provider GPU cluster scarcity constrains smaller studio access to training and inference workloads.
South Korea
Seoul-based metaverse architects and mobile-first creator platforms expand procurement of AI-generated assets for social media distribution. The country's national content regulator monitors synthetic media disclosure standards alongside international frameworks. Busan-Ulsan industrial clusters experiment with NeRF-based environments for retail and architectural visualization applications.
Virtual Content Creation Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the market structure bifurcating between avatar-engine platforms and AI-mesh generation tools. Consolidation pressure concentrates among venture-backed tooling providers seeking geographic expansion and enterprise channel access. Three strategic archetypes dominate: celebrity-focused digital identity stacks, freelance-network video production platforms, and 2D-to-3D conversion specialists for game pipelines. Competitive moves center on strategic partnerships with cloud providers and portfolio diversification into adjacent compliance services.
Within the avatar-technology tier, Genies exemplifies positioning around celebrity and brand digital identity tooling. Wooshii anchors the freelance-network archetype through London-based geographic concentration. Kaedim occupies the AI-mesh specialization vector, representing the 2D-to-3D conversion category for game development pipelines.
| Leading Market Players |
|---|
| Modash.io |
| Siege Media |
| Genies |
| Wooshii |
| uSERP |
| Kaedim |
| Padlet |
| Verblio |
| vidIQ |
| Others |
Value Network & Pricing Analysis
GPU cluster utilization rates at hyperscale facilities determine cost floors across the Virtual Content Creation Market, concentrating supply leverage among cloud providers in the United States while compressing margins for mid-sized studios dependent on spot compute allocation.
Pricing Analysis
Long-term capacity reservations dominate enterprise procurement, with Fortune 500 marketing departments negotiating unlimited generation tiers capped by compute hours rather than deliverable counts. Three-tier pricing structure across premium, standard, and economy levels separates dedicated inference clusters from shared infrastructure and on-device rendering. Cost compression in the standard tier is intensifying because licensing fees for foundational model weights experience unpredictable escalation. Enterprise buyers show the least price sensitivity due to campaign velocity requirements, while independent creators face the highest budget constraints.
Supply Chain Analysis
Inventory buffers for high-performance GPU hardware stretch to sixteen weeks at major distributors, constraining burst capacity for studios facing production deadlines. Supply concentrates in Taiwan for advanced semiconductor fabrication, the United States for cloud orchestration platforms, and South Korea for memory components. Raw material dependencies span NVIDIA H100 accelerators, high-bandwidth memory stacks, and specialized optical interconnects. Single-source vulnerability around TSMC's leading-edge node production creates systemic exposure. Distribution runs through hyperscaler direct contracts and authorized reseller channels serving mid-market buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among agency holding companies and enterprise procurement teams, with consolidation in Los Angeles and London campaign studios enabling volume-based negotiation leverage that displaces traditional freelance commission structures.
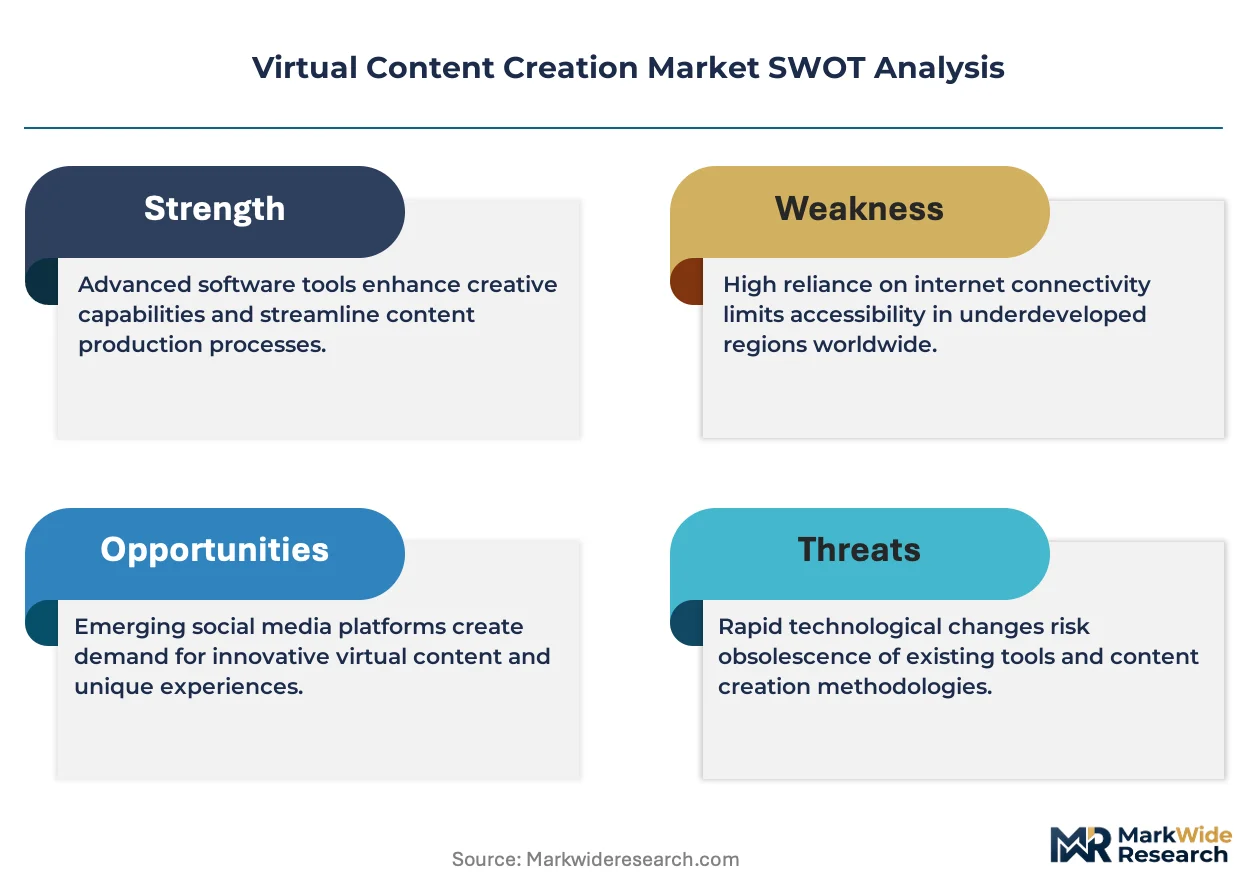
For Market Incumbents: Secure exclusive cloud provider partnerships to lock in GPU cluster allocation ahead of mid-sized competitors facing allocation bottlenecks. Invest in provenance-tracking infrastructure to maintain platform eligibility under EU AI Act disclosure mandates. Acquire specialized prompt engineering teams to address capability scarcity constraining production scaling.
For New Entrants and Emerging Players: Anchor in educational courseware deployment, where K-12 districts and vocational institutions represent greenfield demand for interactive 3D instructional content with limited incumbent saturation. Target Germany and France for compliance tooling development serving cross-border service eligibility requirements. Pursue channel partnerships with learning management system vendors rather than direct enterprise sales.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among avatar-engine platforms serving celebrity and brand digital identity tooling, where subscription retention exceeds project-based creative services. Prioritize targets with embedded provenance metadata capabilities aligned with emerging FTC transparency guidance. Monitor GPU cluster allocation announcements from hyperscalers as the critical inflection signal for downstream capacity expansion viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Provenance Infrastructure Investment | EU AI Act compliance preserves cross-border platform eligibility for German and French marketing technology vendors. |
| Cloud Provider Partnership | Exclusive GPU cluster allocation agreements secure inference capacity ahead of mid-sized studio competitors. |
| Educational Channel Expansion | LMS integrations unlock K-12 procurement budgets for interactive 3D courseware with limited incumbent presence. |
| Prompt Engineering Acquisition | Specialized talent pools bridge natural language inputs and controlled generative outputs for production scaling. |
| Neural Radiance Field Integration | NeRF-based environments with haptics enable spatial design applications for Munich architectural visualization clients. |
Research Methodology
A standing panel of CTOs at gaming studios, AI research leads at avatar platforms, procurement officers at agency holding companies, and cloud infrastructure specialists provided ongoing calibration across the analysis window. Primary interviews with these stakeholders combined with secondary validation against SEC filings from hyperscalers, App Annie mobile content consumption data, and EU regulatory transparency databases. Bottom-up segment sizing triangulated against top-down market envelope estimates derived from venture deployment tracking.
Consistency checks validated volume and value outputs against external benchmarks including hyperscaler capex disclosures and creator-economy platform revenue segments. The analytical framework modeled deployment model, organization size, vertical application, integration complexity, and regional adoption pattern across the projection horizon. CAGRs derived from segment-level growth rate synthesis incorporating inference cost decline curves and regulatory implementation timelines.
Material uncertainties — GPU cluster allocation volatility, foundational model licensing term changes, and regulatory divergence between Washington and Brussels — sit outside the modeled envelope. Forecasts reflect assumptions about technology maturation and compliance trajectory without claiming predictive certainty. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Social Media and Influencer Economy
Global Influencer Market
Social Media and Influencer Economy
User Generated Content Platform Market
Social Media and Influencer Economy
Asia-Pacific User Generated Content Platform Market
Social Media and Influencer Economy
Online Virtual Youtuber Model Market
Social Media and Influencer Economy
Global Short Video Sharing Platform Market
Social Media and Influencer Economy
Global Blogging Platforms Market
Social Media and Influencer Economy
Metaverse Social Media Platforms Market
Social Media and Influencer Economy
Online Love Rush Market
Social Media and Influencer Economy
Social Publishing Application Market
Social Media and Influencer Economy
Virtual Influencer Market
Social Media and Influencer Economy
Photo Sharing Market
Social Media and Influencer Economy
LAMEA User Generated Content Platform Market
Social Media and Influencer Economy
Influencer Marketing Platform Market
Social Media and Influencer Economy
Social Media Content Creation Market
Social Media and Influencer Economy
Europe User Generated Content Platform Market
Social Media and Influencer Economy
Influencer Marketing Market