
 Asia-Pacific User Generated Content Platform Market | 2026-2036
Asia-Pacific User Generated Content Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific User Generated Content Platform Market Insights
Chinese short-video infrastructure is consolidating around Beijing and Hangzhou technology corridors, drawing engineering talent and cloud compute investment into concentrated clusters. TikTok leverages algorithmic content distribution to sustain engagement across Southeast Asian markets. Kuaishou anchors live-commerce functionality in lower-tier Chinese cities where creator monetization through virtual gifting dominates. YouTube competes through premium creator programs that extend revenue-sharing models into Indian and Australian markets.
User Generated Content Platforms comprise digital systems enabling non-professional creators to publish, distribute, and monetize original text, image, video, and audio material through algorithmic curation and social graph propagation. These platforms operate on real-time content moderation pipelines, edge-cached delivery networks, and programmatic advertising insertion to serve both creator livelihoods and brand marketing objectives. Video content type captures the largest share of engagement minutes as bandwidth costs decline across Indonesia, Philippines, and Vietnam. Social media platform type generates disproportionate ad revenue through feed-based native advertising formats that blend creator posts with sponsored content. Enterprise user type represents the fastest-expanding segment as brands deploy white-label UGC tools for testimonial aggregation and product review syndication.
Australia's eSafety Commissioner enforces takedown protocols under the Online Safety Act that increase compliance expenditure for foreign platform operators serving Australian minors. Japan's Ministry of Internal Affairs and Communications applies telecommunications business law provisions requiring content provider registration and transparency reporting from large-scale UGC services. India's Information Technology Rules mandate traceability and grievance officer appointment, reshaping how platforms structure local legal entities and data residency. Stakeholders must monitor evolving cross-border data flow restrictions and creator payment localization requirements as regulatory fragmentation intensifies across the region's heterogeneous digital economies.
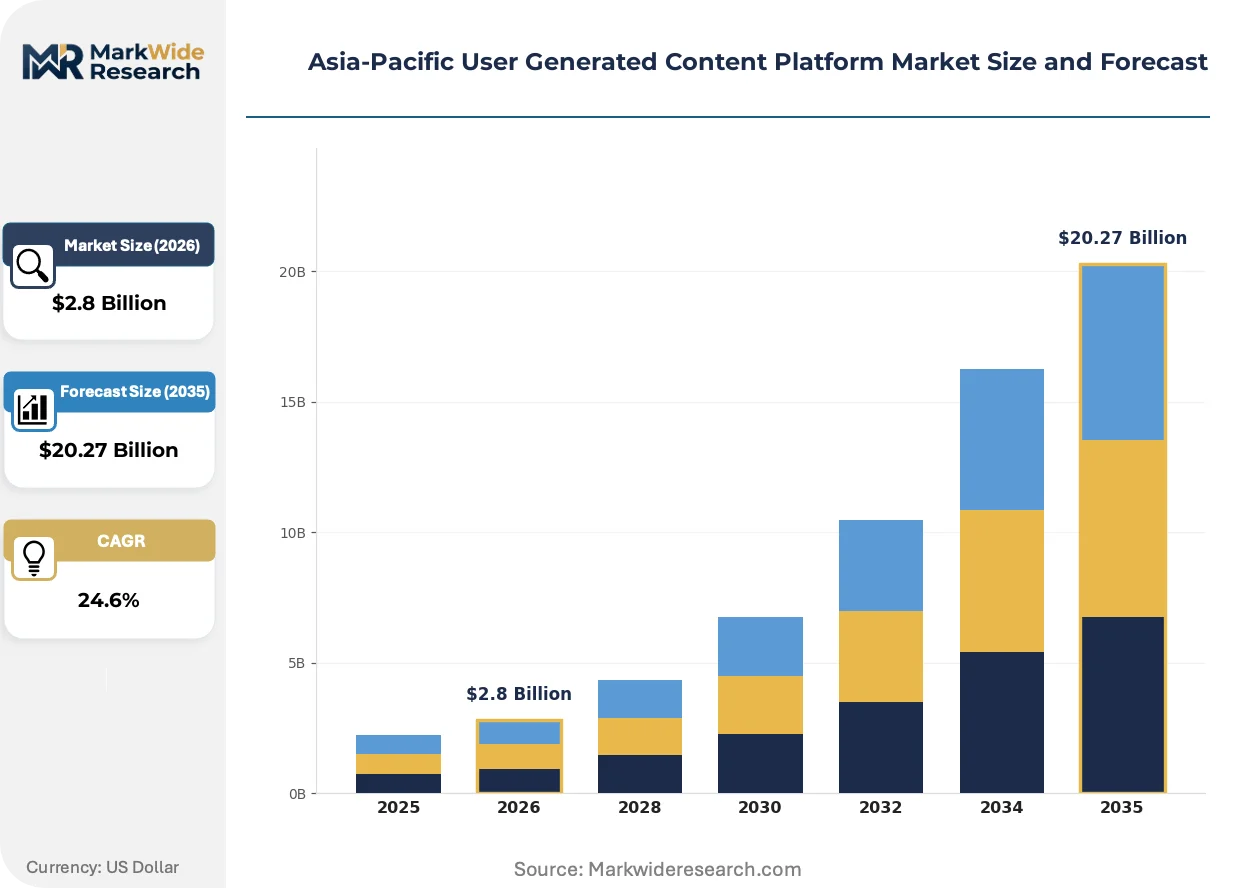
Market Dynamics
Live-stream commerce integration with social media interfaces is compressing the path between content consumption and transaction completion across Southeast Asian markets. This structural shift forces platforms to rebuild their backend infrastructure around real-time payment processing and inventory synchronization.
Growth Catalysts
- India's IT Rules:Mandated grievance officer appointment and traceability requirements create compliance barriers that favor established platforms with legal entity infrastructure already in place.
- Enterprise testimonial aggregation:Brands across Australia and Japan deploy white-label UGC tools for product review syndication, expanding platform revenue beyond advertising.
- Cloud compute clustering:Engineering talent concentration in Beijing and Hangzhou technology corridors accelerates algorithmic content distribution development cycles.
Market Restraints
- Cross-border data flow restrictions:Fragmented localization requirements across Indonesia, Vietnam, and the Philippines force redundant data residency investments.
- Content moderation cost escalation:Australia's Online Safety Act takedown protocols increase operational expenditure for foreign operators serving minors.
- Bandwidth infrastructure gaps:Last-mile connectivity limitations in Philippine and Indonesian archipelagos constrain video upload quality and live-stream stability.
Strategic Opportunities
- Japan's telecommunications oversight:Content provider registration requirements create first-mover advantages for compliant platforms in a market with high creator monetization rates.
- Lower-tier Chinese city live-commerce:Virtual gifting monetization models proven in Kuaishou's ecosystem transfer to Southeast Asian markets with similar income demographics.
- Edge-cached delivery networks:CDN infrastructure partnerships with local telecom operators in Vietnam and Indonesia reduce latency for real-time interactive features.
Industry Challenges
- Multilingual content moderation:Real-time detection across Tagalog, Bahasa Indonesia, Thai, and Vietnamese dialects strains NLP pipeline accuracy and human review scaling.
- Creator payment localization:Cross-border remittance friction and tax withholding complexity delay payout cycles, eroding creator retention in competitive markets.
- Algorithmic transparency mandates:Australia's eSafety Commissioner and Japan's MIC disclosure requirements expose proprietary recommendation systems to competitive reverse-engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific User Generated Content Platform Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $20.27 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Text, Images, Videos, Audio Platform Type: Social Media, Blogging, Forums, Review Sites User Type: Individual Creators, Brands, Influencers, Enterprises Monetization Model: Ad Revenue, Subscription, Sponsorship, Donations |
| Companies Covered | Yotpo, Pixlee, TikTok, CrowdRiff, Stackla, Kuaishou, Bazaarvoice, Curalate, YouTube, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific User Generated Content Platform Market Trends and Innovations
Generative AI tools are embedding into creator workflows across the Asia-Pacific region, compressing production timelines from days to hours. This technological infusion is reshaping platform competitive positioning around AI-native feature sets rather than distribution scale alone.
Real-time content moderation pipelines are automating the detection of policy violations in live-stream environments. Platforms serving India's multilingual creator base deploy these systems to manage grievance officer caseloads under IT Rules mandates. The structural consequence is automating the shift of trust-and-safety headcount from reactive review to proactive model training.
Japan's telecommunications business law provisions now require transparency reporting from large-scale UGC services above defined user thresholds. Platform operators must disclose content removal volumes and government takedown requests quarterly. Enterprise user segments in Australia and Japan face the steepest compliance documentation burdens as they white-label platform infrastructure.
Brand procurement of UGC tools is fragmenting across specialized use cases rather than consolidating on full-stack platforms. Testimonial aggregation, influencer campaign management, and product review syndication now route through distinct vendor relationships. This pattern is most visible in Australian and Indian markets where marketing technology stacks matured earlier.
Asia-Pacific User Generated Content Platform Market Segmentation
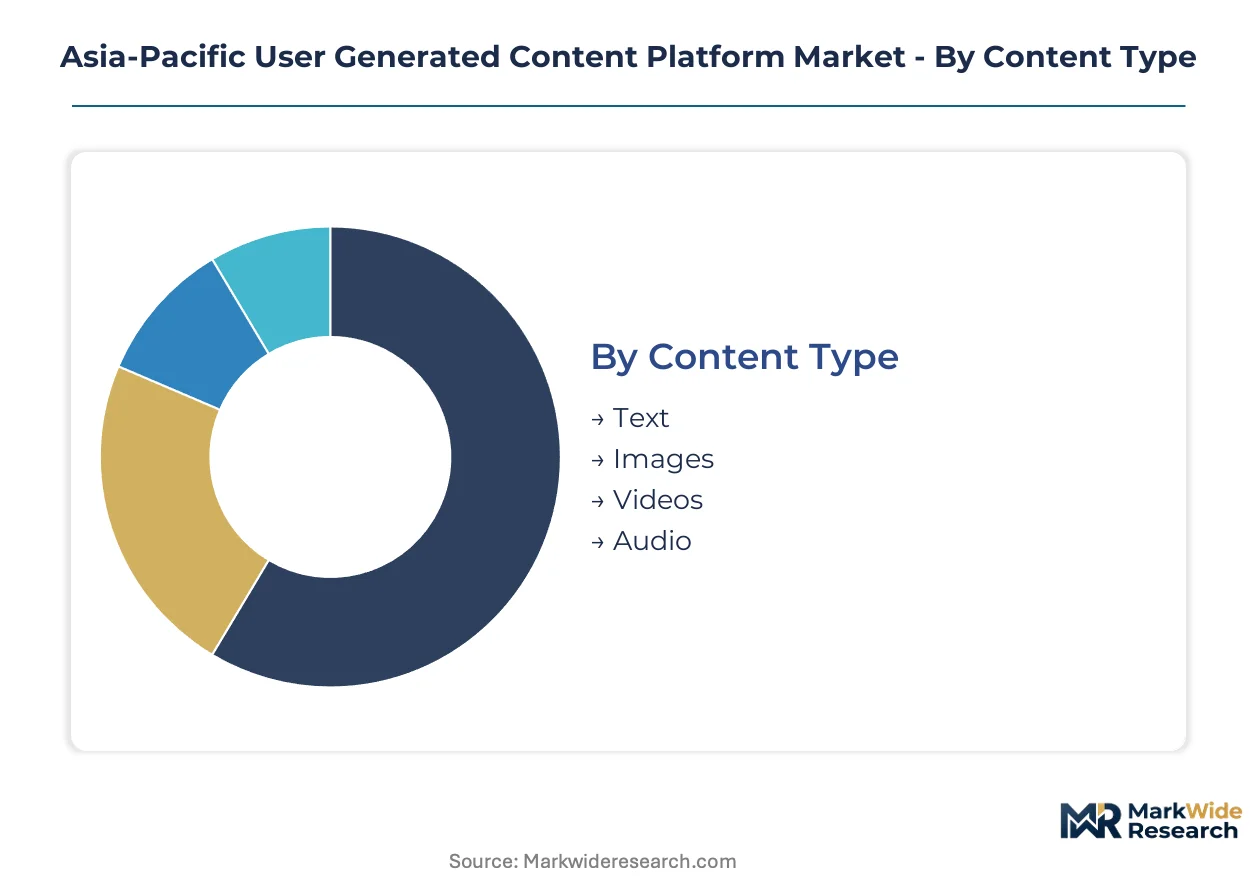
Content type, platform architecture, user identity, and revenue mechanics each reshape infrastructure investment and regulatory exposure for operators across Asia-Pacific. Platform engineering teams prioritize segments with live-stream latency requirements and cross-border payment complexity.
Content Type:
Resolution and compression standards differentiate bandwidth provisioning requirements across platform data centers.
- Videos:H.265 and AV1 encoding reduce bitrates for 1080p streams across Indonesian and Philippine mobile networks. Live-commerce broadcasters in Vietnam and Thailand drive edge server deployment to minimize frame drops during flash sales.
- Images:WebP and HEIC formats cut storage costs for e-commerce catalog syndication. Australian and Japanese brands deploy AI-powered background removal tools for product photography at scale.
- Text:Character-based scripts in Chinese, Japanese, and Korean demand specialized tokenization pipelines for content moderation NLP systems.
- Audio:Podcast and voice-note formats concentrate in Indian commuter markets with low data allowances, compressing files through Opus codecs.
Mature deployment sits with video infrastructure. Newer deployment is concentrated in audio-native formats for vernacular language markets.
Platform Type:
Interface architecture determines advertising inventory format and creator tool complexity.
- Social Media:Feed algorithms prioritize dwell time metrics that reward short-form vertical video. Southeast Asian operators integrate shopfront modules directly into scrollable interfaces, collapsing discovery-to-purchase friction.
- Blogging:Long-form text platforms retain search-optimized content for B2B thought leadership in Australian professional services. SEO dependency constrains monetization to display advertising and affiliate commissions.
- Forums:Thread-based discussion architectures persist in Japanese niche hobby communities and Indian technical support ecosystems. Moderation costs scale with nested reply depth.
- Review Sites:Structured rating schemas aggregate user feedback for hospitality and electronics purchases across Singapore and Hong Kong. Fake review detection consumes machine learning resources disproportionately.
Revenue concentration favors social media feed advertising. Technical complexity peaks in review site integrity systems.
User Type:
Entity scale shapes compliance burden and platform service tier allocation.
- Enterprises:White-label UGC aggregation tools syndicate customer testimonials across Australian and Japanese e-commerce properties. Legal departments mandate data residency guarantees and audit trails for testimonial provenance.
- Brands:Campaign management dashboards track influencer post performance across multiple platform APIs. Procurement teams in India negotiate volume-based creator access fees.
- Influencers:Mid-tier creators with 100,000 to 1 million followers generate disproportionate engagement-per-follower ratios in Indonesian and Vietnamese markets. Platform algorithm changes destabilize income predictability.
- Individual Creators:Hobbyist uploaders populate long-tail content libraries with minimal monetization intent. Storage cost subsidies from platform operators sustain this segment at negative marginal revenue.
Compliance infrastructure investment concentrates with enterprise accounts. Creator acquisition spending targets the influencer tier.
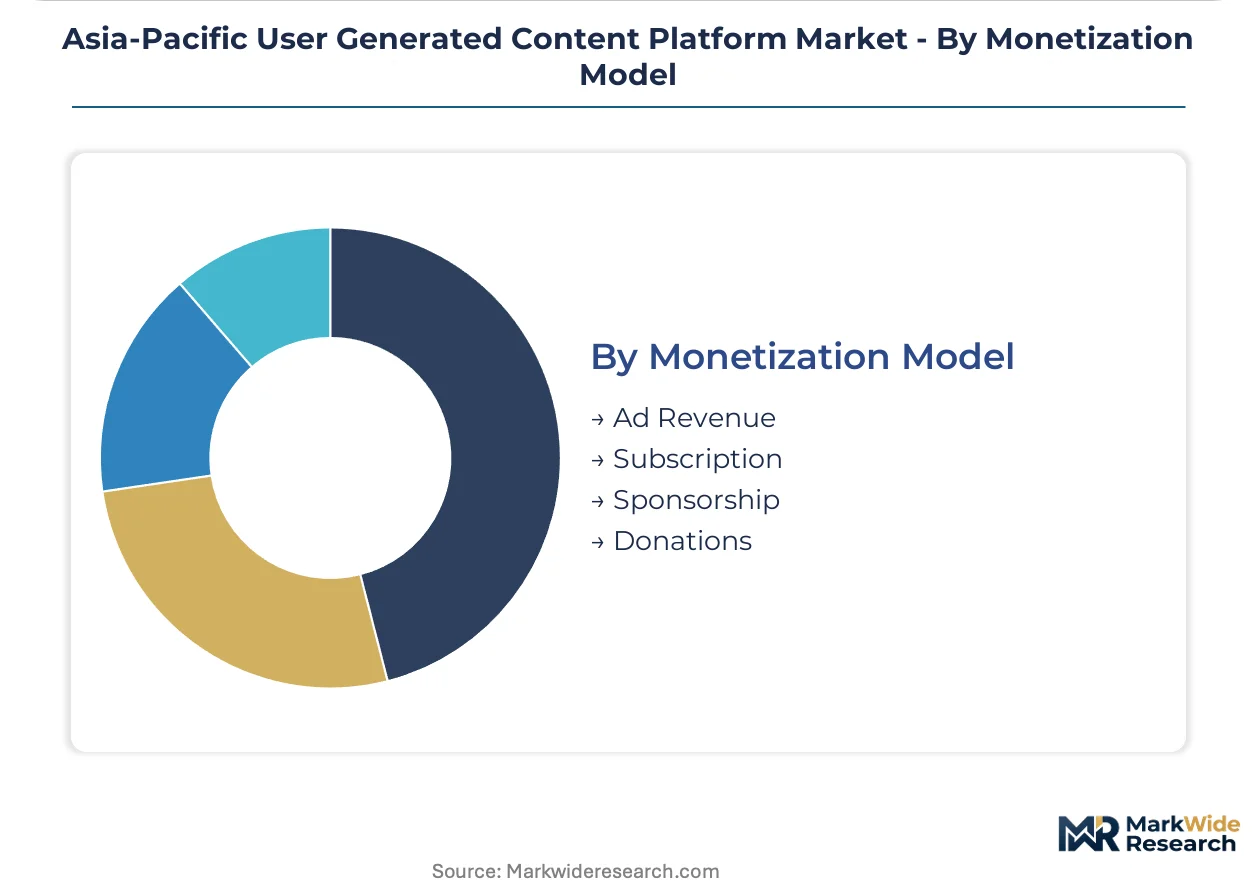
Monetization Model:
Revenue recognition timing and payment rail dependencies vary across collection mechanisms.
- Ad Revenue:Programmatic insertion through real-time bidding exchanges dominates Southeast Asian platform economics. Brand safety filters block inventory adjacent to unmoderated live streams.
- Subscription:Recurring billing relationships reduce churn through annual prepayment discounts in Australian and Japanese markets. Payment processor fees erode margin on low-price tiers.
- Sponsorship:Direct brand-creator contracts bypass platform revenue shares in India's influencer economy. Contract enforcement relies on informal reputation mechanisms rather than platform mediation.
- Donations:Virtual gifting mechanics in Chinese live-stream platforms transfer to Philippine and Indonesian markets with similar income demographics. Cross-border remittance friction delays creator payout cycles.
Operational maturity clusters around advertising technology stacks. Subscription billing systems are expanding most quickly in markets with established digital payment infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud compute investment clusters around Beijing and Hangzhou technology corridors anchor platform engineering capacity across Asia-Pacific. Live-stream commerce infrastructure draws capital into Southeast Asian data center zones. Regulatory divergence between Australia's eSafety Commissioner mandates and India's IT Rules traceability requirements fragments compliance architecture.
China
Short-video algorithm development concentrates engineering talent in Beijing and Hangzhou corridors where Kuaishou anchors live-commerce functionality. MIIT cloud service licensing requirements shape data residency for platform operators serving domestic creators. Lower-tier city virtual gifting monetization models from these clusters now transfer to Southeast Asian markets.
India
Creator economy expansion drives platform adoption as mid-tier influencers generate disproportionate engagement-per-follower ratios in vernacular language markets. IT Rules grievance officer mandates and traceability requirements reshape local legal entity structures for foreign operators. Bengaluru and Mumbai host the technical infrastructure for real-time content moderation NLP pipelines.
Japan
High creator monetization rates attract platform investment despite stringent telecommunications business law oversight from MIC. Content provider registration requirements above defined user thresholds create first-mover advantages for compliant operators. Tokyo and Osaka metropolitan areas concentrate enterprise white-label UGC tool procurement for testimonial aggregation.
Australia
eSafety Commissioner enforcement of Online Safety Act takedown protocols elevates compliance expenditure for foreign platforms serving minors. Enterprise testimonial aggregation demand from Sydney and Melbourne marketing technology stacks drives white-label UGC tool adoption. Local data residency guarantees become procurement prerequisites for brand legal departments.
Indonesia
Live-stream commerce integration with social media interfaces compresses discovery-to-purchase friction across Jakarta and Surabaya metropolitan zones. Cross-border data flow restrictions force redundant infrastructure investment alongside local telecom CDN partnerships. Bandwidth cost declines enable 1080p stream proliferation despite last-mile connectivity gaps in outer archipelago regions.
Asia-Pacific User Generated Content Platform Market Competitive Landscape
Global majors compete with regional champions across algorithmic distribution and live-commerce infrastructure dimensions. Market structure tilts toward consolidated short-video platforms with concentrated engineering talent, while white-label enterprise tools fragment across specialized use cases. Three archetypes dominate: algorithm-native distribution platforms, live-commerce specialists, and enterprise testimonial aggregators. Competitive moves center on edge server deployment partnerships and creator monetization feature licensing.
Within the algorithm-native tier, TikTok and Kuaishou exemplify divergent geographic concentration strategies. TikTok leverages Southeast Asian market penetration through feed-based engagement optimization. Kuaishou occupies a position anchored in lower-tier Chinese city live-commerce with virtual gifting mechanics. Among enterprise-focused operators, Yotpo and Bazaarvoice sit within the testimonial aggregation archetype serving Australian and Japanese brand procurement teams with compliance documentation capabilities.
| Leading Market Players |
|---|
| Yotpo |
| Pixlee |
| TikTok |
| CrowdRiff |
| Stackla |
| Kuaishou |
| Bazaarvoice |
| Curalate |
| YouTube |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up enterprise testimonial aggregators now control pricing discipline across Australian and Japanese brand procurement markets, linking bundled compliance documentation to annual contract value escalators while compressing creator payout margins through standardized SaaS tiers.
Pricing Analysis
Service-bundling separates platforms offering end-to-end content moderation, legal entity registration, and grievance officer support from unbundled self-serve tiers targeting individual creators. Three-tier pricing structure across premium, standard, and economy levels maps to enterprise white-label deployment, mid-tier influencer tool access, and hobbyist upload functionality. Price differentiation rests on data residency guarantees and audit trail depth for enterprise legal departments. Pricing pressure stems from cross-border remittance friction eroding creator retention. Individual creators exhibit highest price sensitivity; enterprise legal departments show lowest sensitivity due to compliance risk exposure.
Supply Chain Analysis
Engineering talent availability in Beijing and Hangzhou technology corridors anchors algorithm development clusters, while cloud compute provisioning concentrates through Singapore and Tokyo data center zones. Raw material dependencies span NVIDIA GPU allocations for training infrastructure, edge server hardware from Taiwanese ODMs, and submarine cable bandwidth across Southeast Asian archipelagos. Supply chain risk centers on single-source vulnerability in AI chip procurement from US-based designers. Distribution runs through local telecom CDN partnerships in Indonesia and Vietnam to reduce last-mile latency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific UGC platform market sits in a technology-transition phase as generative AI tools displace manual content production workflows across creator economies.
For Market Incumbents: Deepen vertical integration into edge-cached delivery infrastructure through exclusive CDN partnerships with Indonesian and Vietnamese telecom operators. Incumbent platforms face displacement risk from AI-native entrants offering automated video generation at fractional production cost. Prioritize certification investment in Japan's MIC content provider registration to lock in first-mover compliance advantages. For New Entrants and Emerging Players: AI-native moderation tools offer a technology-first wedge into Australia's eSafety Commissioner-mandated compliance market where legacy platforms carry reactive review cost burdens. White-space concentration sits in Philippine and Indonesian vernacular-language NLP pipelines where detection accuracy lags. Go-to-market angle targets mid-tier influencer agencies seeking automated grievance case management under India's IT Rules. For Investors and Strategic Acquirers: Distressed-cycle entries favor distressed enterprise testimonial aggregators in Australian marketing technology stacks where brand procurement budget freezes compress valuations. Long-term viability frames around 5-10 year regulatory fragmentation deepening localization requirements. Acquisition target archetype: compliant platforms with existing MIC registration and eSafety Commissioner audit history. Signal to watch: creator payout cycle delays exceeding 45 days as indicator of platform liquidity stress.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Live-commerce module embedding collapses discovery-to-purchase friction in Jakarta and Surabaya metropolitan zones. |
| Geographic Expansion | Lower-tier Chinese city virtual gifting models transfer to Philippine and Indonesian markets with parallel income demographics. |
| Strategic Partnership | Local telecom CDN alliances in Vietnam reduce latency for real-time interactive features below 200 milliseconds. |
| Acquisition of Specialist Firm | Vernacular NLP pipeline targets address moderation cost escalation across Tagalog and Bahasa Indonesia content volumes. |
| Product Launch | Generative AI production tools compress creator timelines from days to hours across Indian and Southeast Asian markets. |
Research Methodology
Document review covered platform transparency reports, telecommunications business law filings, and eSafety Commissioner enforcement actions, complemented by interviews with platform trust-and-safety directors, creator economy monetization leads, enterprise brand procurement managers, and cloud infrastructure architects. Secondary validation drew from SEC filings of listed platform operators, App Annie engagement metrics, hyperscaler capex disclosures, and IT Rules compliance filings with India's Ministry of Electronics and Information Technology. Bottom-up segment sizing triangulated against top-down regional digital advertising forecasts.
Historical growth trajectories cross-referenced against expert panel input on regulatory implementation timelines and bandwidth cost decline curves. Segmentation modeling spanned content type resolution requirements, platform interface architecture, user entity scale, and monetization mechanism revenue recognition timing. CAGRs derived from algorithmic content distribution penetration rates and live-stream commerce transaction velocity across the analysis window. Forecast inputs incorporated edge server deployment partnership announcements and creator fund allocation disclosures.
Several conditions sit outside the modeled scope, including sovereign cloud mandates not yet promulgated, submarine cable disruptions from geostrategic incidents, and generative AI copyright liability rulings pending in Australian and Japanese courts. Forecasts reflect documented assumptions on regulatory enforcement intensity and infrastructure investment continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Social Media and Influencer Economy
Global Blogging Platforms Market
Social Media and Influencer Economy
Global Social Media Market
Social Media and Influencer Economy
Virtual Content Creation Market
Social Media and Influencer Economy
Online Virtual Youtuber Model Market
Social Media and Influencer Economy
Europe User Generated Content Platform Market
Social Media and Influencer Economy
User Generated Content Platform Market
Social Media and Influencer Economy
LAMEA User Generated Content Platform Market
Social Media and Influencer Economy
Social Media Content Creation Market
Social Media and Influencer Economy
Virtual Influencer Market
Social Media and Influencer Economy
Influencer Marketing Market
Social Media and Influencer Economy
Metaverse Social Media Platforms Market
Social Media and Influencer Economy
Global Short Video Sharing Platform Market
Social Media and Influencer Economy
Content Creation Market
Social Media and Influencer Economy
Online Love Rush Market
Social Media and Influencer Economy
Social Publishing Application Market
Social Media and Influencer Economy
Influencer Marketing Platform Market